

AC Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
AC Switchgear Market Insights
Digital twin integration with asset management platforms is reconfiguring how AC switchgear systems are specified, commissioned, and maintained across utility fleets. ABB leverages its Ability platform to anchor predictive maintenance contracts with European grid operators. Siemens sustains technology leadership in vacuum interrupter design through concentrated R&D spending. Schneider Electric differentiates by controlling the low-voltage switchgear-to-medium-voltage integration pathway for commercial and industrial microgrids.
AC switchgear comprises electromechanical assemblies rated for alternating current circuits, typically spanning voltage classes from 1 kV to 800 kV, designed to make, carry, and break normal load currents while withstanding specified short-circuit stresses for defined durations. Circuit breakers occupy the largest value pool within the product type taxonomy due to their functional centrality in fault isolation and the material intensity of their arc-extinguishing chambers. Vacuum technology leads the technology dimension by installed base, though solid-state interruption is gaining fastest in data center and renewable energy applications where switching speed and maintenance elimination justify premium positioning.
The International Electrotechnical Commission's IEC 62271 series governs product safety and performance testing protocols, while the EPA's phased restrictions on sulfur hexafluoride emissions are reshaping insulation medium selection across North American utility procurement. India's Central Electricity Authority mandates BIS certification for switchgear deployed in central transmission projects, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor how regulatory divergence on SF6 phase-out timelines across jurisdictions fragments product platform strategies and regional manufacturing footprints.
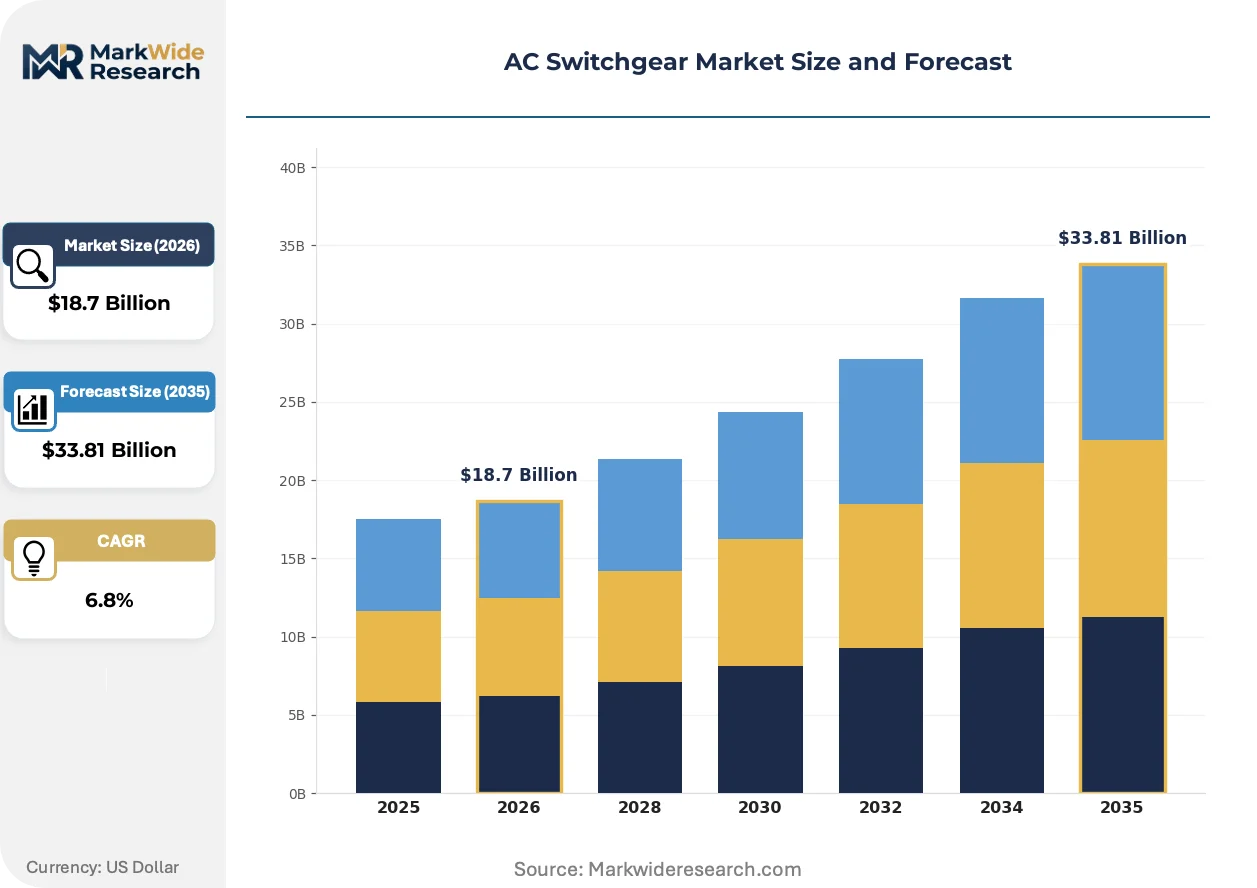
Market Dynamics
EPA restrictions on sulfur hexafluoride emissions are forcing a wholesale transition from gas-insulated to vacuum interruption technologies, compressing product development cycles and redrawing competitive advantage around arc-quenching material science.
Growth Catalysts
- Grid Modernization Mandates:India's Central Electricity Authority tenders for substation upgrades are channeling capital toward 145 kV and 245 kV switchgear classes. State transmission utilities in Maharashtra, Gujarat, and Tamil Nadu dominate procurement volume.
- IEC 62271-200 Compliance:The standard's metallic partition requirements for internal arc classification are accelerating replacement of legacy air-insulated switchgear in European utility fleets. German and French grid operators lead specification tightening.
- Distributed Solar Integration:Southeast Asian utilities require fault current limiting switchgear to manage bidirectional power flows from rooftop solar clusters. Thailand's Provincial Electricity Authority and Vietnam's EVN are piloting smart recloser deployments.
Market Restraints
- Copper and Silver Price Volatility:Contact material costs constitute 18-25% of medium-voltage circuit breaker manufacturing input. Price swings in London Metal Exchange copper contracts compress assembler margins unpredictably.
- SF6 Inventory Stranding:North American utilities face accelerated write-downs of installed gas-insulated switchgear bases. The EPA's phasedown schedule creates asset retirement obligation liabilities for investor-owned utilities in California and Texas.
- Vacuum Interrupter Supply Concentration:Ceramic-to-metal sealing technology for vacuum bottles concentrates among Japanese and German component specialists. This bottleneck limits capacity expansion for tier-two switchgear assemblers.
Strategic Opportunities
- Data Center Direct Current Ties:Hyperscale facilities in Northern Virginia and Frankfurt are specifying solid-state circuit breakers for 1,500 V DC bus protection. Switching speed requirements of under 2 milliseconds exclude electromechanical alternatives.
- EU F-Gas Regulation Phase-Down:The 2030 ban on SF6 in new medium-voltage equipment creates regulatory tailwind for dry air and vacuum insulation platforms. Nordic utilities are advancing procurement timelines to lock in compliant supply.
- Digital Twin Convergence:Integration of switchgear condition monitoring with enterprise asset management platforms enables predictive maintenance contracts. ABB's Ability platform anchors this service model with European transmission operators.
Industry Challenges
- High-Voltage Testing Capacity Scarcity:Short-circuit testing laboratories capable of 63 kA fault current verification concentrate in Germany, Japan, and India. Certification queues for new 420 kV products extend 14-18 months.
- Legacy Protocol Integration:IEC 61850 implementation in brownfield substations requires protocol gateway engineering for serial communication assets. Utilities in Poland and Czech Republic report 30% commissioning overrun on retrofit projects.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Switchgear Market Trends and Innovations
Vacuum interruption technology is collapsing the historical dominance of SF6-based arc extinction, while digital instrumentation and solid-state switching rewrite performance specifications for fault isolation speed.
Solid-state circuit breakers employing silicon carbide power electronics are collapsing the response time gap between detection and interruption. Data center operators and offshore wind developers specify these devices where electromechanical contact wear and maintenance cycles prove unacceptable. The technology is collapsing traditional circuit breaker lifecycle economics by eliminating mechanical wear components entirely.
The EPA's phasedown of sulfur hexafluoride under the American Innovation and Manufacturing Act is compressing procurement timelines for gas-insulated switchgear replacements. Investor-owned utilities in California and Texas are accelerating vacuum and dry air platform qualification to avoid stranded asset risk. Medium-voltage distribution segments face the steepest compliance cost escalation as 2028 interim reduction targets approach.
Utility procurement departments are unbundling switchgear supply from engineering-procurement-construction contracts to secure direct manufacturer relationships. European transmission operators now specify equipment separately from installation services, compressing distributor margins and favoring OEMs with in-house project execution capabilities. This pattern is most visible in German and Dutch grid modernization programs where asset owners retain design authority.
AC Switchgear Market Segmentation
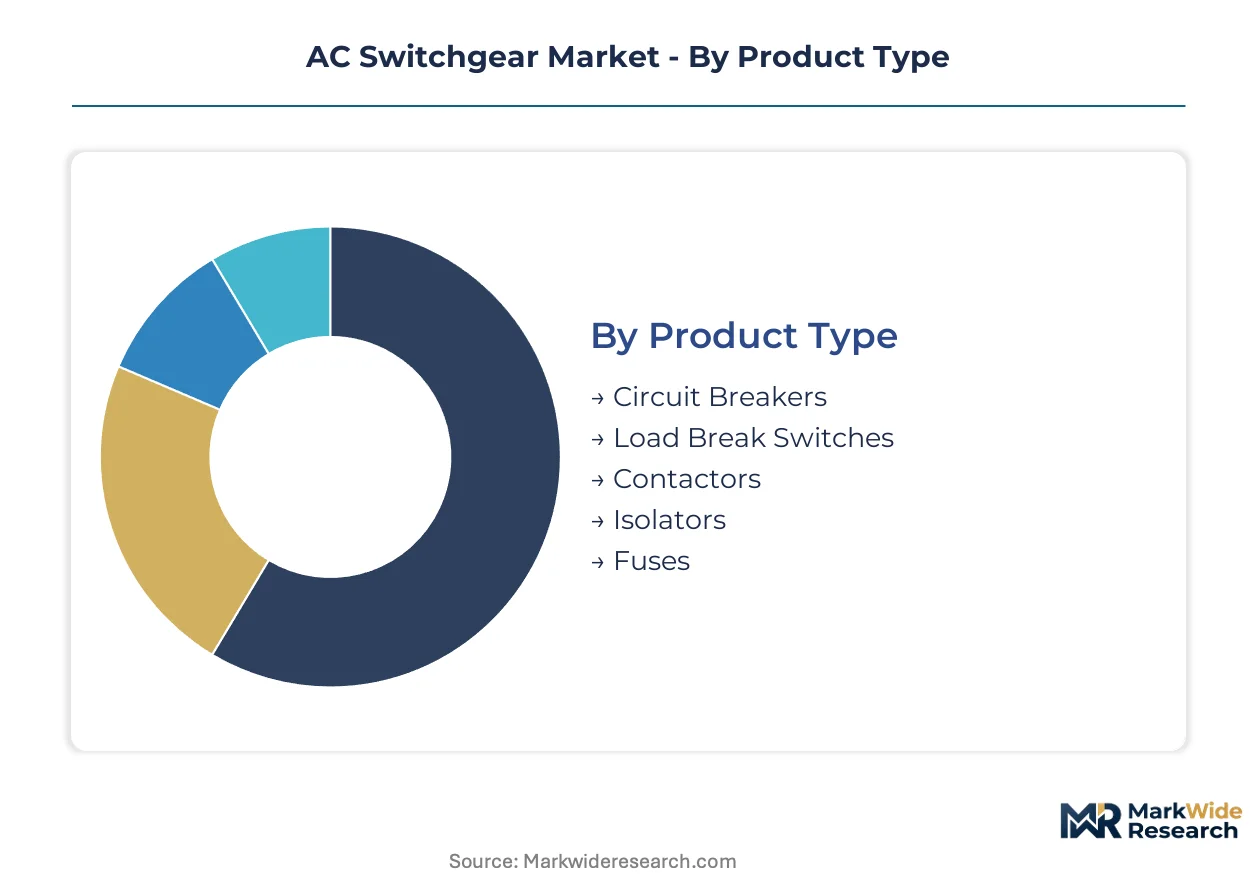
AC switchgear segmentation reflects divergent technical requirements across voltage classes, arc-quenching methods, and asset owner risk profiles. Procurement specifications vary sharply between utilities managing legacy grids and hyperscale operators demanding solid-state switching speeds.
Product Type:
Cost tiers separate capital-intensive fault-interruption equipment from simpler switching devices in utility and industrial procurement.
- Circuit Breakers:These assemblies combine arc-extinguishing chambers with mechanical operating mechanisms rated for repeated fault current interruption. State transmission utilities in Maharashtra and Gujarat concentrate procurement in 145 kV and 245 kV classes for substation modernization programs.
- Load Break Switches:Devices designed for normal load current interruption without short-circuit breaking capability, employing simpler contact systems than full breakers. Distribution network operators in Thailand and Vietnam specify these for feeder sectionalization in solar-rich grid zones where fault levels remain moderate.
- Contactors:Electromechanical switches rated for frequent operational cycles in motor control and capacitor switching applications.
- Isolators:Visible-break disconnectors providing no-load circuit separation for maintenance safety in substation layouts.
- Fuses:Single-operation overcurrent protection devices leveraging fusible element melting for fault clearance in distribution transformers and capacitor banks.
The dominant share belongs to Circuit Breakers, while Solid State interruption is closing the gap fastest in premium applications.
Technology:
Application urgency and regulatory compliance timelines are fragmenting technology selection across utility fleets and industrial sites.
- Vacuum:Ceramic-enclosed interrupters utilizing metal vapor arc diffusion in high-vacuum environments, now the default for medium-voltage distribution. Japanese and German component specialists control ceramic-to-metal sealing capacity, creating supply bottlenecks for tier-two assemblers.
- Solid State:Silicon carbide power electronic switches eliminating mechanical wear and achieving sub-2-millisecond interruption speeds. Hyperscale data center operators in Northern Virginia and Frankfurt specify these for 1,500 V DC bus protection where maintenance elimination justifies premium positioning.
- Air Magnetic:Traditional arc chute interruption for low-voltage applications where cost sensitivity dominates specification.
- Oil Insulated:Legacy bulk-oil and minimum-oil designs persisting in specific utility maintenance strategies and developing market installed bases.
- SF6 Gas:Sulfur hexafluoride-insulated switchgear facing accelerated phase-out under EPA restrictions and EU F-Gas Regulation timelines.
Vacuum technology commands the largest installed base, though Solid State is expanding most quickly in renewable energy and data center segments.
Application:
Customer type and performance requirements stratify demand across grid infrastructure, commercial buildings, and mission-critical facilities.
- Transmission Networks:Extra-high-voltage switchgear rated 245 kV and above for bulk power transfer and grid interconnection. India's Central Electricity Authority mandates BIS certification, creating compliance barriers for non-domestic suppliers in central transmission projects.
- Data Centers:Facilities requiring ultra-fast fault isolation to protect power distribution units and server racks from cascading failures. Operators specify solid-state breakers where electromechanical contact wear and maintenance cycles prove unacceptable.
- Power Generation:Switchgear for generator protection and station service in thermal, hydro, and nuclear plants.
- Commercial Facilities:Medium-voltage metal-clad assemblies for campus and high-rise electrical distribution.
- Renewable Energy Plants:Collector substation and interconnection switchgear for solar and wind farms managing bidirectional power flows.
Transmission Networks retain the largest equipment value pool, while Data Centers are gaining share fastest on switching speed requirements.
End User:
Procurement sophistication and lifecycle cost horizons differentiate buyer segments across regulated utilities and industrial operators.
- Electric Utilities:Regulated transmission and distribution entities with standardized specifications and long asset depreciation horizons. German and French grid operators lead specification tightening under IEC 62271-200 metallic partition requirements.
- Manufacturing Plants:Heavy industrial sites with process-critical power reliability needs and in-house electrical maintenance capabilities.
- Infrastructure Operators:Airport, hospital, and water utility entities with public service continuity obligations.
- Transport Systems:Rail electrification and metro traction power applications with high operational cycle demands.
- Telecommunications:Mobile network and data exchange facilities with backup power integration requirements.
Electric Utilities dominate procurement volume, while Data Center operators within Infrastructure categories are climbing the fastest on digital infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric utilities in India, Germany, Japan, and the United States concentrate procurement authority, while state-level transmission operators in Maharashtra and Gujarat drive tender volumes for 145 kV and 245 kV switchgear classes.
India
Maharashtra State Electricity Transmission Company and Gujarat Energy Transmission Corporation dominate tender issuance for substation modernization. The Central Electricity Authority mandates BIS certification for equipment deployed in central transmission projects, creating compliance barriers for non-domestic suppliers. State utilities in Tamil Nadu and Karnataka are accelerating 400 kV greenfield substation deployments to accommodate renewable energy evacuation.
Germany
TenneT and 50Hertz drive specification tightening for internal arc classification under IEC 62271-200 metallic partition requirements. The EU F-Gas Regulation's 2030 ban on SF6 in new medium-voltage equipment compresses procurement timelines for vacuum and dry air platforms. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate manufacturing capacity for vacuum interrupter assemblies.
United States
Investor-owned utilities in California and Texas face accelerated write-downs of gas-insulated switchgear bases under EPA phasedown schedules. Dominion Energy and Southern California Edison lead vacuum platform qualification programs to avoid stranded asset risk. Data center operators in Northern Virginia specify solid-state circuit breakers for 1,500 V DC bus protection.
Japan
Tokyo Electric Power and Chubu Electric Power maintain stringent specifications for vacuum interrupter reliability in seismic zones. METI's grid resilience directives prioritize domestic manufacturing of ceramic-to-metal sealing components. Osaka-based component specialists control bottlenecked capacity for vacuum bottle production.
Vietnam
Electricity of Vietnam pilots smart recloser deployments to manage bidirectional power flows from rooftop solar clusters. The national power development plan channels investment toward 220 kV and 500 kV transmission corridors. Industrial zones in Binh Duong and Dong Nai provinces concentrate foreign direct investment in manufacturing facilities.
AC Switchgear Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement unbundling trends that separate equipment supply from engineering-procurement-construction contracts. European transmission operators now specify switchgear separately from installation services, compressing distributor margins and favoring original equipment manufacturers with in-house project execution capabilities. Three archetypes dominate: integrated multinationals with digital service platforms, component specialists controlling vacuum interrupter supply, and regional assemblers serving price-sensitive procurement. Competitive moves concentrate on strategic partnerships for solid-state technology access and backward integration into ceramic-to-metal sealing capacity.
Among Swiss-Swedish and German industrial conglomerates, ABB and Siemens exemplify the integrated multinational archetype through predictive maintenance service models. Schneider Electric occupies a position bridging low-voltage and medium-voltage integration pathways for commercial and industrial microgrids. These three anchors represent divergent strategic bets on digitalization, vacuum interrupter design leadership, and microgrid control integration respectively.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| Hitachi Energy |
| GE Vernova |
| Mitsubishi Electric |
| Fuji Electric |
| Hyosung Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
Ceramic-to-metal sealing capacity for vacuum interrupters concentrates among Osaka-based component specialists and German engineering houses, anchoring margin pools with tier-one switchgear assemblers who control direct utility relationships while tier-two players absorb contact material volatility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement between state transmission utilities and OEMs, insulating vendors from contact material swings while compressing assembler margins on fixed-price distributor agreements. Price differentiation rests on IEC 62271-200 internal arc certification tier and after-sales predictive maintenance bundling. Cost compression in medium-voltage distribution segments intensifies as EPA phasedown timelines accelerate SF6 inventory retirement. Price sensitivity peaks among Southeast Asian distribution network operators tendering feeder sectionalization projects, while European transmission operators absorb premiums for digital twin integration.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese and German vacuum bottle specialists enable tier-one assemblers to lock in ceramic-to-metal sealing capacity through 18-month payment terms, starving tier-two competitors of component access. Manufacturing gravity centers on Germany, Japan, and India for high-voltage testing and final assembly, while silver-copper contact materials feed from Chilean and Peruvian mining operations. Single-source vulnerability concentrates in vacuum interrupter ceramic enclosures. Distribution runs through direct manufacturer relationships with state utilities, bypassing traditional EPC intermediaries in European and Indian procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts anchored to digital twin platforms are expanding faster than hardware shipments, converting capital expenditure into recurring service revenue across European transmission operator fleets.
For Market Incumbents: Pre-empt solid-state circuit breaker displacement in data center and offshore wind segments by securing silicon carbide power electronics partnerships before qualification timelines harden. Backward integration into ceramic-to-metal sealing capacity defends component access against Japanese and German supply bottlenecks. Digital twin platform stickiness with European grid operators creates switching costs that delay entrant erosion. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where IEC 62271 compliance requirements remain less stringent than European utility specifications and local assembly partnerships circumvent vacuum interrupter supply constraints. Smart recloser deployments for distributed solar integration in Thailand and Vietnam offer pilot-to-scale pathways. Target engineering-procurement-construction contractors unbundled from equipment specification by European asset owners. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists controlling vacuum interrupter ceramic-to-metal sealing technology, where supply inelasticity sustains pricing power across the analysis window. Long-term viability favors platforms with predictive maintenance service attach rates exceeding hardware replacement cycles. Monitor EPA enforcement acceleration and EU F-Gas Regulation procurement timeline compression as inflection signals for SF6 substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-to-Metal Sealing Capacity Expansion | Secures bottlenecked vacuum interrupter supply for tier-one assemblers competing in Indian and German transmission tenders. |
| Solid-State Circuit Breaker Qualification | Positions suppliers for hyperscale data center procurement in Northern Virginia and Frankfurt requiring sub-2-millisecond interruption. |
| Predictive Maintenance Platform Integration | Converts ABB Ability-type digital twin deployments into recurring revenue contracts with European grid operators. |
| SF6-Free Platform Certification | Ensures EPA and EU F-Gas Regulation compliance for California and Nordic utility procurement acceleration. |
| Direct Utility Relationship Development | Bypasses EPC intermediaries in European procurement unbundling trends favoring OEMs with in-house project execution. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, switchgear procurement managers at state transmission utilities, EPC contractor project directors, and aftermarket service heads, then refined through secondary validation against IEC standards documentation, EPA regulatory filings, FERC interconnection queues, and Indian Central Electricity Authority tender databases, with bottom-up and top-down triangulation across voltage class and application segment.
Demand-supply balance framing anchored the analytical framework across the analysis window, modeling segmentation by voltage class, arc-quenching technology, application, and end-user procurement sophistication. CAGRs derived from utility capital expenditure pipeline analysis and renewable energy interconnection backlogs. Forecast inputs incorporated distributed solar penetration rates and data center power density specifications.
Practitioners should monitor EPA enforcement acceleration, EU F-Gas Regulation procurement timeline compression, and vacuum interrupter ceramic supply expansion for early signals of competitive repositioning. Forecasts reflect assumptions on regulatory phase-out adherence and component supply elasticity. Macroeconomic deviation, regulatory enforcement variance, or solid-state technology cost breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.