
 Video-As-A-Service (Vaas) Market | 2026-2036
Video-As-A-Service (Vaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Video-As-A-Service (Vaas) Market Analytics
Platform bundling is consolidating buyer choice across the Video-As-A-Service landscape as vendors merge video conferencing with messaging, file storage, and AI productivity tools into unified suites. Microsoft Corporation leverages its Office 365 ecosystem to anchor enterprise subscriptions around Teams-integrated video workflows. Zoom Video Communications Inc. competes through vertical specialization in telehealth and financial services compliance modules. Cisco Systems Inc. differentiates via hardware-software convergence with its Webex room systems and security certifications.
Video-As-A-Service denotes cloud-delivered video infrastructure enabling real-time encoding, transcoding, storage, and distribution without on-premise server ownership, typically operating on containerized microservices with sub-200ms latency targets for live streaming. Its primary commercial purpose is to eliminate capital expenditure on broadcast-grade infrastructure while scaling elastically with viewer demand. Public cloud deployment dominates current provisioning due to auto-scaling economics, though hybrid cloud configurations are capturing margin pools from enterprises with data residency requirements. Among applications, live streaming sustains the fastest growth trajectory as sports leagues and retail brands deploy interactive shoppable streams, while video conferencing remains mature with pricing compression in the small-business tier.
FCC net neutrality rulings in the United States, GDPR data localization mandates from European regulators, and India's TRAI cloud framework collectively shape where video data may transit and reside, directly influencing provider architecture decisions. ISO 27001 and SOC 2 Type II certifications function as baseline market-access credentials for enterprise procurement teams evaluating vendor shortlists. Stakeholders must monitor evolving cross-border data transfer agreements and AI-generated content disclosure rules as these will determine which platform architectures retain compliance advantage.
Market Dynamics
Platform bundling is compressing standalone video conferencing margins as enterprise buyers consolidate vendor relationships around unified collaboration suites. Microsoft, Zoom, and Cisco now compete on ecosystem breadth rather than video quality alone.
Growth Catalysts
- Hybrid work infrastructure mandates:Enterprise IT departments in the United States, Germany, and India are standardizing cloud-hosted video platforms as core productivity infrastructure. Procurement teams prioritize auto-scaling elasticity over capital-intensive on-premise deployments.
- GDPR and EU AI Act compliance frameworks:European data residency requirements are accelerating demand for region-locked video architectures with ISO 27001 and SOC 2 Type II certifications. Vendors with pre-certified compliance stacks capture accelerated procurement cycles.
- Interactive live streaming protocols:Sports leagues and retail brands deploy sub-200ms latency streaming with real-time commerce integration. Containerized microservices enable elastic scaling during peak viewership events without infrastructure overprovisioning.
Market Restraints
- Cross-border data transfer restrictions:FCC net neutrality uncertainties and India's TRAI cloud framework create architectural fragmentation. Providers must maintain redundant infrastructure across jurisdictions, elevating operational complexity.
- Public cloud concentration risk:Auto-scaling economics lock most provisioning to hyperscaler platforms. Buyer negotiating power diminishes as migration costs between AWS, Azure, and Google Cloud escalate.
- Small-business pricing compression:Mature video conferencing segments face commoditization as freemium models saturate the lower tier. Revenue per seat stagnates below enterprise contract thresholds.
Strategic Opportunities
- Telehealth compliance modules:HIPAA-aligned video workflows for US healthcare providers remain underpenetrated relative to enterprise adoption. Specialized encryption and audit logging command premium pricing.
- Financial services verticalization:FINRA and SEC recording requirements create demand for immutable video archives with legal hold capabilities. Compliance-native platforms differentiate from generalist competitors.
- AI-generated content disclosure rules:Emerging mandates for synthetic media labeling will favor platforms with integrated provenance tracking. First-mover certification creates switching costs for enterprise buyers.
Industry Challenges
- Container orchestration expertise scarcity:Sub-200ms live streaming requires specialized Kubernetes engineering talent. Platform providers compete for limited DevOps professionals with broadcast-grade latency optimization experience.
- Legacy hardware integration friction:Enterprises with sunk investments in Cisco Webex room systems face complex migration paths to cloud-native architectures. Hybrid deployment support extends sales cycles and elevates support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video-As-A-Service (Vaas) Market |
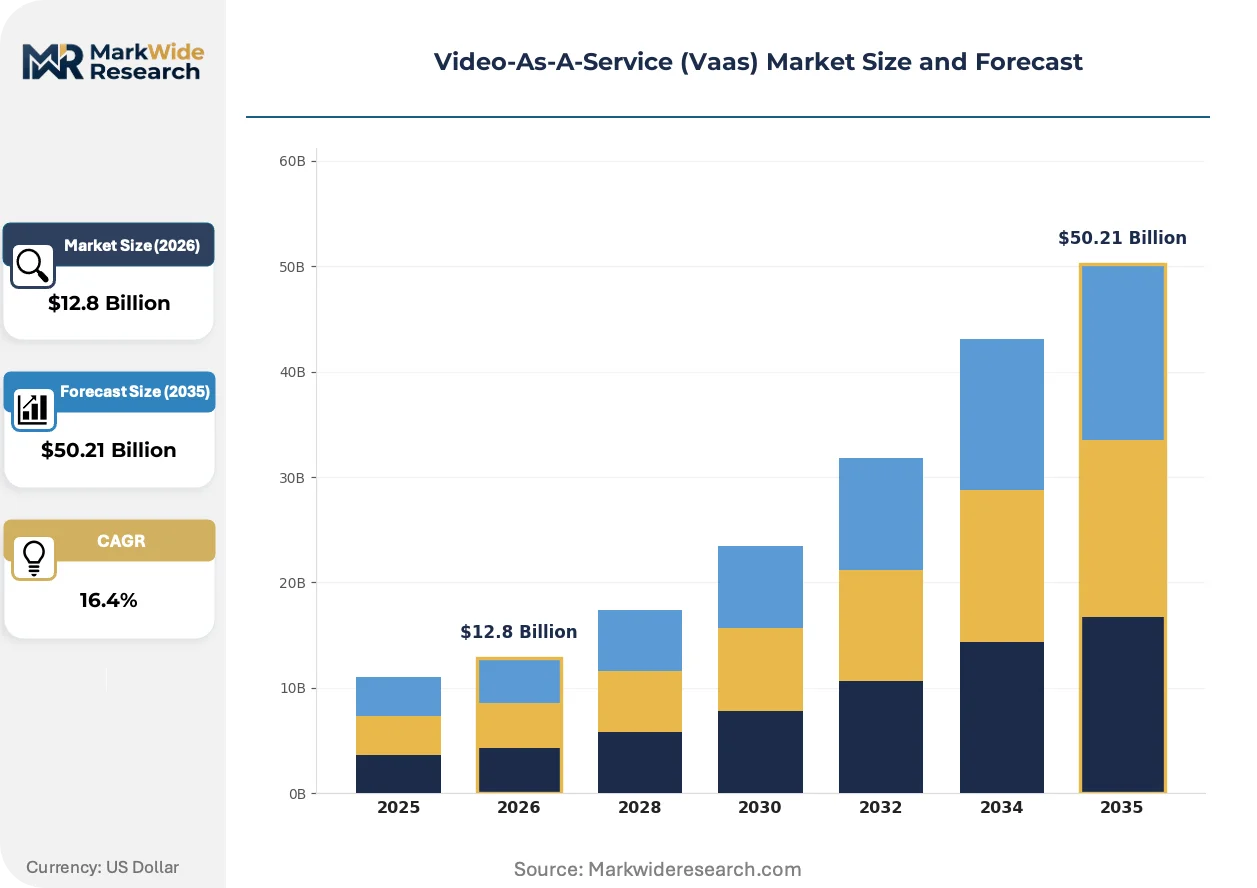
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $50.21 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Enterprises, Educational Institutions, Media Companies, Government Agencies Application: Live Streaming, Video Conferencing, Video Editing, Video Hosting Service Type: Subscription-Based, Pay-Per-View, Ad-Supported, Freemium |
| Companies Covered | Cisco Systems Inc., Zoom Video Communications Inc., Microsoft Corporation, Google LLC, Amazon Web Services, Adobe Inc., Avaya LLC, RingCentral Inc., Poly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video-As-A-Service (Vaas) Market Evolving Landscape
Artificial intelligence is embedding into video workflows through real-time transcription, sentiment analysis, and automated meeting summarization. These capabilities are shifting buyer evaluation criteria from connectivity reliability toward productivity augmentation.
Edge computing nodes are integrating with centralized cloud encoding to reduce latency for interactive live streaming. Sports broadcasters and retail brands deploy these distributed architectures for shoppable video events. The technology is integrating real-time inventory APIs with viewer engagement metrics, compressing the gap between content consumption and transaction completion.
The EU AI Act's risk classification system is mandating algorithmic transparency for biometric identification in video platforms. Providers must document training data provenance and enable human oversight of automated decision systems. European enterprise procurement teams now require AI Act conformity assessments alongside existing GDPR data processing agreements.
Enterprise buying committees are consolidating vendor relationships around platform ecosystems rather than best-of-breed point solutions. IT departments in the United States and Germany prioritize Microsoft Teams-integrated video over standalone alternatives. This concentration is elevating switching costs and compressing evaluation timelines for secondary vendors.
Video-As-A-Service (Vaas) Market Segmentation
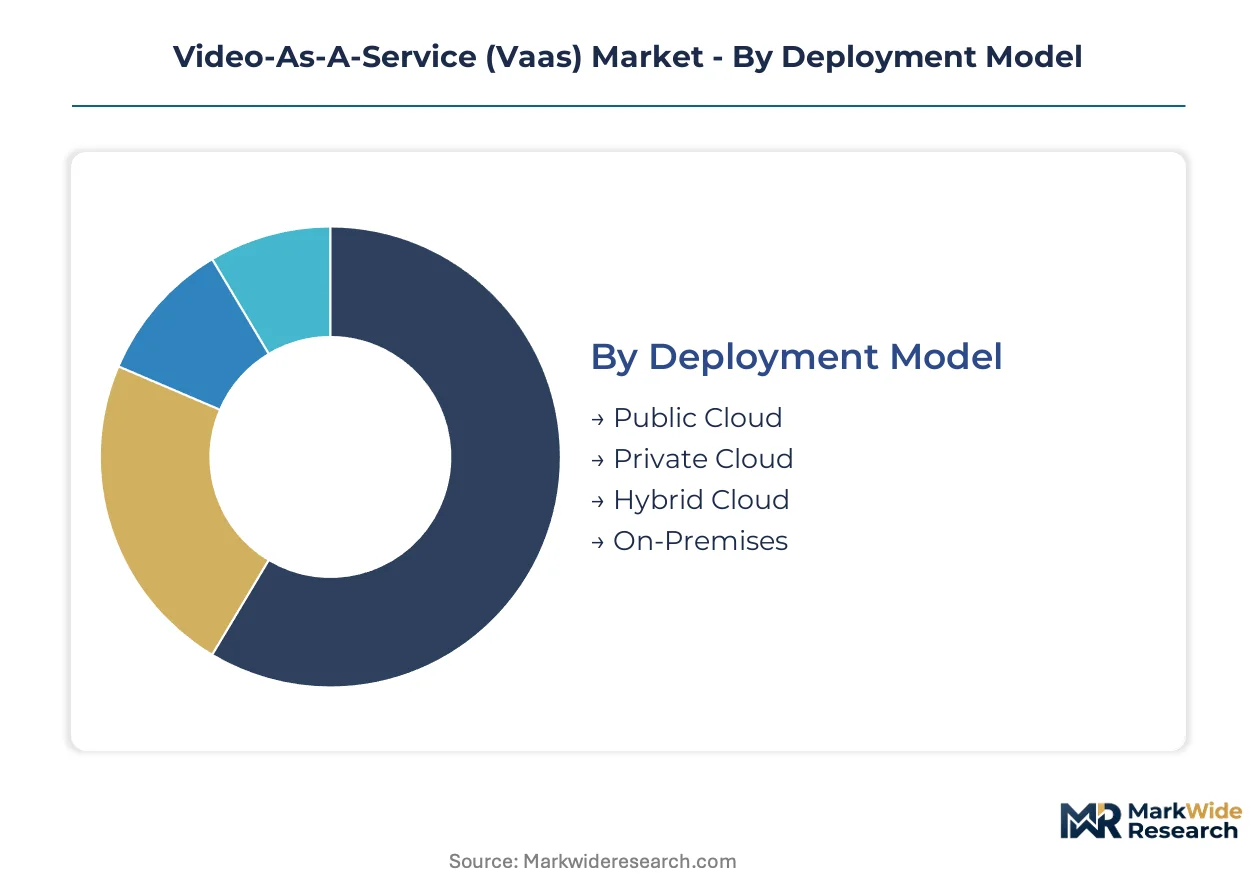
Video-As-A-Service procurement teams evaluate platforms across four critical dimensions: infrastructure control, organizational buyer type, functional use case, and commercial model. Each segmentation axis carries distinct compliance requirements and scaling economics that reshape vendor selection criteria.
Deployment Model:
Buyers with data residency mandates prioritize architectural control over pure cost optimization, driving divergence between elastic public provisioning and captive infrastructure strategies.
- Public Cloud:Containerized microservices on hyperscaler platforms deliver auto-scaling elasticity for variable viewer loads. Procurement teams in the United States and India favor this model for rapid provisioning without capital commitment, though GDPR-bound European enterprises increasingly demand region-locked instances.
- Hybrid Cloud:Workload orchestration splits encoding tasks between on-premise nodes and burst capacity to public infrastructure. German automotive and pharmaceutical buyers deploy this architecture to satisfy ISO 27001 audit trails while retaining elastic scaling for live streaming peaks.
- Private Cloud:Dedicated tenant environments on managed infrastructure address FINRA and SEC recording requirements for US financial services. Single-tenant isolation commands premium pricing but eliminates multi-tenant data co-mingling risks.
- On-Premises:Capital-intensive server ownership persists in defense and classified government installations where air-gapped networks are mandatory. India's defense procurement specifications explicitly exclude cloud-hosted alternatives for strategic communications.
Public Cloud leads on scale; Hybrid Cloud leads on momentum as GDPR and India's TRAI framework accelerate data localization mandates.
End User:
Organizational procurement authority concentrates in IT departments with standardized security certification requirements, though media buyers prioritize encoding performance over compliance documentation.
- Enterprises:Fortune 500 IT departments mandate SOC 2 Type II attestation and ISO 27001 certification as baseline vendor qualifications. Microsoft Teams-integrated workflows dominate US and German procurement shortlists, compressing standalone video conferencing margins.
- Media Companies:Sports leagues and retail brands deploy sub-200ms latency streaming with real-time commerce APIs. Shoppable video events in India and the United States drive elastic scaling requirements during unpredictable viewership spikes.
- Educational Institutions:University IT departments in Germany and India standardize cloud-hosted lecture capture with automated transcription. Budget constraints favor subscription models over capital-intensive on-premise deployments.
- Government Agencies:India's TRAI cloud framework and US FedRAMP authorization create bifurcated procurement paths. Defense segments require on-premise isolation; civilian agencies accept certified public cloud instances.
Enterprises dominate contract value; Media Companies are expanding most quickly as interactive live streaming protocols mature.
Application:
Functional use cases diverge sharply on latency tolerance, with real-time interactivity commanding specialized engineering investment versus asynchronous hosting commoditization.
- Live Streaming:Containerized edge nodes reduce latency for sports broadcasters deploying shoppable video. Real-time inventory API integration compresses transaction completion windows, driving Kubernetes orchestration expertise scarcity.
- Video Conferencing:Mature segment faces pricing compression as Microsoft, Zoom, and Cisco bundle video into unified collaboration suites. Small-business tiers saturate with freemium models, stagnating revenue per seat below enterprise thresholds.
- Video Editing:Cloud-native post-production workflows attract media companies seeking to eliminate render farm capital expenditure. GPU-accelerated instances on AWS and Azure enable elastic scaling for project-based demand.
- Video Hosting:Commoditized storage and delivery functions face margin pressure from hyperscaler direct offerings. Differentiation shifts toward AI-generated content search and automated metadata extraction.
Video Conferencing retains installed base dominance; Live Streaming shows the steepest expansion trajectory as interactive protocols proliferate.
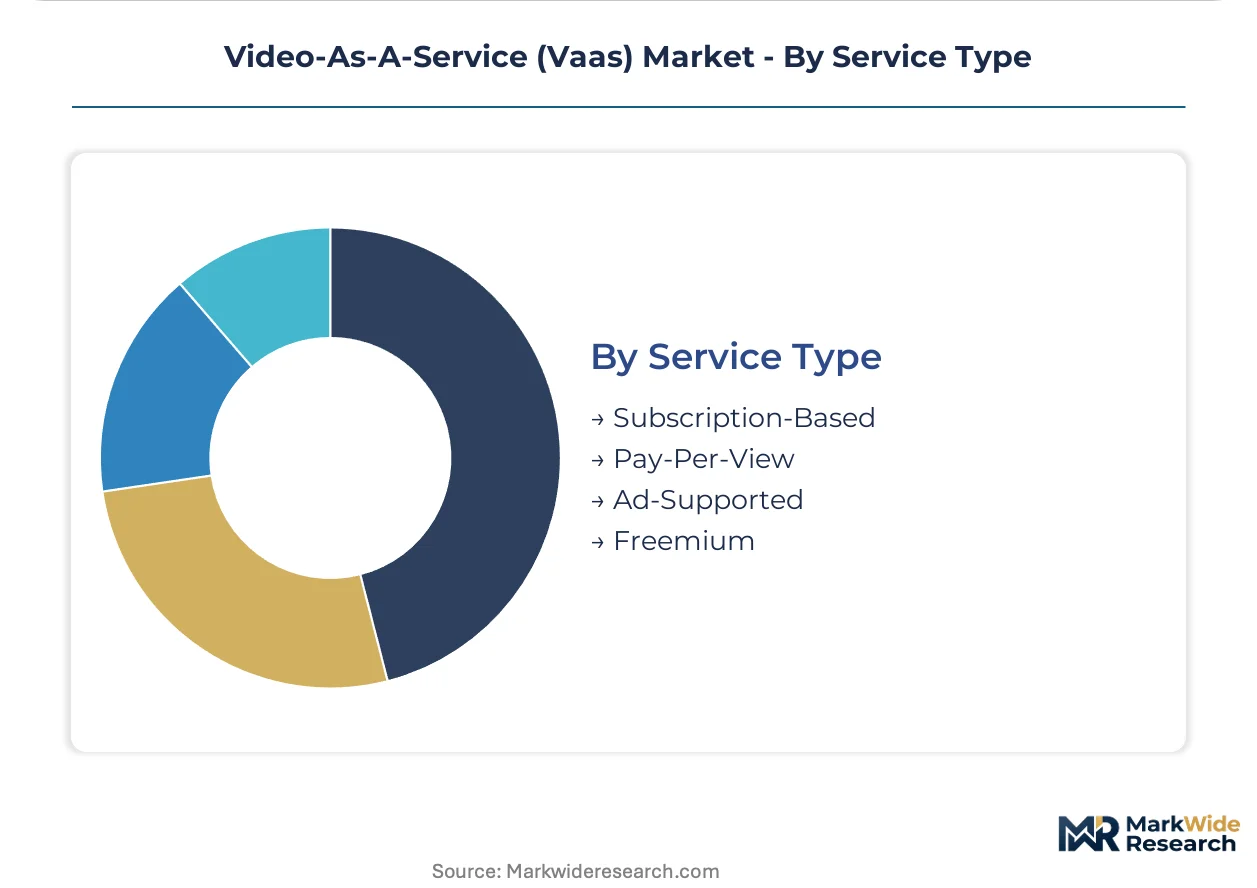
Service Type:
Commercial model selection reflects buyer predictability preferences, with committed subscriptions favored by enterprises and variable consumption models aligning with campaign-based media spending.
- Subscription-Based:Annual or multi-year contracts with predictable seat counts dominate enterprise procurement. German and US buyers negotiate auto-scaling clauses for seasonal workforce fluctuations without renegotiation overhead.
- Pay-Per-View:Event-based pricing aligns cost with actual consumption for sports leagues and entertainment venues. India's cricket streaming market demonstrates peak-load architecture requirements without committed infrastructure.
- Ad-Supported:Free viewer access funded by programmatic advertising sustains reach for media companies and educational content platforms. GDPR consent management and EU AI Act disclosure rules complicate targeting precision.
- Freemium:Feature-limited entry tiers saturate small-business and individual user acquisition. Conversion to paid functionality remains below vendor targets, compressing average revenue per user metrics industry-wide.
Subscription-Based captures the majority of enterprise contract value; Ad-Supported models are gaining share fastest as media buyers prioritize audience scale over direct monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Video-As-A-Service infrastructure originated in United States data centers during the early cloud computing wave, with hyperscaler platforms establishing the architectural templates later adopted across Germany, India, and other demand centers. The industry's geographic footprint now tracks hybrid work policy implementation and data localization mandates rather than pure cost arbitrage.
United States
Enterprise IT departments in financial services and technology sectors drive procurement volume for HIPAA-aligned telehealth modules and FINRA-compliant recording archives. FCC net neutrality rulings create architectural uncertainty for cross-border traffic routing. Silicon Valley and Seattle clusters concentrate platform engineering talent for sub-200ms latency optimization.
Germany
Automotive and pharmaceutical buyers mandate ISO 27001-certified hybrid cloud deployments to satisfy GDPR audit requirements. The EU AI Act's risk classification system forces algorithmic transparency documentation for biometric identification features. Bavaria's industrial corridor leads adoption of region-locked video architectures with on-premise encoding nodes.
India
Cricket streaming and digital education expansion fuel elastic scaling demand for containerized microservices during unpredictable viewership spikes. TRAI cloud framework mandates data localization for government procurement, bifurcating vendor qualification paths. Bangalore and Hyderabad clusters concentrate Kubernetes engineering expertise for broadcast-grade latency optimization.
United Kingdom
Financial services compliance requirements under FCA guidelines drive demand for immutable video archives with legal hold capabilities. Post-Brexit data transfer agreements complicate cross-border hosting arrangements with EU infrastructure. London's fintech concentration anchors premium pricing for specialized encryption and audit logging modules.
Japan
Enterprise buyers prioritize integration with existing productivity suites over standalone video conferencing point solutions. METI guidelines on cloud security certification influence procurement shortlist criteria for multinational corporations. Tokyo-Osaka corridor concentrates demand for hardware-software converged room systems in manufacturing headquarters.
Video-As-A-Service (Vaas) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and ecosystem breadth, with compliance-native architectures commanding 40-60% pricing premiums over generalist alternatives. The vendor base consolidates around three hyperscaler-anchored ecosystems rather than fragmenting across standalone specialists. Two strategic archetypes dominate: platform bundlers integrating video into unified collaboration suites, and vertical specialists targeting regulated industries with pre-certified compliance stacks. Competitive moves center on ecosystem lock-in through API integration depth and geographic expansion via region-locked data center partnerships.
Within the platform bundler tier, Microsoft Corporation and Google LLC exemplify ecosystem-anchored strategies, while Cisco Systems Inc. occupies a position bridging hardware-software convergence with cloud-native delivery. Microsoft leverages Office 365 integration to compress standalone video conferencing margins, Google extends YouTube infrastructure into enterprise workflows, and Cisco represents legacy room system vendors navigating migration friction toward containerized architectures. These three companies collectively illustrate how certification depth and hybrid deployment support now outweigh raw video quality in enterprise procurement decisions.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Zoom Video Communications Inc. |
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services |
| Adobe Inc. |
| Avaya LLC |
| RingCentral Inc. |
| Poly |
| Others |
Value Network & Pricing Analysis
Hyperscaler-anchored platform providers concentrate supply-side power across United States, German, and Indian data center clusters, translating infrastructure ownership into pricing discipline through certification-gated enterprise contracts. Private equity-rolled conferencing specialists face margin compression as ecosystem bundlers leverage captive cloud capacity to undercut standalone SaaS pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Video-As-A-Service procurement, with ISO 27001 and SOC 2 Type II certification tiers commanding 40-60% premiums over uncertified alternatives. Price differentiation hinges on compliance depth and geographic data residency guarantees, not raw encoding performance. Pricing pressure stems from freemium saturation in small-business conferencing tiers, where revenue per seat stagnates below enterprise contract thresholds. Media companies with elastic scaling needs show lowest price sensitivity; educational institutions with fixed budgets exhibit highest.
Supply Chain Analysis
Certification and qualification gating concentrates supply among hyperscaler platforms with pre-audited compliance stacks, drawing from United States, Germany, and India data center footprints. Containerized microservices architectures rest on GPU-accelerated instances, Kubernetes orchestration software, and edge computing nodes as critical inputs. Single-source vulnerability runs through hyperscaler concentration risk, where migration costs between AWS, Azure, and Google Cloud escalate buyer lock-in. Distribution runs through direct enterprise sales teams and systems integrators with vertical specialization in healthcare and financial services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Video-As-A-Service market functions as a regulatory compounder, where EU AI Act algorithmic transparency mandates and GDPR data localization requirements continuously reshape procurement criteria and platform architecture investments.
For Market Incumbents: Acquire container orchestration engineering talent with broadcast-grade latency optimization experience to defend against specialized streaming entrants. Fortify region-locked data center partnerships in Germany and India before TRAI framework and EU AI Act compliance deadlines harden switching costs. Certification investment in HIPAA-aligned telehealth modules represents the priority defensive lever against vertical specialists. For New Entrants and Emerging Players: Capture underpenetrated HIPAA-compliant telehealth workflows in United States healthcare systems where incumbent bundlers lack vertical depth. Target FINRA and SEC recording requirements for financial services with immutable archive architectures that generalist platforms cannot replicate. Lead with compliance-native positioning rather than feature parity to bypass Microsoft Teams ecosystem lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among private cloud specialists with single-tenant isolation capabilities serving defense and classified government segments. Long-term viability across the analysis window favors vendors with hybrid deployment expertise bridging legacy Cisco Webex room systems to cloud-native architectures. Watch for AI-generated content disclosure rule finalization as the signal triggering premium pricing for provenance-tracking platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Region-Locked Data Center Partnership | GDPR and TRAI compliance positioning captures German automotive and Indian government procurement cycles. |
| HIPAA Compliance Module Development | Specialized encryption for US healthcare providers commands premium pricing in underpenetrated telehealth workflows. |
| Container Orchestration Talent Acquisition | Kubernetes expertise scarcity elevates platform capabilities for sub-200ms interactive live streaming events. |
| AI Provenance Tracking Integration | EU AI Act synthetic media labeling mandates create first-mover certification advantages for enterprise buyers. |
| Legacy Hardware Bridge Architecture | Hybrid deployment support extends addressable market to Cisco Webex room system installed base. |
Research Methodology
Coverage spans United States, Germany, and India, with primary inputs from each market's enterprise IT procurement officers, platform engineering leads, and regulatory compliance directors. Secondary validation draws from SEC filings of hyperscaler platforms, TRAI cloud framework documentation, EU AI Act regulatory texts, and ISO certification registries. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across deployment model, end user type, functional application, and commercial service type dimensions. CAGRs derive from elasticity-adjusted demand curves incorporating hybrid work policy implementation timelines and data localization mandate enforcement schedules. Containerized microservices adoption curves and edge computing node deployment patterns inform interactive live streaming trajectory assumptions.
Underlying measurement precision varies by segment; subscription-based enterprise contracts carry tighter precision than ad-supported media models with volatile viewership spikes. Forecasts reflect assumptions about cross-border data transfer agreement stability and hyperscaler capacity expansion continuity. A model refresh is warranted upon material change in EU AI Act enforcement timelines or FCC net neutrality rulings affecting traffic routing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Basketball Apparel Market
Others
France Smart Home Market
Others
Consumer Video Feedback Software Market
Others
Cloud DVR Market
Others
Insoluble Sulfur Market
Others
Global Military Wearable Sensors Market
Others
Fenoxanil Market
Others
Global Cosmetovigilance Market
Others
Underwater Light Market
Others
Global Military and Aerospace Sensors Market
Others
Air Separation Plant Market
Others
Europe Flow Battery Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Global Electronic Filters Market
Others
Fluid Dispensing Systems Market
Others
United States Printed Signage Market