
 South Asia Geosynthetics Market | 2026-2036
South Asia Geosynthetics Market Size, Share, and Industry Trends Forecast 2026-2036
South Asia Geosynthetics Market Outlook
Road construction is consolidating its position as the dominant demand vertical for South Asia geosynthetics, pulling ahead of traditional landfill and agricultural applications. TechFab India Industries Ltd. anchors its market presence through specialized manufacturing of woven and non-woven geotextiles for highway projects. Garware Technical Fibres Ltd. leverages its technical expertise in high-performance polymers to compete in demanding soil stabilization contracts. Enviro Geosynthetics Pvt. Ltd. differentiates through localized production capabilities serving India's infrastructure corridors.
Geosynthetics encompass polymeric materials including polypropylene, polyester, and polyethylene formulations engineered for soil reinforcement, filtration, drainage, and containment functions across civil engineering applications. Manufacturing processes span extrusion, weaving, needle-punching, and thermal bonding to achieve specified tensile strengths, permeability coefficients, and chemical resistance profiles for project-specific performance. Geotextiles and geogrids command the largest volume share given their deployment in India's Bharatmala highway initiative and Bangladesh's Padma Bridge connectivity projects. Geomembranes and geocells represent faster-growing segments driven by landfill liner mandates and slope protection requirements in Nepal's mountainous terrain.
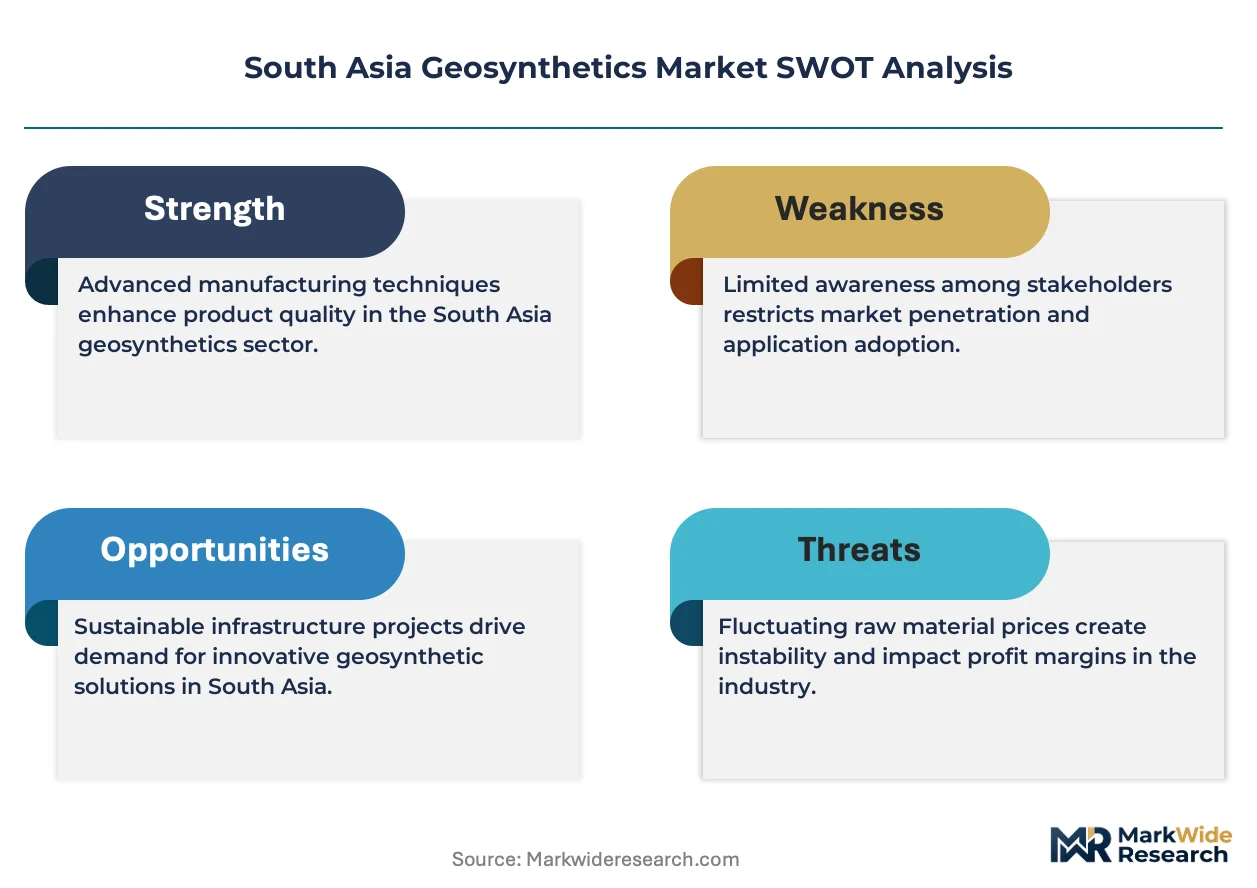
BIS standards govern material specifications for geosynthetics deployed in Indian public works, while Bangladesh's Roads and Highways Department enforces separate technical approval protocols for imported polymer products. The CEA's dam safety guidelines in India increasingly specify geosynthetic filters for reservoir rehabilitation, broadening the addressable market beyond transportation. Stakeholders must monitor evolving polymer feedstock costs and localized testing infrastructure capacity as project volumes scale across the subcontinent.
Market Dynamics
Road construction across India's Bharatmala highway corridors is concentrating polymer specification demand, while BIS certification tightening is filtering out substandard suppliers from public procurement pools. This dual pressure is restructuring competitive positioning around technical compliance and manufacturing scale.
Growth Catalysts
- Bharatmala Phase-II expansion:India's national highway development program is specifying geogrids for pavement reinforcement across 48,000 kilometers of new corridors, locking in multi-year material offtake.
- CEA dam safety mandates:India's Central Electricity Authority guidelines now require geosynthetic filters for reservoir rehabilitation, extending addressable demand beyond transportation into water infrastructure.
- Polypropylene formulation advances:High-tenacity virgin polymer grades are achieving 120 kN/m tensile strength ratings, enabling thinner pavement sections and reducing aggregate consumption for road builders.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyester resin prices fluctuate with crude oil derivatives, compressing margin predictability for converters serving fixed-price government contracts.
- Import dependence for specialty additives:UV stabilizers and anti-oxidant masterbatches concentrate among Southeast Asian chemical suppliers, exposing South Asian manufacturers to currency and shipping cost swings.
- Geogrid-geocell substitution economics:Three-dimensional cellular confinement systems compete directly with biaxial geogrids for slope stabilization, fragmenting specification standards across state public works departments.
Strategic Opportunities
- Bangladesh Padma Bridge connectivity:The southwestern road network expansion around the bridge is generating first-time demand for geosynthetics in a market historically reliant on conventional civil engineering methods.
- Coastal protection in Tamil Nadu and Gujarat:Port modernization and erosion control projects are specifying high-strength woven geotextiles for breakwater and revetment applications.
- PLI scheme for technical textiles:India's Production Linked Incentive scheme is subsidizing capital investment in geosynthetic manufacturing capacity, lowering entry barriers for domestic producers.
Industry Challenges
- BIS certification timeline compression:New product approval cycles now stretch 14-18 months, delaying market entry for novel polymer formulations and coating technologies.
- Field installation skill scarcity:Proper geogrid tensioning and overlap welding require trained crews, but contractor capacity for geosynthetic-specific deployment lags project award volumes in India's western states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Asia Geosynthetics Market |
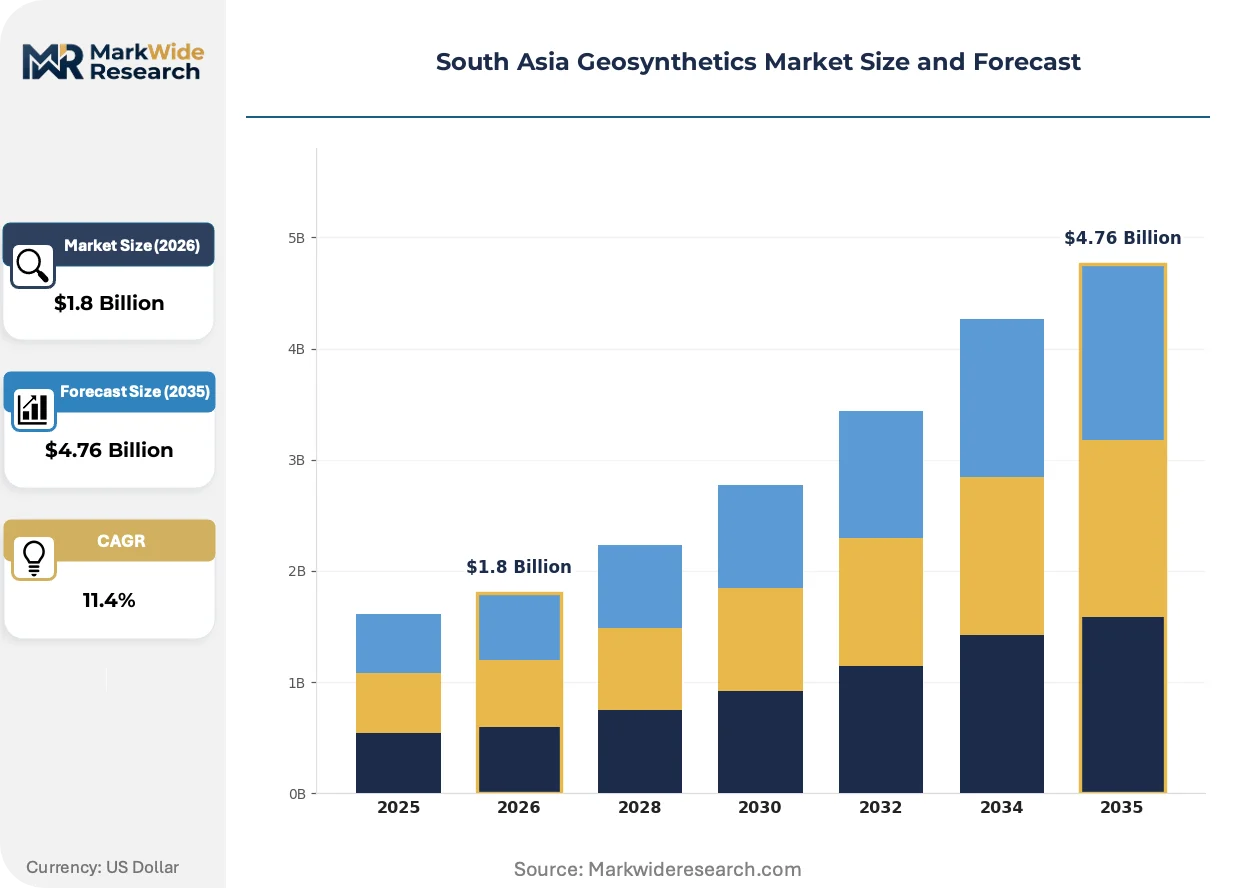
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
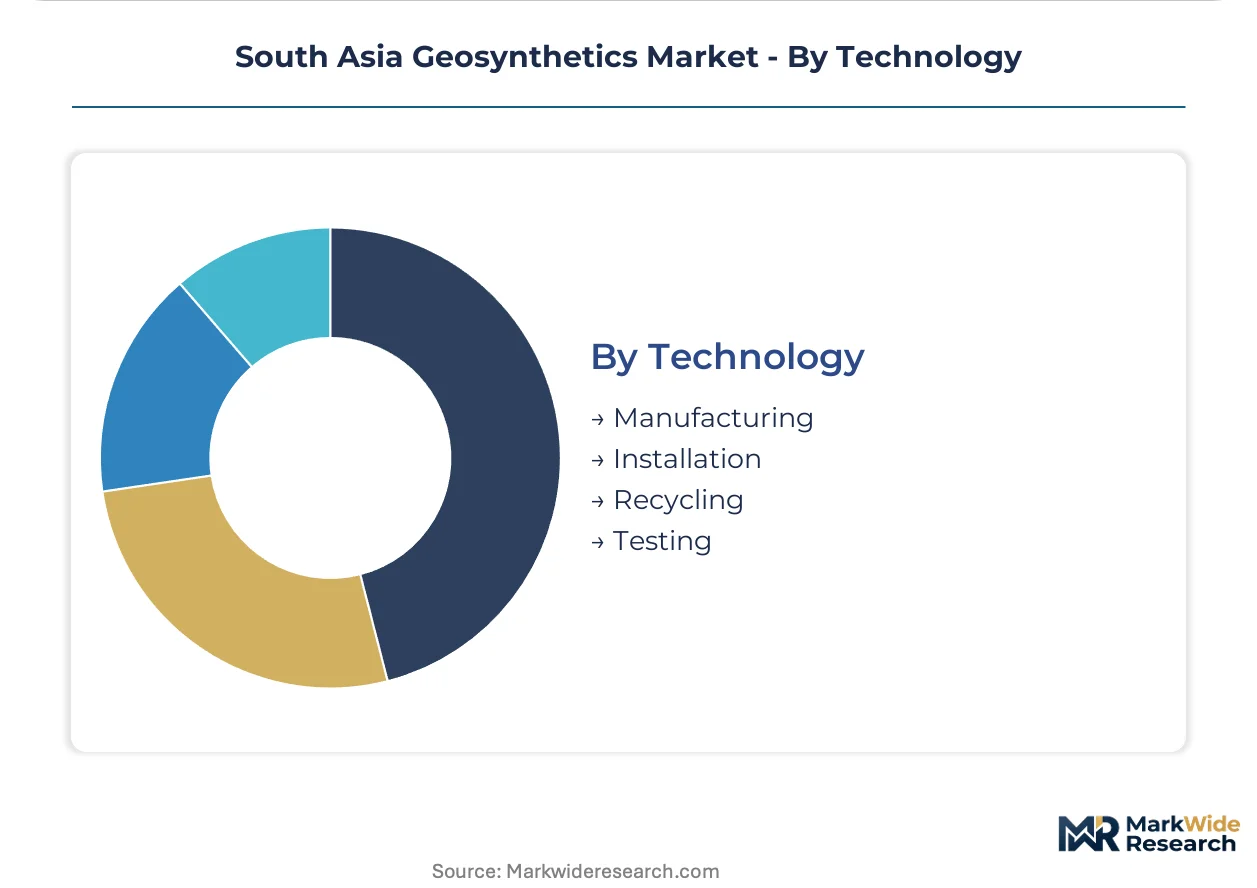
| Segmentation | Product Type: Geotextiles, Geocells, Geogrids, Geomembranes Application: Drainage, Erosion Control, Soil Stabilization, Landfills End User: Construction, Transportation, Agriculture, Environmental Technology: Manufacturing, Installation, Recycling, Testing |
| Companies Covered | Koninklijke TenCate NV, HUESKER Synthetic GmbH, GSE Environmental Inc, Tensar International Corporation, NAUE GmbH & Co. KG, Geofabrics Australasia Pty. Ltd., Enviro Geosynthetics Pvt. Ltd., TechFab India Industries Ltd., Garware Technical Fibres Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Asia Geosynthetics Market Strategic Shifts
Manufacturing automation and specification digitization are compressing quality variance and procurement cycles simultaneously. These shifts are redefining how material performance is verified and how projects source compliant products.
Co-extruded multilayer geomembranes incorporating conductive layers for leak detection are decentralizing quality assurance in landfill and containment applications. State pollution control boards in Maharashtra and Karnataka are mandating their inclusion in hazardous waste facility designs. This technology is decentralizing the role of third-party inspection services by embedding monitoring capability directly into the liner system.
BIS has revised IS 16391 for geosynthetic clay liners, tightening permeability and peel strength requirements effective for all new public works tenders. The standard's industrial consequence is disqualification of legacy bentonite-polyethylene composites that dominated the 2015-2020 project cycle. Landfill operators in Delhi-NCR and Mumbai metropolitan regions are responding by pre-qualifying only suppliers with in-house testing laboratories certified by the National Accreditation Board.
Buyers are consolidating vendor relationships around full-service contractors capable of design-assist, supply, and installation. India's national highway concessionaires are replacing fragmented material-procurement-plus-separate-installation models with single-source performance contracts. This pattern is most visible in Gujarat and Rajasthan where expressway projects are packaging geosynthetic scope within larger EPC agreements.
South Asia Geosynthetics Market Segmentation
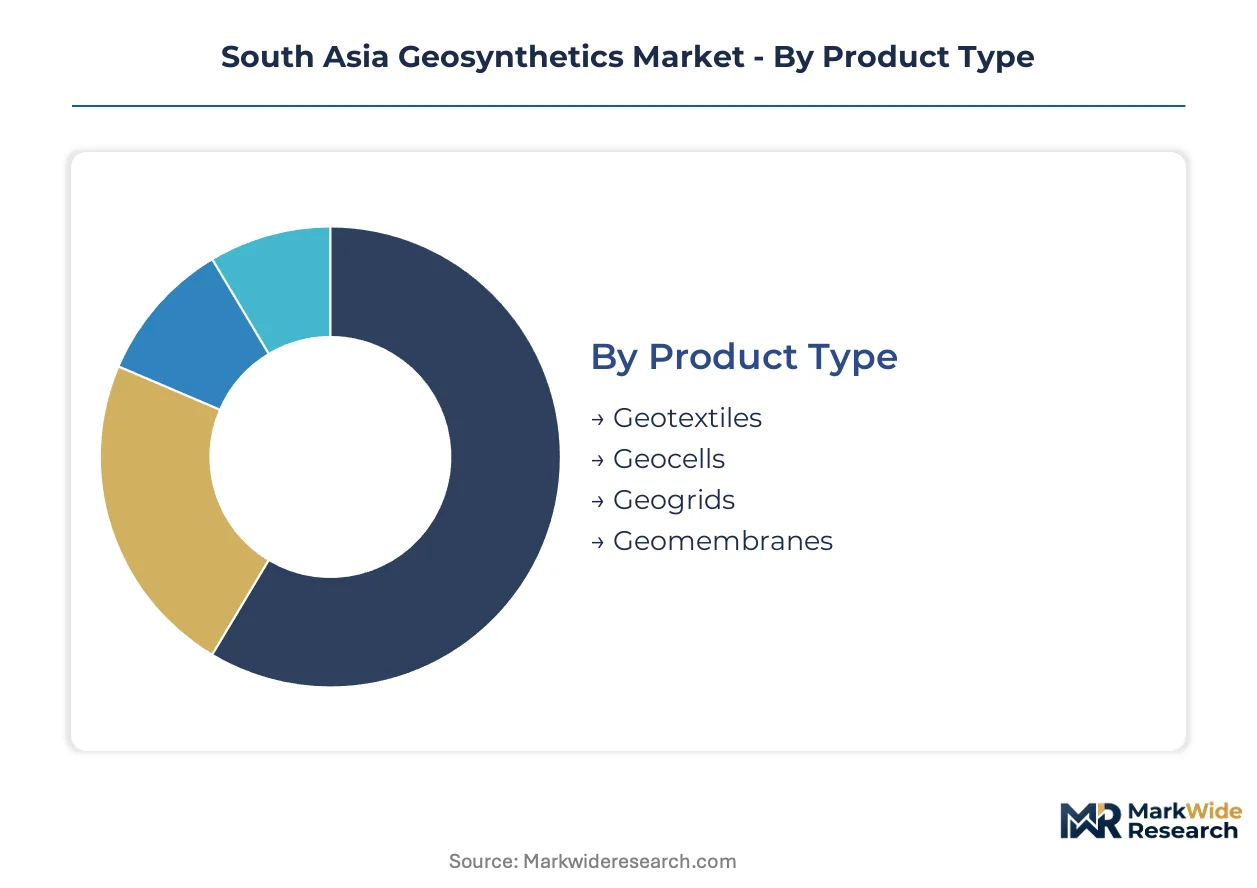
Geosynthetics procurement across South Asia fragments across four distinct classification schemes. Each dimension carries specific certification burdens from BIS, state pollution control boards, and project-specific technical specifications that filter supplier eligibility.
Product Type:
BIS IS 16391 governs geosynthetic clay liners and geomembranes with mandatory peel strength testing, while geotextiles fall under separate IS 14715 standards requiring tensile strength verification. Geogrids lack unified national standards, leaving specification to individual state public works departments.
- Geotextiles:Woven and non-woven polypropylene or polyester fabrics engineered for filtration, separation, and drainage functions. India's Bharatmala highway corridors in Gujarat and Rajasthan are specifying high-strength woven variants for subgrade stabilization, with BIS certification timelines stretching procurement cycles. Demand concentrates where expressway projects package geosynthetic scope within EPC agreements.
- Geogrids:Polymeric grid structures manufactured through extrusion and biaxial stretching to achieve high tensile modulus for soil reinforcement. Bihar and Uttar Pradesh state highways are deploying biaxial geogrids for pavement reinforcement, though specification standards fragment across jurisdictions. Polypropylene formulation advances achieving 120 kN/m ratings are enabling thinner pavement sections.
- Geocells:Three-dimensional honeycomb cellular confinement systems manufactured from textured polyethylene strips. Slope protection projects in Nepal's mountainous terrain are specifying geocells for erosion control on steep embankments.
- Geomembranes:Impermeable polymeric sheets deployed for containment and barrier applications. Co-extruded multilayer variants with conductive leak detection layers are now mandatory for hazardous waste facilities in Maharashtra and Karnataka under state pollution control board directives.
Geotextiles sits at the top of the volume ranking, with geomembranes climbing the fastest.
Application:
Application selection directly determines margin structure, with containment and rehabilitation projects commanding premium pricing over commodity drainage installations.
- Soil Stabilization:Geogrid and geocell deployment for slope reinforcement, retaining wall backfill, and soft ground improvement. Tamil Nadu's port modernization projects are specifying high-strength woven geotextiles combined with geogrids for breakwater foundation stabilization.
- Erosion Control:Surface protection systems utilizing geotextiles, turf reinforcement mats, and cellular confinement. Coastal protection initiatives in Gujarat are accelerating woven geotextile consumption for revetment and shoreline armoring applications.
- Drainage:Geotextile filter layers and geocomposite drainage systems for sub-surface water management. Road construction across India's western states is consolidating specification demand for filtration-grade non-woven geotextiles.
- Landfills:Composite liner systems integrating geomembranes, geosynthetic clay liners, and leak detection layers. Delhi-NCR and Mumbai metropolitan operators are pre-qualifying only suppliers with NABL-certified in-house testing laboratories following revised BIS permeability requirements.
Soil stabilization commands the largest project value, while landfill applications are expanding most quickly on regulatory tightening.
End User:
End-user concentration shapes geographic demand patterns, with national highway development concentrating procurement in India's western and southern states.
- Transportation:Road, rail, and airport infrastructure deploying geosynthetics for subgrade improvement and pavement reinforcement. India's Bharatmala Phase-II program is locking in multi-year material offtake across 48,000 kilometers of new highway corridors.
- Construction:Building foundations, retaining structures, and site development applications. Bangladesh's Padma Bridge connectivity projects are generating first-time geosynthetic demand in a market historically reliant on conventional civil engineering methods.
- Environmental:Waste containment, water treatment, and remediation applications. CEA dam safety guidelines are mandating geosynthetic filters for reservoir rehabilitation, extending addressable demand beyond transportation into water infrastructure.
- Agriculture:Pond linings, canal protection, and soil conservation in farming applications. Subsidized micro-irrigation programs in Maharashtra and Karnataka are specifying geomembrane-lined water harvesting structures.
Transportation dominates procurement volume, with environmental applications gaining share fastest on CEA mandate expansion.
Technology:
Technology tier determines supplier capability thresholds, with testing and installation services filtering competitive participation.
- Manufacturing:Extrusion, weaving, needle-punching, and thermal bonding processes for geosynthetic production. India's PLI scheme for technical textiles is subsidizing capital investment in manufacturing capacity, lowering entry barriers for domestic producers.
- Installation:Field deployment including geogrid tensioning, geomembrane welding, and quality assurance. Contractor capacity for geosynthetic-specific deployment lags project award volumes in India's western states, creating execution bottlenecks.
- Testing:Laboratory and field verification of tensile strength, permeability, and chemical resistance. BIS certification requirements now stretch 14-18 months for new product approvals, delaying market entry for novel formulations.
- Recycling:Post-consumer and post-industrial polymer recovery for secondary geosynthetic applications. Limited infrastructure exists for polypropylene geotextile reclamation, constraining circular economy development.
Manufacturing anchors supplier revenue, with installation services showing the steepest expansion trajectory on EPC contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing cost advantages and diverging certification timelines are redistributing production capacity across South Asian jurisdictions. Suppliers are arbitraging the gap between India's extended BIS approval cycles and Bangladesh's faster technical clearance pathways.
India
Bharatmala Phase-II highway corridors in Gujarat and Rajasthan are absorbing woven geotextile volumes for subgrade stabilization. BIS IS 16391 revisions now mandate NABL-certified laboratory testing for all geomembrane tenders, extending supplier qualification timelines. The Delhi-NCR and Mumbai metropolitan clusters concentrate landfill liner procurement under stricter state pollution control board directives.
Bangladesh
Padma Bridge southwestern connectivity projects are generating first-time specification demand for geogrids and geotextiles in road embankments. The Roads and Highways Department maintains separate technical approval protocols for imported polymer products, creating faster market entry than Indian certification. Dhaka-based contractors are sourcing materials through Chattogram port corridors for distribution across Khulna and Barisal divisions.
Pakistan
China-Pakistan Economic Corridor road upgrades in Punjab and Sindh provinces are deploying geosynthetics for soft ground improvement. The country's national highway regulator enforces material testing through designated public works laboratories, though standardization lags Indian BIS frameworks. Karachi and Lahore industrial zones host localized geotextile weaving operations serving infrastructure corridors.
Sri Lanka
Port City Colombo reclamation and coastal protection works are specifying high-strength woven geotextiles for marine applications. The country's urban development authority mandates third-party durability testing for polymer materials in saline environments. Western Province contractors concentrate procurement through Colombo-based distributors with warehousing at Hambantota port.
Nepal
Mountain road stabilization and hydropower reservoir projects in Gandaki and Bagmati provinces are accelerating geocell demand for slope protection. The Department of Roads maintains project-specific material approvals without unified national standards, enabling flexible supplier qualification. Kathmandu Valley fabricators serve as intermediaries for Indian and Chinese material imports.
South Asia Geosynthetics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-service providers capturing highway EPC packages while component suppliers serve fragmented state-level tenders. The vendor base concentrates around three archetypes: integrated manufacturers with in-house testing laboratories, regional converters sourcing masterbatch additives externally, and installation contractors backward-integrating into material supply. Capacity expansion and certification pre-qualification constitute the dominant competitive moves, as BIS timeline compression rewards early compliance investments.
Among European-headquartered material specialists, Koninklijke TenCate NV and HUESKER Synthetic GmbH occupy positions emphasizing technical specification leadership. NAUE GmbH & Co. KG represents the German engineering-focused tier. Within South Asian domestic production, TechFab India Industries Ltd., Garware Technical Fibres Ltd., and Enviro Geosynthetics Pvt. Ltd. anchor localized manufacturing capacity serving infrastructure corridors.
| Leading Market Players |
|---|
| Koninklijke TenCate NV |
| HUESKER Synthetic GmbH |
| GSE Environmental Inc |
| Tensar International Corporation |
| NAUE GmbH & Co. KG |
| Geofabrics Australasia Pty. Ltd. |
| Enviro Geosynthetics Pvt. Ltd. |
| TechFab India Industries Ltd. |
| Garware Technical Fibres Ltd. |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin spot indices on the Singapore exchange cascade through South Asian geosynthetic converter margins, compressing pricing tiers as feedstock volatility feeds into fixed-price government highway contracts. BIS certification delays amplify this pressure by trapping inventory carrying costs during 14-18 month approval windows.
Pricing Analysis
Distributor markups of 12-18% separate authorized BIS-certified stockists from direct mill sales to national highway concessionaires. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and NABL laboratory accreditation status. Cost compression in the economy tier is intensifying because state public works departments are consolidating procurement volumes under EPC contracts. Small regional contractors show highest price sensitivity, while landfill operators in Delhi-NCR and Mumbai metropolitan regions prioritize leak-detection geomembrane performance over unit cost.
Supply Chain Analysis
Container freight rates from Singapore and Jebel Ali anchor landed cost calculations for UV stabilizer masterbatches and anti-oxidant additives. Manufacturing concentrates in India, Bangladesh, and China, with Indian domestic producers drawing from Saudi and Qatari polypropylene feedstock. Single-source vulnerability concentrates in Southeast Asian chemical suppliers for specialty additives. Distribution runs through Chattogram and Colombo port corridors for Bangladesh and Sri Lankan project sites, with overland trucking from Ahmedabad and Pune serving Indian western state demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Asia geosynthetics function as a geographic-arbitrage play where Bangladesh's 6-9 month technical approval pathway under the Roads and Highways Department outpaces India's 14-18 month BIS cycles, rewarding early entrants with faster revenue recognition.
For Market Incumbents: Acquire NABL-certified testing laboratory assets to compress certification timelines and lock out substandard competitors. Backward integration into polypropylene compounding secures margin control against petrochemical feedstock swings. Threat substitution from geocell cellular confinement systems fragments geogrid specification standards across state public works departments. For New Entrants and Emerging Players: Begin with Bangladesh Padma Bridge connectivity corridors where first-time geosynthetic specification creates virgin demand without incumbent lock-in. Target Nepal's Gandaki and Bagmati province hydropower reservoir projects for geocell slope protection applications. Go-to-market angle: partner with Dhaka-based contractors already qualified under Roads and Highways Department protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap domestic manufacturers possessing in-house testing infrastructure and PLI scheme subsidy eligibility. Five-to-ten year viability hinges on Bharatmala Phase-II corridor completion rates and CEA dam safety mandate enforcement depth. Signal to watch: Maharashtra and Karnataka state pollution control board directives expanding conductive-layer geomembrane mandates to municipal solid waste facilities.| Strategic Initiative | Industry Significance |
|---|---|
| NABL Laboratory Acquisition | Compresses BIS certification timelines from 18 months to 12 months for new product entries. |
| Backward Integration into Compounding | Captive polypropylene formulation control insulates margins against Singapore exchange volatility. |
| Bangladesh Market Entry | Roads and Highways Department technical approvals enable faster revenue recognition than Indian BIS pathways. |
| Installation Capability Buildout | Trained geogrid tensioning crews address execution bottlenecks in Gujarat and Rajasthan expressway projects. |
| Conductive-Layer Geomembrane Capacity | Maharashtra pollution control board mandates create premium pricing tier for leak-detection liner systems. |
Study Parameters
Multiple input streams — primary interviews with BIS certification officers, highway project procurement managers, and polymer compound technical directors; secondary validation through BIS IS 16391 and IS 14715 standard documentation, Central Electricity Authority dam safety guidelines, and state pollution control board hazardous waste facility directives — were reconciled through bottom-up project pipeline aggregation and top-down polymer consumption modeling.
Data-stream reconciliation anchored volume projections across product type, application, end-user, and technology segmentation dimensions. CAGRs were derived from corridor-level Bharatmala Phase-II award schedules and CEA reservoir rehabilitation timelines. Forecast inputs incorporated polypropylene formulation tensile strength advances and PLI scheme capacity addition subsidies.
Several conditions sit outside the modeled scope, including abrupt BIS timeline extensions, currency devaluation impacts on imported additive costs, and geocell substitution rates in slope protection applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Aircraft Lighting Systems Market
Others
Global Computer Graphics Market
Others
Global Surface Analysis Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
US Mobile MRI Services Market
Others
Storage Dewars Market
Others
Floor Cleaning and Mopping Machine Market
Others
Global Digital Caliper Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Fire Sprinkler Market
Others
Global Cosmetovigilance Market
Others
Bitcoin Mining Servers Market
Others
Video Conferencing Hardware Market
Others
United States Smart Homes Market
Others
Healthcare Bioconvergence Market
Others
Plastic Films and Sheets Market