
 Nitrogen Tire Inflators Market | 2026-2036
Nitrogen Tire Inflators Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogen Tire Inflators Market Analytics
Chinese membrane separation equipment manufacturing is shifting toward higher-purity nitrogen generation systems for tire inflation applications. Pneumatech leverages its European engineering base to sustain premium positioning in stationary industrial units. Parker Hannifin anchors North American distribution through its fluid power and filtration channels. Kaeser Compressors competes on rotary screw integration, bundling compressed air with nitrogen separation.
Nitrogen tire inflators are machines that generate or dispense nitrogen gas at purities typically exceeding 95 percent for tire inflation, using membrane separation or pressure swing adsorption to extract nitrogen from ambient air. The equipment reduces oxidative degradation of tire rubber and maintains more stable pressure across temperature fluctuations than compressed air. Stationary systems dominate repair shop and fleet operator installations where volume throughput justifies capital expenditure. Portable units are gaining traction among individual consumers and mobile service providers seeking field flexibility. Membrane separation technology leads installed base due to lower maintenance requirements, while pressure swing adsorption commands premium applications demanding higher purity thresholds.
NHTSA tire pressure monitoring regulations and EPA greenhouse gas standards for commercial vehicles shape fleet procurement decisions toward nitrogen inflation systems in the United States. ISO 8573 air quality classifications and CE marking requirements influence product design for international equipment suppliers seeking cross-border market access. Stakeholders must monitor evolving fuel economy mandates and purity certification standards to align product development with compliance-driven procurement cycles.
Market Dynamics
Fleet operators in the United States face mounting pressure from EPA greenhouse gas standards for commercial vehicles, forcing capital allocation toward tire pressure management systems that demonstrably reduce rolling resistance and fuel burn across long-haul duty cycles.
Growth Catalysts
- EPA Phase 3 GHG Standards:The regulation mandates progressive fuel efficiency improvements for heavy-duty trucks, compelling fleet managers to adopt nitrogen inflation as a verified method for maintaining optimal tire pressure and reducing fuel consumption.
- Membrane separation advancement:Hollow-fiber membrane technology now delivers nitrogen purity exceeding 95 percent with minimal maintenance, lowering total cost of ownership for high-volume tire service operations.
- Aviation MRO expansion:Commercial aircraft maintenance facilities in the United States are retrofitting hangars with stationary nitrogen generators to meet FAA tire inflation protocols and reduce dependence on delivered gas cylinders.
Market Restraints
- Membrane fiber supply concentration:High-performance polyimide hollow fibers for nitrogen separation concentrate among specialty polymer manufacturers in Germany and Japan, exposing equipment assemblers to input cost volatility and extended lead times.
- Capital intensity of PSA systems:Pressure swing adsorption units require carbon molecular sieve beds and precision valve assemblies that demand substantial upfront investment, limiting adoption among independent repair shops with constrained balance sheets.
- Compressed air substitution:Conventional compressed air systems remain entrenched in consumer automotive segments where tire pressure monitoring systems satisfy regulatory minimums without purity premiums.
Strategic Opportunities
- Mobile service channel development:On-demand nitrogen tire inflation via van-mounted membrane units is penetrating last-mile delivery fleets and rental car operations seeking field-based pressure management without facility investment.
- IRA clean vehicle incentives:The Inflation Reduction Act's commercial vehicle tax credits are accelerating electric truck deployments, creating parallel demand for nitrogen systems that extend tire life on heavy battery-electric platforms with torque-rich drivetrains.
- IoT sensor convergence:Integration of nitrogen generators with cloud-connected pressure monitoring is enabling predictive maintenance contracts that bundle inflation services with real-time tire health analytics.
Industry Challenges
- Certification timeline compression:ISO 8573 air quality classifications and NHTSA equipment safety standards require extensive validation cycles that delay product launches and strain engineering bandwidth at smaller equipment manufacturers.
- Legacy fleet integration friction:Retrofitting nitrogen infrastructure into existing maintenance facilities demands reconfiguration of compressed air distribution networks, creating project complexity and downtime costs that stall procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Tire Inflators Market |
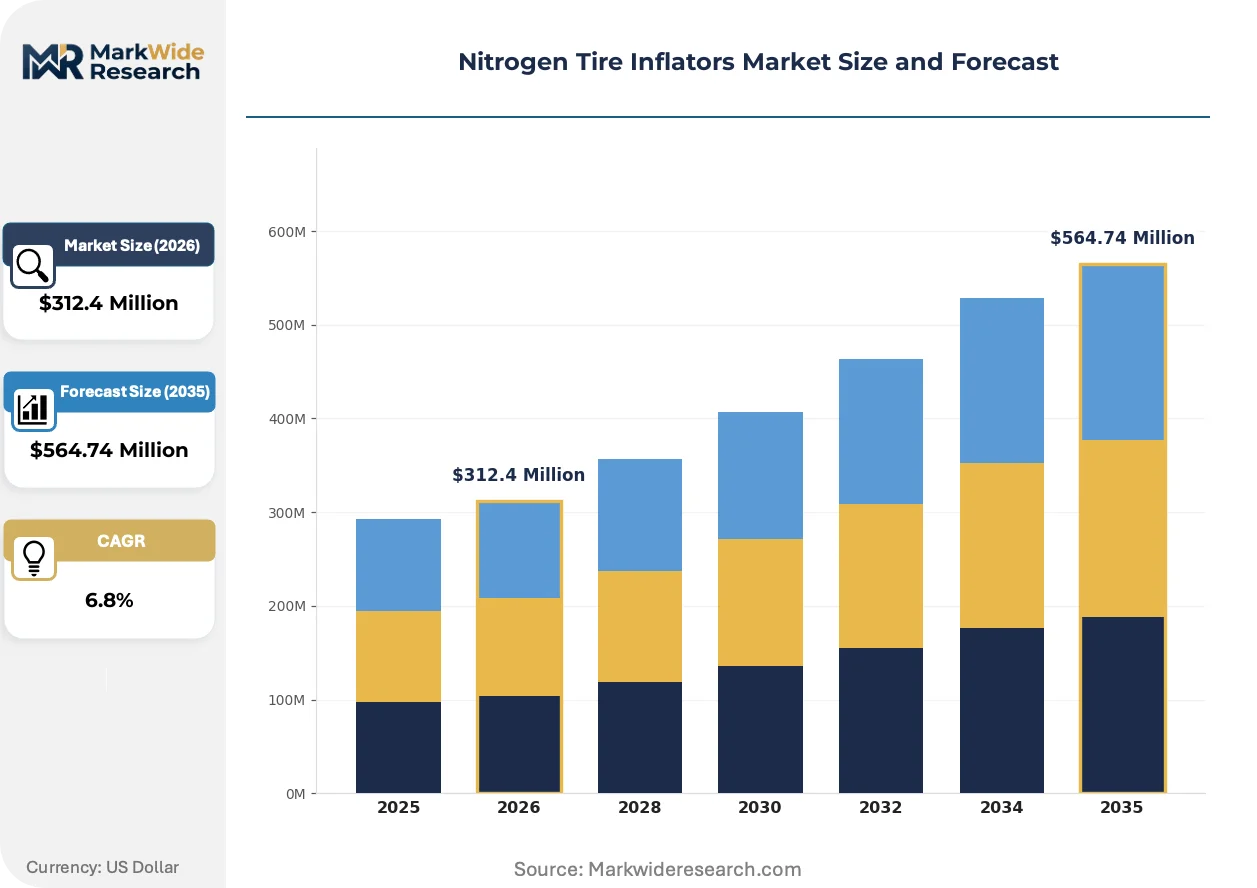
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Heavy-Duty, Compact Application: Automotive, Commercial Vehicles, Aviation, Racing End User: Repair Shops, Retailers, Fleet Operators, Individual Consumers Technology: Membrane Separation, Pressure Swing Adsorption, Vacuum, Cylinder Storage |
| Companies Covered | PurigeN98, Pneumatech, PCL, On Site Gas Systems, Parker Hannifin, NitroFill, Besser Industrial Tools, Branick, Kaeser Compressors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Tire Inflators Market Evolving Landscape
Digital control systems and connected service models are displacing manual operation across nitrogen generation equipment, compressing labor content in tire maintenance while enabling outcome-based pricing structures that align supplier revenue with fleet uptime metrics.
Smart membrane control systems are automating purity adjustment based on real-time feed air conditions and target tire specifications. Long-haul trucking fleets with centralized maintenance depots are adopting these units fastest, replacing fixed-output generators that waste energy on over-purification. The technology is automating operator decision-making and reducing nitrogen consumption variability across shift changes.
NHTSA tire pressure monitoring mandates are tightening compliance windows for commercial vehicle inspectors, accelerating replacement of manual gauge protocols with automated inflation stations. The regulatory pressure is compressing service times at fleet maintenance bays and elevating specification priority for equipment with integrated pressure verification. Heavy-duty truck terminals in California and Texas are responding with bulk nitrogen installations that feed multiple service bays simultaneously.
Service unbundling is fragmenting traditional equipment sales into rental and subscription arrangements. Independent tire dealers and mobile service operators are displacing capital purchase models with monthly fee structures that include generator maintenance and membrane replacement. This shift concentrates most visibly among regional delivery fleets with 50-200 vehicle counts that lack in-house compressed air expertise but require consistent pressure management across dispersed operations.
Nitrogen Tire Inflators Market Segmentation
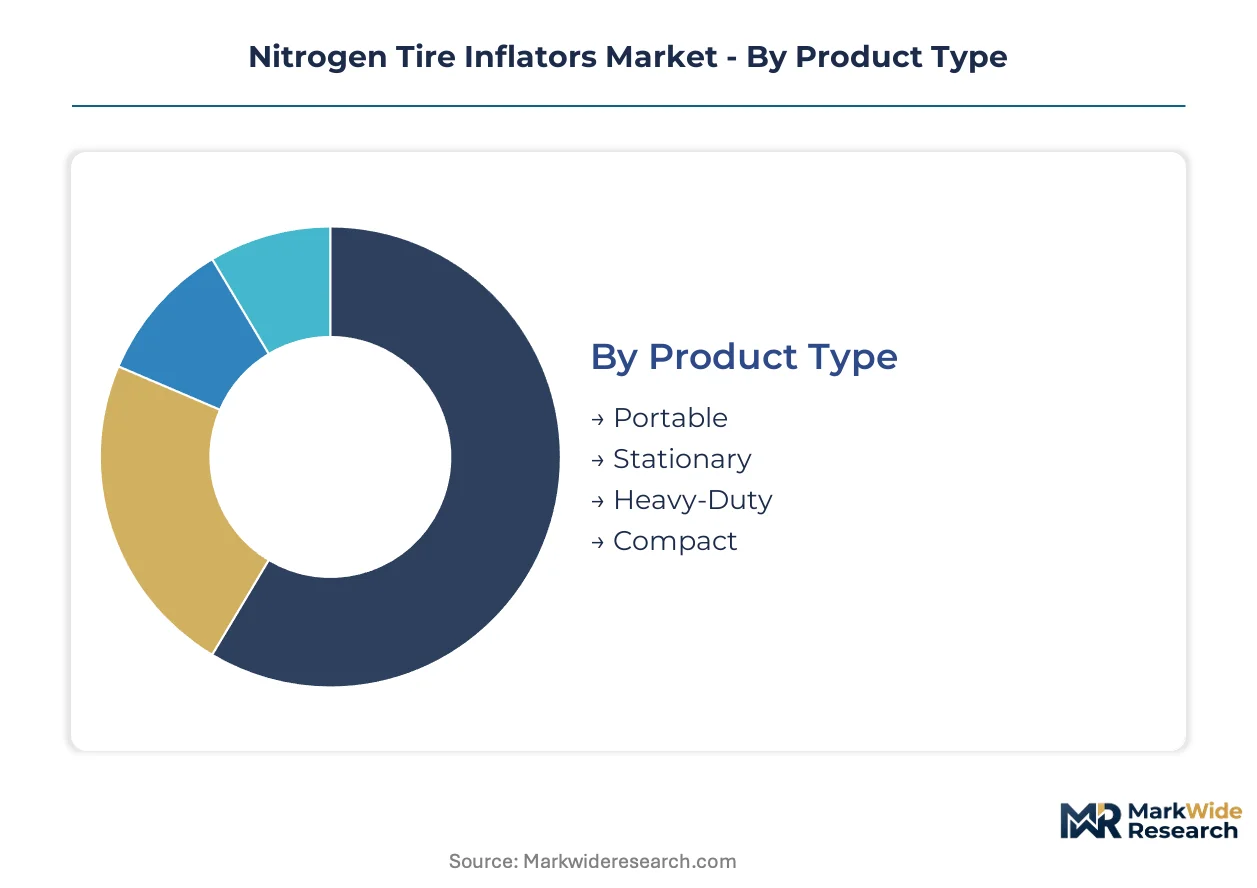
Nitrogen tire inflators serve divergent operational requirements across mobility ecosystems, from high-throughput fleet depots to individual vehicle owners. Segmentation reveals how equipment specifications, purity thresholds, and mobility constraints shape procurement patterns across buyer categories.
Product Type:
Equipment replacement cycles accelerate where membrane degradation or compressor wear creates throughput bottlenecks, forcing upgrade decisions based on duty-cycle intensity rather than calendar age.
- Stationary:Fixed installations integrate hollow-fiber membrane banks or PSA towers into centralized tire service bays, delivering continuous nitrogen output for facilities processing 50+ tires daily. Fleet operators in Texas and California anchor demand, driven by NHTSA inspection protocols that compress service windows and eliminate manual inflation variability.
- Portable:Mobile units mounted on service vehicles or rolling carts deploy membrane separation in compact enclosures, enabling field-based nitrogen delivery without facility infrastructure. Last-mile delivery fleets and rental car operations in Florida and Arizona are adopting these fastest, seeking pressure management flexibility across dispersed vehicle pools.
- Heavy-Duty:Industrial-scale generators pair high-capacity air compressors with dual-stage separation for aviation hangars and commercial truck terminals requiring 99%+ purity.
- Compact:Benchtop units target low-volume repair shops with intermittent nitrogen needs, trading throughput for minimal footprint and plug-and-play installation.
Stationary sits at the top of the volume ranking, with Portable climbing the fastest.
Application:
Cost tier differentiation separates specification-intensive aviation and racing applications from price-sensitive automotive service, with purity certification requirements driving margin stratification.
- Commercial Vehicles:Long-haul trucking fleets and regional delivery operators deploy nitrogen systems to maintain tire pressure across temperature swings and reduce rolling resistance. EPA Phase 3 GHG standards are compelling capital allocation toward tire pressure management as a verified fuel efficiency lever, with heavy-duty terminals in the Midwest leading retrofit activity.
- Aviation:Aircraft maintenance facilities require nitrogen purity exceeding 99.5% for tire inflation per FAA protocols, mandating PSA or high-grade membrane systems with continuous monitoring. MRO expansion in Georgia and Washington state is displacing delivered cylinder dependencies with on-site generation.
- Automotive:Passenger vehicle service represents the broadest addressable base, though compressed air substitution limits nitrogen penetration in price-sensitive consumer segments.
- Racing:Motorsport teams demand ultra-stable pressure characteristics for performance optimization, accepting premium pricing for laboratory-grade purity verification.
Commercial Vehicles commands the largest installed base, while Aviation is gaining share fastest on MRO infrastructure investment.
End User:
Customer type determines procurement modality, with fleet operators favoring capital purchase and independent dealers shifting toward subscription-based service models.
- Fleet Operators:Centralized maintenance organizations with 100+ vehicle counts justify bulk nitrogen infrastructure feeding multiple service bays simultaneously. These buyers prioritize equipment uptime guarantees and predictive maintenance contracts over upfront cost minimization.
- Repair Shops:Independent tire dealers and automotive service centers represent fragmented demand, increasingly adopting rental arrangements that bundle generator maintenance and membrane replacement to bypass compressed air expertise gaps.
- Retailers:Big-box automotive chains and dealership service lanes deploy nitrogen as a premium service differentiator, integrating inflation stations into customer-facing bay designs.
- Individual Consumers:Enthusiast vehicle owners and specialty tire purchasers drive portable unit sales, though price sensitivity and compressed air availability constrain mass-market penetration.
Fleet Operators dominate revenue concentration, with Repair Shops expanding most quickly on service unbundling trends.
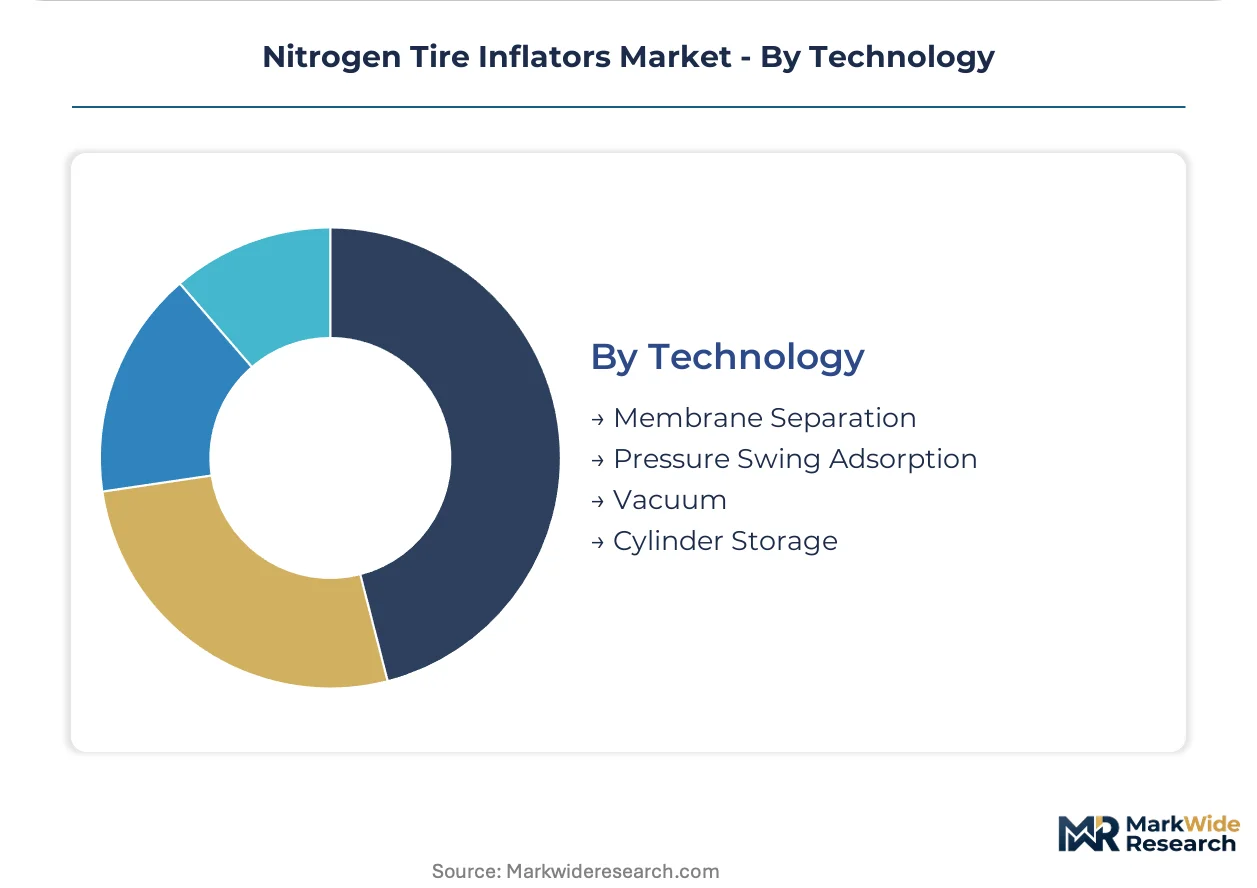
Technology:
Supply concentration in hollow-fiber polymers and carbon molecular sieves shapes equipment economics, with membrane technology leveraging lower maintenance profiles against PSA's purity superiority.
- Membrane Separation:Hollow-fiber polyimide membranes extract nitrogen through selective permeability, achieving 95-99% purity with minimal moving parts and reduced maintenance intervals. The technology leads installed base in tire service applications where 95-98% purity satisfies commercial vehicle and automotive requirements.
- Pressure Swing Adsorption:Carbon molecular sieve beds adsorb oxygen under pressure, cycling between towers to deliver 99.9%+ nitrogen for aviation and specialty applications demanding maximum purity assurance.
- Vacuum:Vacuum pressure swing adsorption variants reduce energy consumption for smaller-scale generation, though limited adoption in tire-specific applications constrains market presence.
- Cylinder Storage:Delivered bulk nitrogen in high-pressure cylinders persists in legacy aviation facilities and remote operations lacking compressed air infrastructure or electrical supply for on-site generation.
Membrane Separation holds the volume lead, with Pressure Swing Adsorption showing steepest expansion on aviation MRO retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands installed base volume for nitrogen tire inflators, while Germany concentrates precision engineering supply for membrane separation systems. China is scaling domestic production to serve Asia-Pacific fleet modernization programs.
United States
Long-haul trucking fleets and aviation maintenance facilities drive equipment procurement, with EPA Phase 3 GHG standards compelling tire pressure management investments. NHTSA inspection protocols compress service windows at commercial vehicle terminals. Heavy-duty truck maintenance hubs in Texas and California are retrofitting bulk nitrogen infrastructure across multiple service bays.
Germany
Specialty polymer manufacturers supply high-performance polyimide hollow fibers for membrane separation systems, anchoring European equipment supply chains. REACH chemical safety classifications influence material selection for nitrogen generation components. Industrial clusters in Baden-Württemberg engineer precision valve assemblies and carbon molecular sieve beds for pressure swing adsorption units.
China
Domestic membrane separation equipment manufacturing is shifting toward higher-purity nitrogen generation systems for tire inflation applications. MIIT industrial upgrading directives accelerate domestic substitution in compressed gas equipment. Manufacturing centers in Jiangsu and Zhejiang provinces scale production of hollow-fiber membrane banks for regional fleet service markets.
Japan
Carbon molecular sieve and advanced adsorption material suppliers serve premium aviation and industrial nitrogen generation applications. METI energy efficiency standards shape equipment design priorities for on-site gas generation. Industrial corridors around Osaka and Nagoya concentrate precision materials engineering for high-purity separation systems.
India
Commercial vehicle fleet operators in logistics and e-commerce sectors are piloting nitrogen tire inflation programs to reduce fuel consumption and extend tire replacement intervals. BIS certification requirements for compressed gas equipment create compliance benchmarks for imported and domestic systems. Automotive service clusters in Maharashtra and Tamil Nadu test mobile nitrogen delivery models for decentralized fleet operations.
Nitrogen Tire Inflators Market Competitive Landscape
North American producers anchor one tier; European specialists hold premium positioning in precision-engineered membrane and adsorption systems. The vendor base concentrates around industrial gas equipment conglomerates and compressed air specialists diversifying into nitrogen separation. Two strategic archetypes dominate: diversified industrial gas equipment houses leveraging distribution scale, and focused membrane technology specialists competing on purity engineering. Capacity expansion in Asian manufacturing hubs and technology licensing partnerships represent the dominant competitive moves reshaping supply availability.
Among diversified industrial equipment manufacturers, Parker Hannifin and Kaeser Compressors exemplify scale-driven positioning, with the former anchoring North American distribution through fluid power channels and the latter bundling rotary screw compression with nitrogen separation. Pneumatech occupies a position within the European engineering tier, sustaining premium positioning in stationary industrial units. These three represent contrasting geographic and strategic archetypes: US-based conglomerate diversification, German compressed air integration, and European precision engineering specialization.
| Leading Market Players |
|---|
| PurigeN98 |
| Pneumatech |
| PCL |
| On Site Gas Systems |
| Parker Hannifin |
| NitroFill |
| Besser Industrial Tools |
| Branick |
| Kaeser Compressors |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up membrane specialists anchor mid-market pricing discipline, compressing margin buffers for independent assemblers while concentrating procurement leverage around hollow-fiber supply contracts. Their ownership structure rewards volume throughput over premium positioning, reshaping how fleet operators negotiate service agreements and equipment leases.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade membrane systems, forcing European and North American producers toward premium-mid-economy pricing differentiation. Price differentiation hinges on purity certification tier and after-sales service bundling, with aviation-grade PSA units commanding substantial premiums over commercial vehicle membrane configurations. Cost compression in entry-level portable units is intensifying because of domestic manufacturing scale in Jiangsu province. Individual consumers exhibit highest price sensitivity, while aviation MRO facilities remain least price-sensitive due to FAA-mandated purity thresholds.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty polymer manufacturers controlling high-performance polyimide hollow-fiber production. Geographic supply concentration centers on China for membrane bank assembly, Germany for precision valve components, and Japan for carbon molecular sieve materials. Raw material dependencies include polyimide resins, compressed air system components, and carbon molecular sieve beds. Tariff exposure on Chinese-manufactured membrane units creates structural risk for North American distributors. Distribution runs through fluid power and industrial gas equipment channels, with OEM-direct sales gaining share in fleet operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with fleet procurement shifting toward predictive maintenance contracts that bundle nitrogen generation with IoT-enabled pressure monitoring. Premium specifications now dominate procurement evaluation criteria over upfront capital cost minimization.
For Market Incumbents: Acquire membrane replacement service contracts to lock in recurring revenue streams and defend against compressed air substitution threats. Consolidate regional service networks to capture independent repair shop demand migrating toward subscription models. Backward integration into hollow-fiber sourcing reduces exposure to German and Japanese supply concentration. For New Entrants and Emerging Players: EPA Phase 3 GHG standards in the United States open a window for mobile nitrogen service platforms targeting last-mile delivery fleets lacking facility infrastructure. Focus white-space capture on 50-200 vehicle regional fleets in Texas and Florida seeking field-based pressure management. Pursue van-mounted membrane unit deployment as the primary go-to-market angle, bypassing capital-intensive stationary installation competition. For Investors and Strategic Acquirers: Valuations sit cheapest among independent membrane technology specialists lacking fleet operator channel relationships. Long-term viability favors equipment-as-a-service platforms with embedded IoT analytics capabilities over pure hardware manufacturers. Acquisition target archetypes include mobile service operators with established fleet contracts and membrane engineering firms with aviation certification pathways. Watch NHTSA inspection protocol tightening as the inflection signal for accelerated equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Chinese manufacturers leverage licensed European designs to penetrate aviation-grade purity segments. |
| Mobile Service Fleet Expansion | Van-mounted nitrogen units capture last-mile delivery demand in California and Texas markets. |
| IoT Platform Integration | Cloud-connected pressure monitoring enables predictive maintenance contracts with fleet uptime guarantees. |
| Aviation MRO Partnership | On-site generator installations displace delivered cylinder dependencies per FAA tire inflation protocols. |
| Backward Integration into Fibers | Equipment assemblers secure captive polyimide supply to mitigate German-Japanese concentration risk. |
Research Methodology
Coverage spans the United States, Germany, China, and Japan, with primary inputs from each market informing demand and supply assessments. The approach combines structured interviews with fleet maintenance directors, aviation MRO procurement managers, membrane equipment engineers, and industrial gas distribution channel heads with secondary validation. Secondary sources include NHTSA regulatory filings, EPA greenhouse gas standard documentation, customs trade data for membrane separation equipment, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up tire service operation modeling and top-down industrial gas equipment market sizing provide triangulation anchors.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include product mobility class, purity technology type, end-use application tier, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, fleet expansion rates, and aviation MRO infrastructure investment trajectories. Industry-specific inputs incorporate EPA Phase 3 compliance timelines, NHTSA inspection window compression effects, and membrane degradation curves for service contract pricing.
Revisions become necessary when EPA regulatory enforcement intensity shifts, hollow-fiber supply disruptions materialize, or compressed air substitution accelerates in price-sensitive consumer segments. Forecasts reflect documented assumptions about fleet electrification pace and aviation travel recovery patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market