
 OBD-Linked Predictive Maintenance Diagnostic Platforms Market | 2026-2036
OBD-Linked Predictive Maintenance Diagnostic Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
OBD-Linked Predictive Maintenance Diagnostic Platforms Market Insights
Fragmentation among mid-size logistics providers is repositioning procurement authority away from top-tier fleets toward regional operators with smaller IT budgets. Bosch leverages its embedded sensor portfolio to anchor hardware-software bundling across European markets. Continental competes through specialized diagnostic modules calibrated for heavy-duty powertrains. Geotab sustains cloud-native architecture leadership with real-time streaming capabilities purpose-built for distributed fleet architectures.
OBD-linked predictive maintenance diagnostic platforms integrate onboard vehicle diagnostics with algorithmic failure prediction, typically processing CAN bus data streams at 500 kbps to forecast component degradation before fault codes trigger. These systems serve commercial and industrial operators by minimizing unplanned downtime and extending asset replacement cycles. Machine learning deployments now dominate technology adoption as neural network inference migrates toward edge devices, while fleet management applications command the largest revenue pool due to recurring software subscription structures. Integrated platforms attract the fastest growth as operators reject siloed hardware and software procurement models.
NHTSA mandates in the United States and EU Green Deal carbon tracking requirements in Europe are reshaping product certification standards and data logging obligations for platform vendors. EPA emissions enforcement and REACH chemical compliance for sensor materials further constrain hardware design choices across transatlantic supply chains. Stakeholders must weigh regulatory divergence against platform standardization economics when architecting multi-jurisdiction deployments.
Market Dynamics
Machine learning inference migration toward edge devices is compressing hardware refresh cycles while fragmenting procurement authority across mid-size fleet operators with constrained IT infrastructure budgets.
Growth Catalysts
- EPA emissions enforcement:Tightened compliance mandates in the United States compel fleet operators to deploy real-time diagnostic logging for audit trails and preemptive fault detection.
- Telematics penetration:Deepening connectivity coverage across commercial vehicle populations generates high-fidelity CAN bus data streams necessary for algorithmic failure prediction.
- EU Green Deal carbon tracking:Mandatory emissions accounting for transport operators across Germany, France, and the Netherlands drives platform adoption for automated compliance reporting.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication concentrates in Taiwan and South Korea, exposing platform vendors to geopolitical supply disruption risks.
- REACH chemical compliance:Sensor material restrictions constrain hardware design flexibility and extend European certification timelines for new product variants.
- Legacy fleet substitution:Retrofit hardware costs for pre-OBD-II commercial vehicles limit addressable market penetration among aging asset bases.
Strategic Opportunities
- India commercial vehicle digitization:BIS telematics mandates for heavy-duty trucks create first-mover positioning for platforms compliant with local data localization requirements.
- Edge-cloud hybrid architectures:Convergence of on-vehicle neural inference with centralized fleet analytics enables tiered service models for distributed operator networks.
- Insurance-linked data monetization:Usage-based coverage products from European automotive insurers generate new revenue streams for aggregated predictive risk scores.
Industry Challenges
- Embedded systems engineering scarcity:Shortages of firmware developers with CAN protocol expertise constrain vendor scaling and extend product development cycles.
- NHTSA cybersecurity certification:Evolving vehicle data protection standards create compliance uncertainty and require iterative platform redesigns for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OBD-Linked Predictive Maintenance Diagnostic Platforms Market |
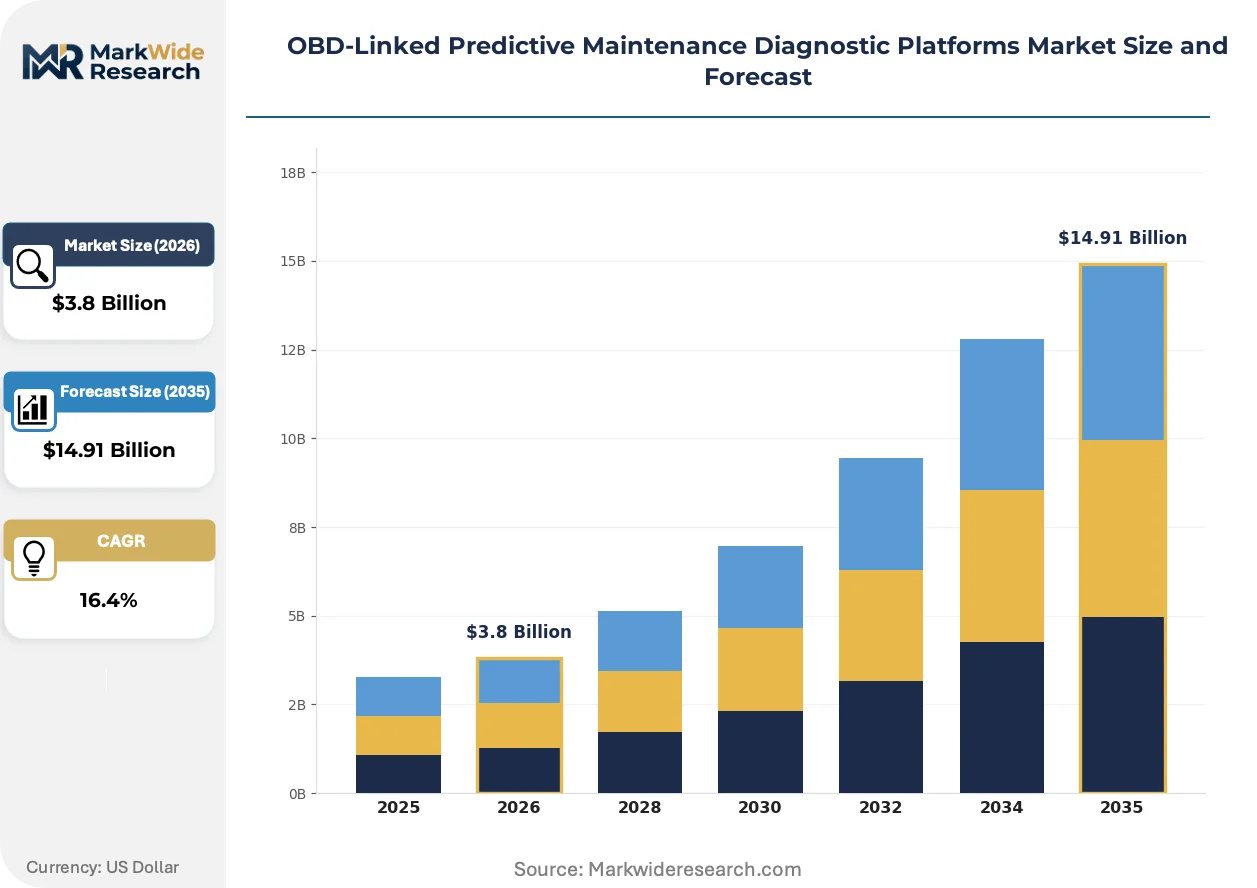
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Units, Software Solutions, Integrated Platforms, Cloud-Based Systems, Edge Devices Technology: Machine Learning, Neural Networks, Fuzzy Logic, Rule-Based Systems, Statistical Analysis Application: Fleet Management, Equipment Monitoring, Predictive Analytics, Vehicle Health Reporting, Asset Optimization End User: Logistics Providers, Rental Companies, Public Transit Operators, Heavy Equipment Operators, Mining Contractors |
| Companies Covered | Bosch, Continental, Geotab, Samsara, IBM, Microsoft, Siemens, Noregon, ACTIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OBD-Linked Predictive Maintenance Diagnostic Platforms Market Trends and Innovations
Neural network compression techniques and federated learning frameworks are redistributing computational workloads across vehicle-edge-cloud hierarchies, altering platform economics and vendor specialization patterns.
TensorFlow Lite and ONNX Runtime deployments on ARM Cortex-M automotive microcontrollers are rewriting failure prediction latency benchmarks. Tier-2 logistics operators in Germany and Japan are piloting these configurations for brake wear and battery degradation alerts. The shift is compressing subscription pricing tiers by collapsing hardware gateway requirements.
EU AI Act conformity assessments for safety-critical automotive applications are mandating algorithmic explainability documentation. Platform vendors serving Dutch and Belgian fleet markets must now embed decision-traceability modules alongside predictive outputs. Heavy-duty powertrain diagnostics face the steepest compliance burden due to collision-risk classification thresholds.
Mid-size fleet purchasing committees are consolidating software procurement authority previously dispersed across maintenance, compliance, and IT departments. Regional logistics operators in the US Midwest and German Ruhr Valley now demand bundled hardware-software contracts with uptime guarantees. This behavioral shift favors integrated platform vendors over specialized diagnostic hardware suppliers.
OBD-Linked Predictive Maintenance Diagnostic Platforms Market Segmentation
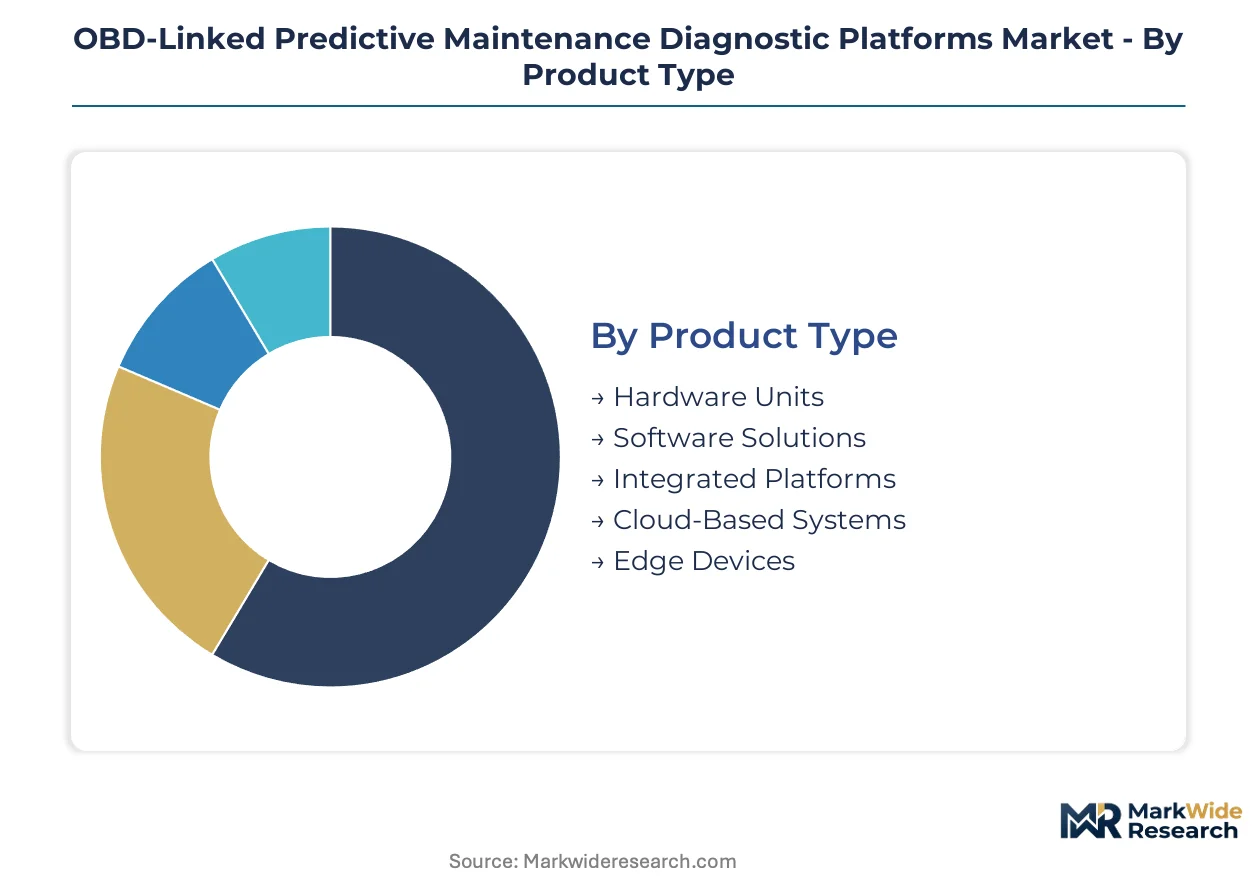
OBD-linked predictive maintenance platforms fragment across hardware-software boundaries and deployment architectures, with integration depth determining procurement patterns. Fleet operators now reject standalone diagnostics in favor of unified systems that collapse sensor acquisition, edge inference, and cloud analytics into single vendor relationships.
Product Type:
Standalone hardware deployments dominate legacy fleet retrofits, while embedded software and integrated platforms capture new vehicle procurement and digital transformation budgets.
- Hardware Units:Physical diagnostic interfaces and telematics gateways process raw CAN bus signals at the vehicle level. Demand concentrates among US Midwest and German Ruhr Valley logistics operators retrofitting pre-OBD-II asset bases where full platform replacement is cost-prohibitive.
- Software Solutions:Cloud-hosted analytics engines ingest telematics feeds for failure prediction algorithm execution. Fleet management departments at Netherlands and Belgian operators prioritize these for rapid deployment without hardware procurement cycles, driven by EU Green Deal carbon tracking mandates.
- Integrated Platforms:Bundled sensor-software-cloud offerings from single vendors.
- Cloud-Based Systems:Centralized predictive analytics without on-vehicle edge processing.
- Edge Devices:ARM Cortex-M microcontrollers executing TensorFlow Lite inference locally.
Volume placements concentrate in Software Solutions; the faster expansion belongs to Integrated Platforms.
Technology:
Algorithm sophistication tiers separate premium predictive accuracy from cost-constrained rule-based implementations, with neural architectures displacing statistical methods in safety-critical powertrain monitoring.
- Machine Learning:Supervised learning pipelines trained on historical failure patterns across component populations. German heavy-duty OEMs and Japanese commercial vehicle manufacturers deploy these for brake wear and battery degradation forecasting, compelled by KBA and METI safety documentation requirements.
- Neural Networks:Deep learning architectures processing multi-sensor fusion for anomaly detection. Dutch fleet operators pilot these under EU AI Act conformity assessments for heavy-duty collision-risk classification, where algorithmic explainability documentation is now mandatory.
- Fuzzy Logic:Heuristic rule systems for uncertainty-tolerant diagnostics.
- Rule-Based Systems:Deterministic if-then logic for standardized fault code interpretation.
- Statistical Analysis:Regression-based trend detection for component lifecycle estimation.
Procurement volume clusters in Machine Learning; Neural Networks are climbing the fastest as edge compression techniques mature.
Application:
Use case specialization reflects organizational maturity, with basic monitoring giving way to predictive optimization as data infrastructure and analytical capabilities deepen.
- Fleet Management:Comprehensive vehicle oversight combining location tracking, maintenance scheduling, and compliance reporting. US logistics providers and German freight operators command the largest revenue pool here due to recurring software subscription structures and NHTSA audit trail mandates.
- Equipment Monitoring:Non-vehicle asset diagnostics extending to attached machinery and trailers.
- Predictive Analytics:Forward-looking failure probability scoring for component replacement timing.
- Vehicle Health Reporting:Standardized condition summaries for maintenance handoffs and resale documentation.
- Asset Optimization:Lifecycle value maximization through replacement cycle engineering.
Revenue concentration sits with Fleet Management; Asset Optimization gains share fastest among mid-size operators consolidating procurement authority.
End User:
Operational intensity and regulatory exposure differentiate customer segments, with emissions-intensive applications commanding premium platform investments.
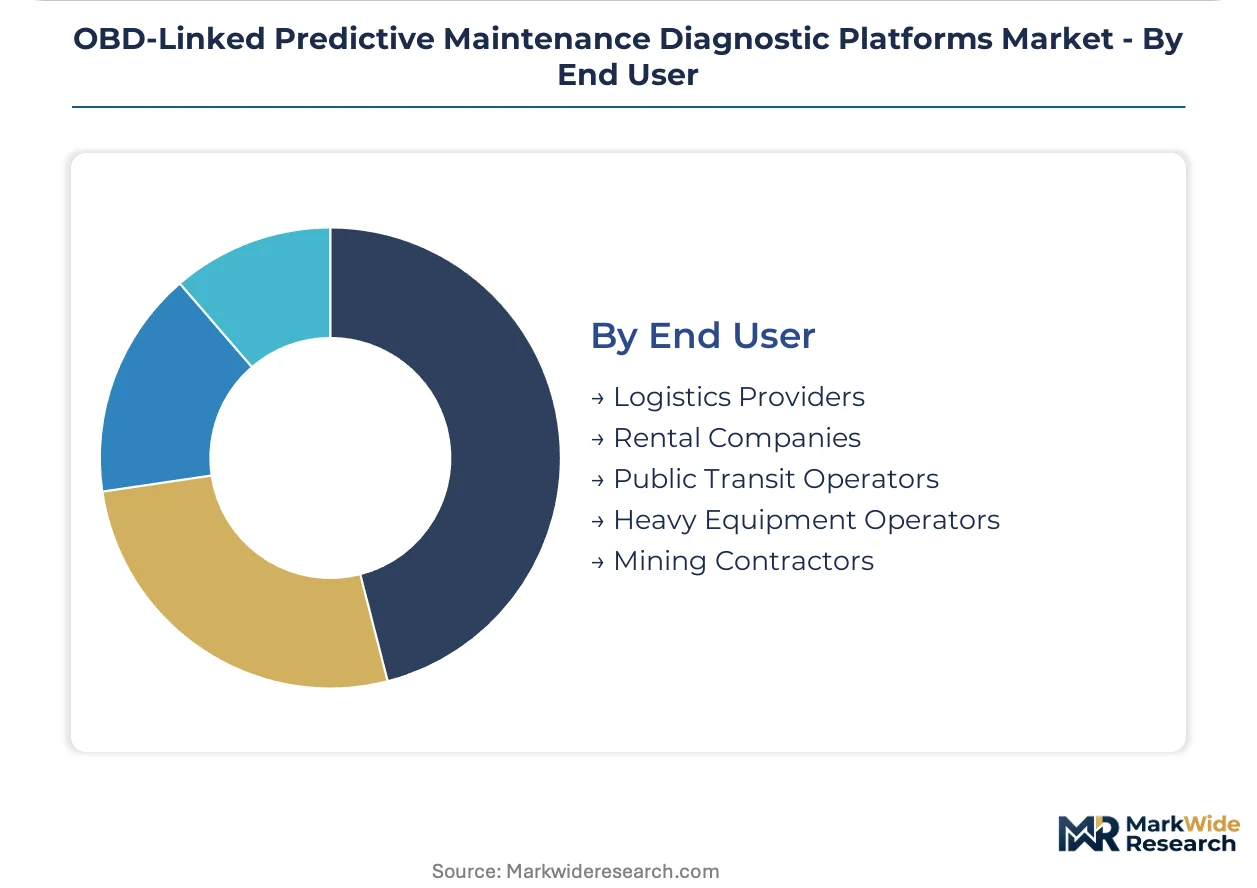
- Logistics Providers:Goods transport fleets operating under tight delivery windows and EPA emissions enforcement. Regional operators across the US Southeast and German industrial corridors now consolidate software procurement authority previously dispersed across maintenance, compliance, and IT departments.
- Rental Companies:Short-term vehicle lessors requiring rapid condition assessment between customer turnovers.
- Public Transit Operators:Municipal and regional bus fleets subject to uptime guarantees and passenger safety regulations.
- Heavy Equipment Operators:Construction and agricultural machinery fleets with intermittent utilization patterns.
- Mining Contractors:Extractive industry operators managing extreme-duty powertrains in remote deployment conditions.
Contract volume concentrates in Logistics Providers; Mining Contractors show the steepest expansion trajectory as autonomous haulage adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle density and emissions enforcement intensity concentrate platform demand in Germany, the United States, and Japan. Fleet digitization timelines diverge sharply across regulatory jurisdictions.
United States
EPA emissions enforcement and NHTSA audit trail mandates compel logistics operators to deploy real-time diagnostic logging. The US Southeast freight corridor drives retrofit hardware demand among regional carriers consolidating previously siloed procurement functions.
Germany
KBA safety documentation requirements and EU Green Deal carbon tracking accelerate predictive platform adoption. The Ruhr Valley industrial cluster anchors heavy-duty powertrain diagnostic deployments for brake wear and battery degradation forecasting.
Japan
METI safety mandates and dense commercial vehicle populations create concentrated demand for algorithmic failure prediction. Nagoya's automotive manufacturing belt generates edge-device pilot programs for TensorFlow Lite deployments on ARM Cortex-M microcontrollers.
Netherlands
EU AI Act conformity assessments for heavy-duty collision-risk classification mandate algorithmic explainability documentation. Rotterdam's port logistics operators pilot neural network architectures with embedded decision-traceability modules.
India
BIS telematics mandates for heavy-duty trucks create first-mover positioning for platforms compliant with local data localization requirements. Maharashtra's commercial vehicle registration hubs drive software solution demand among emerging fleet operators.
OBD-Linked Predictive Maintenance Diagnostic Platforms Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and edge-AI specialization. The vendor base stratifies across integrated platform bundlers, diagnostic hardware specialists, and pure-play analytics providers. Two strategic archetypes dominate: sensor-software integrators leveraging embedded portfolios, and cloud-native specialists streaming real-time CAN bus data. Competitive moves center on hardware-software bundling contracts and edge-cloud hybrid architecture development.
Within the integrated platform tier, Bosch and Continental exemplify sensor-software bundling strategies across European markets. Geotab occupies a position representing cloud-native architecture leadership with distributed fleet capabilities. These three anchors illustrate the divergence between hardware-rooted and software-native competitive vectors.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Geotab |
| Samsara |
| IBM |
| Microsoft |
| Siemens |
| Noregon |
| ACTIA |
| Others |
Pricing and Supply Chain Analysis
ARM Cortex-M microcontroller unit costs cascade through three distinct pricing tiers as fleet operators balance edge inference performance against cloud analytics expenditure. German heavy-duty OEMs and US Midwest logistics providers anchor premium tier procurement, while Indian commercial vehicle digitization programs concentrate demand at standard tier price points.
Pricing Analysis
Volume placements cluster in software subscription tiers with per-vehicle monthly fees, while margin capture concentrates in integrated platform bundles combining sensor hardware with multi-year analytics contracts. Price differentiation separates EPA-certified audit trail systems from basic diagnostic logging configurations. Cost compression in edge AI chip procurement is intensifying because Taiwan and South Korea fabrication concentration exposes vendors to geopolitical supply disruption risks. Regional logistics operators with consolidated procurement authority demonstrate highest price sensitivity, whereas mining contractors managing autonomous haulage fleets exhibit lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Reverse logistics flows for telematics gateway refurbishment and sensor module remanufacturing are gaining traction among sustainability-focused Dutch and Belgian fleet operators under EU Green Deal carbon accounting mandates. Taiwan, South Korea, and Germany concentrate edge AI chip fabrication, automotive-grade sensor production, and diagnostic software development respectively. Raw material dependencies center on silicon wafers, rare earth elements for magnetic sensors, and REACH-compliant polymer housings. Single-source vulnerability in Taiwan semiconductor fabrication represents the dominant structural risk. Distribution runs through Tier 1 automotive suppliers and direct fleet procurement channels with embedded software licensing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform vendors as mid-size fleet operators reject siloed procurement models and embedded systems engineering scarcity eliminates weaker hardware specialists.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by deepening hardware-software bundling contracts with uptime guarantees for German Ruhr Valley and US Southeast logistics corridors. Prioritize backward integration into ARM Cortex-M microcontroller supply chains to secure allocation priority against fabless competitors. Invest in EU AI Act algorithmic explainability documentation capabilities before Dutch and Belgian conformity assessment deadlines tighten. For New Entrants and Emerging Players: Launch via white-label edge device partnerships with Indian commercial vehicle manufacturers responding to BIS telematics mandates for heavy-duty trucks. Target Maharashtra's emerging fleet operators with software solutions compliant with local data localization requirements. Penetrate through insurance-linked data monetization arrangements with European automotive insurers seeking usage-based coverage risk scores. For Investors and Strategic Acquirers: EU AI Act conformity assessment deadline acceleration is the leading indicator that algorithmic explainability capabilities will command acquisition premiums. Five-to-ten year viability favors vendors with embedded sensor portfolios and cloud-native architecture hybridization. Target acquisition archetypes include edge-AI specialists with TensorFlow Lite compression expertise and federated learning framework deployments. Monitor NHTSA cybersecurity certification timeline announcements for US market entry inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Cloud Hybrid Architecture Development | Enables tiered service models for distributed German and US Midwest fleet networks. |
| EU AI Act Conformity Investment | Mandates algorithmic explainability documentation for Dutch heavy-duty collision-risk classification. |
| India Data Localization Compliance | Captures first-mover positioning under BIS telematics mandates for Maharashtra truck fleets. |
| Insurance Data Monetization Partnership | Generates recurring revenue streams from European usage-based automotive coverage products. |
| Embedded Systems Talent Acquisition | Addresses firmware developer scarcity constraining CAN protocol product development cycles. |
Research Methodology
Multi-period observation of telematics penetration rates, EPA emissions enforcement actions, and EU Green Deal carbon tracking mandate implementation anchored the trend analysis, supplemented by interviews with fleet operations directors, predictive maintenance platform engineers, automotive Tier 1 procurement managers, and commercial vehicle regulatory compliance officers. Secondary validation drew from NHTSA rulemaking dockets, EU AI Act conformity assessment guidance, BIS telematics standard publications, and SEC filings from publicly traded fleet management technology providers. Bottom-up unit economics modeling and top-down market sizing triangulation ensured cross-verification.
Input-output matrices mapped algorithmic technology adoption curves against fleet operator procurement authority consolidation patterns across the projection horizon. Segmentation dimensions modeled include product type integration depth, machine learning versus neural network technology tiers, fleet management versus asset optimization applications, and logistics provider versus mining contractor end-user intensity. CAGRs were derived from regression-based trend extrapolation of historical platform deployment velocities, adjusted for regulatory mandate acceleration effects and semiconductor supply availability constraints.
Semiconductor supply disruption, EU AI Act implementation timeline shifts, and NHTSA cybersecurity certification standard evolution are the dominant revision risks to forecast assumptions. Practitioners should monitor Taiwan foundry utilization rates, European Commission AI Act delegated act publications, and US DOT vehicle data protection rulemaking notices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Europe E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
Car Recycling Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market