
 Non OEM EV MRO Market | 2026-2036
Non OEM EV MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Non OEM EV MRO Market Analytics
Fleet operators are unwinding their historical reliance on captive OEM service networks as EV volumes outstrip dealership capacity. Element Fleet Management leverages its scale to negotiate direct technician training partnerships outside manufacturer channels. Continental sustains a competitive edge through diagnostic tool specialization that addresses battery degradation patterns across multiple OEM platforms. Merchants Fleet anchors its growth strategy on predictive maintenance software that reduces unplanned downtime for commercial clients.
Non OEM EV MRO encompasses independent maintenance, repair, retrofitting, and overhaul services performed on electric vehicle powertrains, energy storage systems, and charging infrastructure by entities unaffiliated with original manufacturers, typically requiring high-voltage certification above 600V and specialized isolation procedures. The primary commercial purpose is preserving vehicle uptime and extending asset life while avoiding OEM service premiums and parts monopolies. Maintenance and battery services dominate current revenue pools, while diagnostic tools and integrated charging solutions represent the fastest-expanding technology segments as software-defined vehicle architectures multiply data-access points. Fleet operators command the largest end-user share, though public transport authorities are emerging as a concentrated margin pool due to their stringent reliability requirements and long-term service contracts.
NHTSA battery safety standards, EPA right-to-repair guidance, and OSHA high-voltage workplace regulations collectively shape technician certification requirements and facility investment thresholds for independent service providers. The EU Green Deal and F-Gas Regulation extend these pressures to European operators through mandated refrigerant handling protocols and circular-economy disposal rules for battery modules. Stakeholders must monitor how evolving software-access legislation affects their ability to perform warranty-compliant updates without OEM authorization.
Market Dynamics
Fleet electrification timelines are compressing maintenance windows as commercial operators demand localized high-voltage service capacity that OEM networks cannot deploy rapidly enough. This supply-demand asymmetry is redrawing competitive boundaries between manufacturer-captive facilities and independent certified providers.
Growth Catalysts
- EPA right-to-repair guidance:Federal pressure on OEMs to release diagnostic software and service documentation is dismantling proprietary lock-in that previously steered fleet maintenance toward dealerships.
- Last-mile delivery electrification:E-commerce logistics operators operating dense urban routes require overnight turnaround maintenance that centralized OEM service centers cannot economically provide.
- Battery thermal runaway protocols:NHTSA mandates for specialized high-voltage handling are creating certified competency barriers that favor established independent networks over opportunistic entrants.
Market Restraints
- Lithium supply concentration:Battery module availability depends on processing capacity concentrated in China, exposing independent repair networks to input cost volatility beyond their hedging capacity.
- OEM software authorization gates:Firmware updates and battery management system recalibrations require manufacturer digital keys that independent technicians cannot independently obtain.
- Facility capex thresholds:OSHA high-voltage workplace regulations mandate isolation equipment and arc-flash containment systems that demand capital deployment exceeding small-operator balance sheet capacity.
Strategic Opportunities
- Midwestern fleet corridors:Interstate trucking routes through Ohio, Indiana, and Illinois present concentrated demand pockets where independent providers can anchor regional high-voltage maintenance hubs.
- Second-life battery retrofitting:Grid storage applications for degraded automotive packs create a downstream revenue stream for independent technicians with cell-level diagnostic capabilities.
- Integrated charging-maintenance bundles:Fleet operators are consolidating vendor relationships, creating openings for service providers who can combine DC fast-charger upkeep with vehicle-level powertrain work.
Industry Challenges
- High-voltage technician certification pipelines:Training programs accredited to OSHA and manufacturer standards cannot graduate sufficient certified technicians to match fleet growth trajectories.
- Warranty compliance documentation:Independent repairs must satisfy OEM record-keeping requirements to preserve vehicle coverage, creating administrative friction that slows service velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non OEM EV MRO Market |
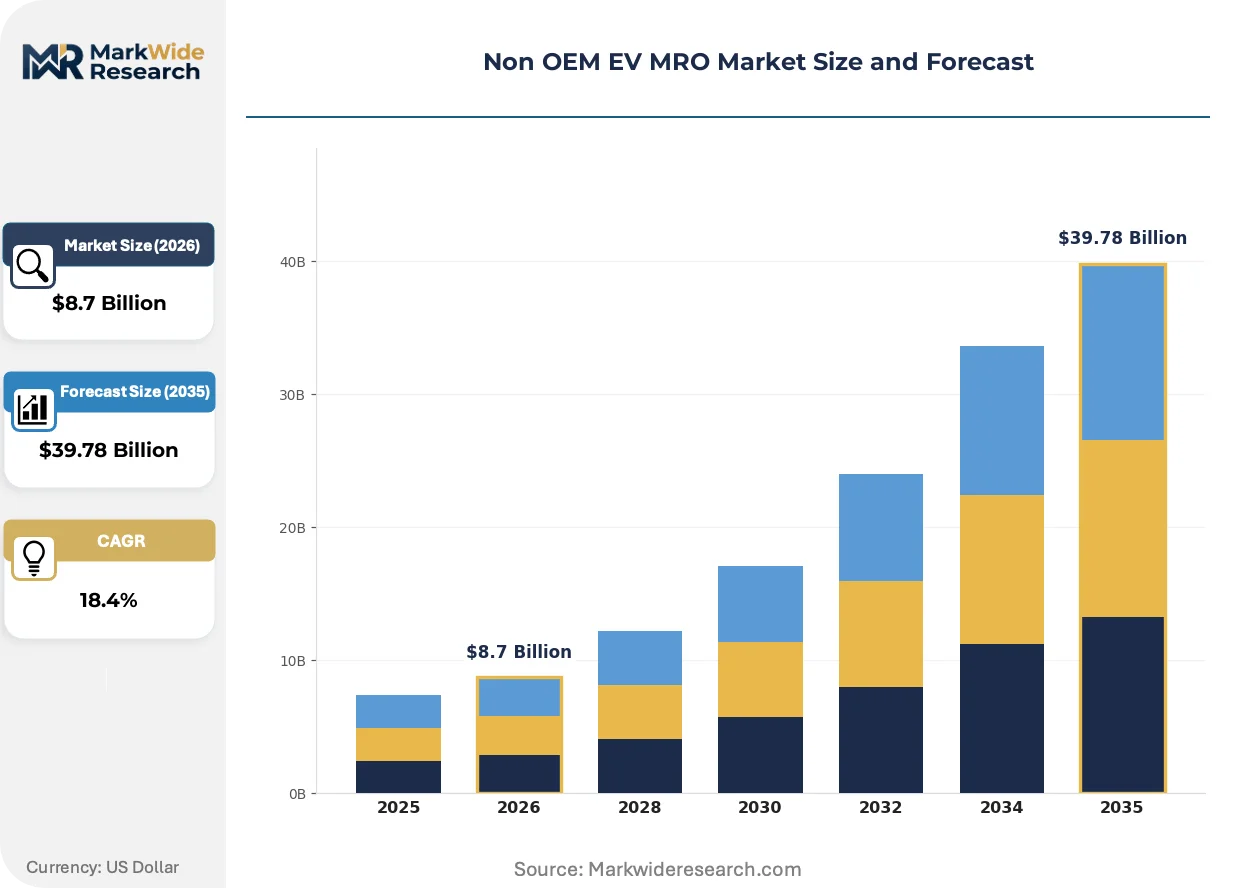
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Retrofitting, Overhaul End User: Fleet Operators, Individual Owners, Commercial Entities, Public Transport Component: Batteries, Motors, Electronic Control Units, Charging Systems Technology: Battery Management Systems, Diagnostic Tools, Software Updates, Integrated Charging Solutions |
| Companies Covered | Element Fleet Management, Lion Electric, Volvo, Geotab, Scania, Daimler, Merchants Fleet, Continental, MAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non OEM EV MRO Market Evolving Landscape
Diagnostic access models are restructuring competitive advantage in EV maintenance as software-defined architectures multiply data touchpoints beyond traditional mechanical repair. Three developments are compressing the window for competitive differentiation.
Cloud-based battery health monitoring is fragmenting the diagnostic services market by enabling independent providers to access degradation analytics previously captive to OEM servers. Fleet operators in California and Texas are adopting these platforms fastest, compressing the information asymmetry that once favored manufacturer service networks. The technology is fragmenting revenue pools away from bundled dealership contracts toward discrete software subscriptions and per-vehicle analytics fees.
EU F-Gas Regulation mandates for refrigerant handling in thermal management systems are extending compliance burdens to North American operators serving European-manufactured vehicles. Independent facilities must now invest in recovery equipment and technician certification for fluorinated gas containment. The regulation is most affecting service providers in border states handling cross-border commercial fleets.
Commercial buyers are unbundling maintenance from vehicle procurement, separating service contracts from initial acquisition decisions. Fleet management companies are consolidating vendor relationships through multi-year performance agreements that penalize downtime rather than rewarding parts volume. This shift is most visible among logistics operators in the Midwest and Southeast who operate mixed-brand fleets requiring platform-agnostic service capability.
Non OEM EV MRO Market Segmentation
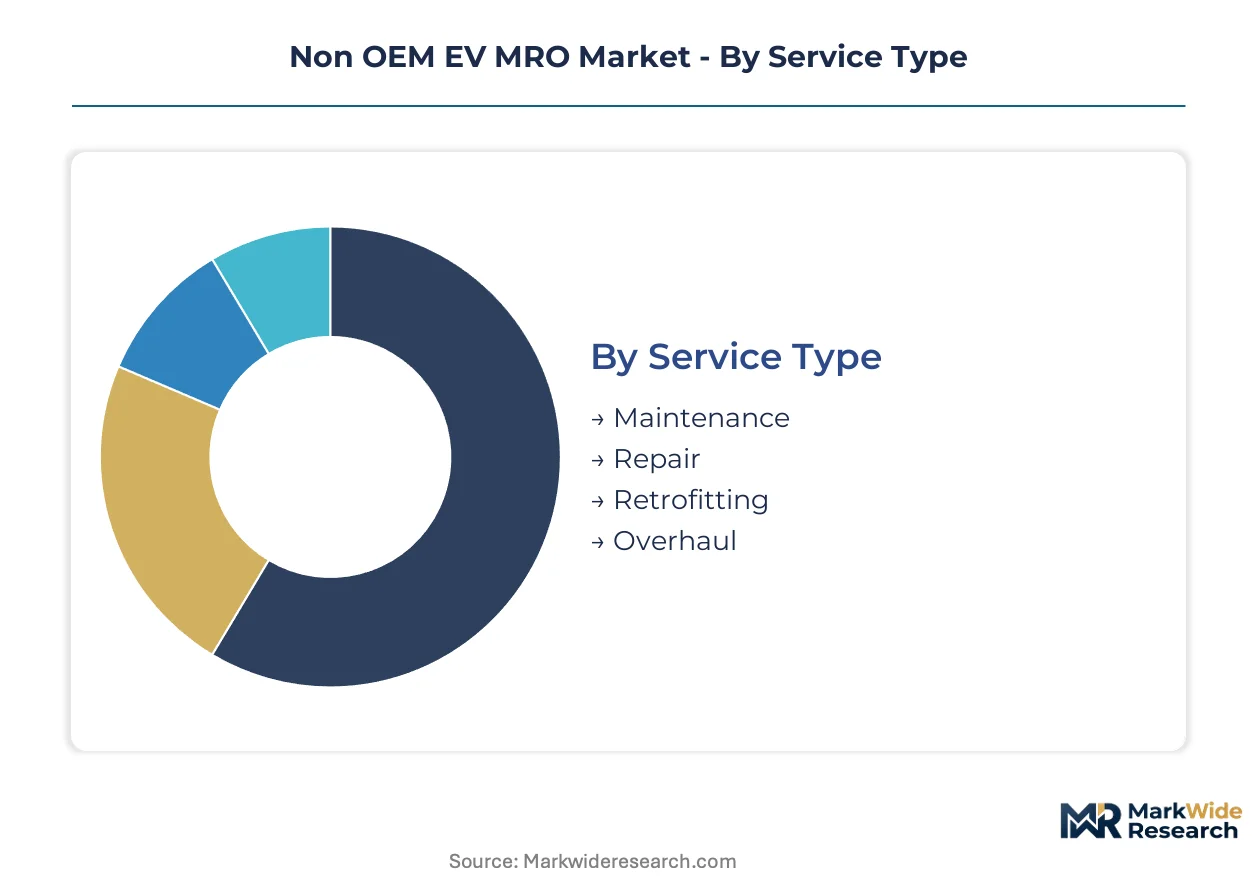
Segmentation in Non OEM EV MRO reveals where independent providers can capture value outside manufacturer-captive networks. Service mix and component specialization determine which operators build sustainable margin pools versus competing on commodity labor rates.
Service Type:
Margin pools concentrate in services requiring certified high-voltage competency and specialized equipment that creates barriers to opportunistic competition.
- Maintenance:Scheduled preventive work on thermal management systems, brake regen units, and high-voltage interlock loops. Fleet operators in California and Texas are consolidating maintenance spend under multi-year contracts with independent networks that guarantee sub-4-hour response times along interstate corridors.
- Repair:Corrective interventions following fault codes or physical damage, encompassing cell replacement, inverter rebuilds, and charging port restoration. Individual owners in suburban markets are driving demand for collision-integrated EV repair as insurer preferred-shop networks expand beyond OEM dealerships.
- Retrofitting:Hardware and software modifications to extend vehicle capability or adapt to new charging standards. Commercial entities operating legacy delivery vans are retrofitting CCS compatibility to avoid premature fleet replacement.
- Overhaul:Comprehensive powertrain rebuilds and battery pack remanufacturing for extended service life. Public transport authorities in the Midwest are anchoring overhaul demand through 12-year bus lifecycle mandates.
Maintenance holds installed capacity. Repair is rotating up the share rankings.
End User:
Customer type dictates contract structure, with fleet-scale buyers extracting performance guarantees unavailable to fragmented retail demand.
- Fleet Operators:Logistics and last-mile delivery companies operating 50+ vehicles under unified maintenance agreements. These buyers are unbundling service from procurement, separating repair contracts from vehicle acquisition decisions and penalizing downtime rather than rewarding parts volume.
- Commercial Entities:Corporate and utility vehicle pools with mixed-brand composition requiring platform-agnostic diagnostic capability. Facility managers in Ohio and Indiana are consolidating vendor relationships through integrated charging-maintenance bundles that combine DC fast-charger upkeep with powertrain work.
- Public Transport:Municipal bus authorities and regional transit agencies with stringent reliability requirements and 10-15 year asset horizons. These contracts carry concentrated margin pools due to penalty structures for service interruptions during peak ridership periods.
- Individual Owners:Retail consumers seeking alternatives to dealership labor rates and parts markups. This segment remains price-sensitive and geographically dispersed, limiting independent provider investment in dedicated capacity.
Fleet Operators anchor contract value. Commercial Entities are climbing the fastest as procurement centralizes.
Component:
Technical complexity and safety certification requirements determine which component categories support premium pricing versus commodity competition.
- Batteries:Energy storage system maintenance encompassing thermal management, cell balancing, and state-of-health recalibration. NHTSA thermal runaway protocols are creating certified competency barriers that favor established independent networks over opportunistic entrants in high-voltage markets.
- Motors:Permanent magnet and induction motor diagnostics, bearing replacement, and inverter integration. These repairs concentrate in Midwestern trucking corridors where independent providers anchor regional maintenance hubs along interstate routes.
- Electronic Control Units:Powertrain control module programming and sensor calibration requiring manufacturer software authorization. EPA right-to-repair guidance is dismantling proprietary lock-in that previously steered this work toward dealerships.
- Charging Systems:Onboard charger diagnostics, port replacement, and DC fast-charger infrastructure maintenance. Fleet operators are consolidating vendor relationships, creating openings for providers who combine vehicle-level powertrain work with charging hardware upkeep.
Batteries command premium pricing. Charging Systems are gaining share fastest as infrastructure scales.
Technology:
Software-defined architectures are fragmenting revenue pools away from bundled mechanical services toward discrete diagnostic and data subscriptions.
- Diagnostic Tools:Multi-platform scan equipment and cloud-based degradation analytics accessing previously OEM-captive battery health data. Fleet operators in California and Texas are adopting these platforms fastest, compressing information asymmetry that once favored manufacturer service networks.
- Battery Management Systems:Firmware updates, cell balancing algorithms, and thermal control logic requiring high-voltage isolation procedures. These services demand OSHA-compliant facility investments that exceed small-operator balance sheet capacity.
- Software Updates:Over-the-air compatibility patches and feature activation requiring manufacturer digital keys. Independent technicians face authorization gates that limit warranty-compliant performance without OEM cooperation.
- Integrated Charging Solutions:Coordinated vehicle-charger diagnostics and predictive maintenance software reducing unplanned downtime. Commercial buyers are separating service contracts from acquisition decisions, creating demand for platform-agnostic capability across mixed-brand fleets.
Diagnostic Tools hold technology leadership. Integrated Charging Solutions show the steepest expansion trajectory as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German independent EV service networks export diagnostic expertise to Central European fleet operators managing mixed-brand commercial vehicles across the Rhine corridor.
United States
California's dense last-mile delivery corridors and Texas interstate trucking routes concentrate demand for localized high-voltage maintenance capacity. NHTSA battery thermal runaway protocols mandate OSHA-compliant facility investments that favor established independent networks over small entrants. Midwestern fleet hubs in Ohio and Illinois anchor regional service infrastructure as commercial buyers consolidate vendor relationships.
Germany
Industrial vehicle pools and municipal bus authorities drive demand for platform-agnostic powertrain overhaul services. EU F-Gas Regulation mandates refrigerant handling certification for thermal management repairs, extending compliance burdens to facilities serving European-manufactured vehicles. Bavarian and Baden-Württemberg service clusters specialize in battery remanufacturing for extended commercial asset lifecycles.
China
Domestic battery processing capacity and dense urban logistics networks create integrated maintenance ecosystems independent of manufacturer channels. MIIT vehicle safety standards and dual carbon goals accelerate technician certification requirements for high-voltage workplace procedures. Yangtze River Delta service hubs cluster around Shanghai's commercial fleet density and cell manufacturing supply chains.
United Kingdom
Corporate fleet electrification timelines and public transport decarbonization contracts concentrate demand for certified repair capacity outside OEM dealerships. CSRD sustainability disclosure rules and REACH chemical handling protocols shape facility investment thresholds for independent providers. London and Southeast England service networks prioritize overnight turnaround maintenance for urban delivery operators.
India
State transport utility electrification programs and e-commerce logistics expansion drive demand for cost-competitive EV servicing outside premium manufacturer networks. BIS safety standards and PLI scheme incentives for domestic battery manufacturing reshape technician training requirements. Maharashtra and Karnataka commercial corridors anchor independent service infrastructure near fleet operator concentration zones.
Non OEM EV MRO Market Competitive Landscape
Listed fleet management conglomerates compete with private diagnostic specialists across certification depth and geographic coverage density. The market structure fragments across three capability tiers: scale-driven fleet service integrators, component-specialist technology providers, and regional high-voltage maintenance operators. Dominant competitive moves include direct technician training partnerships outside manufacturer channels and predictive maintenance software integration that reduces client downtime exposure.
Among fleet-scale service integrators, Element Fleet Management and Merchants Fleet exemplify the procurement-unbundling archetype as commercial buyers separate maintenance contracts from vehicle acquisition decisions. Continental represents the diagnostic technology specialist tier, occupying a position defined by multi-platform battery degradation analytics. These three entities anchor competitive positioning across the contract value chain without manufacturer affiliation.
| Leading Market Players |
|---|
| Element Fleet Management |
| Lion Electric |
| Volvo |
| Geotab |
| Scania |
| Daimler |
| Merchants Fleet |
| Continental |
| MAN |
| Others |
Value Network & Pricing Analysis
NHTSA high-voltage certification mandates gate both facility qualification and price differentiation simultaneously, forcing independent providers to recover OSHA-compliant equipment costs through tiered service rates while fleet operators consolidate spend under performance-guaranteed contracts that penalize downtime.
Pricing Analysis
Current-gen diagnostic platforms command premium subscription rates against prior-gen scan tools and next-gen cloud-analytics suites. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with OSHA-certified high-voltage work extracting margins unavailable to general mechanical shops. Cost compression in the standard tier is intensifying because diagnostic tool vendors are democratizing battery health analytics previously captive to OEM servers. Fleet operators show lowest price sensitivity due to unplanned downtime penalties, while individual owners drive commoditization in retail repair segments.
Supply Chain Analysis
Strategic stockpiling of battery modules and thermal management components dominates over just-in-time preferences as lithium processing concentration in China, South Korea, and Japan creates supply vulnerability. Independent networks draw from cell manufacturers, inverter suppliers, and refrigerant recovery equipment vendors. Single-source vulnerability runs through Chinese lithium hydroxide refining capacity. Distribution runs through regional high-voltage hubs that combine parts warehousing with certified technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification timelines are compressing maintenance windows, with EPA right-to-repair guidance dismantling proprietary software lock-in that previously steered commercial spend toward manufacturer-captive networks.
For Market Incumbents: Compound certification depth through direct technician training partnerships outside OEM channels, anchoring regional high-voltage hubs along interstate trucking corridors in Ohio and Indiana. Capacity addition in Midwestern fleet corridors defends against emerging platform-agnostic diagnostic specialists. Channel control over predictive maintenance software subscriptions preserves recurring revenue as hardware margins compress. For New Entrants and Emerging Players: Lead with integrated charging-maintenance bundles targeting commercial entities in suburban facility management markets where procurement centralization is climbing fastest. White-space concentrates in second-life battery retrofitting for grid storage applications and DC fast-charger upkeep contracts. Go-to-market through multi-year performance agreements that penalize downtime rather than reward parts volume. For Investors and Strategic Acquirers: EPA right-to-repair guidance reshapes the acquisition landscape by validating independent diagnostic platforms that access previously OEM-captive battery health data. Long-term viability centers on platform-agnostic capability across mixed-brand fleets with software-defined architectures multiplying data touchpoints. Target acquisition archetype: regional high-voltage maintenance operators with OSHA-compliant facilities and established fleet relationships. Signal to watch: NHTSA thermal runaway protocol enforcement intensity crossing thresholds that accelerate certified technician scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | OSHA-compliant training programs address certified high-voltage competency gaps that outstrip fleet growth trajectories. |
| Multi-Platform Diagnostic Tool Development | Cloud-based battery health monitoring fragments revenue pools away from bundled dealership service contracts. |
| Integrated Charging-Maintenance Bundles | Fleet operators in California and Texas consolidate vendor relationships through combined DC fast-charger and powertrain service agreements. |
| Second-Life Battery Retrofitting Capability | Grid storage applications for degraded automotive packs create downstream revenue streams requiring cell-level diagnostic expertise. |
| Predictive Maintenance Software Integration | Merchants Fleet and Element Fleet Management reduce client downtime exposure through algorithmic unplanned outage prevention. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, independent service facility owners, high-voltage technician training program administrators, and OEM aftermarket strategy leads; and secondary validation against EPA right-to-repair guidance documents, NHTSA battery safety standard filings, OSHA high-voltage workplace regulations, and fleet management company procurement disclosures. Bottom-up triangulation across service type revenue pools and top-down cross-check against fleet electrification timelines anchored volume and value estimates.
Across the analysis window, the analytical framework modeled segmentation dimensions including service type, end-user category, component specialization, and technology deployment pattern. CAGRs were derived from fleet growth trajectories, certified technician supply constraints, and regulatory compliance cost curves. Forecast inputs incorporated battery thermal runaway protocol enforcement intensity and cloud-based diagnostic platform adoption rates among California and Texas fleet operators.
The analysis sits within stated boundaries; outcomes outside sustained EPA right-to-repair enforcement, stable lithium supply from Chinese processing capacity, and OSHA high-voltage workplace regulation continuity would require recalibration. Revision becomes warranted when OEM software authorization gate restrictions intensify beyond current EPA guidance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Fuel Additives Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
North America Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market