
 Mobile Car Wash and Detailing Market | 2026-2036
Mobile Car Wash and Detailing Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Car Wash and Detailing Market Foresight
Aftermarket service revenue is rewriting profit distribution between fixed-site car washes and mobile operators. Spiffy leverages proprietary scheduling technology to anchor recurring fleet contracts across southeastern US markets. Washos competes through specialized waterless cleaning formulations that comply with drought-restricted municipalities. DetailXPerts differentiates via steam-based sanitization protocols that address commercial vehicle hygiene standards.
Mobile car wash and detailing encompasses on-location vehicle cleaning, restoration, and protection services performed at customer-designated sites using self-contained water, power, and chemical systems, typically operating from van-mounted or trailer-based rigs with pressure ratings between 1,500 and 4,000 PSI and water recovery capacities of 50–200 gallons. These services eliminate transit time for vehicle owners while reducing fixed real estate overhead for service providers. Exterior Wash commands the largest transaction volume due to lower per-service pricing and faster turnaround, while Interior Detailing captures premium margin pools from fleet operators requiring sanitization documentation. Subscription-Based delivery models are expanding fastest among urban individual owners seeking predictable maintenance schedules.
EPA stormwater discharge rules under the Clean Water Act constrain chemical runoff protocols for mobile operators, while OSHA workplace safety standards govern pressure equipment operation and chemical handling procedures. California's State Water Resources Control Board enforces specific water reclamation percentages that directly determine equipment investment thresholds for market entry. Stakeholders must monitor evolving municipal permitting frameworks that increasingly differentiate mobile operators from stationary facilities on zoning and wastewater grounds.
Market Dynamics
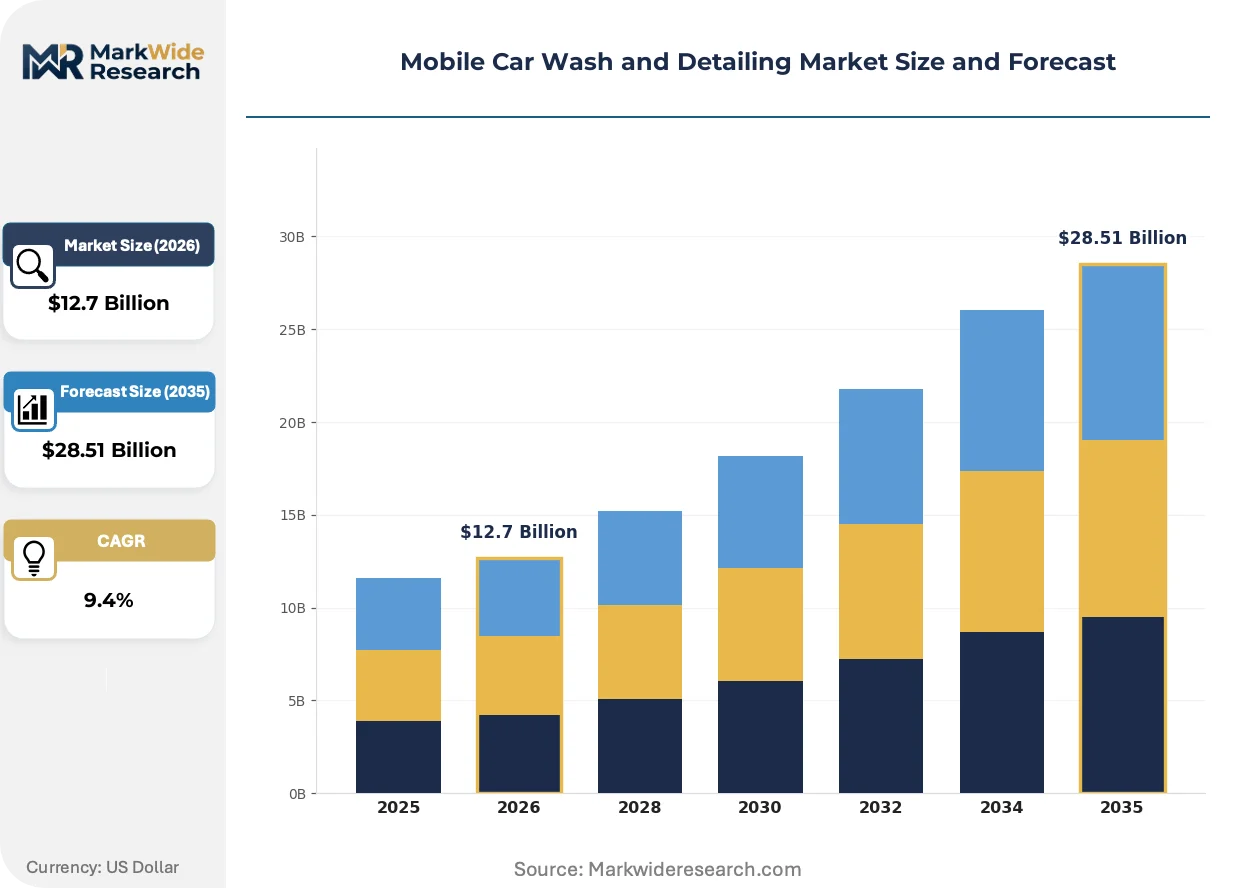
Water reclamation mandates from California's State Water Resources Control Board are compressing equipment investment thresholds for new entrants while favoring operators with captive recycling systems. Fleet procurement teams now require documented sanitization protocols as a condition of contract renewal.
Growth Catalysts
- EPA Stormwater Regulations:The Clean Water Act's discharge rules are forcing fixed-site operators to absorb compliance costs that mobile units bypass, redirecting fleet procurement toward van-based providers.
- Subscription Scheduling Platforms:Proprietary routing algorithms enable predictable recurring revenue from urban individual owners who prioritize convenience over price.
- Texas and Florida Vehicle Density:Metropolitan corridors in these states concentrate high-value exterior wash demand due to climate-driven frequent service cycles and limited seasonal downtime.
Market Restraints
- Water Recovery Equipment Costs:Van-mounted reclamation systems with 50–200 gallon capacities require upfront capital that excludes small independent operators from municipal contract bidding.
- Input Cost Volatility:Biodegradable surfactant formulations face price pressure from petrochemical feedstock fluctuations, compressing margin on waterless cleaning services.
- Zoning Permitting Fragmentation:Municipal frameworks increasingly differentiate mobile operators from stationary facilities on wastewater grounds, creating compliance patchwork across jurisdictions.
Strategic Opportunities
- Commercial Vehicle Sanitization:Steam-based protocols that generate hygiene documentation are penetrating food transport and medical logistics fleets with strict cargo-contamination protocols.
- California Water Reclamation Mandates:The state's percentage-based recovery requirements create competitive moat for operators with certified closed-loop systems.
- IoT-Enabled Fleet Monitoring:Integration of pressure sensor telemetry with customer dashboards enables usage-based billing models for enterprise accounts.
Industry Challenges
- Pressure Equipment Certification:OSHA compliance for 1,500–4,000 PSI systems requires specialized training programs that extend technician onboarding timelines.
- Chemical Handling Protocols:Workplace safety standards for concentrated detergent storage create liability exposure during multi-stop daily routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Car Wash and Detailing Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exterior Wash, Interior Detailing, Full-Service Wash, Waxing Vehicle Type: Sedans, SUVs, Trucks, Vans Delivery Model: On-Demand, Subscription-Based, One-Time Service, Seasonal Packages Customer Type: Individual Owners, Fleet Operators, Businesses, Car Dealerships |
| Companies Covered | Spiffy, Washos, MobileWash, DetailXPerts, Get Spiffy, Inc., NuWash, Washé, Wype, AutoSpa360, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Car Wash and Detailing Market Shifts & Advancements
Service delivery models are bifurcating between technology-enabled subscription platforms and specialized compliance-focused operators serving regulated fleet segments. Equipment manufacturers are embedding telemetry to validate water recovery claims for municipal auditors.
Steam-based sanitization systems operating at temperatures exceeding 300°F are penetrating commercial vehicle hygiene contracts. Food transport fleets and medical logistics operators are adopting these protocols fastest to satisfy cargo-contamination documentation requirements. High-temperature vapor delivery without chemical residue is rendering obsolete traditional interior shampoo methods that require drying time and ventilation.
California's State Water Resources Control Board enforces specific reclamation percentages that determine equipment investment thresholds for market entry. Operators must demonstrate closed-loop water recovery to obtain mobile washing permits in drought-restricted municipalities. The regulatory burden falls heaviest on independent contractors lacking capital for certified reclamation rigs, consolidating contract awards toward scaled fleet operators.
Fleet procurement teams are unbundling exterior wash from interior detailing to optimize cost allocation across vehicle classes. Enterprise accounts now source exterior services through scheduled mobile programs while retaining specialized providers for sanitization documentation. This pattern concentrates most visibly in Texas metropolitan corridors where fleet density supports dedicated vendor relationships.
Mobile Car Wash and Detailing Market Segmentation
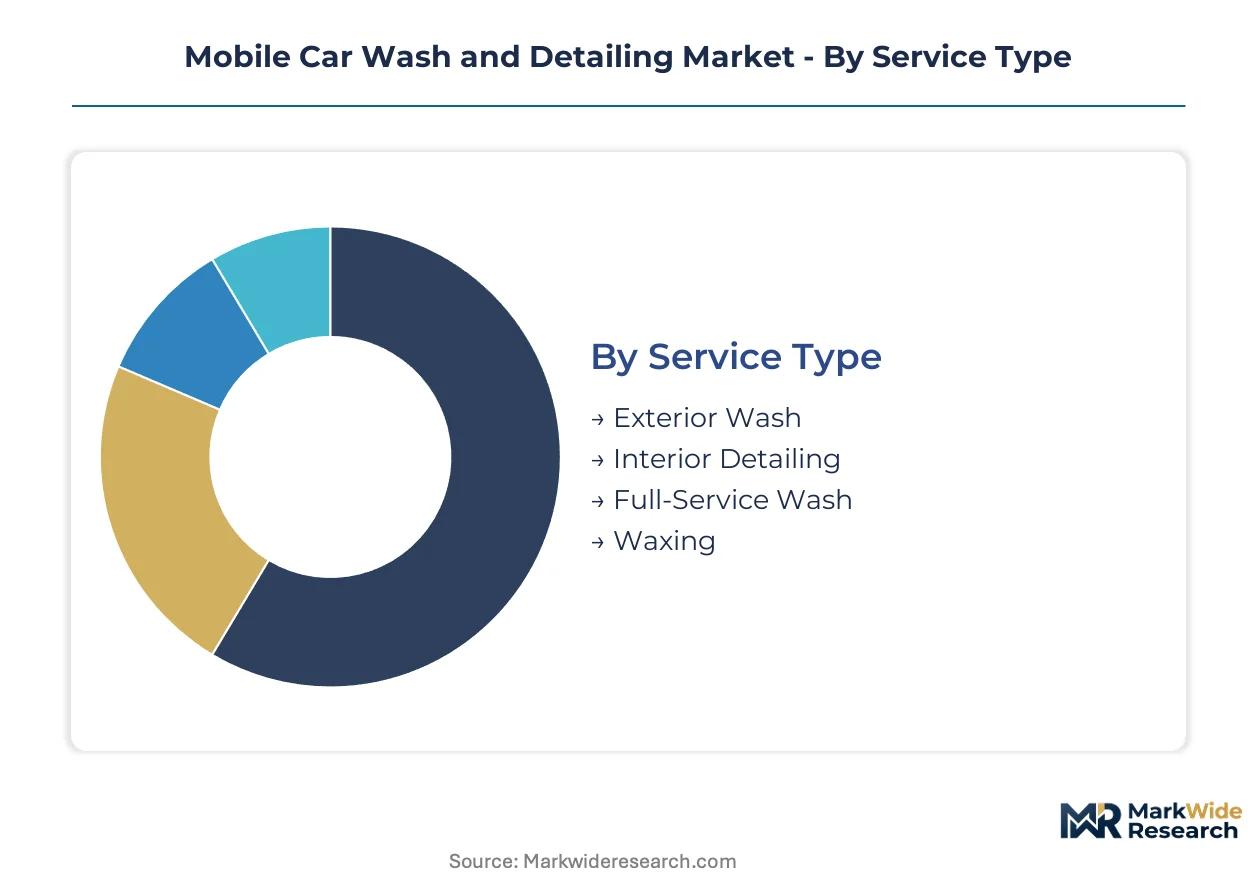
Service differentiation in mobile car wash and detailing hinges on water recovery capacity, pressure specifications, and sanitization documentation requirements. Fleet procurement teams unbundle service categories to optimize cost allocation across vehicle classes and compliance tiers.
Service Type:
Van-mounted rigs with 1,500–4,000 PSI pressure ratings serve distinct use cases ranging from rapid exterior maintenance to intensive restoration protocols.
- Exterior Wash:High-volume transactions leverage 50–200 gallon water recovery systems for rapid turnaround at lower per-service pricing. Demand concentrates in Texas and Florida metropolitan corridors where climate conditions drive frequent service cycles and minimal seasonal downtime constraints.
- Interior Detailing:Premium-margin services incorporate steam-based sanitization exceeding 300°F to satisfy commercial vehicle hygiene documentation. Fleet operators in food transport and medical logistics mandate these protocols as contract renewal conditions.
- Full-Service Wash:Bundled exterior-interior packages target individual owners seeking comprehensive vehicle maintenance without multiple provider coordination.
- Waxing:Protective coating applications command seasonal demand spikes tied to regional weather patterns and UV exposure concerns.
Established volume favors Exterior Wash; emerging adoption favors Interior Detailing.
Vehicle Type:
Chassis dimensions and surface area dictate equipment configuration and chemical formulation requirements across mobile operator fleets.
- Sedans:Compact footprint enables fastest service completion rates and highest daily route density for van-based operators.
- SUVs:Expanded surface area and wheel well geometry require specialized brush attachments and extended water recovery cycles.
- Trucks:Commercial fleet contracts concentrate here due to cargo-contamination documentation requirements and enterprise procurement scale.
- Vans:Food transport and medical logistics operators prioritize these vehicles for steam-based sanitization protocols with hygiene certification.
Route efficiency peaks with Sedans; contract value concentrates with Trucks.
Delivery Model:
Scheduling architecture separates transactional convenience from predictable revenue streams in operator business models.
- On-Demand:Immediate response positioning captures urban individual owners prioritizing convenience over price optimization.
- Subscription-Based:Proprietary routing algorithms anchor recurring revenue through predictable maintenance schedules. This segment is expanding most quickly among metropolitan individual owners seeking cost certainty.
- One-Time Service:Event-driven demand surrounding vehicle resale preparation or seasonal deep cleaning requirements.
- Seasonal Packages:Prepaid multi-service bundles address climate-specific protection needs in high-UV or winter-corrosion regions.
Revenue stability favors Subscription-Based; margin per transaction favors One-Time Service.
Customer Type:
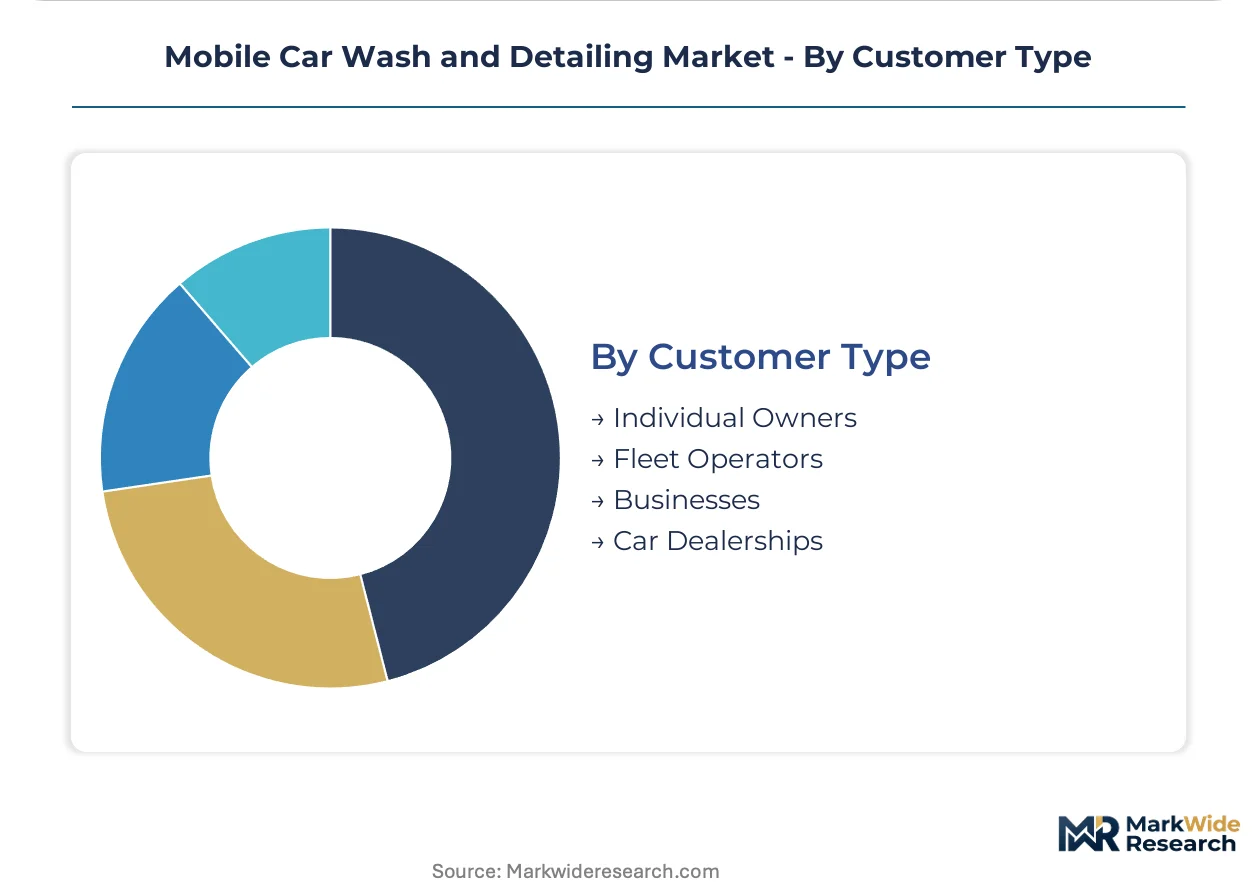
Procurement sophistication varies from individual convenience-seeking to enterprise compliance documentation requirements.
- Individual Owners:Urban density corridors in Texas and Florida drive subscription adoption through technology-enabled scheduling platforms.
- Fleet Operators:Enterprise accounts unbundle exterior and interior services across vehicle classes to optimize vendor allocation. Sanitization documentation requirements now condition contract renewals.
- Businesses:Corporate vehicle pools balance cost control with employee convenience through scheduled mobile programs.
- Car Dealerships:Volume prep services for inventory presentation require rapid turnaround and consistent finish quality.
Contract scale favors Fleet Operators; margin expansion favors Businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Individual owners in sun-belt metropolitan corridors accept premium convenience pricing, while fleet procurement teams in northern climates drive hard volume discounts during seasonal downtime.
United States
Texas and Florida metropolitan corridors concentrate exterior wash demand due to climate-driven frequent service cycles. EPA stormwater discharge rules under the Clean Water Act constrain chemical runoff protocols, redirecting fleet procurement toward van-based providers with compliant recovery systems. Dallas-Fort Worth and Miami-Dade host the densest operator networks competing for subscription-based individual owner accounts.
Canada
Seasonal compression limits exterior wash demand to six-month peak windows, pushing operators toward interior detailing and protective coating specialization. Environment Canada's wastewater effluent guidelines govern mobile operator permitting, particularly in Great Lakes basin municipalities. Toronto and Vancouver metropolitan areas sustain year-round subscription models through underground parking facility partnerships.
Germany
Commercial fleet sanitization documentation requirements are expanding fastest among food transport and medical logistics operators. REACH chemical regulations and strict wastewater discharge standards from federal environmental agencies elevate equipment investment thresholds. The Rhine-Ruhr industrial corridor concentrates demand from logistics fleets requiring hygiene certification for cross-border EU operations.
United Kingdom
London's congestion charging zone and ultra-low emission standards favor van-based operators over customer vehicle movement to fixed sites. Environment Agency discharge permits regulate mobile washing in water-stressed southeastern catchments. The M25 orbital corridor hosts specialized operators serving corporate vehicle pools with scheduled maintenance programs.
Australia
Water scarcity in southeastern states drives adoption of waterless and steam-based cleaning formulations. State-level environmental protection agencies enforce varying reclamation standards, fragmenting compliance requirements across New South Wales, Victoria, and Queensland. Sydney and Melbourne metropolitan areas concentrate subscription adoption among time-constrained professional households.
Mobile Car Wash and Detailing Market Competitive Landscape
Capability concentration sits with specialized compliance-focused operators; scale advantage sits with technology-enabled subscription platforms. The market structures around three tiers: fleet-contract specialists with certified reclamation systems, urban convenience platforms with proprietary routing algorithms, and independent contractors serving price-sensitive transactional demand. Dominant competitive moves include geographic expansion through metro-cluster replication and backward integration into equipment manufacturing to control reclamation system costs.
Within the technology-enabled platform tier, Spiffy and Washos exemplify divergent specialization vectors. Spiffy anchors recurring fleet contracts through southeastern US market density. Washos occupies a position defined by waterless formulation compliance in drought-restricted municipalities. DetailXPerts represents the sanitization-documentation specialist archetype, serving commercial vehicle hygiene requirements.
| Leading Market Players |
|---|
| Spiffy |
| Washos |
| MobileWash |
| DetailXPerts |
| Get Spiffy, Inc. |
| NuWash |
| Washé |
| Wype |
| AutoSpa360 |
| Others |
Supply & Pricing Matrix
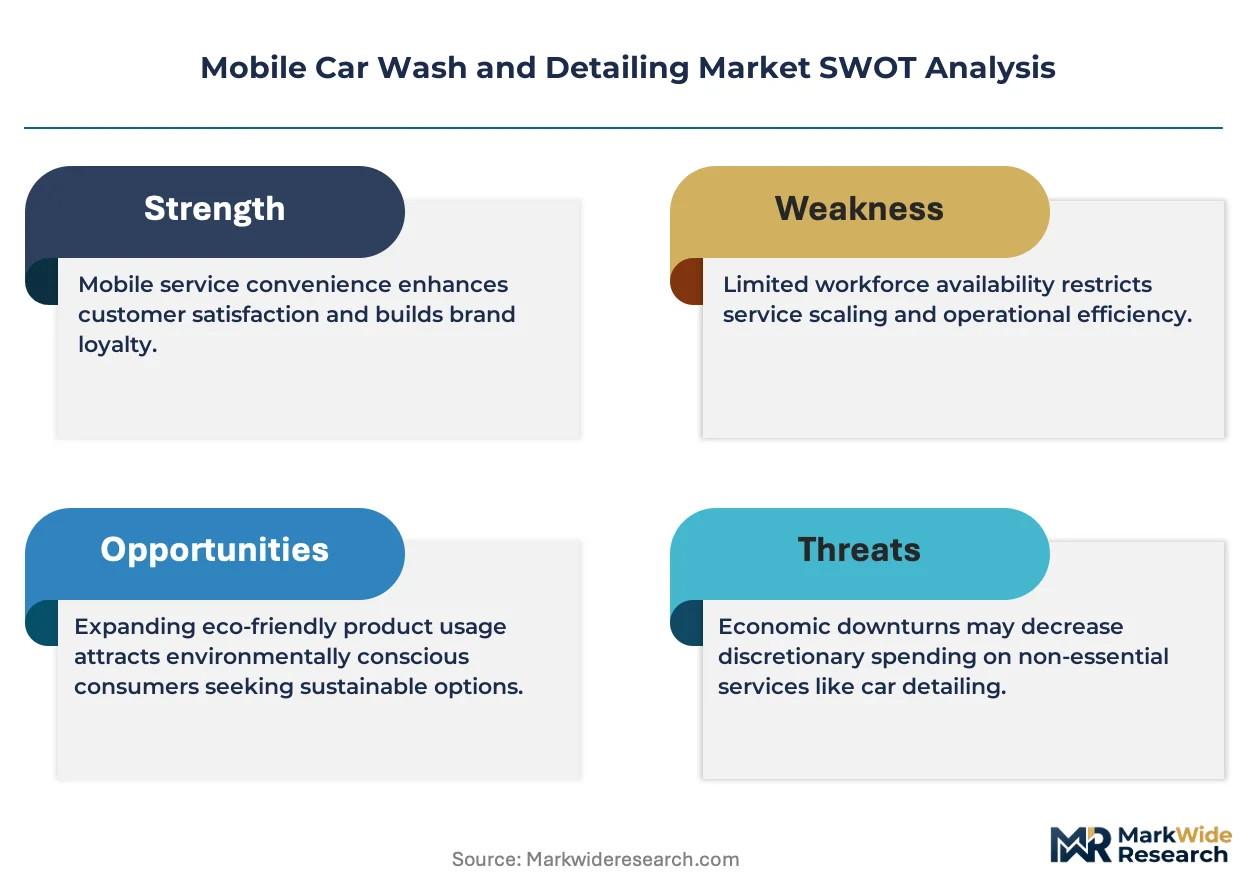
Chinese pressure-washer component manufacturing concentrates upstream supply for van-mounted reclamation systems, anchoring margin pools with operators who backward integrate into equipment assembly rather than sourcing turnkey rigs. California's water reclamation mandates compound this dynamic by forcing certified system investments that only scaled fleet operators can amortize across high-volume recurring contracts.
Pricing Analysis
After-sales service revenue from subscription maintenance programs drives lifetime value differentiation between technology-enabled platforms and transactional operators. Three-tier pricing structure across premium steam-sanitization, standard exterior-interior bundles, and economy rapid-wash levels reflects certification grade and documentation capability. Cost compression in biodegradable surfactant formulations is intensifying because petrochemical feedstock volatility squeezes waterless service margins. Individual owners in Texas and Florida metropolitan corridors show lowest price sensitivity, while northern fleet procurement teams drive hardest volume discounts during seasonal downtime.
Supply Chain Analysis
Export-control scrutiny on high-pressure pump technology from Germany and Italy constrains component flows to North American equipment assemblers. Manufacturing concentrates in China for pressure systems, Germany for precision pumps, and Mexico for van upfitting services. Raw material dependencies span aluminum alloys for tank fabrication, specialized membranes for water filtration, and biodegradable surfactant bases. Single-source vulnerability runs through German high-pressure pump suppliers with limited qualified alternatives. Distribution runs through regional equipment distributors serving metropolitan operator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile car wash and detailing represents a high-growth disruption as EPA stormwater regulations under the Clean Water Act redirect fleet procurement toward compliant van-based providers and away from fixed-site competitors.
For Market Incumbents: Harden subscription platform moats through proprietary routing algorithm refinement that locks in recurring urban individual owner revenue. Deepen backward integration into reclamation system manufacturing to control equipment costs against Chinese component price volatility. Defensive consolidation of southeastern US market density protects against Washos-style waterless formulation specialists encroaching on drought-restricted municipalities.
For New Entrants and Emerging Players: Canadian metropolitan corridors outside Toronto and Vancouver present geographic underpenetration for year-round subscription models through underground parking facility partnerships. Food transport and medical logistics fleet segments offer the most penetrable white-space for steam-based sanitization documentation services. A go-to-market angle targeting California municipal contract bidding with certified closed-loop recovery systems bypasses incumbent scale advantages.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled subscription platforms with demonstrated recurring revenue density and proprietary scheduling infrastructure rather than independent contractor networks. Long-term viability favors operators with regulatory certification moats spanning multiple jurisdictions. The signal to watch is fleet procurement team unbundling patterns separating exterior wash from interior detailing contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Equipment Manufacturing | Captive supply of reclamation systems insulates margin from Chinese component price swings. |
| Proprietary Scheduling Platform Development | Routing algorithm density anchors recurring revenue from urban individual owner segments. |
| Steam-Based Sanitization Certification | Food transport and medical logistics fleets mandate hygiene documentation for contract renewal. |
| California Water Reclamation Compliance | Closed-loop system certification creates municipal contract bidding eligibility in drought-restricted markets. |
| Geographic Expansion through Metro-Cluster Replication | Texas and Florida corridor density models transfer to southeastern US metropolitan markets. |
Research Methodology
A spread of perspectives from fleet procurement managers, mobile operator owners, equipment manufacturing engineers, and municipal permitting officers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from EPA discharge filings, California State Water Resources Control Board permits, SEC 10-K equipment manufacturer disclosures, and trade customs data for pressure-washer component imports. Bottom-up route-density modeling and top-down metropolitan serviceable market estimation provided triangulation across the analysis window.
Demand-supply-balance framing anchored the forecast framework across service type, vehicle class, delivery model, and customer type segmentation dimensions. CAGRs derived from historical adoption curve analysis and regulatory inflection timing. Fleet contract renewal rates, individual owner subscription churn patterns, and equipment replacement cycles for reclamation systems served as industry-specific forecast inputs throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by technology-enabled platforms or sudden tariff imposition on Chinese pressure-system components would shift outcomes. Material shifts in EPA stormwater enforcement intensity or California reclamation percentage requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
United Kingdom Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Silicone in Car Care Products Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market