
 US Maintenance Repair and Operations (MRO) Market | 2026-2036
US Maintenance Repair and Operations (MRO) Market Size, Share, and Industry Trends Forecast 2026-2036
US Maintenance Repair and Operations (MRO) Market Insights
Composite materials are shifting maintenance economics across aviation MRO as carbon fiber repairs displace traditional aluminum rework. StandardAero sustains vertical integration across engine overhaul lines, while AAR Corporation anchors its position through component repair specialization. GE Aerospace leverages technology leadership in predictive maintenance analytics, and Delta TechOps dominates narrow-body fleet support through captive airline volume.
Maintenance Repair and Operations encompasses the procurement and execution of activities required to keep facilities, equipment, and production lines functional, spanning spare parts replacement, calibration, and facility upkeep with tolerances often measured in thousandths of an inch for rotating machinery. The primary purpose centers on minimizing unplanned downtime and extending capital asset lifecycles across industrial and commercial installations. Aviation end users command premium service margins due to FAA-certification requirements and airworthiness traceability, while online retailers in distribution channels capture fastest-growing share as procurement teams shift from catalog-based ordering to digital platforms with real-time inventory visibility.
OSHA mandates govern worker safety equipment specifications, FAA airworthiness directives dictate aviation MRO documentation and parts traceability, and EPA hazardous waste rules shape chemical handling and disposal protocols across industrial facilities. These frameworks elevate compliance costs but create barriers that favor established providers with certified quality systems. Stakeholders must monitor how predictive analytics integration reshapes inventory management service models and whether direct sales channels can retain relevance against digital procurement platforms.
Market Dynamics
Fleet lifecycle extension programs across US commercial aviation are compressing maintenance intervals and forcing MRO providers to recalibrate capacity planning around aging airframe inspection cycles.
Growth Catalysts
- FAA Airworthiness Directives:Mandatory structural inspection protocols for aging aircraft are expanding addressable service hours per airframe. Repair stations certified under Part 145 capture recurring revenue from recurring compliance cycles.
- Composite Material Damage Tolerance:Carbon fiber airframe penetration above fifty percent in new deliveries is creating specialized repair demand distinct from traditional metalworking. Technicians trained in bonded repair processes command premium billing rates.
- Southeast Manufacturing Corridor Concentration:Automotive and aerospace clusters across Georgia, Alabama, and Tennessee concentrate industrial parts consumption within a four-hundred-mile radius. Proximity reduces emergency procurement lead times and supports vendor-managed inventory programs.
Market Restraints
- Specialized Labor Scarcity:FAA-certified airframe and powerplant mechanics require eighteen-to-twenty-four-month training pipelines. Enrollment shortfalls at Part 147 schools constrain shop throughput expansion regardless of equipment investment.
- Titanium and Nickel Alloy Price Volatility:Aerospace-grade superalloy exposure ties component repair pricing to London Metal Exchange fluctuations. Margin compression during commodity spikes discourages long-term fixed-price contracts.
- Consolidated OEM Distribution:Engine manufacturers' captive parts networks restrict independent MRO access to proprietary components. Boeing and Airbus authorized service centers receive allocation priority during supply-constrained periods.
Strategic Opportunities
- Texas and Florida Industrial Growth:Petrochemical expansion along the Gulf Coast and space launch infrastructure at Cape Canaveral are generating new heavy machinery maintenance demand. Service providers establishing presences in these states capture first-mover relationships with capital-intensive operators.
- OSHA Process Safety Management Integration:Chemical facility operators must document mechanical integrity programs under 29 CFR 1910.119. Third-party MRO vendors certified to manage these compliance workflows embed into plant operations beyond transactional parts supply.
- Predictive Analytics and Additive Manufacturing Convergence:Sensor-driven failure prediction combined with on-demand metal printing enables point-of-use component fabrication. Airlines experimenting with this pairing reduce AOG downtime from days to hours for select part categories.
Industry Challenges
- AS9100D Certification Timeline:Aerospace quality system accreditation requires twelve-to-eighteen-month preparation and third-party audit cycles. Smaller repair stations delay pursuit due to documentation burden, ceding commercial aviation contracts to incumbent certified shops.
- Legacy ERP Integration Friction:Digital procurement platforms must interface with decades-old maintenance management systems prevalent in industrial facilities. API standardization gaps force expensive custom middleware development for real-time inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Maintenance Repair and Operations (MRO) Market |
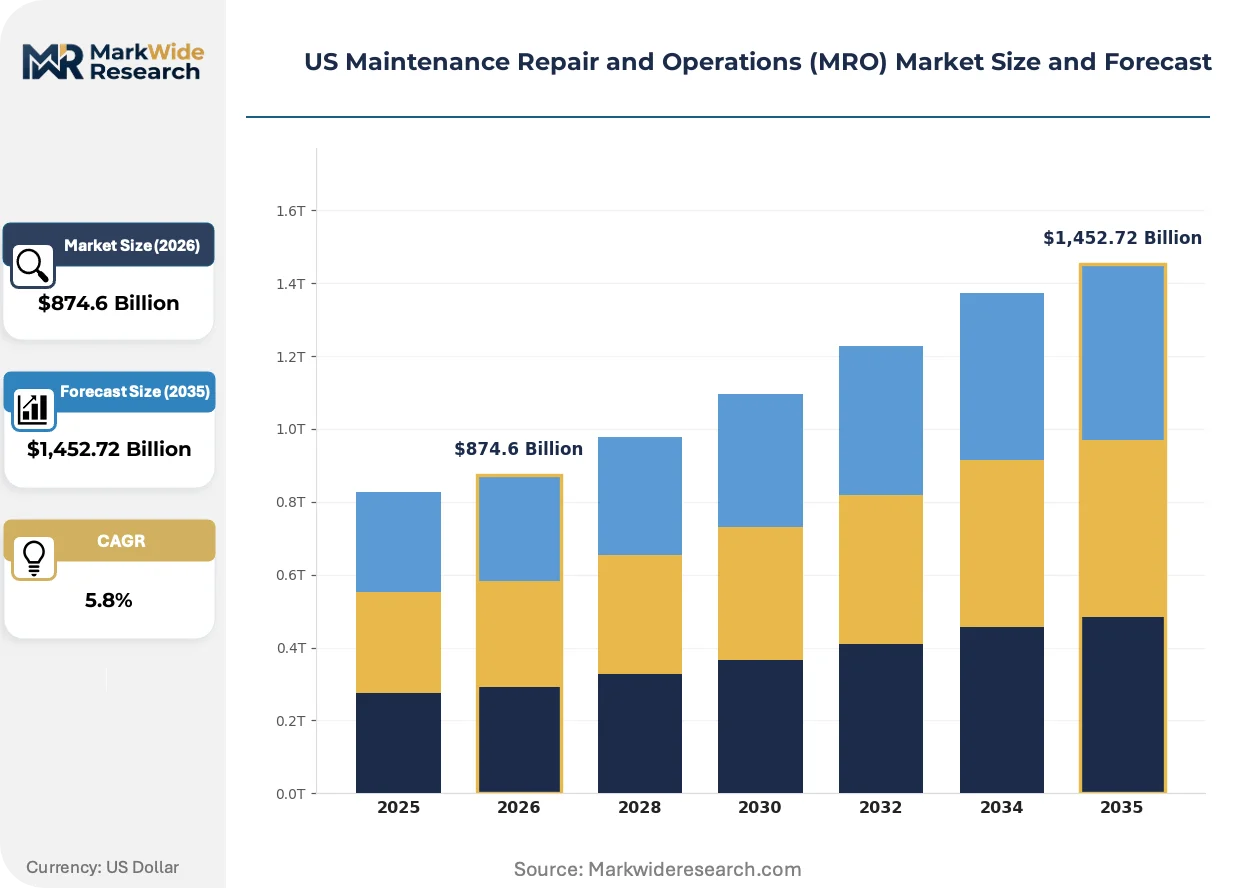
| Market Size in 2026 | $874.6 Billion |
| Market Size in 2035 | $1,452.72 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Fasteners, Safety Equipment, Electrical Supplies End User: Manufacturing, Construction, Automotive, Aviation Distribution Channel: Online Retailers, Wholesale Distributors, Direct Sales, Catalogs Service Type: Inspection, Repair, Inventory Management, Logistics |
| Companies Covered | StandardAero, Constant Aviation, AAR Corporation, Boeing Global Services, GE Aerospace, Delta TechOps, STS Aviation Group, Lufthansa Technik, HAECO Americas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Maintenance Repair and Operations (MRO) Market Trends and Innovations
Digital thread technologies are collapsing the information gap between equipment operation and maintenance execution, compressing decision cycles from weeks to hours across industrial and aviation applications.
Digital twins are unifying physical asset behavior with computational modeling across US aviation MRO operations. Airlines including Delta and United deploy these virtual replicas to simulate component degradation before physical inspection. The technology is unifying fleet-wide reliability data with individual airframe maintenance histories, enabling condition-based task interval optimization that reduces unnecessary teardowns.
OSHA's expanded enforcement of the Hazard Communication Standard is tightening chemical inventory tracking across industrial MRO warehouses. Facilities must now maintain machine-readable safety data sheet access and real-time hazardous substance location logs. Metalworking shops in Michigan and Ohio are retrofitting storage infrastructure to achieve compliance, absorbing capital costs that smaller distributors struggle to fund.
Vendor-managed inventory programs are displacing traditional purchase-order procurement among Southeast automotive suppliers. Tier-one manufacturers now require MRO providers to maintain consigned stock at plant locations with consumption-based billing. This arrangement concentrates purchasing power with buyers while transferring carrying cost risk to distributors, favoring national suppliers with balance sheet capacity over regional independents.
US Maintenance Repair and Operations (MRO) Market Segmentation
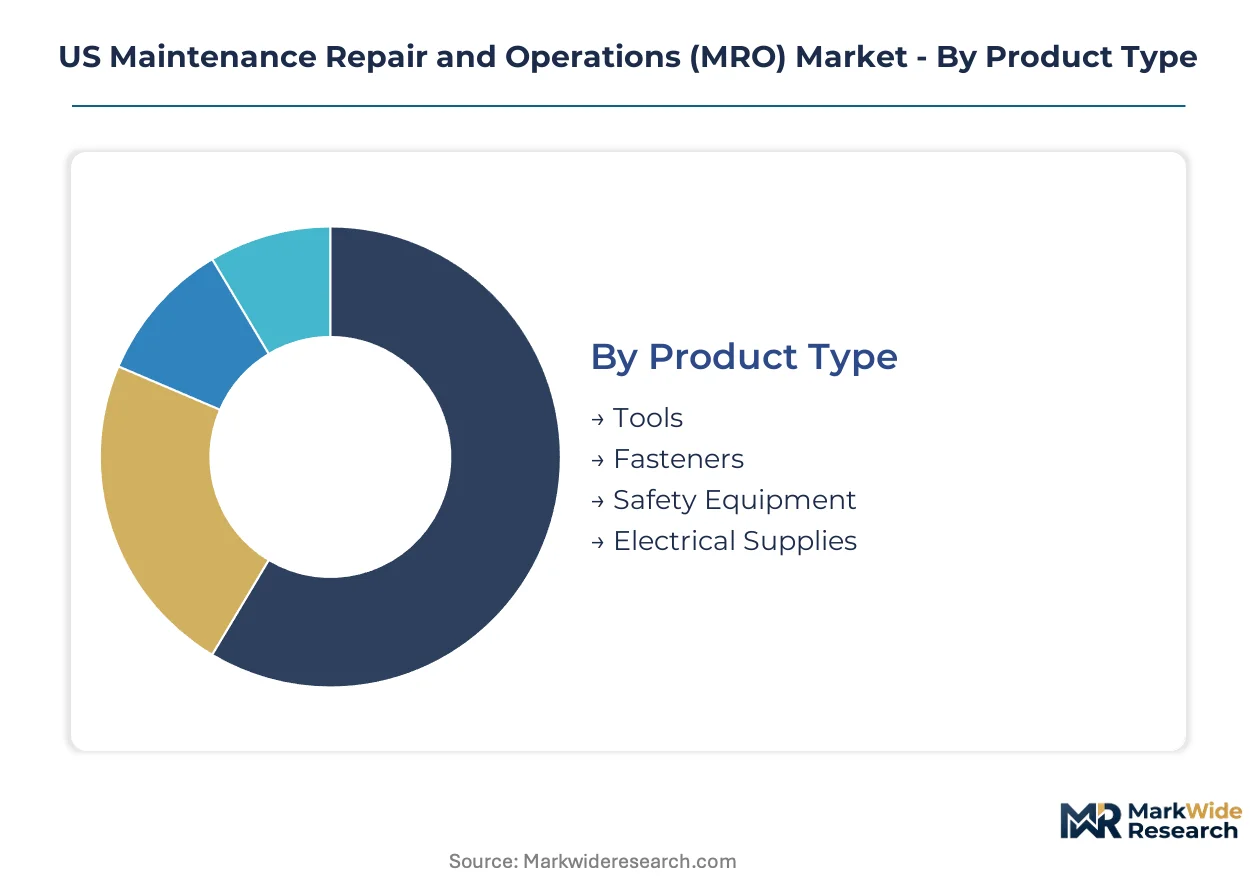
Segmentation in US MRO procurement reveals how buyer priorities diverge across capital intensity, regulatory exposure, and supply chain sophistication. Understanding these fault lines exposes where margin pools concentrate and which channels are displacing legacy purchasing patterns.
Product Type:
Buyers in this category separate by operational criticality and specification tolerance, with aviation and automotive end users demanding traceable certifications that general manufacturing does not require.
- Tools:Precision measurement instruments and calibrated torque equipment serve FAA-certified repair stations and automotive assembly lines. Demand clusters in the Southeast manufacturing corridor where Boeing and Mercedes-Benz operations require thousandth-inch tolerances on rotating machinery maintenance.
- Safety Equipment:OSHA-compliant personal protective equipment and fall protection systems carry mandatory documentation under 29 CFR standards. Chemical facilities along the Texas Gulf Coast drive volume as petrochemical expansion accelerates mechanical integrity program spending.
- Fasteners:Aerospace-grade titanium and nickel alloy hardware with full material certification.
- Electrical Supplies:Industrial-grade wiring, conduit, and arc-flash protection for facility infrastructure.
Tools lead volumes today; safety equipment is gaining share fastest as OSHA enforcement tightens.
End User:
Application environment dictates procurement behavior, with regulated industries accepting premium pricing for compliance documentation that unregulated sectors dismiss.
- Aviation:FAA Part 145 repair stations and airline captive MRO operations command the highest service margins due to airworthiness traceability requirements. Delta TechOps and United Technical Operations in Georgia and Texas concentrate demand for engine overhaul and composite repair services.
- Manufacturing:Automotive and general industrial facilities across Tennessee and Alabama prioritize vendor-managed inventory programs to reduce carrying costs. Tier-one suppliers now mandate consigned stock with consumption-based billing, transferring inventory risk to distributors.
- Automotive:Assembly plants and tier suppliers with just-in-time production lines.
- Construction:Commercial and infrastructure projects with project-based procurement cycles.
Manufacturing leads volumes today; aviation is climbing the fastest on fleet lifecycle extension programs.
Distribution Channel:
Channel selection tracks organizational digital maturity and purchase frequency, with large enterprises consolidating spend through integrated platforms while smaller operators retain legacy relationships.
- Online Retailers:Digital procurement platforms with real-time inventory visibility and punch-out catalog integration. Procurement teams at multi-site manufacturers in Ohio and Michigan are shifting from phone-based ordering to automated replenishment systems that reduce emergency procurement lead times.
- Wholesale Distributors:Regional and national distributors with branch networks and same-day delivery capabilities. Southeast automotive clusters rely on these relationships for vendor-managed inventory programs that embed suppliers into plant operations.
- Direct Sales:Manufacturer-direct relationships for high-volume, specification-critical purchases.
- Catalogs:Legacy print and PDF ordering systems retained by smaller facilities with limited procurement staff.
Wholesale distributors lead volumes today; online retailers are expanding most quickly as procurement digitization accelerates.
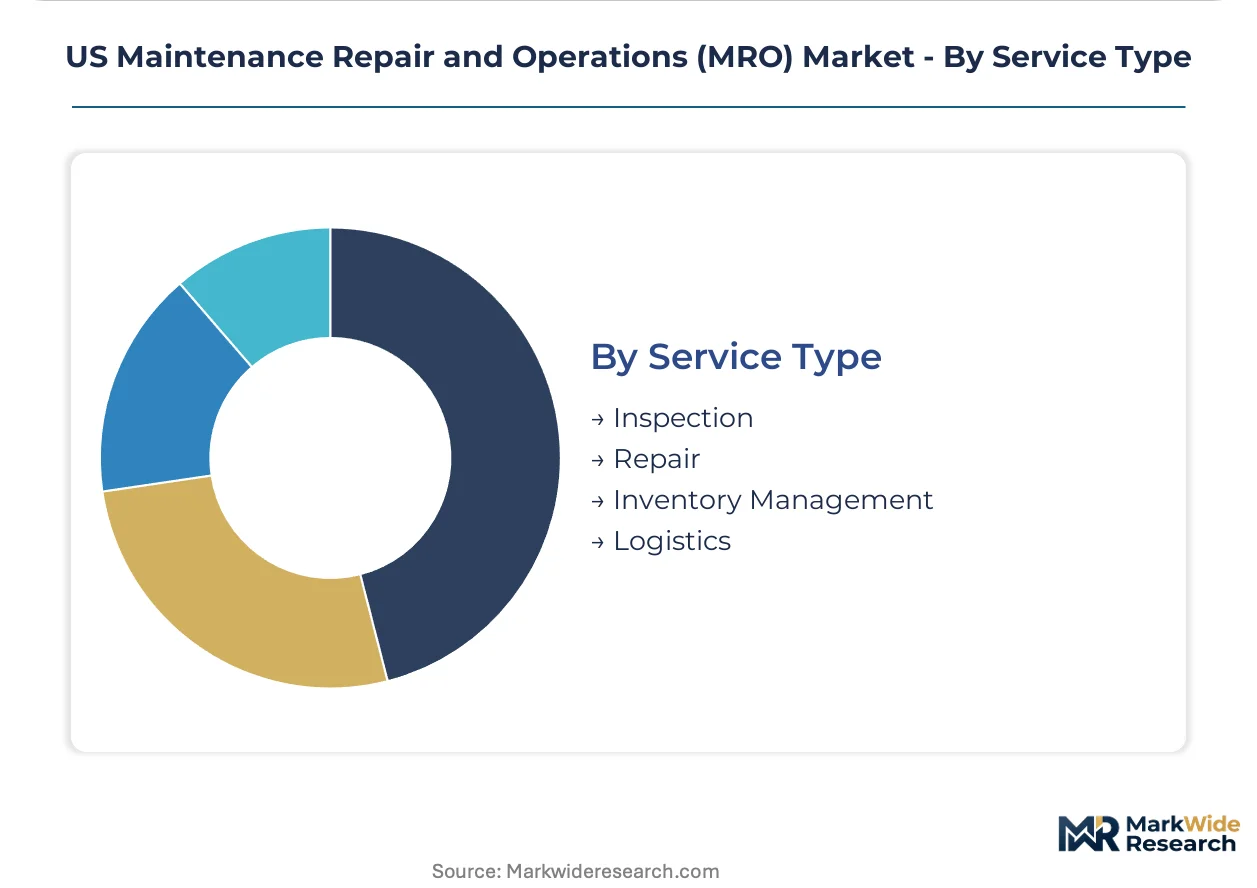
Service Type:
Service attachment rates correlate with asset criticality and downtime costs, with aviation and continuous-process manufacturers outsourcing functions that intermittent operations keep in-house.
- Inventory Management:Vendor-managed stock programs and automated replenishment systems. Tier-one automotive suppliers in Alabama and Georgia require MRO providers to maintain consigned inventory at plant locations, transferring carrying cost risk while concentrating purchasing power with buyers.
- Repair:Component overhaul and refurbishment services with turnaround time guarantees. Aviation MRO providers in Florida and Texas capture recurring revenue from aging fleet structural inspections mandated by FAA airworthiness directives.
- Inspection:Non-destructive testing and compliance documentation services.
- Logistics:Emergency parts delivery and AOG response coordination.
Repair leads volumes today; inventory management is gaining share fastest as vendor-managed programs displace traditional purchase-order procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southeast manufacturing corridor spanning Georgia, Alabama, and Tennessee anchors US MRO demand through dense automotive and aerospace clustering. Fleet lifecycle extension programs and OSHA compliance mandates are redistributing service capacity across sub-regional industrial bases.
Southeast
Georgia hosts Delta TechOps and Boeing assembly operations driving engine overhaul and composite repair demand. FAA Part 145 certification requirements concentrate certified repair stations around Atlanta and Savannah. Alabama's Mercedes-Benz and Hyundai plants mandate vendor-managed inventory programs from MRO distributors.
Texas
Petrochemical expansion along the Gulf Coast generates heavy rotating machinery maintenance demand from Dow and ExxonMobil facilities. OSHA Process Safety Management rules under 29 CFR 1910.119 require documented mechanical integrity programs. Houston anchors the nation's largest concentration of chemical facility MRO procurement.
Florida
Space launch infrastructure at Cape Canaveral and Kennedy Space Center creates specialized ground support equipment maintenance demand. FAA oversight of commercial space operations extends airworthiness protocols to launch vehicle support systems. Miami-Dade aviation clusters concentrate business jet MRO capacity serving Latin American operators.
Midwest
Michigan and Ohio metalworking shops face OSHA Hazard Communication Standard enforcement tightening chemical inventory tracking. Automotive stamping and tooling operations in Detroit-Toledo corridors consume precision measurement instrument calibration services. Cleveland and Chicago distribute industrial fasteners and cutting tools to manufacturing networks.
Pacific Northwest
Boeing's Washington state production facilities and Alaska Airlines' Seattle hub drive airframe component repair demand. EPA hazardous waste rules shape chemical handling protocols across Puget Sound industrial zones. Portland's semiconductor equipment manufacturers require ultra-clean facility maintenance exceeding standard industrial tolerances.
US Maintenance Repair and Operations (MRO) Market Competitive Landscape
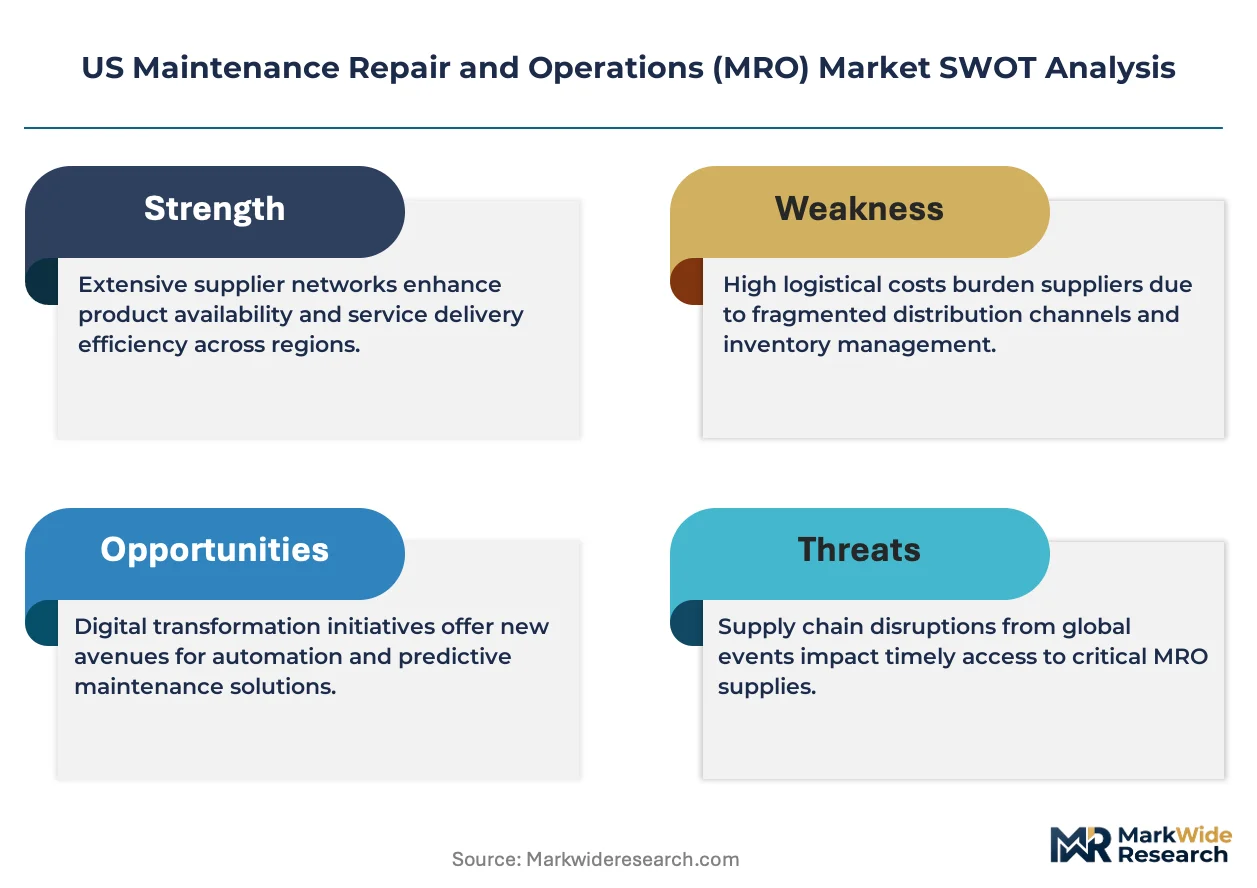
Capacity expansion dominates the current landscape as established providers add square footage to capture aging fleet inspection cycles. The market structures around three tiers: OEM-captive service centers, independent Part 145 repair stations, and diversified industrial distributors. Strategic archetypes include vertical integrators controlling engine overhaul lines, component specialists focused on narrow repair segments, and technology leaders deploying predictive analytics platforms. M&A activity and geographic expansion represent the dominant competitive vectors as players chase Southeast corridor clustering and Texas petrochemical growth.
Among independent aviation specialists, StandardAero and AAR Corporation exemplify contrasting scale positions within the maintenance ecosystem. StandardAero occupies the integrated engine overhaul tier through captive airline relationships and OEM partnerships. AAR Corporation anchors the component repair specialization vector with focused capabilities on airframe structures and landing systems. GE Aerospace represents the technology-led archetype, leveraging sensor analytics and digital thread integration across its service portfolio. These three players collectively illustrate how certification depth, geographic proximity to fleet concentrations, and technology investment separate margin capture in aviation MRO.
| Leading Market Players |
|---|
| StandardAero |
| Constant Aviation |
| AAR Corporation |
| Boeing Global Services |
| GE Aerospace |
| Delta TechOps |
| STS Aviation Group |
| Lufthansa Technik |
| HAECO Americas |
| Others |
Pricing and Supply Chain Analysis
FAA-certification tiers bifurcate the US MRO market into premium traceable services and commodity parts supply, with this divergence manifesting in both margin structures and inventory positioning strategies across Southeast aviation clusters and Gulf Coast chemical facilities.
Pricing Analysis
Titanium and nickel alloy spot price exposure feeds directly into component repair quotations through London Metal Exchange linkages. Three-tier pricing structure across OEM-authorized, AS9100D-certified, and uncertified service levels reflects documentation depth and airworthiness traceability. Cost compression in commodity fasteners and general industrial tools is intensifying because digital procurement platforms collapse information asymmetries. Tier-one automotive manufacturers exhibit lowest price sensitivity due to vendor-managed inventory consolidation, while regional job shops face acute margin pressure from catalog-to-digital procurement migration.
Supply Chain Analysis
Part 147 school enrollment shortfalls across Georgia, Alabama, and Tennessee constrain FAA-certified mechanic pipeline expansion regardless of equipment investment. Aerospace-grade superalloy sourcing draws from domestic specialty mills and European titanium processors. Single-source vulnerability concentrates in proprietary engine components where Boeing and Airbus captive networks restrict independent MRO access. Distribution runs through national wholesale networks with branch-level consignment programs embedding inventory at Southeast automotive and Texas petrochemical plant locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US MRO rests on predictive analytics adoption compressing inventory carrying costs and fleet lifecycle extension programs elevating premium-tier service attach rates.
For Market Incumbents: Cement Southeast corridor dominance through AS9100D certification preemption at Georgia and Alabama repair stations. Additive manufacturing capability investment defends against digital-native entrants targeting AOG downtime reduction. Backward integration into consigned inventory programs locks out regional distributors from tier-one automotive relationships.
For New Entrants and Emerging Players: Mid-size chemical facilities along the Texas Gulf Coast present an underserved buyer archetype lacking OSHA Process Safety Management documentation support. Digital procurement platform specialization with legacy ERP middleware integration captures procurement teams at Ohio and Michigan metalworking shops. Go-to-market through predictive maintenance analytics partnerships with industrial sensor vendors bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where AS9100D certification timelines exceed twelve months and smaller repair stations cede commercial aviation contracts. Long-term viability favors platforms combining geographic proximity to Southeast fleet concentrations with technology-led predictive capabilities. Watch FAA airworthiness directive issuance frequency as inflection indicator for addressable service hour expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| AS9100D Certification Investment | Captures recurring FAA-mandated inspection revenue from aging narrow-body fleets. |
| Predictive Analytics Platform Deployment | Delta TechOps and United Technical Operations leverage digital twins for condition-based maintenance. |
| Vendor-Managed Inventory Expansion | Mercedes-Benz and Hyundai Alabama operations require consigned stock with consumption-based billing. |
| Additive Manufacturing Capability Buildout | Point-of-use metal printing reduces AOG downtime from days to hours for select part categories. |
| Gulf Coast Geographic Presence | Dow and ExxonMobil petrochemical expansion generates heavy rotating machinery maintenance demand. |
Research Methodology
Multiple input streams — maintenance director interviews at Southeast automotive facilities, procurement lead discussions at Texas petrochemical plants, and FAA Part 145 repair station operator consultations — were reconciled against customs data, SEC filings from listed distributors, and OSHA enforcement records. Secondary validation drew from FAA airworthiness directive databases, EIA industrial energy consumption reports, and ACC chemical facility maintenance expenditure surveys. Bottom-up service hour estimates and top-down market sizing were cross-referenced for triangulation.
Historical fleet maintenance patterns were cross-referenced against expert panel input from Delta TechOps and StandardAero operations leadership. Segmentation modeling spanned product type, end-user industry, distribution channel, and service attachment rate across the projection horizon. CAGRs were derived from regression analysis of capital expenditure cycles and regulatory compliance mandate timelines. Forecast inputs included FAA aircraft registration aging curves and OSHA inspection enforcement intensity indices.
Underlying measurement precision varies by segment; aviation MRO carries tighter precision than general industrial supply due to FAA documentation requirements. Forecasts reflect assumptions about fleet lifecycle extension program continuity and commodity alloy price stability. Material deviation in FAA airworthiness directive issuance velocity or Part 147 school enrollment trends warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Heavy-Duty Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Europe Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
Car Recycling Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Vehicle Health Monitoring Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market