
 Vehicle Recycling Market | 2026-2036
Vehicle Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Recycling Market Intelligence
European shredder capacity expansion is realigning feedstock flows across the Atlantic. Schnitzer Steel Industries leverages its West Coast port infrastructure to export processed ferrous scrap to Asian steelmakers. Hensel Recycling Group anchors its competitive position through specialized catalytic converter precious metal recovery operations. Scholz Recycling GmbH dominates Central European dismantling through integrated collection-to-smelter logistics.
Vehicle recycling encompasses the systematic decommissioning, depollution, dismantling, and material recovery of end-of-life automobiles, typically processing passenger vehicles containing 65-70% ferrous metals by weight to recover reusable raw materials for secondary manufacturing. The primary industrial purpose centers on closing material loops in automotive supply chains while neutralizing hazardous fluids and components before landfill diversion. Steel and aluminum material type segments lead volume throughput due to established magnetic separation infrastructure and consistent foundry demand, while battery component recovery represents the fastest-expanding margin pool as electrified powertrains proliferate. Processing service type operations capture disproportionate value through automated shredding and post-shred separation technologies that upgrade mixed scrap into furnace-ready fractions.
The EPA administers hazardous waste classifications for automotive fluids and mercury-containing switches under RCRA, while the EU ELV Directive mandates 85% material recovery rates and producer responsibility financing across member states. China's MIIT enforces dual carbon goals that restrict raw steel output and elevate scrap-fed electric arc furnace quotas. Stakeholders must monitor how evolving battery chemistry compositions alter dismantling hazards and recovery economics before committing to specialized infrastructure.
Market Dynamics
Electrified powertrain proliferation is fragmenting established dismantling economics as battery chemistry heterogeneity forces recyclers to retool for thermal runaway containment and high-voltage isolation protocols.
Growth Catalysts
- EU ELV Directive recovery mandates:The 85% material recovery quota and producer responsibility financing obligations across member states are compelling OEMs to fund dismantling infrastructure expansion.
- Electric arc furnace steelmaking:China's MIIT dual carbon restrictions on raw steel output are elevating scrap-fed EAF quotas, pulling shredded auto bodies into metallurgical feedstock streams.
- Lithium-ion battery enclosure demand:Secondary aluminum and recovered steel from end-of-life vehicles are feeding battery housing fabrication for EV original equipment manufacturers.
Market Restraints
- Copper and aluminum price volatility:Non-ferrous scrap valuations swing with LME trading bands, compressing margin predictability for shredder operators dependent on mixed metal sales.
- Specialized dismantling labor scarcity:Certified technicians for high-voltage battery removal command wage premiums that inflate processing costs beyond legacy internal combustion vehicle economics.
- Mercury switch legacy contamination:Pre-2003 vehicle stocks retain mercury-containing convenience lighting that triggers RCRA hazardous waste classification and disposal liability.
Strategic Opportunities
- Catalytic converter precious metal recovery:Rhodium and palladium price elevation is expanding margins for specialized pyrometallurgical processing of ceramic honeycomb substrates.
- India's informal sector formalization:Central Pollution Control Board registration mandates for vehicle dismantling facilities are creating acquisition targets for integrated operators.
- Blockchain-enabled provenance tracking:Digital material passports are integrating with shredder output certification to secure furnace-ready scrap premiums from quality-sensitive buyers.
Industry Challenges
- High-voltage technician certification timelines:OEM-specific battery architecture training programs delay workforce deployment as vehicle electrification outpaces credentialing infrastructure.
- Depollution equipment capex intensity:Automated fluid extraction and refrigerant recovery systems require capital outlays that strain independent dismantler balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Recycling Market |
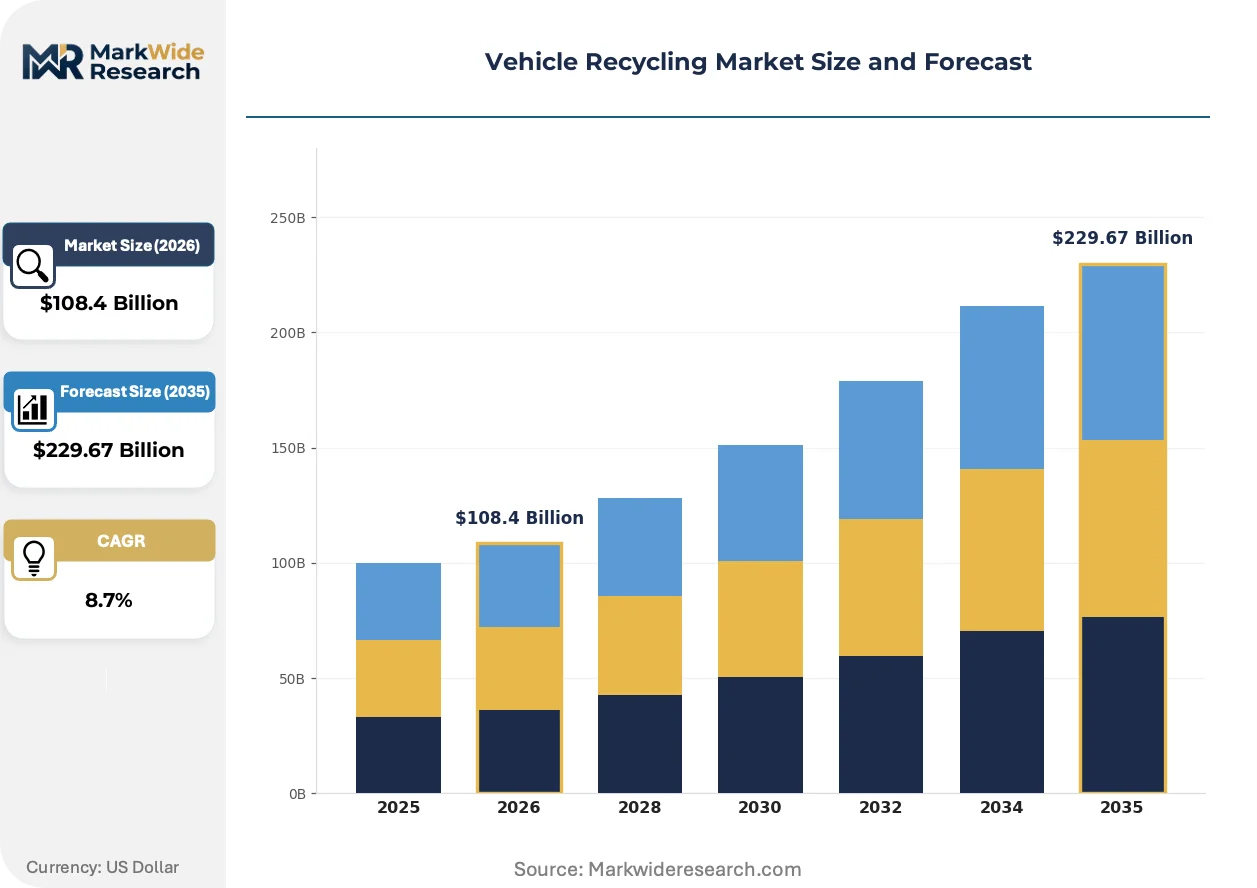
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $229.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Plastic, Glass Component: Engine Parts, Tires, Batteries, Electronics Service Type: Collection, Dismantling, Processing, Reselling End User: Automotive Manufacturers, Salvage Yards, Recycling Facilities, Consumers |
| Companies Covered | Schnitzer Steel Industries, Inc., Hensel Recycling Group, Scholz Recycling GmbH, Keiaisha Co. Ltd, Indra Automobile Recycling, Copart Inc., ASM Auto Recycling LTD, Sims Metal Management Limited, LKQ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Recycling Market Strategic Shifts & Innovations
Sensor-driven sorting and artificial intelligence classification are compressing post-shred separation economics while regulatory pressure on material provenance accelerates digital traceability adoption.
Robotic disassembly arms equipped with computer vision are integrating into dismantling lines to depollute end-of-life vehicles before shredder feeding. European operators are deploying these systems to handle heterogeneous vehicle architectures with reduced labor exposure to hazardous fluids. The technology is integrating manual-intensive depollution steps into continuous-flow processing, enabling higher throughput per square meter of facility footprint.
China's MIIT enforcement of dual carbon goals is restricting raw steel output and mandating scrap-fed electric arc furnace quotas. This regulatory pressure is redirecting shredded auto body flows toward domestic metallurgical demand rather than export markets. Shredder operators in Germany and the United States are responding by upgrading density separation to produce higher-grade furnace fractions that meet Chinese import quality specifications.
Automotive OEMs are consolidating dismantling partnerships through exclusive feedstock agreements that guarantee battery material recovery for closed-loop cathode manufacturing. These arrangements are displacing spot-market scrap sales with long-term offtake contracts indexed to London Metal Exchange pricing. The shift is most visible in Germany and South Korea, where battery cell producers are securing pyrometallurgical and hydrometallurgical processing capacity through equity stakes in recycling ventures.
Vehicle Recycling Market Segmentation
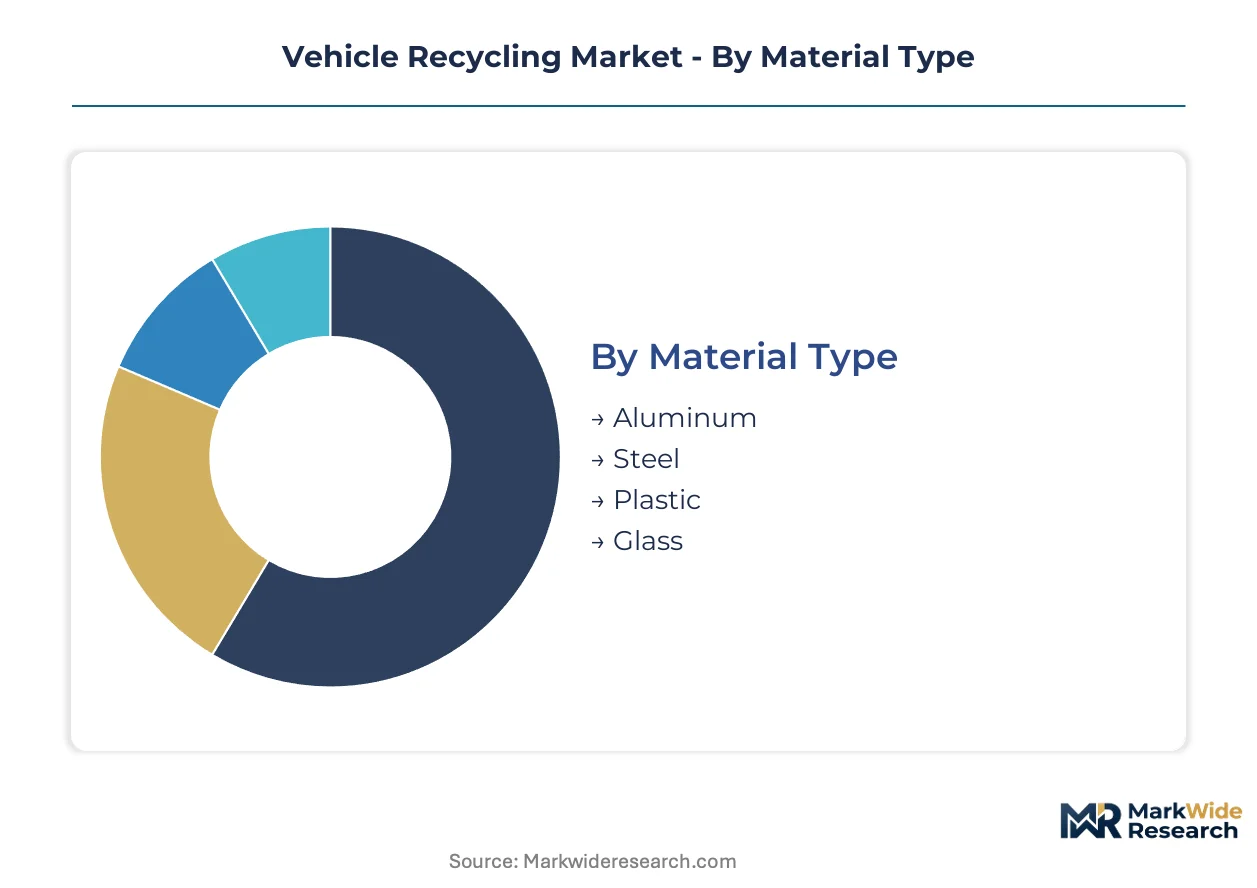
Vehicle recycling economics hinge on matching material recovery yields to downstream metallurgical specifications. Segmentation reveals how service capabilities and component complexity determine margin capture across dismantling operations.
Material Type:
Foundry feedstock specifications dictate magnetic separation investment and alloy sorting precision requirements.
- Steel:Ferrous scrap from auto bodies typically comprises 65-70% of vehicle weight and feeds electric arc furnace operations. China's MIIT dual carbon restrictions on raw steel output are elevating scrap-fed EAF quotas, pulling shredded auto bodies into metallurgical feedstock streams.
- Aluminum:Secondary aluminum recovery from engine blocks and wheel castings requires density separation and eddy current sorting. Battery enclosure manufacturers in Germany and South Korea are securing long-term offtake contracts for recovered aluminum feedstock.
- Plastic:Polypropylene and polyurethane fractions from bumpers and interior panels require resin identification and flake processing. Automotive OEMs are consolidating dismantling partnerships for closed-loop manufacturing feedstock.
- Glass:Laminated windshield glass demands specialized crushing and interlayer separation. Flat glass manufacturers accept cullet with strict contamination limits.
Steel leads on scale; aluminum leads on momentum.
Component:
Component value density determines whether dismantlers invest in manual removal or bulk shredding economics.
- Engine Parts:Cast iron blocks and aluminum cylinder heads yield high-purity ferrous and non-ferrous fractions. Remanufacturers in the United States source complete engines for rebuild programs.
- Tires:Rubber recovery through cryogenic grinding or pyrolysis produces crumb rubber and recovered carbon black. Cement kilns absorb tire-derived fuel volumes.
- Batteries:Lithium-ion packs from electrified powertrains require thermal runaway containment and high-voltage isolation protocols. OEM-specific battery architecture training programs delay workforce deployment.
- Electronics:Circuit boards and wiring harnesses contain copper and rare earth elements. Smelters in Germany process automotive electronics for precious metal recovery.
Engine parts dominate current throughput; batteries are climbing the fastest.
Service Type:
Capital intensity and labor requirements segment operators by facility scale and automation level.
- Collection:Logistics networks aggregate end-of-life vehicles from dealerships and insurance salvage. Port infrastructure on the United States West Coast enables export flows to Asian steelmakers.
- Dismantling:Manual depollution and component removal precede shredder feeding. Robotic disassembly arms equipped with computer vision are integrating into European dismantling lines.
- Processing:Automated shredding and post-shred separation upgrade mixed scrap into furnace-ready fractions. Density separation upgrades produce higher-grade fractions that meet Chinese import quality specifications.
- Reselling:Used parts distribution channels connect dismantlers with repair shops and rebuilders. Digital marketplaces are formalizing price discovery for reclaimed components.
Processing commands the steepest expansion trajectory; collection anchors baseline economics.
End User:
End-user sophistication determines quality certification requirements and contract structure preferences.
- Automotive Manufacturers:OEMs fund dismantling infrastructure expansion to meet EU ELV Directive producer responsibility obligations. Exclusive feedstock agreements guarantee battery material recovery for closed-loop cathode manufacturing.
- Salvage Yards:Independent operators prioritize part resale over material recovery. Central Pollution Control Board registration mandates in India are creating acquisition targets for integrated operators.
- Recycling Facilities:Integrated smelters and refiners purchase shredded fractions for metal recovery. Pyrometallurgical and hydrometallurgical processing capacity is securing equity stakes from battery cell producers.
- Consumers:Individual sellers transact through scrap metal dealers and online platforms. Price transparency remains limited compared to institutional channels.
Automotive manufacturers drive contract formalization; recycling facilities concentrate processing scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting dismantling investment toward jurisdictions with ELV Directive-style mandates that internalize end-of-life costs, while export-dependent operators in less regulated markets face shrinking arbitrage margins as destination countries tighten scrap quality standards.
Germany
Producer responsibility financing under the EU ELV Directive channels OEM capital into integrated collection-to-smelter networks. The KBA enforces type-approval traceability that links dismantlers to vehicle registration databases. Scholz Recycling GmbH anchors Central European capacity through its Hamburg-Rotterdam logistics corridor, processing feedstock from across the Benelux region.
China
MIIT dual carbon restrictions on raw steel output are elevating scrap-fed electric arc furnace quotas, pulling shredded auto bodies into domestic metallurgical streams. National GB standards for end-of-life vehicle recycling mandate dismantler certification and prohibit unregistered salvage trading. Shredder operators in the Yangtze River Delta are upgrading density separation to meet stricter import quality specifications for furnace-ready fractions.
United States
West Coast port infrastructure enables processed ferrous scrap exports to Asian steelmakers, though EPA RCRA hazardous waste classifications for automotive fluids complicate depollution economics. California's CARB regulations extend producer responsibility to mercury switch recovery from pre-2003 vehicle stocks. Schnitzer Steel Industries leverages its Portland-Long Beach terminal network to arbitrage trans-Pacific freight differentials.
India
Central Pollution Control Board registration mandates for vehicle dismantling facilities are formalizing a previously informal sector and creating acquisition targets for integrated operators. The Ministry of Road Transport's vehicle scrappage policy ties commercial fleet renewal to authorized recycler certificates. Gujarat and Maharashtra are concentrating the first wave of licensed shredding capacity near Ahmedabad-Pune industrial corridors.
Japan
METI recycling promotion laws mandate designated collection points and material recovery targets that exceed EU ELV quotas for specific rare earth elements. The Japan Auto Recycling Partnership coordinates OEM-funded dismantling infrastructure for hybrid and electric powertrains. Keiaisha Co. Ltd exemplifies the keiretsu-integrated model where dismantlers hold equity ties to steelmakers and battery cell producers.
Vehicle Recycling Market Key Industry Players
European producers anchor the integrated dismantling tier; North American port-access operators hold export-arbitrage positions. Market structure fragments across three functional layers: multinational shredder-smelter conglomerates with furnace integration, regional dismantling specialists with OEM partnership contracts, and salvage-yard networks prioritizing used parts resale over material recovery. Dominant competitive moves include exclusive feedstock agreements with automotive OEMs for battery material recovery, and automated shredding upgrades to capture Chinese EAF-grade scrap premiums.
Within the multinational conglomerate tier, Schnitzer Steel Industries, Inc. and Sims Metal Management Limited exemplify port-anchored arbitrage strategies, while Scholz Recycling GmbH occupies a position representing integrated Central European dismantling-to-smelter logistics. Hensel Recycling Group sits within the specialized recovery archetype, its company name signaling catalytic converter precious metal concentration rather than bulk ferrous throughput. These three anchors illustrate how geographic positioning and feedstock specialization stratify competitive returns across the value chain.
| Leading Market Players |
|---|
| Schnitzer Steel Industries, Inc. |
| Hensel Recycling Group |
| Scholz Recycling GmbH |
| Keiaisha Co. Ltd |
| Indra Automobile Recycling |
| Copart Inc. |
| ASM Auto Recycling LTD |
| Sims Metal Management Limited |
| LKQ Corporation |
| Others |
Cost & Logistics Intelligence
The EU ELV Directive recovery mandates gate both qualified dismantler certification and premium-tier furnace-ready scrap pricing access. OEM-funded infrastructure expansion under producer responsibility obligations is concentrating certified supply capacity while spot-market operators face margin compression from quality-sensitive buyers.
Pricing Analysis
Distributor margins on shredded ferrous scrap absorb logistics cost volatility before smelter offtake. Contract-based long-term offtake agreements indexed to London Metal Exchange pricing dominate OEM partnerships, while spot-market transactions face compression from Chinese import quality specifications. Price differentiation rests on furnace-ready grade certification and density separation precision. Independent dismantlers exhibit highest price sensitivity due to depollution equipment capex intensity; integrated smelter-conglomerates command lowest sensitivity through captive furnace demand.
Supply Chain Analysis
Single-source vulnerability sits with German shredder-smelter logistics corridors feeding Central European EAF operations. Raw material flows draw from end-of-life vehicle aggregation in the United States, China, and Germany, with component dependencies on high-voltage battery architectures, catalytic converter substrates, and aluminum wheel castings. Tariff exposure on trans-Pacific ferrous scrap movements threatens West Coast port-anchored arbitrage strategies. Distribution runs through exclusive feedstock agreements with automotive OEMs and spot-market sales to integrated steelmakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vehicle recycling market functions as a stable compounder. Regulatory mandates for material recovery quotas and producer responsibility financing create durable demand floors for certified dismantling capacity.
For Market Incumbents: To counter battery chemistry heterogeneity disrupting legacy dismantling economics, incumbents should acquire high-voltage technician certification infrastructure and deepen backward integration into pyrometallurgical battery processing. Exclusive OEM feedstock agreements for closed-loop cathode manufacturing anchor volume certainty against spot-market volatility. For New Entrants and Emerging Players: Capture India's formalizing dismantling sector under Central Pollution Control Board registration mandates, where licensed shredding capacity concentrates near Ahmedabad-Pune industrial corridors. Partner with commercial fleet operators on vehicle scrappage policy compliance to secure predictable feedstock inflows. For Investors and Strategic Acquirers: Roll-up economics work for regional dismantling specialists with OEM partnership contracts because fragmented salvage-yard networks lack capital for automated depollution and shredder upgrades. Target operators with port infrastructure or integrated collection-to-smelter logistics. Watch Chinese MIIT enforcement of scrap-fed EAF quotas as the inflection signal for furnace-ready scrap premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Shredder Upgrades | Density separation precision captures Chinese EAF-grade scrap premiums under MIIT dual carbon enforcement. |
| High-Voltage Technician Certification Programs | OEM-specific battery architecture training addresses workforce deployment delays from electrification pace. |
| Exclusive OEM Feedstock Agreements | Long-term offtake contracts displace spot-market sales for battery material closed-loop recovery. |
| Catalytic Converter Recovery Capacity | Pyrometallurgical processing of ceramic honeycomb substrates expands margins from rhodium and palladium price elevation. |
| Blockchain-Enabled Provenance Tracking | Digital material passports secure furnace-ready scrap premiums from quality-sensitive smelter buyers. |
Research Approach
Bottom-up dismantling throughput modeling reconciled against top-down steel and aluminum scrap supply tracking forms the analytical core. Primary interviews with dismantling facility operators, OEM sustainability officers, smelter procurement managers, and high-voltage technician training program administrators combined with secondary validation from EPA hazardous waste classifications, EU ELV Directive implementation reports, and China MIIT dual carbon policy enforcement disclosures. Trade data on ferrous scrap flows and electric arc furnace operating rates triangulate volume estimates.
Historical trendline analysis of shredder capacity expansion and material recovery rate improvements informed projection parameters across the analysis window. Segmentation dimensions modeled include material type, component complexity, service capability tier, and end-user sophistication. CAGRs derived from regression against EAF steelmaking adoption curves and battery electric vehicle penetration assumptions. Forecast inputs incorporate battery chemistry evolution timelines and regulatory quota phase-in schedules.
Regulatory enforcement intensity, battery chemistry standardization pace, and scrap-fed EAF quota achievement rates are the dominant revision risks. Forecasts reflect documented assumptions about OEM producer responsibility financing continuity and Chinese import quality specification stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
Stolen Vehicle Recovery Market
Vehicle Maintenance & Aftermarket
Portable Leather Polishing Machine Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Asia Pacific Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Cleaning Products Market
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Polisher Market