
 Cap Liner Market | 2026-2036
Cap Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Cap Liner Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is shifting the cost-of-entry calculus for cap liner material suppliers. AptarGroup leverages its extensive R&D in sustainable polymers to meet these new compliance demands. Berry Global competes on its massive manufacturing scale and ability to source recycled content globally. Selig Group differentiates through its specialization in induction heat-seal liners for high-barrier applications in sensitive end-use industries.
A cap liner is a disc or layer of material inserted within the cap of a container. Composed of materials like foam, polyethylene, or aluminum foil, it provides a seal between the cap and the container's rim to ensure product integrity. Foam-based polyethylene liners dominate the beverage and food processing sectors due to their cost-effectiveness and sealing performance. However, multi-layered aluminum foil liners for tamper evidence and leakage prevention in the pharmaceutical industry represent a higher-margin application.
Regulations from the US FDA, the European Medicines Agency (EMA), and China's NMPA dictate material composition and safety standards for liners in contact with food and drugs. These frameworks directly influence material selection and market access for suppliers. Supplier success will depend on navigating the complex trade-offs between cost, performance, and the increasing regulatory pressure for material circularity.
Market Dynamics
The fundamental dynamic in the cap liner market is the structural tension between escalating sustainability mandates and the non-negotiable performance requirements of high-value end-use sectors. Regulatory pressure for material circularity, exemplified by the EU Green Deal, directly conflicts with the need for complex, multi-layer barrier materials essential for product safety in the pharmaceutical and food industries.
Growth Catalysts
- Regulatory Mandates for Circularity:Directives under the EU Green Deal are compelling brand owners to adopt mono-material and recyclable liners, creating a dedicated growth vector for suppliers with certified sustainable polymer solutions.
- Pharmaceutical Sector Expansion:The global expansion of parenteral drugs and biologics requires advanced induction-seal and high-barrier liners to ensure sterility and prevent contamination, a demand reinforced by stringent EMA and FDA guidelines.
- Food and Beverage Processing Growth:Rising food and beverage manufacturing output in industrializing economies, particularly India and Brazil, is driving high-volume demand for cost-effective foam-based polyethylene liners for non-sensitive products.
Market Restraints
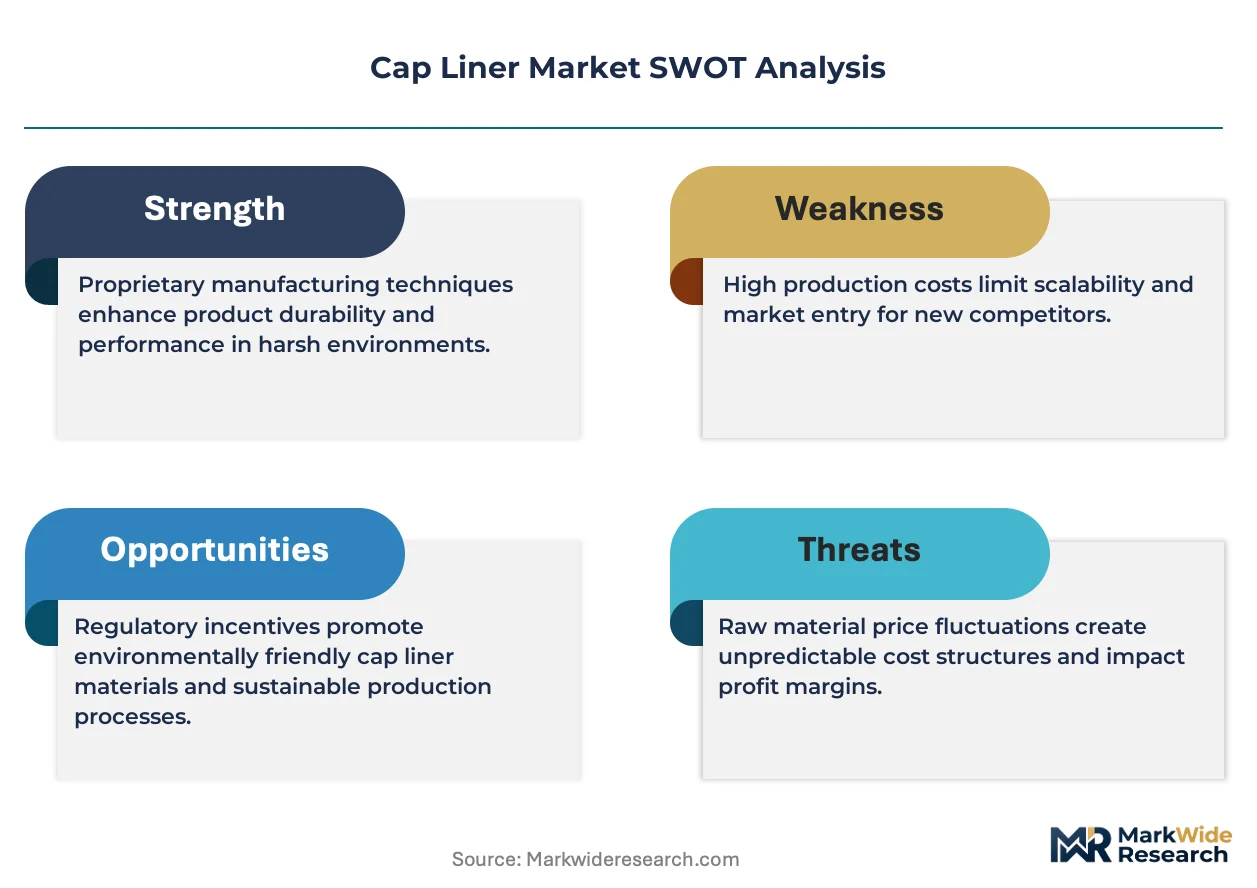
- Input Material Price Volatility:Fluctuations in the cost of key raw materials, such as polyethylene resins and aluminum foil, directly impact liner manufacturing costs and create margin pressure for suppliers.
- Performance Gaps in Sustainable Alternatives:Mono-material liners often exhibit lower barrier performance against oxygen and moisture compared to traditional multi-layer composites, limiting their use in sensitive applications.
- Regulatory Qualification Hurdles:The extensive time and cost required to test and certify new, sustainable materials for food contact compliance with bodies like the US FDA and EFSA slows market introduction of innovations.
Strategic Opportunities
- Liners for New Beverage Categories:The rapid growth of plant-based milks, cold-brew coffee, and functional beverages creates an opportunity for specialized liners designed to protect unique flavor profiles and extend shelf life.
- Smart Packaging Integration:Incorporating NFC or RFID technology into liners offers a pathway for anti-counterfeiting, supply chain tracking, and direct consumer engagement, particularly for premium spirits and pharmaceuticals.
- Personal Care Market Penetration:Expanding personal care and cosmetics markets in Southeast Asia present an opportunity for liners that offer premium aesthetics, enhanced sealing for viscous products, and tamper evidence.
Industry Challenges
- Certification and Compliance Burden:Recertifying entire product portfolios to meet evolving material regulations and sustainability standards like the CSRD imposes significant administrative and testing costs on suppliers.
- Supply Chain Reconfiguration:Shifting procurement from established suppliers of composite liners to new vendors specializing in mono-materials requires a complete requalification process, disrupting established logistics and quality control protocols.
- Capital Investment for Modernization:Upgrading manufacturing lines to process novel biopolymers or recycled-content resins requires significant capital expenditure, creating a barrier for smaller, less capitalized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cap Liner Market |
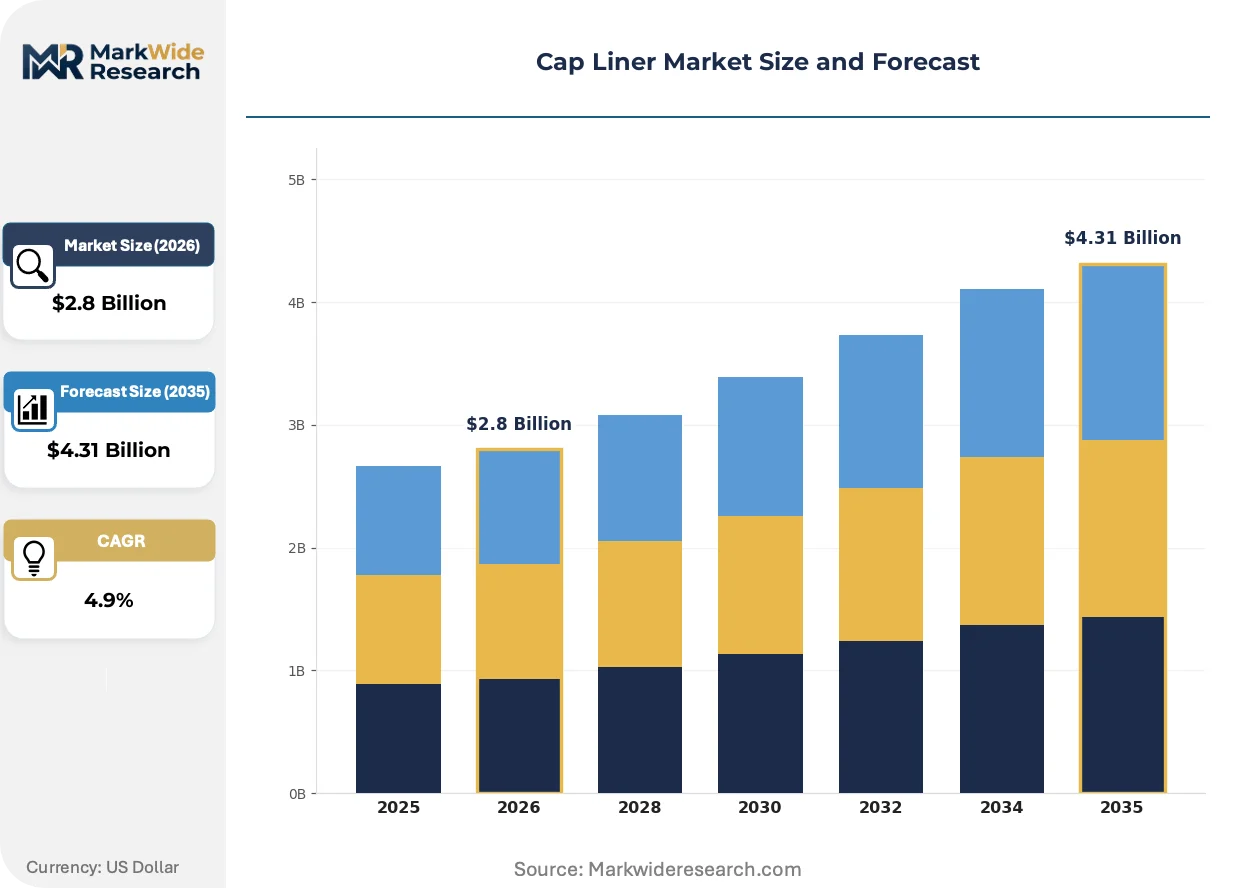
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.31 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Foam, Polyethylene, Rubber, Aluminum, Cork, Synthetic Packaging Type: Closure Caps, Screw Caps, Flip-Top Caps, Snap-On Caps, Spray Caps, Pump Caps End Use Industry: Beverage, Personal Care, Pharmaceuticals, Chemicals, Food Processing Application: Sealant, Leakage Prevention, Insulation, Tamper Evidence |
| Companies Covered | AptarGroup, Selig Group, Tekni-Plex, Press-On Corporation, Bluemay Weston Limited, Meyer Seals, Berry Global, Guala Closures, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cap Liner Market Strategic Shifts & Innovations
The cap liner industry is undergoing a material science-led transformation, re-engineering products to meet circular economy goals without compromising sealing integrity. This shift prioritizes recyclability and the elimination of problematic substances, forcing innovation in polymer chemistry and liner construction.
Mono-material polyethylene and polypropylene liners are designed specifically for compatibility with common container recycling streams. Food, beverage, and consumer goods companies are rapidly adopting these solutions to meet corporate sustainability targets and respond to consumer preferences. This movement toward simplified, recyclable designs is absorbing market share from legacy multi-layer and coated foil liners that contaminate plastic recycling processes.
Heightened regulatory focus on material safety is altering formulation strategies. The US FDA's scrutiny of PFAS compounds in food-contact applications is compelling a phase-out of certain fluorinated chemicals traditionally used for oil and grease resistance in liners. This directly impacts suppliers to the food and industrial packaging sectors, who must now invest in developing and validating effective, PFAS-free barrier technologies.
A significant behavioral shift is occurring in how sustainability claims are validated by customers. Brand owners are increasingly demanding third-party verification of recycled content, such as ISCC PLUS certification, rather than relying on supplier declarations. This change disrupts traditional procurement practices by embedding rigorous auditing into the supply chain. The trend is most advanced within the European CPG sector, where regulatory and consumer expectations for transparency are highest.
Cap Liner Market Segmentation
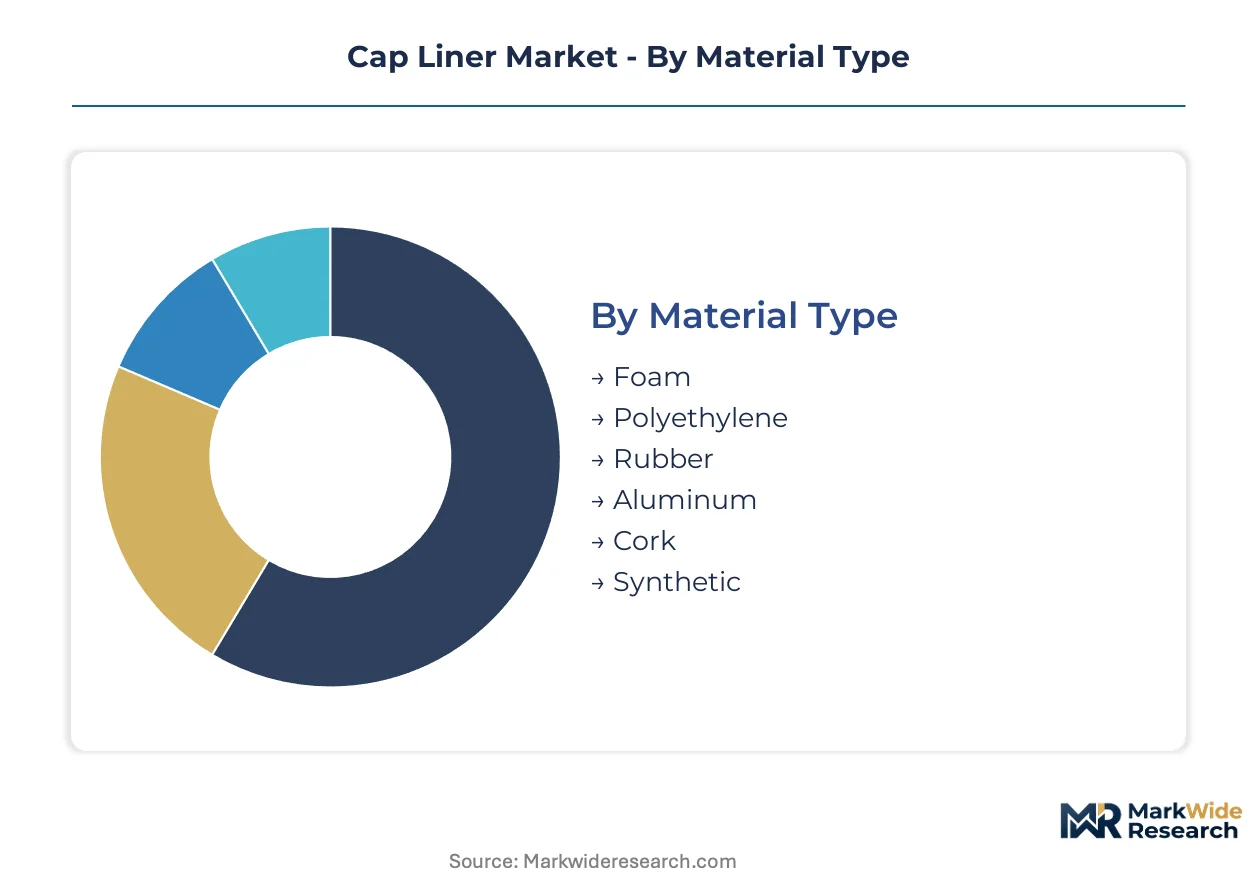
The cap liner market's segmentation provides a granular view of material science, application complexity, and end-use demands. Understanding these distinctions clarifies where innovation is concentrated and where established technologies maintain market dominance. This detailed breakdown highlights the critical trade-offs between cost-effectiveness, performance characteristics, and regulatory compliance across diverse packaging needs.
Material Type:
The capital intensity of developing and producing advanced cap liner materials significantly influences market entry and competitive positioning.
- Polyethylene:These liners, often foam-based, offer excellent sealing performance and cost-effectiveness for high-volume applications. Demand concentrates in the food processing and beverage sectors, driven by the need for reliable, economical seals.
- Aluminum:Multi-layered aluminum foil liners provide superior barrier properties against moisture and oxygen, critical for product stability and extended shelf life. The pharmaceutical sector, under stringent EMA and FDA guidelines, represents a high-value application for these high-barrier solutions.
- Foam:Cost-effective and widely used, foam liners offer general-purpose sealing for various consumer goods.
- Rubber:Providing chemical resistance and elasticity, rubber liners serve specialized applications requiring robust sealing for aggressive contents.
- Cork:Traditionally employed in wine and spirits, cork liners offer a natural aesthetic and effective sealing for specific beverage categories.
- Synthetic:Engineered polymers beyond standard polyethylene provide enhanced barrier performance or specific chemical resistance for niche industrial applications.
Most installed capacity flows through Polyethylene. Expansion is steepest in Aluminum.
Packaging Type:
Application complexity dictates the design and material selection for cap liners, influencing both manufacturing processes and product performance.
- Screw Caps:These represent the most common packaging type, requiring versatile liners to ensure product integrity across a broad range of consumer goods. Universal adoption across food, beverage, and personal care drives high-volume liner demand.
- Pump Caps:Designed for dispensing viscous liquids or foams, pump caps demand specialized liners that prevent leakage and maintain product efficacy. The personal care and pharmaceutical industries rely on these for precise, contamination-free delivery systems.
- Closure Caps:A broad category encompassing various cap designs, these require liners that provide basic sealing and product protection.
- Flip-Top Caps:Offering user convenience, flip-top caps necessitate liners that maintain a secure seal despite frequent opening and closing cycles.
- Snap-On Caps:Used for quick sealing applications, snap-on caps typically require less complex liners for non-critical product containment.
- Spray Caps:Employed in aerosols and fine mist products, spray caps need liners that can withstand internal pressure and prevent propellant escape.
Volume demand is highest for Screw Caps. Innovations are concentrated in Pump Caps.
End Use Industry:
Profitability margins vary significantly across end-use industries, with high-value sectors driving demand for advanced cap liner solutions.
- Pharmaceuticals:This sector demands high-barrier, tamper-evident, and sterile liners to protect sensitive drug formulations and ensure patient safety. Stringent regulations from the US FDA and European Medicines Agency (EMA) mandate rigorous material qualification.
- Food Processing:Requiring liners that extend shelf life and prevent spoilage, this industry drives demand for cost-effective, high-performance sealing solutions. India and Brazil's expanding food processing output creates significant volume opportunities.
- Beverage:High-volume production in the beverage industry requires efficient, reliable liners for carbonation retention and freshness.
- Personal Care:Liners in personal care products must offer aesthetic appeal, prevent leakage of viscous formulations, and provide tamper evidence.
- Chemicals:This industry requires liners with strong chemical resistance and robust barrier properties to safely contain hazardous or corrosive substances.
The largest market share originates from Food Processing. Strategic investment targets Pharmaceuticals.
Application:
The criticality of a cap liner's function directly impacts material selection and design, prioritizing specific performance attributes.
- Tamper Evidence:Liners designed for tamper evidence provide a visual indicator if a product has been opened or compromised, crucial for consumer safety and regulatory compliance. Pharmaceutical and high-value food products heavily utilize these features.
- Leakage Prevention:This fundamental application ensures product containment, preventing spills during transport and storage while maintaining product integrity. Universal across all end-use sectors, it is a non-negotiable performance requirement.
- Sealant:The primary function of a liner, forming an airtight or liquid-tight barrier between the cap and container, is essential for product preservation.
- Insulation:Specialized liners offer thermal insulation properties, protecting temperature-sensitive contents from external heat or cold fluctuations.
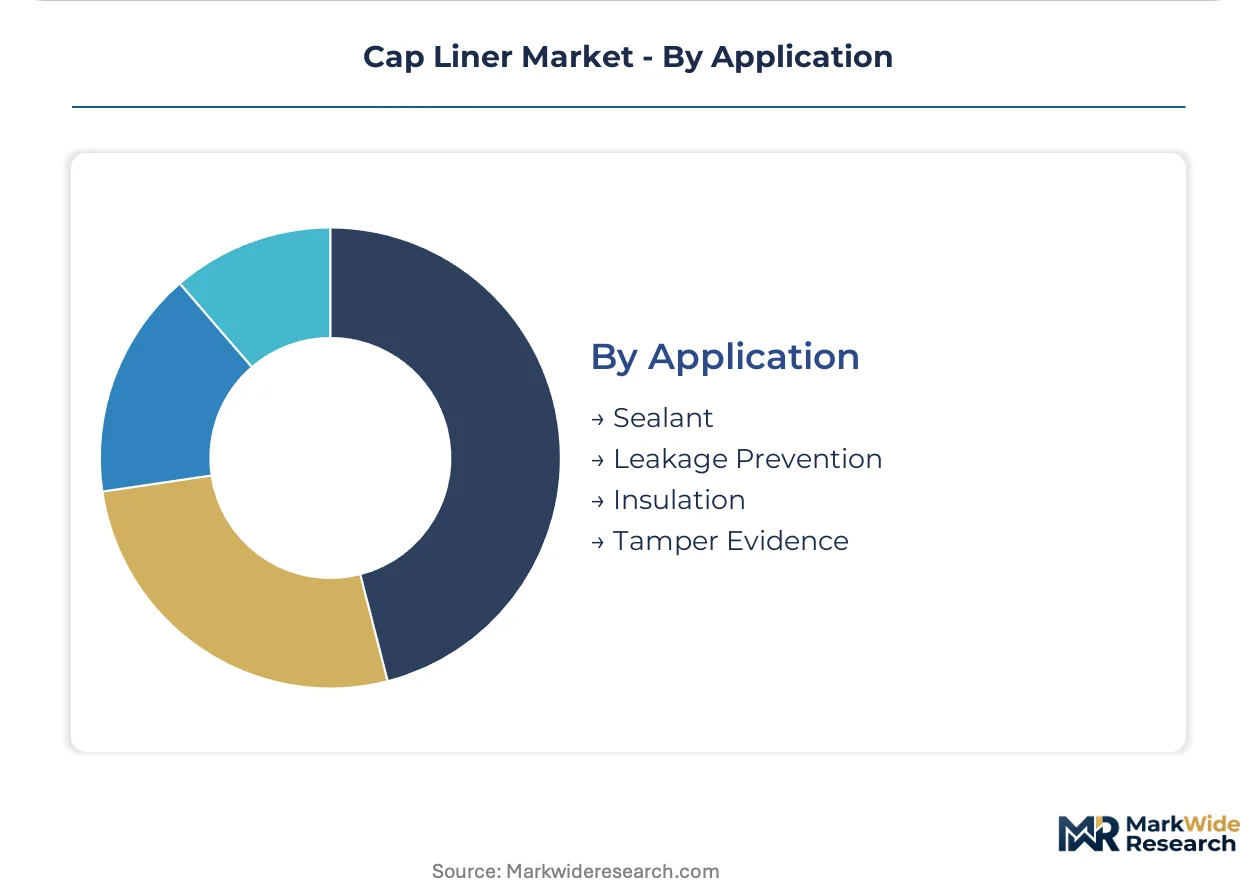
Core demand is concentrated in Leakage Prevention. Future growth vectors point towards Tamper Evidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent in key manufacturing regions drives innovation in cap liner solutions. These concentrations of expertise support both domestic demand and export markets for advanced sealing technologies. The global cap liner market sees significant activity across diverse economic landscapes.
United States
Pharmaceutical sector expansion, particularly for parenteral drugs and biologics, creates demand for advanced induction-seal liners. US FDA guidelines mandate rigorous material qualification for all food and drug contact applications. Research hubs in Boston and California focus on high-barrier and smart packaging integration for premium products.
Germany
European sustainability mandates, including directives under the EU Green Deal and CSRD, compel brand owners to adopt mono-material and recyclable liners. The German national pharmaceutical regulator, EMA, influences material selection for drug packaging. The Rhine-Ruhr region, a major industrial center, develops mono-material polyethylene and polypropylene liners for European brand owners.
India
Rising food and beverage manufacturing output, alongside pharmaceutical sector expansion, drives high-volume demand for cost-effective liners. BIS standards guide material safety and quality for domestic consumption across various industries. Manufacturing hubs around Mumbai and Bengaluru expand production capacity for foam-based polyethylene liners.
China
The expanding food processing sector and the pharmaceutical industry's growth create substantial demand for both basic and high-barrier cap liner solutions. NMPA regulations dictate material safety and performance for drug packaging. Industrial zones in the Yangtze River Delta concentrate on producing both high-volume foam liners and specialized aluminum foil solutions.
Brazil
Robust growth in food processing and expanding personal care markets stimulate demand for reliable and cost-effective cap liners. ANVISA guidelines impact material selection for food and pharmaceutical contact applications. São Paulo's industrial base serves as a key production center for cap liners, catering to both domestic and South American export needs.
Cap Liner Market Key Industry Players
The competitive structure tilts toward specialized innovation and scale manufacturing in the cap liner market. A tiered landscape emerges, encompassing material science innovators, large-scale producers, and niche technology specialists. Companies pursue strategic partnerships for sustainable material development and invest in R&D to meet evolving regulatory demands. Capacity expansion in emerging markets also represents a key competitive move.
Within the material science and specialized solutions tier, AptarGroup exemplifies innovation in sustainable polymers, representing a focus on meeting new compliance demands. Berry Global, a large-scale producer, occupies a position anchored by its extensive global manufacturing footprint and sourcing capabilities for recycled content. This allows Berry Global to address the growing need for circularity in packaging materials. Selig Group differentiates through its specialization in induction heat-seal liners, particularly for high-barrier applications in sensitive end-use industries. These entities collectively underscore the market's emphasis on both advanced material development and efficient, compliant production at scale.
| Leading Market Players |
|---|
| AptarGroup |
| Selig Group |
| Tekni-Plex |
| Press-On Corporation |
| Bluemay Weston Limited |
| Meyer Seals |
| Berry Global |
| Guala Closures |
| Amcor |
| Others |
Cost & Logistics Intelligence
Skilled manufacturing workforces in industrial centers like the Yangtze River Delta and São Paulo influence cap liner pricing structures, creating distinct pricing tiers based on labor cost differentials and production scale.
Pricing Analysis
Bundled service offerings, integrating material supply with technical support and certification guidance, command premium pricing within the cap liner market. Contract-based long-term offtake dominates for large volume buyers, while smaller, specialized orders operate on a per-unit transactional model. FDA certification for pharmaceutical-grade liners and customization for unique packaging designs drive significant price premiums. Pricing softness reflects intense competition from Asian manufacturers in high-volume, standard polyethylene liners. Food processing customers are highly price-sensitive for foam-based liners, whereas pharmaceutical companies prioritize performance and regulatory compliance over cost.
Supply Chain Analysis
Domestic content mandates in countries like India and Brazil are reshaping cap liner sourcing, compelling local production for expanding food and beverage sectors. Production heavily concentrates in China, India, and Germany, serving both domestic and export markets. The supply chain relies heavily on polyethylene resins and aluminum foil, whose global prices are subject to volatility. Input material price volatility presents a significant structural risk, directly impacting manufacturing costs and supplier margins. Downstream distribution primarily runs through a mix of direct sales to large brand owners and specialized packaging distributors for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cap liner market functions as a geographic-arbitrage play, leveraging lower manufacturing costs in India and Brazil compared to the higher regulatory compliance overhead in the European Union.
For Market Incumbents:
Deploy strategic capacity expansion in emerging markets to counter margin pressure from new entrants. Incumbents should invest in upgrading manufacturing lines in regions like India and Brazil, focusing on cost-effective foam-based polyethylene liners. Simultaneously, deepen R&D in sustainable polymers to meet evolving EU Green Deal mandates. This counters the threat of regulatory-driven market displacement by specialized material science innovators.
For New Entrants and Emerging Players:
Specialized packaging distributors represent a penetrable channel for new entrants offering niche cap liner solutions. Focus on developing mono-material polyethylene and polypropylene liners certified for recyclability, targeting European consumer goods companies. The personal care market in Southeast Asia also offers significant white-space opportunity for liners with premium aesthetics and enhanced sealing for viscous products. A go-to-market angle emphasizing rapid regulatory qualification and third-party sustainability verification will resonate with brand owners.
For Investors and Strategic Acquirers:
Specialized material science firms are the most active acquirers in this space, seeking to integrate advanced polymer technologies and intellectual property. Long-term viability hinges on companies that can successfully navigate the structural tension between sustainability mandates and performance requirements. Acquisition targets should include innovators in PFAS-free barrier technologies and developers of smart packaging integration for anti-counterfeiting. The signal to watch is the widespread adoption of ISCC PLUS certification by major brand owners, indicating validated sustainable supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands production footprint in high-growth regions like India, meeting rising demand for cost-effective liners. |
| Sustainable Material R&D | Develops mono-material and recyclable liners, aligning with EU Green Deal and CSRD compliance demands. |
| Certification Investment | Secures critical regulatory approvals like FDA and EMA, enabling market access to high-value pharmaceutical applications. |
| Strategic Partnership | Collaborates with technology firms to integrate NFC/RFID into liners, enhancing smart packaging capabilities for premium products. |
| Geographic Expansion | Penetrates underserved markets in Southeast Asia, capturing growth in personal care and cosmetics sectors. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core for assessing the cap liner market. This approach integrates primary interviews with packaging engineers, procurement managers at CPG firms, and regulatory compliance officers. Secondary validation draws from trade association reports, regulatory body publications from the US FDA and EMA, and company financial filings. The methodology ensures a robust understanding of both demand drivers and supply capabilities within the industry.
An input-output matrix framing quantifies market dynamics across the analysis window, projecting future trends based on key variables. The framework segments the market by material type, packaging type, end-use industry, application, and regional regulatory clusters. Compound annual growth rates are derived from historical trend analysis and projected shifts in material adoption and end-user demand. Key forecast inputs include raw material price projections and anticipated regulatory implementation timelines.
Revisions become necessary when unforeseen shifts in raw material supply, new regulatory mandates, or disruptive material innovations materialize. Forecasts reflect assumptions regarding economic stability and technological progression. Specific risk factors, such as sudden policy changes affecting plastic recycling or significant fluctuations in oil prices, could alter market trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Side Pour Caps Market
Caps and Closures
South Africa Plastic Caps and Closures Market
Caps and Closures
Benelux Plastic Caps and Closures Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Spout Closures Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Twist Dispensing Closures Market
Caps and Closures
Caps and Closures Market
Caps and Closures
IBC Caps Market
Caps and Closures
Polypropylene Screw Caps Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Overcaps Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Crimp Top Cap Market
Caps and Closures
Box Latch Market
Caps and Closures
Cork Stoppers Market