
 Canada Whey Protein Ingredients Market | 2026-2036
Canada Whey Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Whey Protein Ingredients Market Outlook
Food and beverage manufacturer procurement is consolidating around fewer large-scale contract buyers with technical specification expertise. Agropur Dairy Cooperative leverages its Quebec processing network to secure long-term supply agreements with major CPG customers. Glanbia PLC competes on whey protein isolate capacity and sports nutrition channel penetration. Saputo Inc. anchors its position through backward integration into fluid milk supply across Eastern Canada.
Whey protein ingredients comprise milk-derived fractions separated during cheese production, containing beta-lactoglobulin and alpha-lactalbumin protein fractions with typical concentrate grades spanning 34% to 80% protein content; these ingredients function primarily as functional nutrition inputs and texture-modifying agents in formulated foods. Whey protein isolate commands premium positioning due to higher purity and lower lactose content, while hydrolyzed whey attracts specialized sports nutrition applications with its pre-digested peptide structure. Powder form dominates commercial volumes because of shelf stability and blending compatibility across protein fortification and muscle recovery applications.
Health Canada enforces protein content verification and allergen labeling through the Food and Drugs Regulations, while the Canadian Food Inspection Agency audits dairy processing facilities for HACCP compliance. The Safe Food for Canadians Regulations mandate traceability systems that increase operational costs for smaller whey fractionators. Stakeholders must monitor evolving protein claim thresholds and sustainability audit requirements from major retail banners.
Market Dynamics
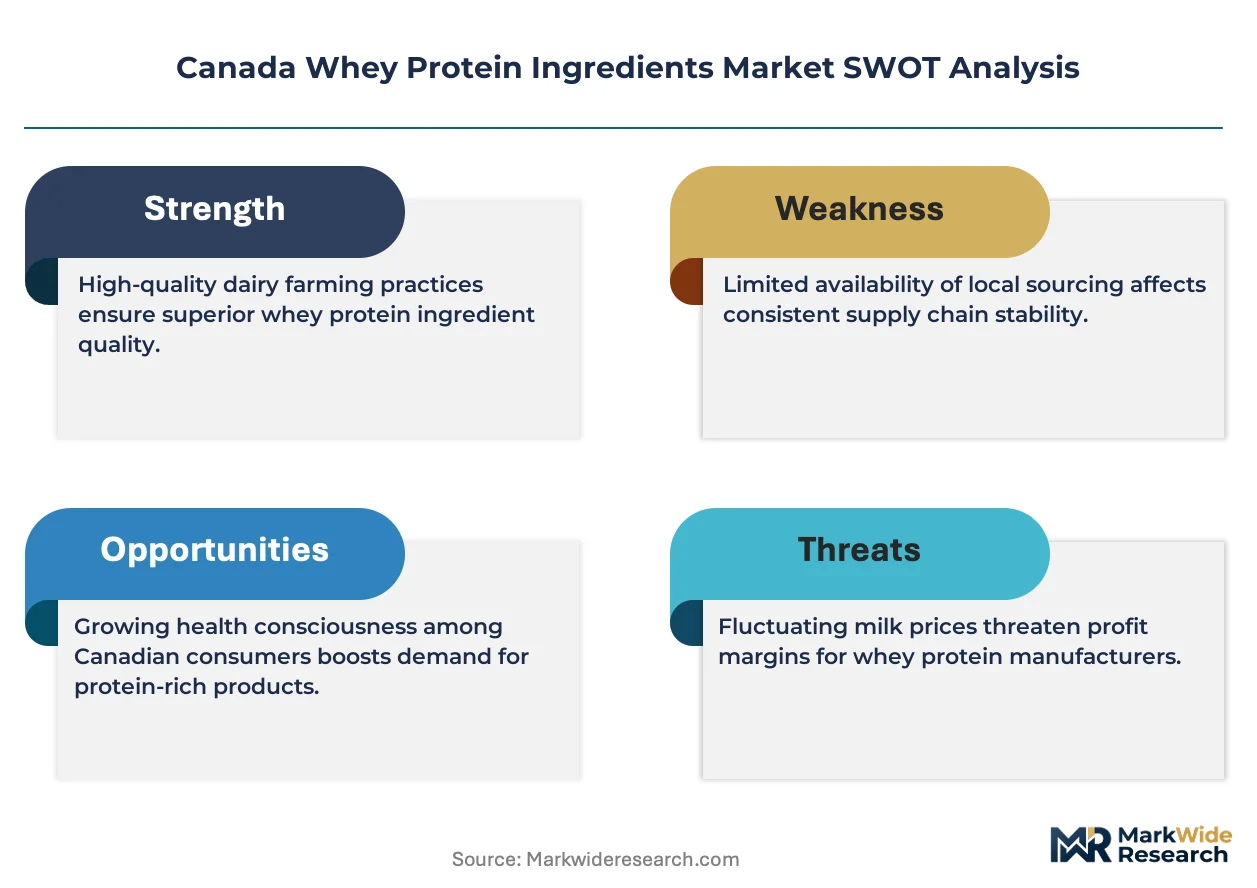
Consolidation among Canadian dairy processors is compressing supplier margins while concentrating technical specification power in the hands of fewer large-scale contract buyers across Ontario and Quebec processing corridors.
Growth Catalysts
- Health Canada protein claim thresholds:The Natural Health Products Directorate's evolving purity standards create compliance-driven demand for higher-grade whey isolates among sports nutrition formulators seeking differentiated positioning.
- Cross-border sports nutrition procurement:US-based functional food manufacturers are expanding Canadian whey isolate sourcing to secure supply chain proximity and tariff-advantaged trade flows under CUSMA provisions.
- Cheese production volume expansion:Fluid milk processing growth in Quebec and Ontario generates increased whey fraction availability, lowering raw material acquisition costs for domestic ingredient processors.
Market Restraints
- Fluid milk price volatility:Canadian Dairy Commission pricing adjustments create input cost instability that compresses whey fractionator margins unpredictably across quarterly cycles.
- Quebec-Ontario supply concentration:Over 80% of whey protein processing capacity sits within 400 kilometers of Montreal and Toronto, exposing buyers to regional weather and logistics disruptions.
- Plant protein substitution threat:Pea and oat protein isolates from Prairie processing facilities are capturing share in mass-market protein fortification applications where taste differentiation matters less.
Strategic Opportunities
- Western Canada underpenetration:Alberta and British Columbia food manufacturing corridors lack localized whey fractionation capacity, creating greenfield investment potential for processors with fluid milk partnerships.
- Medical nutrition applications:Hospital and long-term care procurement specifications for immunonutrition formulas favor high-purity whey hydrolysates with documented bioactive peptide profiles.
- CFIA digital traceability mandates:The Safe Food for Canadians Regulations' enhanced tracking requirements favor processors with integrated ERP systems, creating competitive separation from smaller fractionators.
Industry Challenges
- Protein chemistry specialization gap:Whey fractionation facilities require operators with dairy biochemistry expertise that Canadian technical colleges produce in insufficient volumes relative to industry expansion.
- Legacy equipment retrofit timelines:Converting cheese plants for isolate-grade production demands 18-24 month capex cycles that strain cooperative member capital commitment horizons.
- Organic certification pathway complexity:Transitioning conventional dairy supply to Canadian Organic Regime standards requires three-year herd conversion periods that deter rapid portfolio pivots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Whey Protein Ingredients Market |
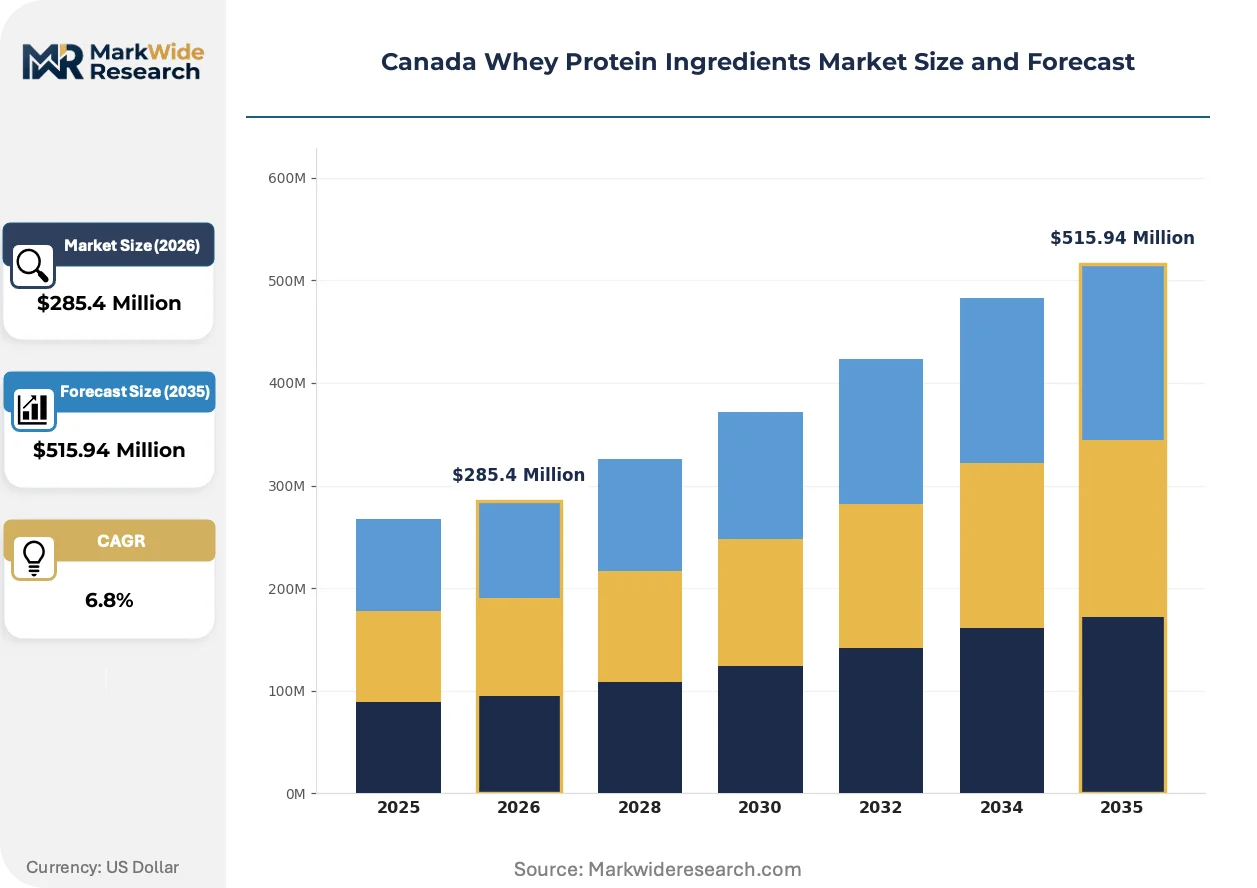
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey, Native Whey End User: Food & Beverages, Nutritional Supplements, Dairy Products, Bakery & Confectionery Form: Powder, Liquid, Granulated, Capsule Application: Protein Fortification, Muscle Recovery, Weight Management, Sports Nutrition |
| Companies Covered | Fonterra Co-operative Group Limited, Arla Foods, Agropur Dairy Cooperative, Milk Specialties Global, Cooke Inc, Glanbia PLC, Groupe Lactalis, Dairy Farmers of America, Saputo Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Whey Protein Ingredients Market Strategic Shifts
Membrane filtration advances and shifting buyer specification power are compressing traditional grade boundaries while forcing processors to demonstrate bioactive peptide retention beyond crude protein metrics.
Microfiltration-ceramic hybrid systems are rewriting whey isolate production economics by enabling continuous processing with reduced thermal degradation of immunoglobulin fractions. Sports nutrition contract manufacturers in the Greater Toronto Area are adopting these systems at replacement cycle points, compressing the premium gap between isolate and concentrate grades as functional bioactivity becomes the specified differentiator rather than crude protein percentage alone.
Health Canada's evolving Natural Health Products Directorate monograph requirements for protein content verification and specific health claim substantiation are tightening label compliance burdens. The regulatory friction most acutely affects mid-sized sports nutrition brands lacking in-house regulatory affairs capacity, driving consolidation of formulation partnerships toward larger processors with dedicated compliance infrastructure in Quebec and Ontario.
Ingredient specification sheets now dominate buyer-processor negotiations, replacing spot-price contracting with multi-year technical partnership agreements. Large CPG procurement teams in Montreal and Toronto are unbundling protein sourcing from full-service ingredient supply, directly engaging fractionators for custom isolate grades while relegating commodity concentrate procurement to trading houses.
Canada Whey Protein Ingredients Market Segmentation
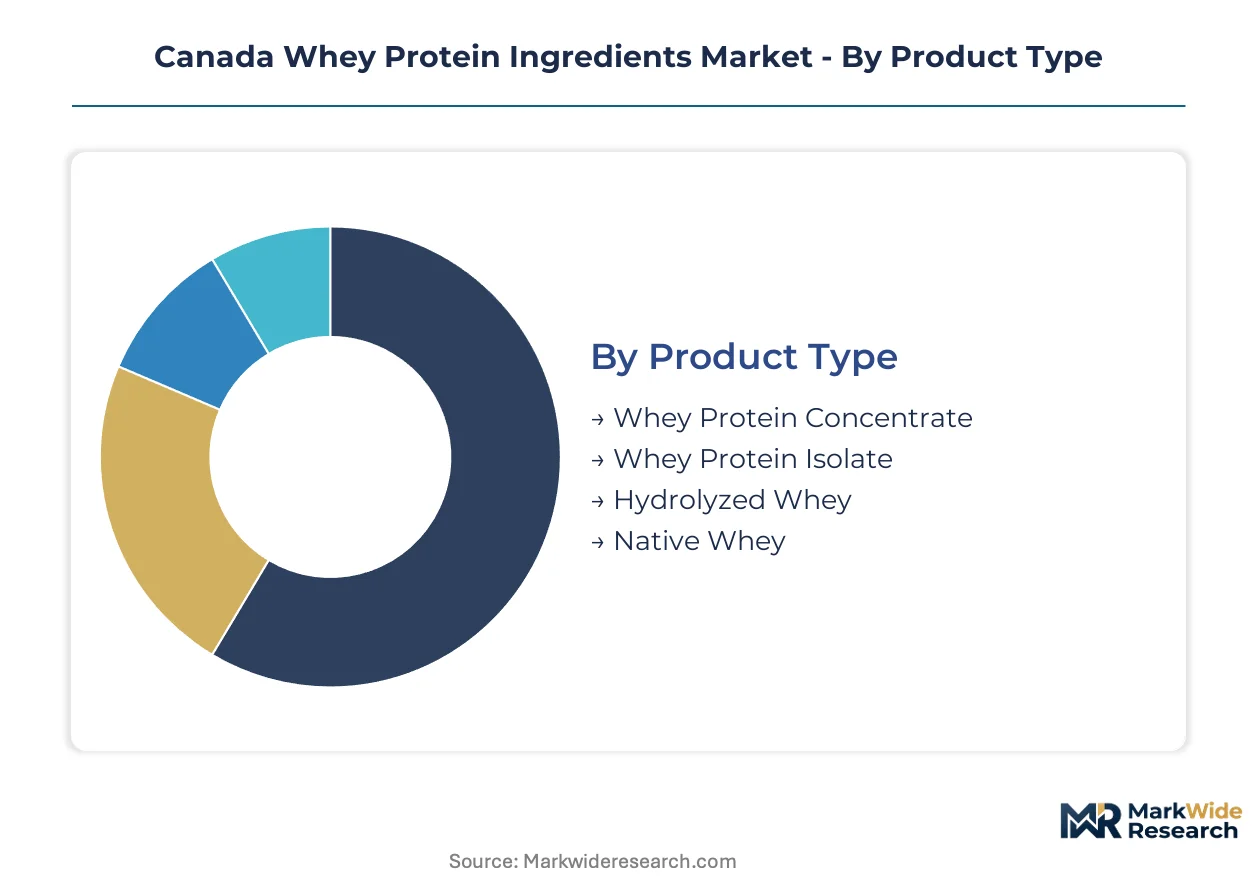
Whey protein ingredient procurement in Canada stratifies sharply between commodity-grade concentrates and premium isolates, with specification power consolidating among fewer technical buyers. Segmentation decisions determine margin capture, regulatory compliance burden, and vulnerability to plant protein substitution across Ontario and Quebec processing corridors.
Product Type:
Volume concentrates dominate tonnage while premium isolates command specification power in sports nutrition channels.
- Whey Protein Concentrate:Grades span 34% to 80% protein content, functioning as cost-effective fortification inputs for mass-market bakery and dairy applications. Ontario food manufacturers leverage concentrate economics for mainstream protein enrichment where bioactive retention matters less than unit cost.
- Whey Protein Isolate:Delivers 90%+ protein purity with minimal lactose, attracting Health Canada-compliant sports nutrition formulators seeking differentiated positioning. Quebec processors capture premium positioning through membrane filtration investments that satisfy Natural Health Products Directorate purity thresholds.
- Hydrolyzed Whey:Pre-digested peptide structures command specialized sports nutrition and medical nutrition premiums.
- Native Whey:Cold-processed from milk rather than cheese whey retains higher immunoglobulin fractions for premium functional applications.
Today's leader: Whey Protein Concentrate. Tomorrow's challenger: Whey Protein Isolate.
End User:
Procurement consolidation favors large-scale contract buyers with in-house technical specification expertise over fragmented spot purchasers.
- Food & Beverages:Mass-market fortification applications in ready-to-drink beverages and snack bars concentrate buying power among Montreal and Toronto CPG headquarters. Health Canada's protein claim verification requirements favor processors with dedicated regulatory infrastructure.
- Nutritional Supplements:Sports nutrition brands drive isolate-grade demand through direct fractionator relationships, bypassing traditional ingredient distributors.
- Dairy Products:Greek yogurt and high-protein fluid milk applications absorb concentrate volumes from Quebec cheese production corridors.
- Bakery & Confectionery:Texture-modifying concentrate applications face substitution pressure from Prairie-sourced pulse proteins.
Nutritional Supplements climb the fastest on isolate premiums; Food & Beverages defend volume leadership.
Form:
Supply chain economics favor formats with shelf stability and blending compatibility across dispersed Canadian manufacturing geography.
- Powder:Dominates commercial volumes through moisture stability, bulk handling efficiency, and compatibility with automated blending systems. British Columbia and Alberta food manufacturers rely on powder logistics given distance from Quebec-Ontario fractionation clusters.
- Liquid:Fresh whey streams serve adjacent cheese plants with minimal transport economics.
- Granulated:Agglomerated particles improve dispersibility for instant beverage applications.
- Capsule:Pre-measured dosing formats target direct-to-consumer supplement channels with compliance packaging requirements.
Powder maintains supply chain dominance; Liquid captures freshness premiums in regional corridors.
Application:
Functional claims differentiation separates commodity protein inputs from premium-priced specialized nutrition.
- Protein Fortification:Mass-market bakery, beverage, and snack applications absorb concentrate volumes where taste neutrality and cost efficiency outweigh bioactive specifications. Prairie oat and pea protein isolates threaten share in undifferentiated fortification segments.
- Muscle Recovery:Sports nutrition brands specify isolate and hydrolysate grades with documented leucine content and absorption kinetics, creating technical barriers to commodity substitution.
- Weight Management:Satiety-focused formulations favor high-purity isolates with minimal carbohydrate contribution.
- Sports Nutrition:Pre- and post-workout applications drive the steepest premium pricing for hydrolyzed and native whey fractions.
Protein Fortification holds volume crown; Sports Nutrition captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's whey protein processing concentrates in Ontario and Quebec corridors, while Alberta and British Columbia food manufacturers import powder from eastern fractionators due to underdeveloped local capacity.
Ontario
Greek yogurt and high-protein fluid milk applications absorb concentrate volumes from Toronto-area dairy processing clusters. Health Canada's Food and Drugs Regulations enforce protein content verification and allergen labeling standards that favor large processors with dedicated compliance infrastructure. The Greater Toronto Area hosts sports nutrition contract manufacturers adopting microfiltration-ceramic hybrid systems at replacement cycle points.
Quebec
Cheese production expansion in the Saint-Hyacinthe and Victoriaville corridors generates increased whey fraction availability for ingredient processors. The Canadian Food Inspection Agency audits dairy facilities for HACCP compliance under the Safe Food for Canadians Regulations. Montreal-based CPG procurement teams engage fractionators directly for custom isolate grades, bypassing traditional ingredient distributors.
Alberta
Food manufacturing growth in Calgary and Edmonton corridors lacks localized whey fractionation capacity, forcing reliance on rail-shipped powder from Quebec-Ontario clusters. Prairie-sourced pea and oat protein isolates capture share in mass-market fortification applications where taste differentiation matters less. The province's dairy processing infrastructure remains concentrated in fluid milk rather than ingredient fractionation.
British Columbia
Health-conscious consumer demand in Vancouver and Victoria metro areas drives premium isolate procurement for sports nutrition and functional beverage applications. Distance from eastern fractionation centers elevates logistics costs for powder shipments. The province's natural products sector aligns with Health Canada Natural Health Products Directorate requirements for label claims and purity thresholds.
Atlantic Canada
Smaller-scale dairy processing in Nova Scotia and New Brunswick generates limited whey stream volumes for commercial fractionation. Regional food manufacturers source concentrate through distributor networks rather than direct processor relationships. The area remains dependent on supply chain flows from Quebec and Ontario processing corridors.
Canada Whey Protein Ingredients Market Competitive Environment
Quebec-based cooperatives anchor one tier; Irish and New Zealand dairy multinationals hold another through cross-border supply arrangements. The Canadian whey protein ingredients market structures around three to four large-scale fractionators with membrane filtration investments and a fragmented tier of smaller trading houses. Two strategic archetypes dominate: cooperative-backed processors with captive fluid milk supply and multinational dairy ingredients divisions with global sourcing networks. Competitive moves concentrate on long-term supply agreements with major CPG customers and capacity investments in isolate-grade production.
Within the cooperative tier, Agropur Dairy Cooperative and Dairy Farmers of America exemplify the model of backward integration into fluid milk supply. Glanbia PLC represents the multinational specialist archetype competing on isolate capacity and sports nutrition channel penetration. Saputo Inc. occupies a hybrid position bridging Canadian dairy cooperative heritage with North American scale. These three anchors illustrate the competitive tension between local supply security and global technical specification expertise.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Arla Foods |
| Agropur Dairy Cooperative |
| Milk Specialties Global |
| Cooke Inc |
| Glanbia PLC |
| Groupe Lactalis |
| Dairy Farmers of America |
| Saputo Inc. |
| Others |
Value Chain & Pricing Dynamics
Isolate-concentrate grade bifurcation in Canadian whey protein channels generates divergent pricing power and supply chain configurations, with premium membrane-filtered isolates commanding specification-driven premiums while commodity concentrates compete on volume scale and logistics efficiency. Health Canada's Natural Health Products Directorate purity thresholds reinforce this divergence by embedding compliance costs that smaller fractionators cannot absorb, compressing supply options for buyers seeking differentiated positioning.
Pricing Analysis
Capacity additions in Quebec and Ontario cheese corridors are reshaping price floors for whey concentrates while isolate premiums remain anchored to membrane filtration investments. Contract-based long-term offtake dominates buyer-processor relationships, with price differentiation driven by protein purity grade and Health Canada certification tier. Cost compression in concentrate segments is intensifying because fluid milk price volatility transmits unpredictably through Canadian Dairy Commission pricing cycles. Mass-market bakery and beverage manufacturers exhibit highest price sensitivity, while sports nutrition brands demonstrate lowest sensitivity given isolate specification requirements.
Supply Chain Analysis
Skilled dairy biochemistry technicians in Quebec and Ontario manufacturing clusters constrain expansion timelines for fractionation facilities seeking isolate-grade production. Geographic supply concentration centers on Canada for fluid milk and whey streams, with secondary dependencies on US membrane filtration equipment and Irish multinational technical expertise. Single-source vulnerability runs through the Montreal-Toronto processing corridor where over 80 percent of capacity sits within 400 kilometers. Distribution runs through rail-bulk powder shipments to Alberta and British Columbia food manufacturers, with direct processor relationships bypassing traditional ingredient distributors for isolate grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's whey protein ingredients market functions as a regulatory compounder where Health Canada's evolving Natural Health Products Directorate monograph requirements continuously elevate compliance barriers and consolidate procurement around technically capable processors.
For Market Incumbents: Deploy membrane filtration capacity expansion to defend isolate-grade positioning against plant protein substitution threats from Prairie-sourced pea and oat isolates. Secure backward integration into fluid milk supply through cooperative membership structures or long-term supply agreements with Quebec and Ontario dairy producers. Channel control through direct CPG procurement relationships in Montreal and Toronto headquarters protects margin capture against trading house commoditization.
For New Entrants and Emerging Players: Capture Western Canada underpenetration by establishing Alberta or British Columbia fractionation partnerships with regional fluid milk processors. Target medical nutrition procurement specifications for immunonutrition formulas in hospital and long-term care channels where bioactive peptide documentation creates technical barriers to incumbent substitution. Go-to-market through specialized sports nutrition contract manufacturers seeking secondary isolate sourcing reduces customer acquisition friction against established Quebec-Ontario processors.
For Investors and Strategic Acquirers: Asymmetric upside sits with processors possessing integrated ERP systems that satisfy CFIA digital traceability mandates under Safe Food for Canadians Regulations. Long-term viability across the analysis window favors fractionators with demonstrated Health Canada compliance infrastructure and isolate-grade membrane filtration assets. Monitor Canadian Dairy Commission pricing announcement timing as inflection indicator for input cost compression cycles affecting cooperative member returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Enables isolate-grade production that satisfies Health Canada purity thresholds for sports nutrition channels. |
| Backward Integration into Fluid Milk Supply | Secures captive whey stream access through Quebec and Ontario dairy cooperative partnerships. |
| CFIA Digital Traceability Compliance Investment | Creates competitive separation from smaller fractionators under Safe Food for Canadians Regulations mandates. |
| Medical Nutrition Application Development | Opens hospital procurement channels requiring documented bioactive peptide profiles for immunonutrition formulas. |
| Western Canada Geographic Expansion | Addresses Alberta and British Columbia manufacturing corridor demand currently served by rail-shipped eastern powder. |
Study Parameters
Multiple input streams — primary interviews with dairy processing executives and sports nutrition formulators, secondary validation through Health Canada regulatory filings and Canadian Dairy Commission pricing records, and customs data on cross-border whey ingredient flows — were reconciled to construct market estimates. Primary fieldwork engaged plant managers at Quebec and Ontario fractionation facilities, procurement leads at Toronto and Montreal CPG headquarters, and regulatory affairs specialists navigating Natural Health Products Directorate compliance pathways. Secondary sources included Canadian Food Inspection Agency audit records, provincial dairy board production statistics, and trade flow databases tracking US-Canada whey movements under CUSMA provisions. Bottom-up volume modeling and top-down value reconciliation triangulated segment estimates.
Data-stream reconciliation across product type, end user, form, and application dimensions anchored the analytical framework throughout the projection horizon. Segmentation modeling incorporated protein grade tier, geographic processing corridor, regulatory compliance tier, and channel structure. CAGRs were derived from fitted growth curves calibrated to historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs included Canadian Dairy Commission pricing cycle assumptions, membrane filtration capacity expansion timelines, and plant protein substitution elasticity estimates for mass-market fortification applications.
Fluid milk price volatility, regulatory claim threshold revisions, and plant protein isolate quality improvements are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding cheese production volume expansion and cross-border procurement patterns. Practitioners should monitor Canadian Dairy Commission announcement schedules, Health Canada monograph updates, and Prairie pulse protein processing capacity additions for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Beer Adjuncts Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Wheat Starch Derivative Market
Ingredients
South America Fruit and Vegetable Ingredients Market
Ingredients
Guar Gum Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Hen Egg White Protein Market
Ingredients
Dry Molasses Products Market
Ingredients
Dry Mixes Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Potato Granules Market
Ingredients
Sugared Egg Yolk Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Canola Oil Market
Ingredients
Marine Protein Market
Ingredients
Fish Feed Ingredients Market