
 Dry Molasses Products Market | 2026-2036
Dry Molasses Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Molasses Products Market Foresight
The EU Green Deal is hardening feed-grade ingredient standards across member states, compelling livestock nutrition formulators to verify sustainability credentials for molasses-derived inputs. Cargill, Incorporated leverages its integrated supply chain from Brazilian cane processing to North American feed mills, sustaining volume leadership across multiple geographies. Archer Daniels Midland Company dominates the merchant trade in dry molasses derivatives, while Zook Molasses Company specializes in region-specific formulations for Midwestern dairy cooperatives.
Dry molasses products consist of dehydrated sugarcane or sugar beet molasses, typically reduced to ten to fifteen percent moisture content through spray-drying or drum-drying processes, yielding free-flowing powders or pellets used as palatability enhancers, fermentation substrates, and soil amendment carriers. Powdered molasses leads volume in feed applications due to its ease of bulk handling and uniform blending with mineral premixes, while pelletized molasses commands premium positioning among equine and specialty livestock segments where dust control and measured dosing matter. Organic dry molasses occupies a narrowing but high-margin niche as certified operations in the European Union and North America enforce strict provenance requirements.
The United States Department of Agriculture and the Food and Drug Administration jointly govern molasses labeling and feed safety under the Federal Food, Drug, and Cosmetic Act, while the European Food Safety Authority evaluates novel molasses applications under updated feed additive authorization pathways. Brazil's Ministry of Agriculture enforces its own sanitary standards for imported molasses products, creating a multi-jurisdictional compliance burden for exporters. Stakeholders must monitor evolving carbon accounting rules for agricultural inputs, as scope-three emissions disclosure requirements threaten to reroute procurement toward regionally processed molasses with verifiable supply chain footprints.
Market Dynamics
The EU Green Deal is hardening feed-grade ingredient standards across member states, compelling livestock nutrition formulators to verify sustainability credentials for molasses-derived inputs. This regulatory pivot is redrawing procurement patterns toward certified natural additives and away from synthetic alternatives.
Growth Catalysts
- EU Green Deal feed mandates:The European Union's push for sustainable feed additives and reduced antibiotic dependency is redirecting procurement toward natural molasses-based solutions across member states.
- Livestock palatability requirements:Cattle and poultry operations are intensifying use of energy supplements and taste enhancers to optimize feed conversion ratios in high-density operations.
- Brazilian beef expansion:Expansive beef and dairy operations in Brazil sustain heavy consumption of dry molasses for both feed and soil amendment applications.
Market Restraints
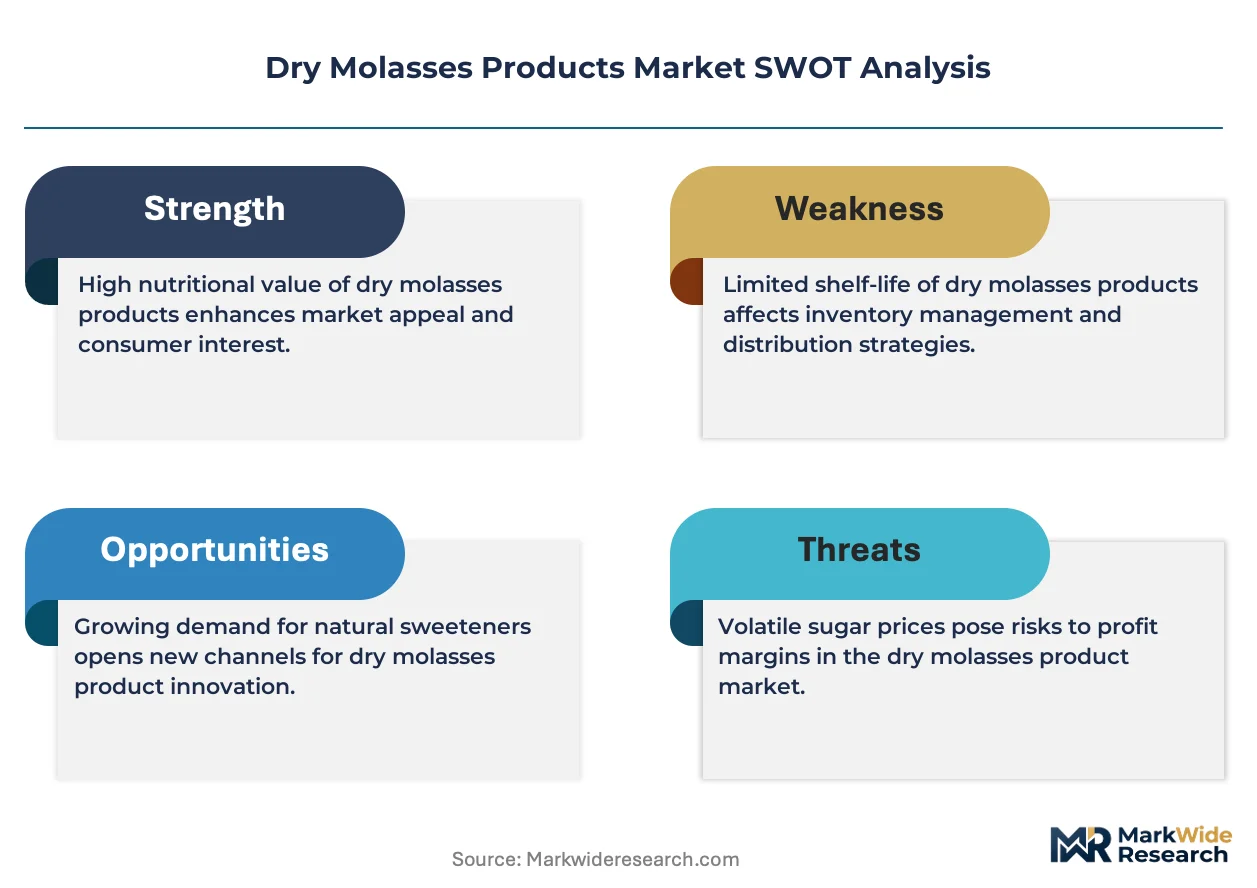
- Sugarcane input volatility:Raw cane sugar price swings and weather-driven harvest variability compress margins for spray-drying and drum-drying processors.
- Brazilian supply concentration:A majority of global cane molasses originates from Brazilian processing facilities, creating geographic single-point vulnerability.
- Synthetic amino acid substitution:Manufactured lysine and methionine products compete directly with molasses as cost-efficient energy sources in poultry rations.
Strategic Opportunities
- Organic certification premium:Certified operations in the European Union and North America enforce strict provenance requirements, creating high-margin positioning for organic dry molasses.
- Soil amendment crossover:Pelletized molasses formulations are penetrating regenerative agriculture programs as microbial fermentation substrates and carbon amendment carriers.
- Carbon accounting disclosure:Scope-three emissions tracking requirements threaten to reroute procurement toward regionally processed molasses with verifiable supply chain footprints.
Industry Challenges
- Multi-jurisdictional compliance burden:Exporters must simultaneously satisfy the Federal Food, Drug, and Cosmetic Act in the United States, European Food Safety Authority feed additive pathways, and Brazil's Ministry of Agriculture sanitary standards.
- Moisture specification precision:Achieving ten to fifteen percent moisture content consistently across batch-scale spray-drying operations demands specialized process engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Molasses Products Market |
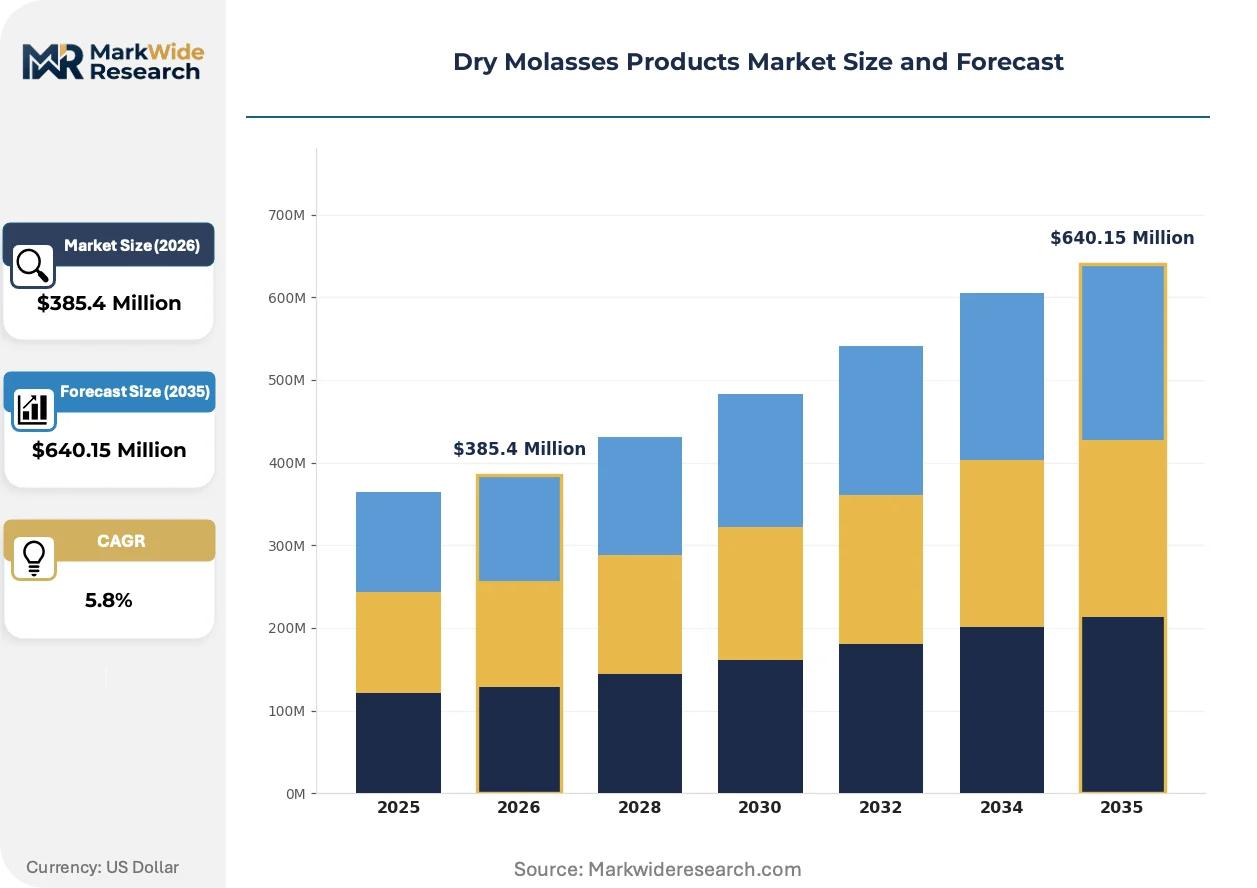
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Syrup Molasses, Organic Dry Molasses, Pelletized Molasses, Powdered Molasses Application: Animal Feed, Food Industry, Nutritional Supplements, Fertilizer End User: Livestock Farmers, Food Manufacturers, Agronomists, Pet Food Producers Distribution Channel: Online Retailers, Agricultural Cooperatives, Wholesalers, Supermarkets |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Bunge Limited, Tereos Group, Louis Dreyfus Company, Zook Molasses Company, Westway Feed Products, Nordzucker AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Molasses Products Market Shifts & Advancements
Processing technology and regulatory disclosure requirements are actively reshaping how dry molasses products are manufactured, certified, and procured across livestock and agricultural end uses.
Drum-drying equipment retrofitted with real-time moisture sensors is decentralizing quality control from centralized laboratories to production lines. Mid-sized Brazilian processors are adopting these systems faster than North American counterparts. This shift is compressing batch rejection rates and enabling just-in-time certification for export shipments.
REACH and the EU Green Deal are tightening documentation requirements for agricultural input carbon footprints. Feed compounders must now trace molasses from cane field to finished premix. European livestock cooperatives are responding by mandating supplier-provided lifecycle assessment data before contract renewal.
Direct contracting between cane processors and large dairy cooperatives is displacing traditional merchant trading structures. Midwestern feed manufacturers now source pelletized molasses through bilateral agreements rather than commodity brokers. This pattern is most visible in Wisconsin and Minnesota, where vertical supply agreements lock in twelve-month pricing windows.
Dry Molasses Products Market Segmentation
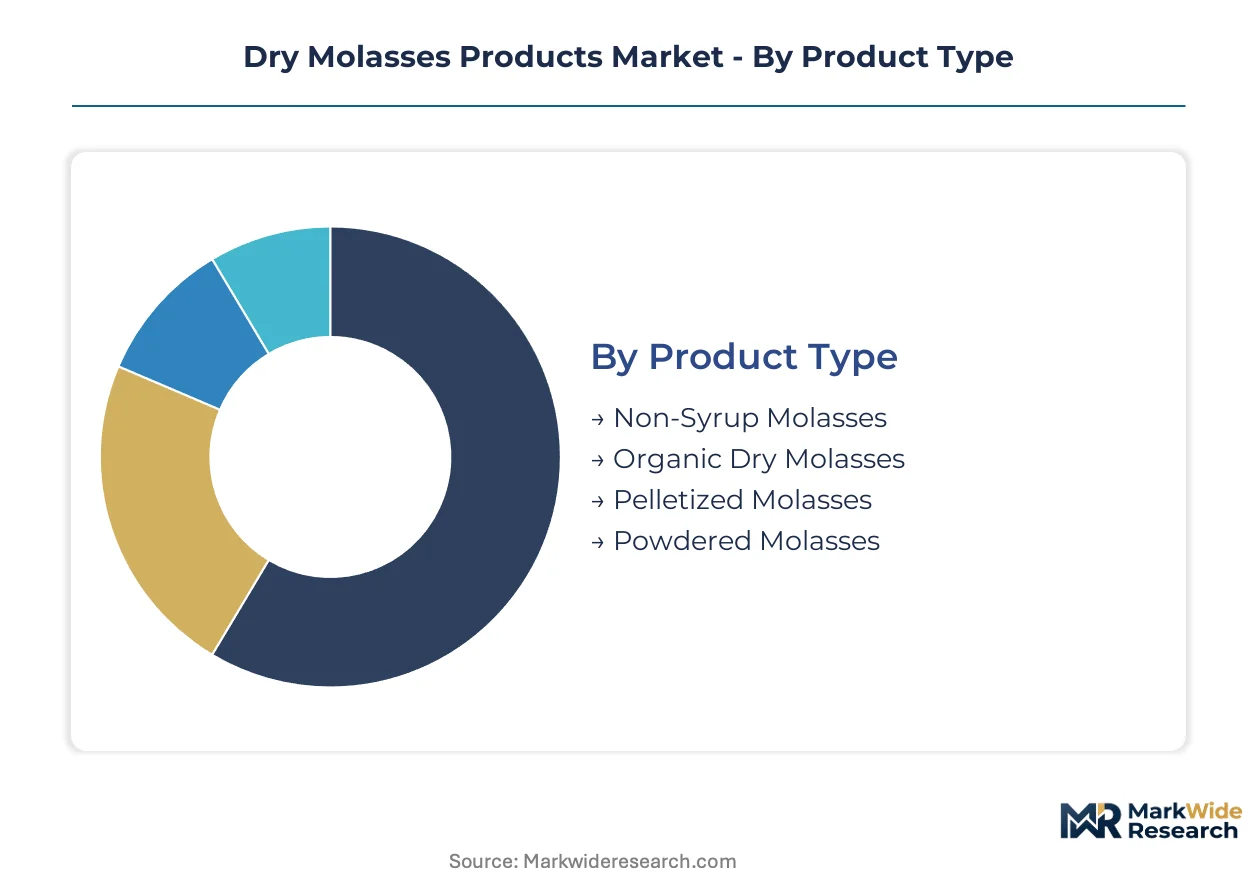
Dry molasses products serve divergent functional requirements across feed, food, and agricultural channels, necessitating precise specification matching. Product form, application intensity, and procurement channel each reshape margin structures and customer loyalty patterns for processors.
Product Type:
Standardization dominates commodity grades while specialty formats command specification premiums.
- Powdered Molasses:Spray-dried or drum-dried to ten to fifteen percent moisture, this free-flowing format integrates uniformly with mineral premixes and bulk feed rations. Demand concentrates in Brazilian beef operations and North American poultry integrators seeking dust-free handling and precise dosing in high-volume mixing systems.
- Pelletized Molasses:Compressed into measured-dose cylinders or spheres with binding agents for controlled release, this format targets equine facilities and specialty livestock segments where dust suppression and ration consistency outweigh per-unit cost premiums.
- Organic Dry Molasses:Certified provenance molasses processed under EU organic regulation and USDA National Organic Program standards occupies narrowing but defensible positioning among European dairy cooperatives.
- Non-Syrup Molasses:Dehydrated variants including flake and granular forms serve industrial fermentation substrates and soil amendment carriers where solubility control matters.
Leading the category by volume: Powdered Molasses. Growing fastest: Pelletized Molasses.
Application:
Feed-grade absorption rates diverge sharply from food and agricultural uses on specification stringency.
- Animal Feed:Palatability enhancement and energy supplementation in cattle, poultry, and swine rations drives the dominant share, with EU Green Deal antibiotic reduction mandates accelerating natural additive substitution.
- Fertilizer:Pelletized and powdered molasses serve as carbon carriers and microbial fermentation substrates in regenerative agriculture programs across Brazil and the Midwestern United States.
- Food Industry:Limited but stable demand for natural sweeteners and browning agents in baked goods and confectionery, constrained by sugar content labeling requirements.
- Nutritional Supplements:Trace mineral delivery and iron fortification applications in human health products face competition from synthetic chelates.
Animal Feed commands the largest volume position. Fertilizer applications are expanding most quickly on soil health program adoption.
End User:
Procurement sophistication varies from cooperative bulk purchasing to specialized formulation requirements.
- Livestock Farmers:Beef and dairy operations in Brazil, Wisconsin, and Minnesota source directly through bilateral supply agreements, displacing traditional merchant intermediaries.
- Food Manufacturers:Bakeries and confectioners require food-grade certification and consistent color specification for browning agent applications.
- Agronomists:Soil amendment specialists in regenerative agriculture networks specify pelletized molasses for carbon amendment protocols.
- Pet Food Producers:Premium pet nutrition formulators use molasses for palatability masking in functional ingredient matrices.
Livestock Farmers dominate procurement volume. Agronomists represent the steepest expansion trajectory on soil carbon program growth.
Distribution Channel:
Channel selection reflects shipment scale, certification verification needs, and price transparency requirements.
- Agricultural Cooperatives:Midwestern dairy and beef cooperatives aggregate member demand for twelve-month supply contracts with Brazilian processors.
- Wholesalers:Traditional merchant traders including Archer Daniels Midland facilitate spot market access for smaller feed compounders.
- Online Retailers:Equestrian and specialty livestock suppliers source small-batch pelletized molasses through digital procurement platforms.
- Supermarkets:Limited retail shelf presence for consumer-packaged molasses supplements and gardening amendments.
Agricultural Cooperatives lead by tonnage throughput. Online Retailers are gaining share fastest among specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors Brazilian cane processing capacity, concentrating spray-drying operations that supply North American feed mills and European compounders. This geographic weight shapes procurement patterns across three continents.
Brazil
Beef and dairy operations in Mato Grosso and Goiás sustain heavy consumption of pelletized molasses for feed rations and soil amendments. Brazil's Ministry of Agriculture enforces sanitary standards for exported molasses products, creating compliance checkpoints at Santos port terminals. São Paulo state processors dominate drum-drying capacity, shipping powdered formats to Midwestern US cooperatives under twelve-month supply contracts.
United States
Wisconsin and Minnesota dairy cooperatives source directly through bilateral agreements with Brazilian suppliers, displacing traditional merchant intermediaries. The USDA and FDA jointly govern molasses labeling under the Federal Food, Drug, and Cosmetic Act, requiring traceability documentation for feed-grade imports. Chicago-based trading desks still facilitate spot market access for smaller compounders lacking direct procurement scale.
Germany
REACH documentation requirements and EU Green Deal mandates redirect procurement toward certified natural additives with verifiable carbon footprints. EFSA evaluates novel molasses applications under updated feed additive authorization pathways, extending approval timelines for new entrants. Hamburg port facilities handle bulk imports for redistribution to Dutch and Danish compounders.
Netherlands
Rotterdam's warehousing infrastructure serves as a consolidation point for EU-bound Brazilian molasses, with specialized handlers managing moisture-sensitive cargo. The EU Green Deal's antibiotic reduction targets accelerate substitution toward palatability enhancers in poultry integrator rations. Agrifirm and other cooperative buyers mandate supplier-provided lifecycle assessment data before contract renewal.
China
Domestic cane processing in Guangxi Zhuang Autonomous Region supplies regional feed manufacturers, though quality variability limits export competitiveness. SAMR feed safety standards govern molasses derivative labeling, with provincial inspectors enforcing moisture content specifications. Yangtze River Delta compounders increasingly specify pelletized formats for precision dosing in swine operations.
Dry Molasses Products Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive cane supply and merchant trading specialists with established logistics networks. Three archetypes dominate: Brazilian processors with backward integration into sugarcane estates, North American feed ingredient distributors with cooperative relationships, and European refiners with organic certification capabilities. Capacity expansion and direct contracting with livestock cooperatives represent the dominant competitive moves, compressing margins for traditional commodity brokers.
Among integrated agribusiness operators, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning across multiple geographies. Cargill leverages its Brazilian cane processing infrastructure to supply North American feed mills, while Archer Daniels Midland dominates merchant trade in dry molasses derivatives. Zook Molasses Company occupies a specialist position, with its Midwestern focus reflecting region-specific formulation requirements for dairy cooperatives in Wisconsin and Minnesota.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Bunge Limited |
| Tereos Group |
| Louis Dreyfus Company |
| Zook Molasses Company |
| Westway Feed Products |
| Nordzucker AG |
| Others |
Supply & Pricing Matrix
Spray-drying process engineers concentrated in São Paulo's industrial corridor command wage premiums that compress margin spreads between standard and organic dry molasses tiers. Labor-cost differentials between Brazilian processing hubs and North American toll-drying facilities amplify pricing stratification across certification grades.
Pricing Analysis
Yield-linked pricing anchors premium tiers, with organic dry molasses commanding substantial markups based on feed conversion ratio improvements in dairy operations. Price differentiation rests on EU organic certification status and bilateral contract volume scale, with spot-market powdered molasses experiencing downward pressure from synthetic amino acid substitution in poultry rations. Large cooperative buyers exhibit lowest price sensitivity due to locked twelve-month supply agreements, while small compounders remain highly responsive to spot-market fluctuations.
Supply Chain Analysis
EU organic regulation and USDA National Organic Program standards gate supplier eligibility, filtering downstream participants by traceability documentation capability. Supply concentrates in Brazil, with secondary processing capacity in the United States and Germany; raw cane sugar, binding agents for pelletization, and moisture-control additives constitute critical inputs. Single-source vulnerability from Brazilian cane harvest variability threatens supply continuity. Distribution runs through agricultural cooperatives for bulk tonnage and merchant traders for spot-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated processors with captive cane supply, as EU Green Deal documentation requirements force merchant traders toward specialization or exit.
For Market Incumbents: Lock in twelve-month bilateral contracts with Midwestern dairy cooperatives before certification renewal cycles. Secure backward integration into Brazilian cane estates to insulate margin structures from raw sugar volatility. Invest in drum-drying equipment with real-time moisture sensors to compress batch rejection rates and defend positioning against synthetic amino acid substitution threats. For New Entrants and Emerging Players: Launch via digital procurement platforms targeting equestrian and specialty livestock segments where pelletized molasses dust-control properties justify premium positioning. Penetrate regenerative agriculture networks in the Midwestern United States with soil amendment formulations. Exploit organic certification gaps in European dairy cooperatives demanding provenance-verified supply. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized Brazilian processors possessing EU organic certification and direct cooperative relationships given carbon accounting disclosure acceleration. Long-term viability favors operators with verifiable scope-three emissions data and bilateral contract books. Monitor EU feed additive authorization pathway decisions as inflection indicators for natural molasses substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cane Estates | Cargill's Brazilian infrastructure demonstrates margin protection against raw sugar price swings. |
| Organic Certification Investment | EU Green Deal mandates redirect procurement toward USDA National Organic Program verified suppliers. |
| Drum-Drying Technology Upgrade | Real-time moisture sensors enable just-in-time certification for export shipments to Hamburg. |
| Direct Cooperative Contracting | Wisconsin and Minnesota dairy buyers now displace Archer Daniels Midland merchant intermediaries. |
| Carbon Footprint Disclosure Program | Lifecycle assessment data mandates from Dutch cooperative buyers reshape supplier qualification criteria. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving feed formulation scientists, Brazilian cane processing plant managers, EU regulatory affairs specialists, and Midwestern cooperative procurement directors. Secondary sources included EFSA feed additive authorization databases, USDA Foreign Agricultural Service trade statistics, Brazil's Ministry of Agriculture export documentation, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up volume modeling and top-down value reconciliation ensured triangulation integrity.
Granularity extended to product-type splits across powdered, pelletized, organic, and non-syrup formats; application-level differentiation between feed, fertilizer, food, and nutritional supplement channels; and end-user segmentation spanning livestock farmers, agronomists, and pet food producers. CAGRs were derived from fitted growth curves across the projection horizon, incorporating sugarcane harvest variability indices and EU antibiotic reduction policy implementation timelines as industry-specific forecast inputs.
Raw cane sugar price volatility, EU Green Deal enforcement intensity, and Brazilian sanitary standard modifications are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding cooperative procurement pattern persistence and synthetic amino acid substitution elasticity. A model refresh is warranted upon material change in EU feed additive authorization pathway timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Immunity Support Ingredients Market
Ingredients
Pea Flour Market
Ingredients
Sunflower Meal Market
Ingredients
Collagen Casings Market
Ingredients
Soy Hydrolysates Market
Ingredients
Organic Virgin Coconut Oil Market
Ingredients
Kairomones Market
Ingredients
North America Malt Ingredients Market
Ingredients
Protein Ingredients Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
North America Sodium Reduction Ingredients Market
Ingredients
Honey Powder Market
Ingredients
Baobab Ingredient Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Rendered Products Market