
 Canola Oil Market | 2026-2036
Canola Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Canola Oil Market Intelligence
Canadian processor investment is broadening crush capacity across Saskatchewan and Alberta. Bunge Limited leverages its North American oilseed infrastructure to secure origination advantages. Cargill Incorporated anchors its position through integrated supply chains spanning farm gate to refinery. Viterra Inc. competes by controlling inland elevator networks that feed western Canadian crush plants.
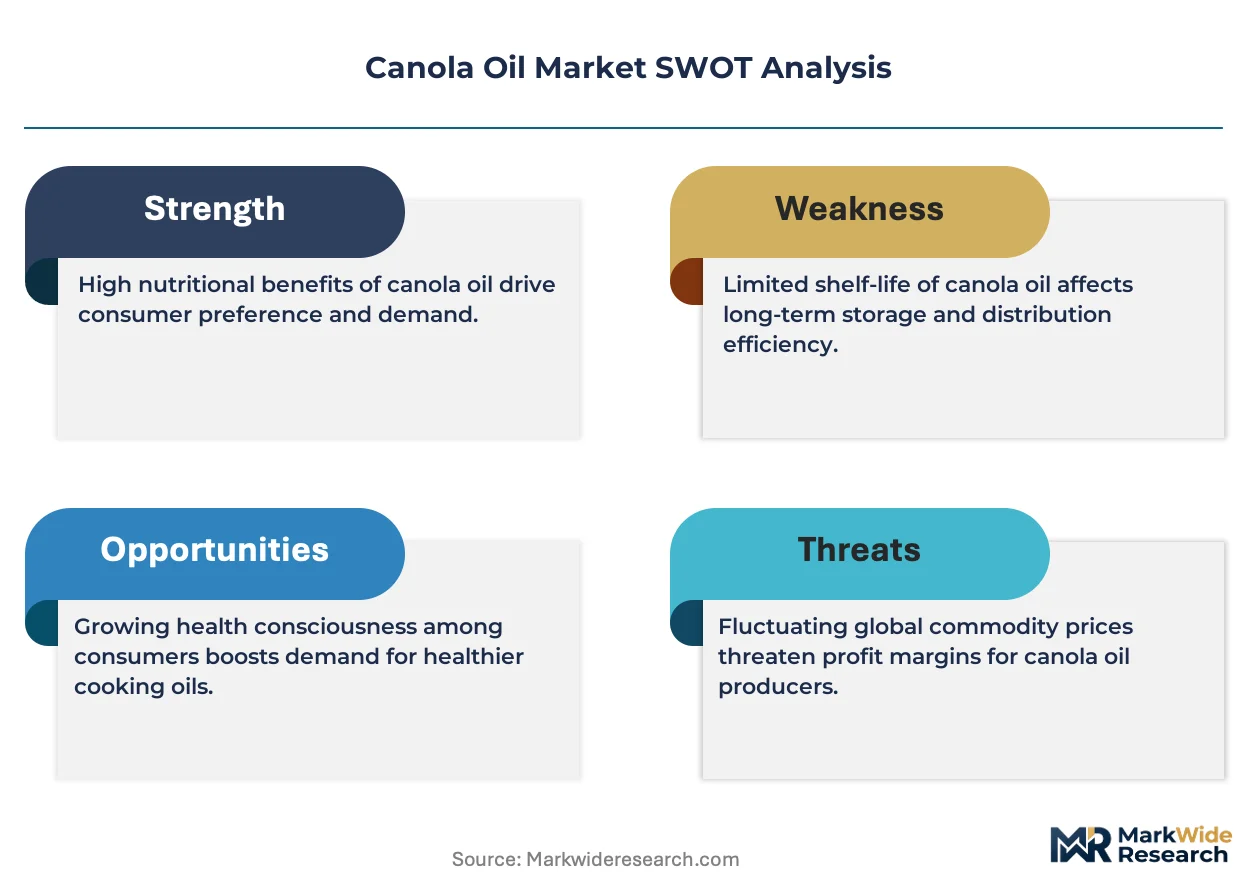
Canola oil is a vegetable oil extracted from rapeseed cultivars bred for low erucic acid and low glucosinolate content, yielding a light-colored oil with a smoke point near 204 degrees Celsius suitable for frying and baking. The oil serves industrial buyers seeking high-oleic formulations for extended fry life in food service operations. Refined canola oil dominates volume flows due to its neutral flavor profile and cost efficiency in bulk food manufacturing. Organic canola oil commands premium positioning as certified non-GMO and cold-pressed variants capture niche health-conscious segments through specialty stores and online retail channels.
Health Canada regulates novel trait approvals for herbicide-tolerant canola varieties, while the USDA oversees oil quality grading and export certification for cross-border trade. The EPA Renewable Fuel Standard shapes biofuel demand by qualifying canola oil as an advanced biofuel feedstock, redirecting crush volumes from food to energy markets. Stakeholders must monitor evolving low-carbon fuel standards and oilseed sustainability certifications that will determine access to premium market tiers.
Market Dynamics
Crush capacity expansion across the Canadian Prairies is tightening seed supply chains and redirecting procurement patterns toward long-term origination contracts with farm cooperatives.
Growth Catalysts
- EPA Renewable Fuel Standard:The regulation qualifies canola oil as an advanced biofuel feedstock, redirecting crush volumes from food applications into renewable diesel production facilities.
- Clean-label frying demand:North American food manufacturers are expanding canola oil procurement for high-heat applications requiring neutral flavor profiles and extended fry stability.
- Health Canada novel food pathway:Accelerated trait-enhanced variety approvals are compressing development timelines for herbicide-tolerant cultivars with improved oil profiles.
Market Restraints
- Seed supply concentration:Canadian Prairies dominance creates origination risk during drought cycles or frost events that damage flowering canola stands.
- Input cost volatility:Nitrogen fertilizer price swings directly impact farm-level planting economics and contracted acreage commitments.
- Soybean oil substitution:Argentine and Brazilian soybean crush expansions offer competing high-oleic oil formulations at volume scale.
Strategic Opportunities
- High-oleic industrial formulations:Extended fry life specifications for food service operations create premium positioning above commodity refined grades.
- Organic certification channel:Cold-pressed non-GMO variants capture specialty retail and direct-to-consumer segments through e-commerce platforms.
- EU Green Deal biofuel mandates:Low-carbon fuel standards in European markets qualify imported canola oil for renewable energy credits.
Industry Challenges
- Plant breeding talent scarcity:Molecular marker-assisted selection expertise concentrates at public research stations and select seed companies.
- Identity preservation infrastructure:Segregated handling systems for trait-specific varieties require elevator network reconfiguration and traceability investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canola Oil Market |
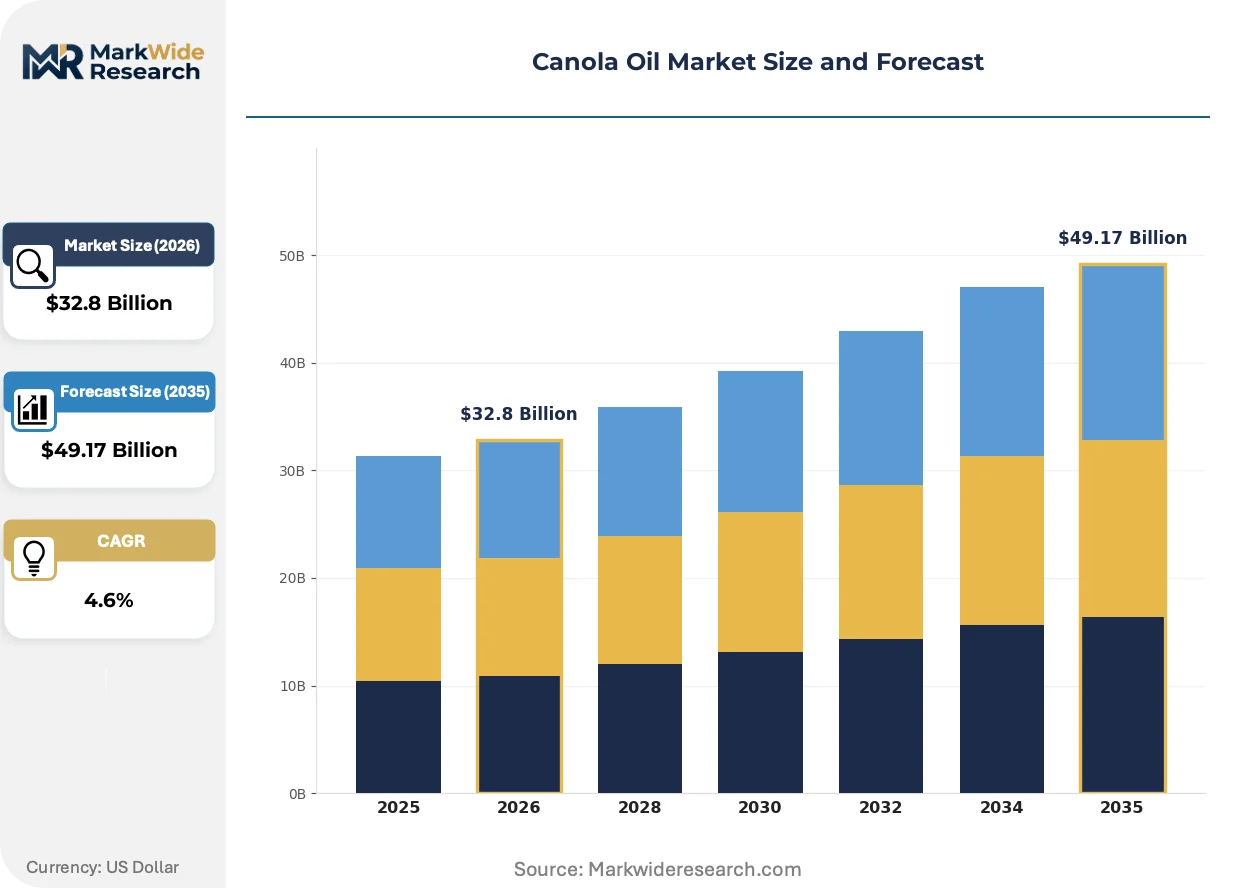
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Canola Oil, Crude Canola Oil, Organic Canola Oil, Cold-Pressed Canola Oil End Use Industry: Food & Beverage, Biofuels, Cosmetics, Animal Feed Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bottles, Bulk Containers, Cans, Tetra Packs |
| Companies Covered | Bunge Limited, CHS Inc., Louis Dreyfus Company, Richardson Oilseed, Viterra Inc., Archer Daniels Midland Company, Wilmar International, COFCO Corporation, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canola Oil Market Strategic Shifts & Innovations
Gene-edited oil profile enhancement and renewable diesel feedstock qualification are compressing traditional boundaries between food and energy markets for canola crush output.
High-oleic canola varieties engineered through CRISPR-Cas9 editing are delivering oxidative stability above 35 hours on the OSI test. Major quick-service restaurant chains in the United States are reformulating fryer systems around these oils to extend oil change intervals. The technology is absorbing volume that previously flowed into partially hydrogenated soybean alternatives, collapsing trans-fat replacement timelines.
Health Canada's updated novel food regulations are streamlining safety assessments for gene-edited traits without foreign DNA insertion. The framework reduces regulatory review periods from 24 months to approximately 12 months for certain categories. Seed developers are prioritizing Canadian regulatory approval as a pathway credential for subsequent submissions to the USDA and other national regulators.
Food manufacturers are consolidating supplier relationships around crush plants offering certified sustainable supply chains. Large buyers are bypassing commodity merchants to contract directly with processor-owned origination networks. This concentration is most pronounced in North American baking and snack manufacturing, where scope three emissions reporting requirements favor vertically integrated traceability.
Canola Oil Market Segmentation
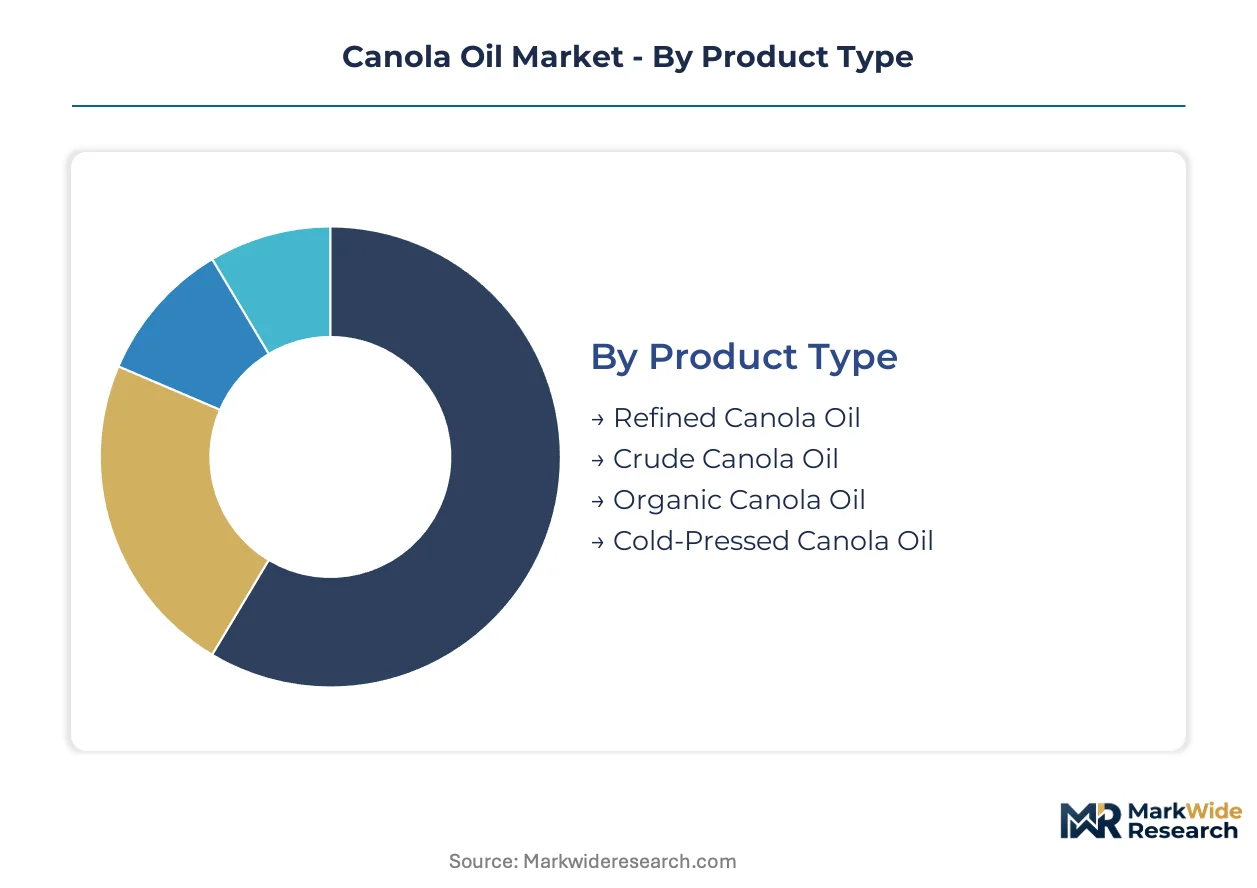
Canola oil segmentation reflects divergent certification burdens across food-grade and industrial applications. EPA biofuel qualification, Health Canada novel food approvals, and USDA organic certification create distinct compliance pathways that reshape procurement economics for each product tier.
Product Type:
Health Canada novel food regulations apply selectively: gene-edited high-oleic varieties face streamlined review, while organic claims require third-party certification to USDA National Organic Program standards.
- Refined Canola Oil:Neutral-flavored oil processed through degumming, neutralization, bleaching, and deodorization stages to achieve smoke points exceeding 204 degrees Celsius. Food manufacturers in the United States concentrate procurement around this grade for high-volume frying operations where extended fry life reduces oil change frequency.
- Organic Canola Oil:Certified non-GMO oil from farms meeting three-year transition requirements and annual third-party audits. Demand concentrates in specialty retail channels across Canadian urban centers where consumers pay premiums for cold-pressed extraction methods and identity-preserved supply chains.
- Crude Canola Oil:Unrefined extraction output requiring further processing before food-grade application.
- Cold-Pressed Canola Oil:Mechanical extraction without solvent use, retaining higher tocopherol content for niche health-positioned products.
Leading the category by volume: Refined Canola Oil. Growing fastest: Organic Canola Oil.
End Use Industry:
Application-specific margins range from commodity biofuel feedstock pricing to premium cosmetic formulations, with regulatory qualification determining market access tiers.
- Food & Beverage:Largest demand sink spanning frying, baking, salad dressings, and margarine production. Quick-service restaurant chains in the United States reformulate fryer systems around high-oleic canola to eliminate partially hydrogenated oils while maintaining oxidative stability above 35 hours.
- Biofuels:EPA Renewable Fuel Standard qualification as an advanced biofuel feedstock redirects crush volumes from food applications into renewable diesel production. Renewable diesel facilities in Louisiana and California anchor procurement for this segment.
- Cosmetics:Emollient applications in skincare formulations leverage canola oil's linoleic acid profile for barrier repair products.
- Animal Feed:Post-crush canola meal supplies protein content for livestock rations, particularly in Prairie province feedlot operations.
Food & Beverage commands absolute volume. Biofuels climbs fastest on renewable diesel capacity expansion.
Distribution Channel:
Channel selection correlates with pack size and certification requirements: bulk wholesale moves undifferentiated refined grades while specialty stores capture organic premiums.
- Wholesale:Tanker-truck and railcar volumes supplying food manufacturers, biofuel refiners, and institutional buyers. Bunge Limited and Cargill Incorporated leverage origination networks to bypass merchant intermediaries for large-account direct contracting.
- Supermarkets:Branded retail bottles and private-label offerings for household consumption. Canadian grocery chains consolidate shelf space around mid-tier refined options with limited organic SKU allocation.
- Online Retail:Direct-to-consumer shipments of cold-pressed and organic variants, bypassing traditional distributor markups.
- Specialty Stores:Health food retailers and organic co-ops serving certification-conscious segments.
Wholesale dominates tonnage. Online Retail expands most quickly on subscription model adoption for specialty grades.
Packaging Type:
Packaging economics align with supply chain distance and contamination risk: short-loop food service favors bulk while export channels require sealed unitization.
- Bulk Containers:Flexitanks and ISO tank containers for intercontinental shipment of refined oil to European renewable diesel facilities and Asian food manufacturers. Tetra Pak and similar aseptic bulk formats reduce oxidation during extended transit.
- Bottles:PET and glass formats for retail household segments, with bottle size stratification across economy, standard, and premium price tiers.
- Cans:Metal packaging for food service and institutional frying applications requiring durability in high-volume kitchen environments.
- Tetra Packs:Aseptic cartons for ambient-stable retail distribution with extended shelf life claims.
Bulk Containers lead by volume. Bottles gain share fastest on private-label retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canadian Prairies anchor worldwide canola seed origination, with Saskatchewan and Alberta crush plants processing over twenty million metric tons annually. Prairie elevator networks feed integrated oilseed complexes that supply North American food manufacturers and renewable diesel refiners.
United States
Midwest food processors drive refined canola procurement for high-volume frying operations. EPA Renewable Fuel Standard qualification redirects crush volumes toward Louisiana and California renewable diesel facilities. Chicago-based oilseed traders coordinate cross-border flows from Canadian Prairie crushing plants.
Canada
Health Canada novel food regulations compress trait-enhanced variety approval timelines from twenty-four months to approximately twelve months. Saskatchewan crush capacity expansion tightens seed supply chains and redirects procurement toward long-term farm cooperative contracts. Calgary and Winnipeg anchor processor headquarters controlling inland elevator networks.
Germany
EU Green Deal biofuel mandates qualify imported canola oil for renewable energy credits in European refining operations. REACH compliance requirements shape import specifications for industrial feedstock applications. Hamburg port terminals handle bulk oil shipments destined for German biodiesel production facilities.
China
State reserve purchasing programs stabilize domestic oilseed prices amid import dependency. NMPA food safety standards govern refined oil labeling and quality grading for retail distribution. Yangtze River Delta crushing plants process imported Canadian seed for food service and packaged goods manufacturing.
Australia
Organic certification demand from Asian export markets drives non-GMO acreage expansion in New South Wales and Victoria. TGA-equivalent state food authorities oversee cold-pressed oil production for health-conscious segments. Melbourne-based specialty oil processors supply direct-to-consumer channels through e-commerce subscription models.
Canola Oil Market Key Industry Players
Global majors compete with regional champions across origination networks and crush capacity deployment. The vendor base stratifies into three tiers: integrated agrib conglomerates controlling farm-to-refinery supply chains, cooperative-owned processors securing local seed flows, and specialty oil packagers serving certified organic channels. Dominant competitive moves include crush plant capacity expansion across the Canadian Prairies and backward integration into farm cooperative origination contracts.
Within the integrated agribusiness tier, Bunge Limited and Cargill Incorporated exemplify scale-driven positioning through North American oilseed infrastructure. Richardson Oilseed occupies a position among regional champions leveraging Prairie province elevator networks. These three anchors illustrate how competitive advantage flows from controlling inland logistics rather than downstream branding.
| Leading Market Players |
|---|
| Bunge Limited |
| CHS Inc. |
| Louis Dreyfus Company |
| Richardson Oilseed |
| Viterra Inc. |
| Archer Daniels Midland Company |
| Wilmar International |
| COFCO Corporation |
| Cargill Incorporated |
| Others |
Cost & Logistics Intelligence
Seed procurement costs cascade through Canadian Prairie crush plants into refined oil pricing tiers, with nitrogen fertilizer volatility at farm level compressing margins for commodity grades while identity-preserved organic streams capture certification premiums downstream.
Pricing Analysis
Certification bundling separates organic cold-pressed variants from unbundled commodity refined grades. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and volume scale. Pricing pressure stems from Argentine soybean oil substitution in high-oleic formulations. Food manufacturers exhibit highest price sensitivity; cosmetics buyers absorb premium spreads for emollient specifications.
Supply Chain Analysis
Workforce availability in Saskatchewan and Alberta crush corridor operations constrains capacity expansion timelines. Supply concentrates in Canada, the United States, and Germany for origination and refining. The chain draws from rapeseed cultivars, nitrogen fertilizer inputs, and renewable diesel offtake agreements. Single-source vulnerability runs through Prairie elevator networks feeding integrated crush plants. Distribution runs through processor-owned origination networks bypassing merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene-edited high-oleic varieties are displacing partially hydrogenated soybean oils in quick-service restaurant fryer systems, compressing trans-fat replacement timelines and redirecting crush volumes toward food service premium tiers.
For Market Incumbents: Lock in long-term origination contracts with Prairie farm cooperatives before crush capacity expansion tightens seed availability. Secure backward integration into identity-preservation infrastructure for trait-specific varieties. Bunge Limited and Cargill Incorporated already anchor positions through elevator network control; laggards face origination displacement.
For New Entrants and Emerging Players: Capture organic certification channel white space through cold-pressed extraction methods and direct-to-consumer e-commerce subscription models. Australian specialty oil processors demonstrate viable archetype for Asian export markets. Target health-conscious urban centers in Canada where consumers pay premiums for non-GMO supply chains.
For Investors and Strategic Acquirers: Health Canada approval timeline compression to twelve months for gene-edited traits is the leading indicator that regulatory pathway efficiency will concentrate value capture among first-mover seed developers. Long-term viability favors integrated origination-to-refinery platforms over standalone crush operators. Watch EPA Renewable Fuel Standard qualification expansion as inflection signal for biofuel feedstock demand redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Crush Capacity Expansion | Saskatchewan and Alberta plant additions tighten seed supply chains and consolidate origination control. |
| Backward Integration | Processor-owned elevator networks bypass commodity merchants for direct farm cooperative contracting. |
| Gene-Edited Variety Development | CRISPR-Cas9 high-oleic strains deliver oxidative stability above 35 hours for extended fry life. |
| Organic Certification Investment | Three-year transition requirements and third-party audits create barrier to specialty retail channel entry. |
| Renewable Diesel Feedstock Qualification | EPA advanced biofuel status redirects crush volumes from food applications to Louisiana and California refiners. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with crush plant operations managers, grain elevator procurement leads, food manufacturer R&D directors, and renewable diesel refinery supply specialists combined with Health Canada novel food submission databases, EPA compliance documentation, and Prairie province agricultural statistics. Bottom-up seed production estimates and top-down oil consumption surveys underwent triangulation validation.
Granularity-level modeling addressed product type, end-use industry, distribution channel, and packaging format dimensions at country-specific resolution. CAGRs were derived through trend extrapolation and driver elasticity assessment across the analysis window. Forecast inputs incorporated crush capacity buildout schedules, gene-edited trait approval timelines, and renewable diesel facility commissioning.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nitrogen fertilizer price cycles, Prairie drought frequency, and EU Green Deal biofuel mandate stringency. Material deviation in EPA Renewable Fuel Standard qualification thresholds or Health Canada novel food pathway revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Phytosterols Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Functional Flours Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Meat Extract Market
Ingredients
Pea Starch Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Elecampane Root Market
Ingredients
Calendula Oil Market
Ingredients
Multi-Grain Premixes Market
Ingredients
North America Agar Market
Ingredients
Europe Potato Protein Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Global Yeast Market
Ingredients
US Ingredients Market
Ingredients
Hops Derivative Market