
 North America Alcohol Ingredients Market | 2026-2036
North America Alcohol Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alcohol Ingredients Market Analytics
Organic certification under USDA National Organic Program standards is redrawing supplier eligibility across the North America Alcohol Ingredients Market. Cargill leverages its grain origination network to anchor malt and starch supply for large-scale brewers. Kerry Group differentiates through its taste modulation technologies, while ADM competes on fermentation-derived specialty ingredients for distilled spirits.
Alcohol ingredients encompass flavorings, sweeteners, preservatives, acidulants, yeasts, enzymes, and colorants formulated to modify taste, stability, appearance, or fermentation performance in alcoholic beverages. These inputs typically specify minimum purity grades, microbial limits, and alcohol solubility parameters to ensure batch consistency and regulatory compliance. Flavorings and sweeteners command the deepest margin pools as beverage brands chase premiumization and reduced-sugar positioning. Extract and liquid forms lead volume in spirits applications, while powder formats gain traction in ready-to-drink cocktail manufacturing for shelf stability.
FDA food additive regulations, TTB labeling requirements for alcohol beverages, and TTB formula approval processes collectively determine which ingredients gain market access and how suppliers must document safety and identity. The FDA's GRAS notification pathway shapes innovation timelines for novel flavor compounds, while TTB formula scrutiny limits rapid formulation changes in distilled products. Stakeholders must monitor pending FDA guidance on natural flavor definitions, as reclassification would force reformulation across beer, wine, and spirits portfolios.
Market Dynamics
The FDA's updated Food Safety Modernization Act traceability mandates are compressing supplier qualification timelines and forcing ingredient distributors to restructure documentation workflows for alcohol additives across the United States, Canada, and Mexico.
Growth Catalysts
- TTB Formula Approval Streamlining:The Alcohol and Tobacco Tax and Trade Bureau's expedited review pathways for GRAS-affirmed ingredients are accelerating new flavor compound introductions in distilled spirits.
- Craft Distillery Expansion:Over 2,800 small-scale producers across the American Southeast are diversifying procurement portfolios beyond commodity inputs toward specialty yeast strains and heritage grain malts.
- Enzyme Efficiency Gains:High-activity glucoamylase formulations are reducing fermentation cycle times by 15-20% in bourbon and whiskey production, driving repeat purchasing from Tennessee and Kentucky operations.
Market Restraints
- Oak Extract Supply Concentration:French and American white oak sourcing is tightening as cooperage competition from premium wine sectors limits extract availability for spirits aging acceleration products.
- Organic Certification Cost Burden:USDA National Organic Program compliance requires 36-month transition timelines for grain suppliers, excluding most conventional maltsters from premium-priced organic beer ingredient contracts.
- Natural Flavor Definition Uncertainty:Pending FDA guidance on natural versus artificial flavor classifications threatens reformulation costs across existing beer, wine, and spirits portfolios if reclassification occurs.
Strategic Opportunities
- Mexican Agave Spirits Vertical:Tequila and mezcal export growth to the United States is creating demand for specialized yeast nutrients and pH stabilizers calibrated to high-sugar agave musts.
- Ready-to-Drink Cocktail Powder Formats:Shelf-stable encapsulated flavor systems are opening manufacturing partnerships with contract canning facilities serving the convenience channel.
- Carbon-Neutral Fermentation Inputs:California's Low Carbon Fuel Standard credit mechanisms are incentivizing brewers to source fermentation-derived ingredients from verified low-emission production pathways.
Industry Challenges
- TTB Formula Scrutiny Delays:Distilled spirits innovators face 90-180 day approval windows for novel ingredient submissions, compressing product development calendars against seasonal launch targets.
- Microbiological Specification Divergence:Inconsistent yeast viability testing protocols between Canadian and American laboratories are generating batch rejection disputes at cross-border ingredient transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alcohol Ingredients Market |
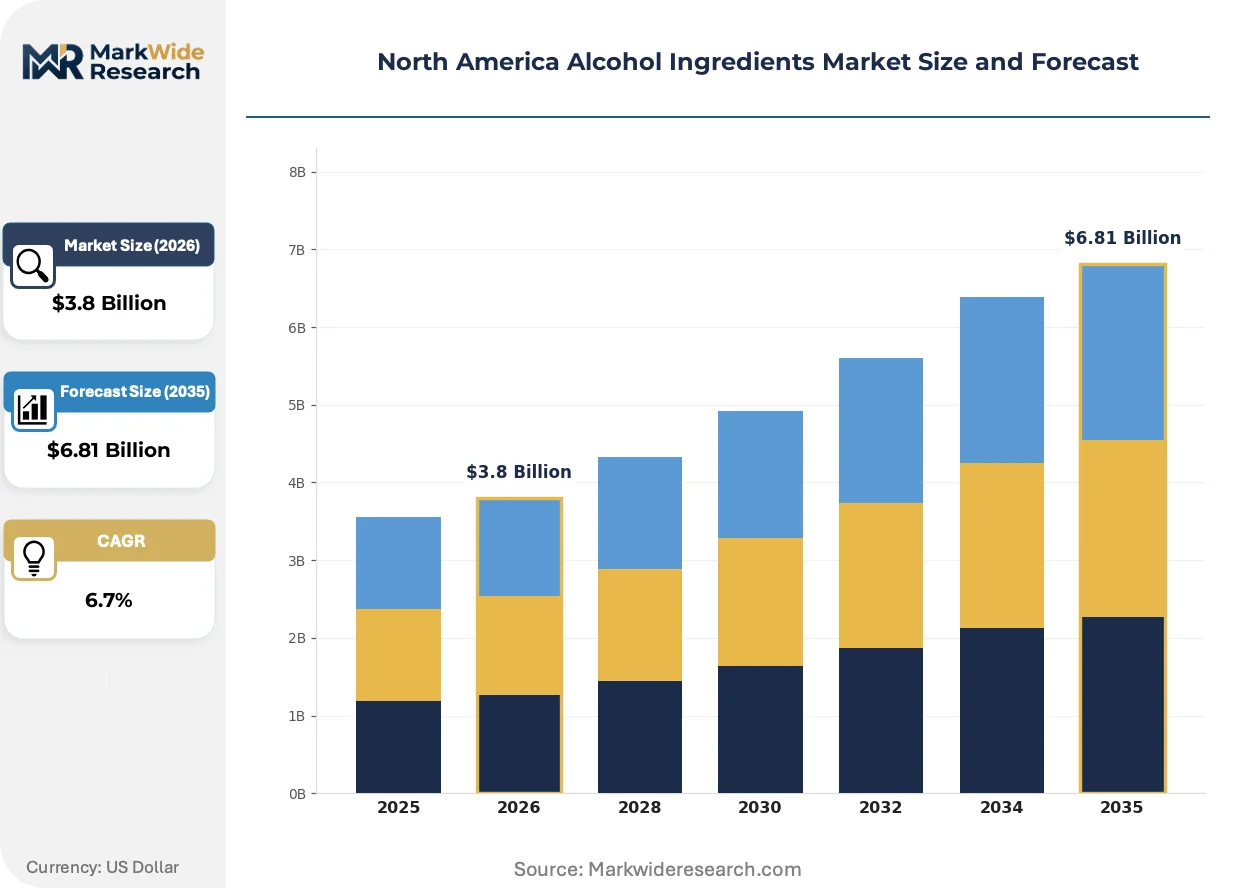
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Flavorings, Sweeteners, Preservatives, Acidulants Application: Beer, Wine, Spirits, Cocktails Form: Liquid, Powder, Granular, Extract End User: Brewery, Distillery, Food Industry, Home Cosumptors |
| Companies Covered | DSM, Sensient Technologies Corporation, ADM, Kerry Group, Dohler Group SE, Cargill, D.D. Williamson & Co. Inc, Tate & Lyle, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alcohol Ingredients Market Evolving Landscape
Precision fermentation platforms and AI-assisted strain development are rewriting yeast and enzyme procurement specifications, while regulatory clarity on natural claims is forcing simultaneous reformulation across multiple beverage categories.
Bioreactor-cultivated specialty yeast strains with targeted ester production profiles are supplanting traditional propagation methods in craft distillery operations. Tennessee and Kentucky bourbon producers are adopting these inputs within 18-month qualification cycles. The technology is compressing flavor development timelines from years to months while reducing dependence on seasonal grain quality variation.
Health Canada's updated Food and Drug Regulations for novel food ingredients are extending safety documentation requirements for fermentation-derived additives entering the Canadian market. This friction is diverting innovation investment toward GRAS-affirmed pathways in the United States. Distilled spirits manufacturers with cross-border distribution are maintaining dual formulation inventories to satisfy divergent approval standards.
Direct-procurement relationships between craft brewers and specialty malt houses are displacing traditional distributor intermediaries in regional supply chains. Pacific Northwest and New England brewing clusters are negotiating multi-year contracts with single-origin barley suppliers. This consolidation of purchasing authority is visible most acutely in Vermont and Oregon, where farm-to-fermenter traceability commands price premiums of 12-18% above commodity alternatives.
North America Alcohol Ingredients Market Segmentation
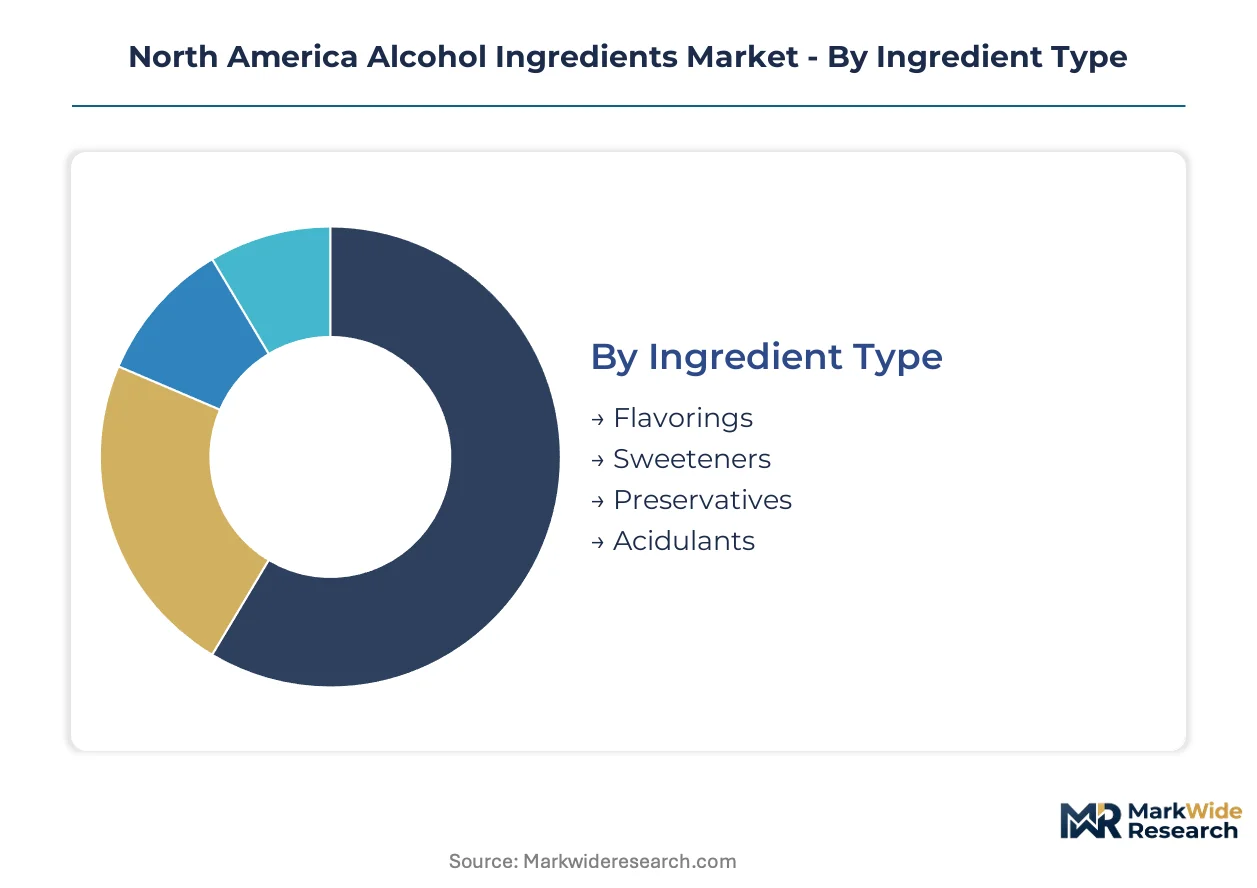
Ingredient specifications diverge sharply across beverage categories in the North America Alcohol Ingredients Market. TTB formula requirements, organic certification thresholds, and shelf-stability demands create distinct procurement profiles for each segment cluster.
Ingredient Type:
Flavorings and sweeteners move predominantly through distributor networks serving large brewers, while preservatives and acidulants flow direct to distillery technical teams managing fermentation control.
- Flavorings:These compounds deliver targeted aromatic profiles through natural extracts, essential oils, and synthesized esters. Bourbon producers in Kentucky and Tennessee source oak-derived vanillin and caramel notes through specialized cooperage suppliers. Demand concentrates where heritage grain malts require complementary flavor layering.
- Sweeteners:Fermentable sugars and non-nutritive alternatives modify mouthfeel and residual sweetness. Craft distilleries across the American Southeast are expanding procurement of honey-based and agave-derived sweeteners for specialty spirit formulations. FDA GRAS notification pathways shape innovation timelines for novel compounds.
- Preservatives:Sulfur dioxide, sorbates, and benzoates extend shelf stability in wine and ready-to-drink applications.
- Acidulants:Tartaric, malic, and citric acids adjust pH balance in fruit-forward spirits and wine coolers.
By volume, flavorings lead. By growth pace, sweeteners are expanding most quickly.
Application:
Cost tier stratification separates commodity-grade inputs for mass-market beer from premium-priced specialty ingredients for aged spirits and craft cocktails.
- Beer:Malt enzymes, hop extracts, and yeast nutrients dominate procurement spend. Large-scale brewers in the Midwest negotiate multi-year contracts for glucoamylase formulations that accelerate fermentation cycles. Organic certification requirements under USDA National Organic Program standards are redrawing supplier eligibility.
- Spirits:Bourbon and whiskey production in Kentucky and Tennessee drives bulk purchases of high-activity enzymes and oak extracts for aging acceleration. Craft distilleries are diversifying toward heritage grain malts and specialty yeast strains with targeted ester profiles.
- Wine:Sulfur management compounds and fermentation aids support vintage consistency across California and Pacific Northwest operations.
- Cocktails:Shelf-stable encapsulated flavor systems are opening manufacturing partnerships with contract canning facilities.
Spirits command the highest ingredient cost per liter. Beer generates the largest absolute procurement volumes.
Form:
Volume economics favor liquid concentrates for distillery tank operations, while powder formats gain traction where transportation costs and shelf stability matter.
- Liquid:Standardized for tank-injection systems at large distilleries. Tennessee and Kentucky bourbon producers favor liquid enzyme concentrates for precise dosing control.
- Powder:Encapsulated flavor systems and dry yeast cultures support ready-to-drink manufacturing and export logistics.
- Granular:Specialized for controlled-release applications in extended fermentation protocols.
- Extract:Oak-derived and botanical concentrates command premium pricing for spirits finishing programs.
Liquid forms dominate current procurement. Powder formats are climbing the fastest as RTD production scales.
End User:
Customer type determines specification rigor, with commercial producers demanding full TTB documentation and microbiological certification that home channels bypass.
- Brewery:Large-scale operators in the Midwest and craft clusters in Vermont and Oregon drive differentiated procurement patterns. Farm-to-fermenter traceability commands price premiums of 12-18% above commodity alternatives in New England and Pacific Northwest markets.
- Distillery:Over 2,800 small-scale producers across the American Southeast are diversifying procurement portfolios beyond commodity inputs. FDA's updated Food Safety Modernization Act traceability mandates are compressing supplier qualification timelines.
- Food Industry:Flavor houses and contract manufacturers source alcohol-soluble extracts for cross-category applications.
- Home Consumers:Homebrew and craft cocktail enthusiasts purchase through specialty retail and direct-to-consumer channels with reduced regulatory documentation requirements.
Commercial breweries and distilleries represent the deepest revenue pool. Home consumer channels are gaining share fastest through e-commerce expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TTB formula approval streamlining and FDA traceability mandates are reshaping procurement patterns across North American alcohol ingredient markets. State-level carbon credit programs in California and federal organic certification requirements in the United States are creating divergent compliance pathways. Cross-border ingredient transfers face heightened documentation scrutiny at Canadian and Mexican customs checkpoints.
United States
Bourbon production in Kentucky and Tennessee drives concentrated demand for high-activity enzymes and oak extracts. The FDA's Food Safety Modernization Act traceability rules compress supplier qualification timelines for alcohol additives. Craft distilleries across the American Southeast diversify procurement portfolios toward specialty yeast strains and heritage grain malts.
Canada
Health Canada's updated Food and Drug Regulations extend safety documentation requirements for fermentation-derived additives entering Canadian markets. British Columbia and Ontario wine operations drive sulfur management compound procurement for vintage consistency. Distilled spirits manufacturers maintain dual formulation inventories to satisfy divergent approval standards.
Mexico
Tequila and mezcal export growth to the United States creates demand for specialized yeast nutrients calibrated to high-sugar agave musts. Mexican regulatory frameworks for Denomination of Origin spirits mandate specific ingredient sourcing documentation. Jalisco and Guanajuato production clusters anchor agave spirits vertical supply chains.
North America Alcohol Ingredients Market Competitive Landscape
Player mix skews toward diversified ingredient conglomerates with fermentation expertise and specialty additive specialists. Market structure concentrates around grain-origination networks and taste-modulation technology portfolios. Three archetypes dominate: integrated agricultural processors, fermentation-derived ingredient specialists, and flavor-house technology licensors. Competitive moves center on backward integration into grain supply and geographic expansion into Mexican agave spirits verticals.
Within the integrated agricultural processor tier, Cargill leverages its grain origination network to anchor malt and starch supply, while ADM competes on fermentation-derived specialty ingredients for distilled spirits. Kerry Group occupies a differentiated position through taste modulation technologies. Among fermentation technology specialists, DSM and Chr. Hansen Holding A/S represent the enzyme and yeast strain development vector. Sensient Technologies Corporation exemplifies the flavor-house archetype with colorant and extract portfolios. Tate & Lyle and Dohler Group SE sit within the sweetener and acidulant specialization cluster.
| Leading Market Players |
|---|
| DSM |
| Sensient Technologies Corporation |
| ADM |
| Kerry Group |
| Dohler Group SE |
| Cargill |
| D.D. Williamson & Co. Inc |
| Tate & Lyle |
| Chr. Hansen Holding A/S |
| Others |
Value Network & Pricing Analysis
Ninety-day supplier qualification cycles under FDA's updated Food Safety Modernization Act compress inventory buffers for Tennessee and Kentucky bourbon producers while amplifying pricing power for pre-qualified specialty yeast and enzyme distributors. This lead-time compression concentrates procurement authority among distributors with established documentation workflows, forcing craft distilleries to absorb premium markups or risk production delays.
Pricing Analysis
Certification level under USDA National Organic Program standards creates the primary spread between commodity malt inputs and premium-priced organic alternatives. Three-tier pricing structure across organic-certified, conventional-grade, and economy-tier inputs dominates contract negotiations. Cost compression in conventional grain supply is intensifying because of drought-driven harvest volatility in the American Midwest. Large-scale brewers in the Midwest exhibit lowest price sensitivity due to volume-scale leverage, while craft distilleries in the American Southeast face highest sensitivity to organic certification premiums.
Supply Chain Analysis
French and American white oak cooperage capacity serves as the critical chokepoint for oak extract availability, constraining spirits aging acceleration product supply. Geographic supply concentration centers on the United States for grain origination, France for cooperage-grade oak, and Mexico for agave-derived inputs. Raw material dependencies include heritage barley varieties, high-activity enzyme formulations, and specialized yeast nutrients. Single-source vulnerability in white oak sourcing generates supply chain risk as premium wine sectors compete for limited cooperage output. Distribution runs through integrated agricultural processors with captive grain origination networks and specialty additive distributors serving craft producer clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against precision-fermentation-derived flavor compounds that threaten traditional botanical and oak-derived extract demand. Incumbents must navigate synthetic biology entrants with targeted ester production capabilities.
For Market Incumbents: Fortify supplier qualification workflows to compress TTB formula approval timelines below competitor benchmarks. Backward integration into heritage grain origination secures volume commitments from Vermont and Oregon craft brewing clusters. Certification investment in USDA National Organic Program compliance locks out conventional maltsters from premium contract pools. Channel control through direct-procurement relationships with craft distilleries displaces distributor intermediaries in regional supply chains.
For New Entrants and Emerging Players: Anchor in Mexican agave spirits verticals where specialized yeast nutrient demand outpaces established supplier presence. White-space targets include pH stabilizers calibrated to high-sugar agave musts and encapsulated flavor systems for ready-to-drink cocktail manufacturing. The most penetrable segment sits in contract canning facility partnerships serving convenience channel distribution. Go-to-market execution should leverage California's Low Carbon Fuel Standard credit mechanisms to differentiate fermentation-derived inputs.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because distributor intermediaries face displacement from direct-procurement trends and traceability mandate compliance costs. Acquisition targets include specialty malt houses with single-origin barley contracts in the Pacific Northwest and New England brewing clusters. The signal to watch is FDA guidance publication on natural flavor definitions, which would force reformulation spending across existing portfolios and reshape ingredient supplier valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heritage Grain Supply | Cargill's grain origination network anchors malt procurement for large-scale brewers seeking volume security. |
| Specialty Yeast Strain Development Partnership | DSM and Chr. Hansen precision fermentation platforms accelerate craft distillery qualification cycles in Tennessee. |
| Organic Certification Program Investment | USDA National Organic Program compliance opens premium-priced contracts excluded from conventional supplier pools. |
| Direct-Procurement Channel Establishment | Farm-to-fermenter traceability commands 12-18% price premiums in Vermont and Oregon brewing clusters. |
| Mexican Agave Spirits Vertical Expansion | Tequila export growth to the United States creates demand for specialized yeast nutrients in Jalisco production hubs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with distillery technical directors, craft brewery procurement managers, specialty malt house operations leads, and TTB compliance officers at distributed spirits manufacturers. Secondary validation drew from FDA GRAS notification filings, TTB formula approval databases, USDA National Organic Program certification records, and American Craft Spirits Association member surveys. Bottom-up volume estimates from individual producer procurement patterns were triangulated against top-down ingredient category spending reported in SEC filings of diversified agricultural processors.
Across the analysis window, the forecasting framework modeled ingredient demand by type, application, form, and end-user category with specific attention to bourbon production volume in Kentucky and Tennessee, craft distillery expansion rates in the American Southeast, and ready-to-drink cocktail manufacturing scale-up. CAGRs were derived from regression analysis against historical procurement volumes and projected beverage production capacity additions. Industry-specific forecast inputs included enzyme efficiency gain adoption curves and oak extract supply constraints from cooperage competition.
Material uncertainties — FDA natural flavor definition reclassification, white oak harvest volatility, and TTB formula approval timeline shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and grain supply continuity that practitioners should keep alternative scenarios live as precision fermentation technology maturity and carbon credit program expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Black Cumin Seed Oil Market
Ingredients
Ximenia Oil Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Egg Albumin Protein Market
Ingredients
Sesame Oil Market
Ingredients
Potato Peel Powder Market
Ingredients
Sunflower Lecithin Market
Ingredients
Asia-Pacific Protein Market
Ingredients
Potato Granules Market
Ingredients
South America Agar Market
Ingredients
Mirepoix Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Canola Meal Market
Ingredients
Europe Agar Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Soluble Fibers Market