
 South Africa Sodium Reduction Ingredients Market | 2026-2036
South Africa Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Sodium Reduction Ingredients Market Analytics
Ingredient formulation services revenue is tilting away from basic salt replacers toward integrated flavor-system design. Cargill Inc leverages its global savory applications portfolio to anchor premium positioning in South African processed meat accounts. Kerry Group competes through localized taste-modulation labs that sustain technical relationships with mid-tier bakery manufacturers. Ajinomoto Co., Inc. differentiates via umami-based sodium reduction technologies that dominate Asian-style sauce applications in the region.
Sodium reduction ingredients comprise functional compounds—potassium chloride, yeast extracts, amino acids, and mineral salts—engineered to replicate sodium chloride's sensory and preservative functions while delivering less than 40 percent of the sodium content per equivalent unit. These ingredients preserve microbial stability, water-holding capacity, and flavor perception in processed matrices where salt serves multiple technical roles. Flavor enhancers command expanding margin pools as manufacturers seek clean-label alternatives to potassium chloride's metallic off-notes. Salt substitutes retain volume leadership across mass-market processed foods and dairy products where cost sensitivity constrains premium ingredient uptake. The health sector channel is accelerating fastest as hospital and institutional foodservice operators face mandatory sodium caps.
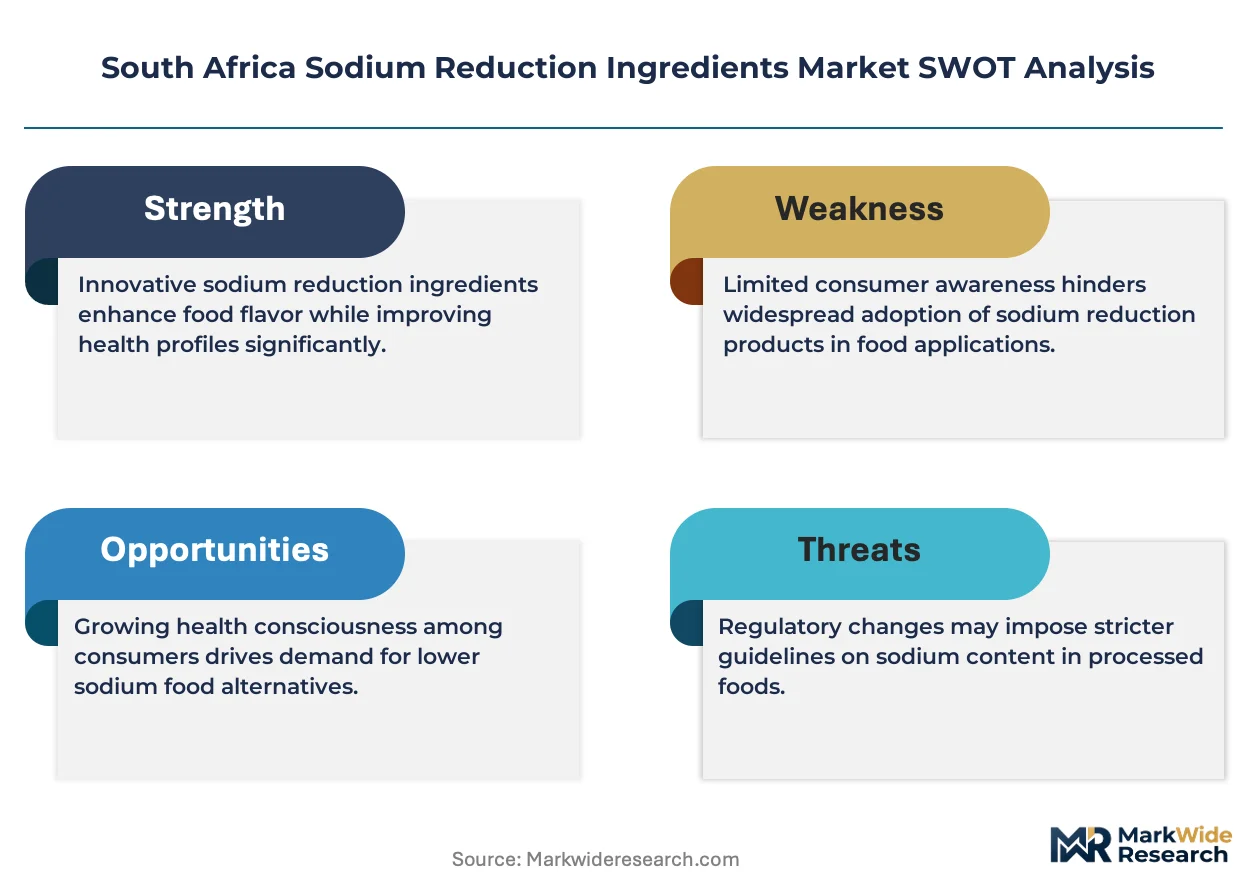
South Africa's Department of Health enforces mandatory sodium limits for bread, cereals, fats, and processed meats through regulations aligned with WHO targets, compressing reformulation timelines for non-compliant manufacturers. The country's national standards regulator verifies label claims and enforces penalties for misrepresented sodium content, tightening market access for imported ingredients without local certification dossiers. SABS standards for food additive safety and the Consumer Protection Act's disclosure requirements collectively elevate technical documentation burdens. Stakeholders must monitor enforcement intensity in provincial health inspectorates and pre-position compliant formulation portfolios before compliance windows narrow.
Market Dynamics
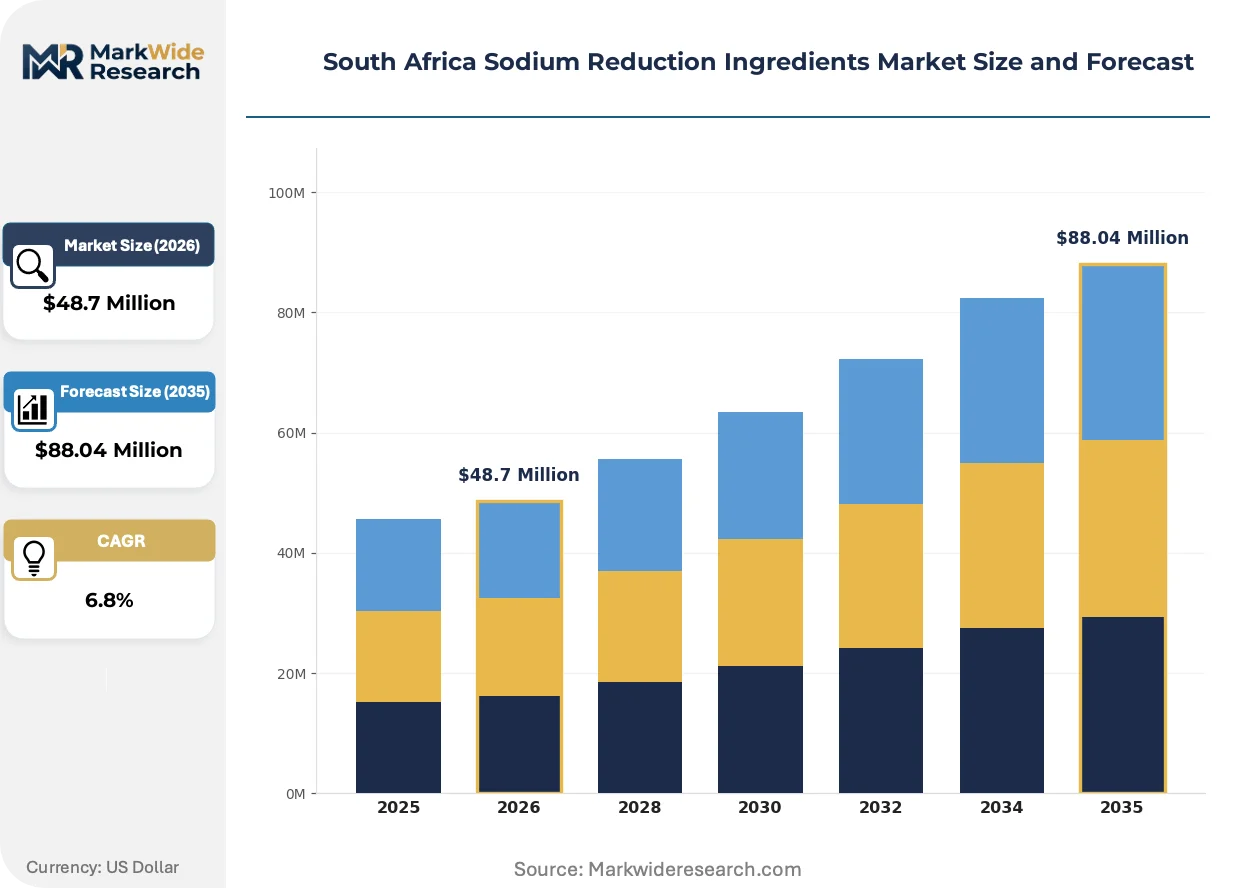
South Africa's sodium reduction ingredients sector is compressing around the Department of Health's mandatory salt limits for bread, cereals, and processed meats, forcing manufacturers to accelerate reformulation timelines or face market exclusion.
Growth Catalysts
- Regulatory enforcement intensity:The Department of Health's WHO-aligned sodium targets for staple foods are tightening compliance windows, compelling bread and processed meat manufacturers to source reduction ingredients immediately.
- Gauteng industrial corridor concentration:Packaged food production clusters in Johannesburg and Pretoria generate concentrated demand for technical formulation support and rapid ingredient supply.
- Yeast extract functionality:Clean-label umami technologies are displacing potassium chloride in premium applications where metallic off-notes previously blocked adoption.
Market Restraints
- Potassium chloride cost volatility:Import dependency for bulk potassium salts exposes formulators to currency fluctuation and shipping cost shocks.
- Flavor system complexity:Multi-component sodium replacers require specialized application labs that mid-tier manufacturers cannot maintain in-house.
- SABS certification timelines:Extended safety dossier reviews for novel mineral salt blends delay product launch windows by 12-18 months.
Strategic Opportunities
- Western Cape wine region expansion:Fermentation-derived flavor enhancers from local yeast processing facilities can supply adjacent food corridors with reduced logistics costs.
- Institutional foodservice channel:Hospital and correctional facility operators face mandatory sodium caps that packaged food manufacturers do not yet serve.
- KwaZulu-Natal sauce manufacturing:Asian-style condiment producers in Durban represent underpenetrated demand for umami-based reduction systems.
Industry Challenges
- Sensory scientist scarcity:Formulators with sodium reduction-specific taste-modulation expertise command premium salaries that fragment technical teams.
- Legacy equipment incompatibility:Existing salt dispersion machinery requires retrofitting to handle hygroscopic potassium chloride without caking or flow interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Sodium Reduction Ingredients Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Preservatives, Nutraceuticals End User: Food Manufacturers, Beverage Producers, Health Sector, Retailers Delivery Mode: Bulk, Retail Packaged, Online, Food Service Application: Processed Foods, Sauces, Snacks, Dairy Products |
| Companies Covered | Cargill Inc, Givaudan SA, Kerry Group, Tate & Lyle PLC, Archer Daniels Midland Company, Salt of the Earth Ltd, Ajinomoto Co., Inc., NuTek Natural Ingredients, DSM NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Sodium Reduction Ingredients Market Evolving Landscape
Flavor technology convergence and regulatory compliance automation are reshaping how South African ingredient suppliers structure their technical service offerings and portfolio priorities.
Integrated savory flavor systems are collapsing the traditional separation between salt replacers and taste enhancers in processed meat applications. Mid-tier sausage and deli meat manufacturers in Gauteng are adopting these pre-blended systems to bypass in-house formulation complexity. The shift is compressing margins for standalone potassium chloride suppliers while elevating value capture for full-system providers.
Automated sodium monitoring and label verification protocols are tightening enforcement of Department of Health regulations across provincial health inspectorates. Manufacturers now deploy real-time sodium testing at production lines to preempt compliance failures. Bread producers in particular are investing in inline spectroscopy to maintain continuous certification readiness.
Buyer concentration among South African retail chains is forcing ingredient suppliers to unbundle technical consulting from product supply. Large supermarket private-label programs now demand standalone formulation audits before awarding sodium-reduced product contracts. This procurement pattern is most visible in Cape Town and Johannesburg, where retailer technical teams directly specify reduction ingredient blends.
South Africa Sodium Reduction Ingredients Market Segmentation
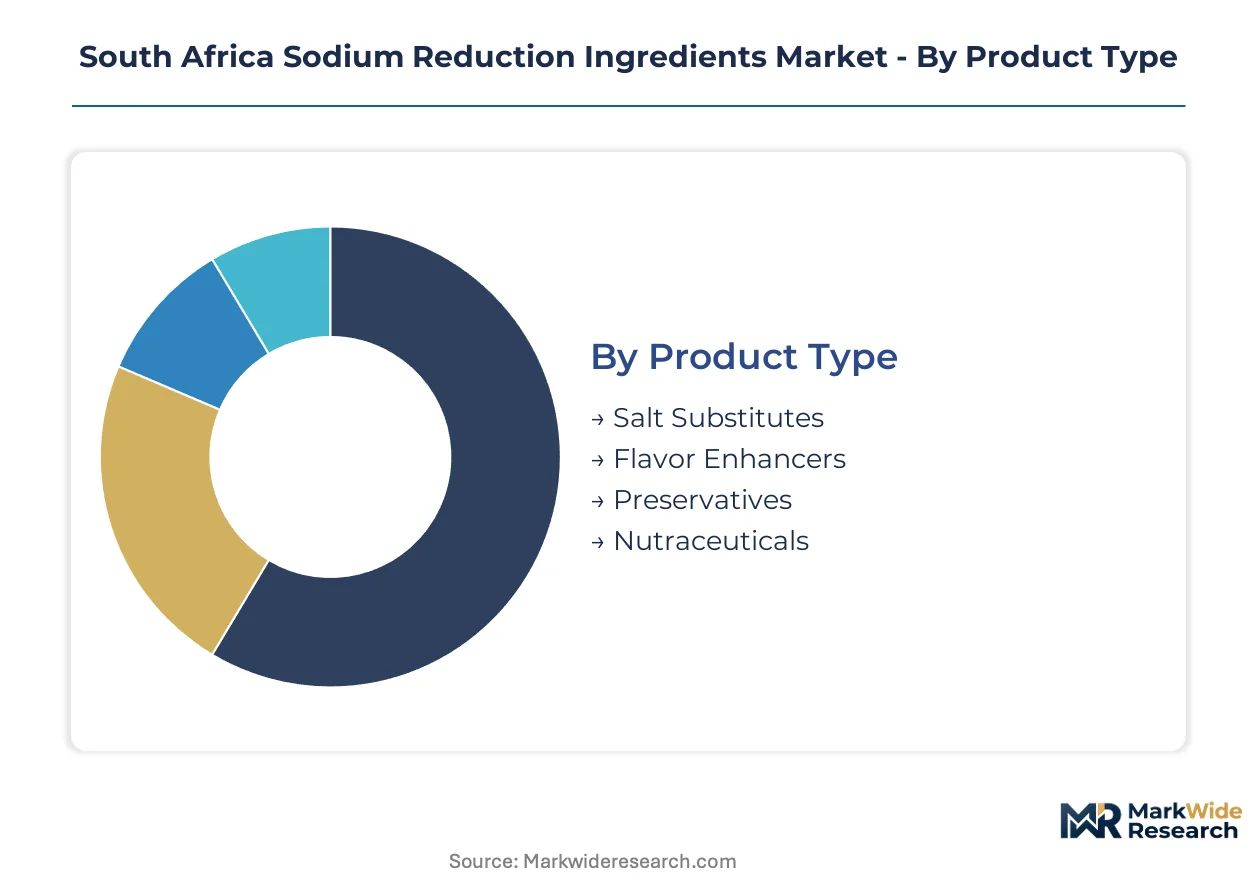
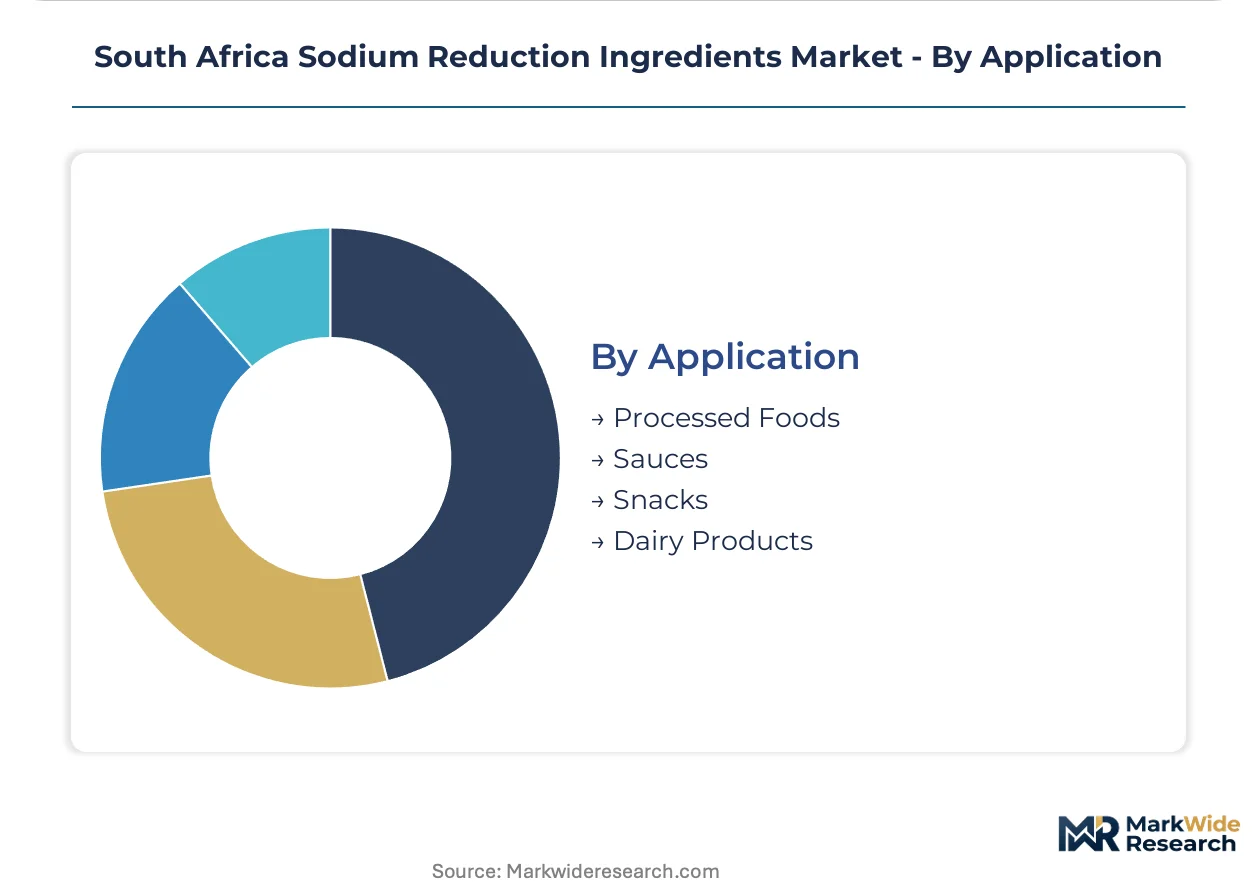
Sodium reduction ingredient procurement in South Africa fragments across technical specification tiers, with after-sales formulation support intensity varying sharply between bulk commodity buyers and integrated flavor-system clients. Manufacturers in Gauteng's industrial corridor demand rapid-response technical service, while institutional buyers prioritize certification documentation over application lab access.
Product Type:
After-sales service intensity escalates from commodity mineral salts through complex multi-component flavor systems, with technical support obligations expanding proportionally to formulation complexity.
- Salt Substitutes:Potassium chloride and mineral salt blends replicate sodium chloride's ionic functionality at 40-60 percent sodium reduction levels. Mass-market bread manufacturers in Johannesburg and Pretoria drive volume procurement, constrained by metallic off-note challenges that limit clean-label positioning.
- Flavor Enhancers:Yeast extracts, amino acids, and umami compounds mask potassium chloride bitterness while delivering sodium-free savory depth. Premium processed meat accounts in Gauteng accelerate adoption as WHO-aligned compliance deadlines compress reformulation windows.
- Preservatives:Low-sodium antimicrobial systems maintain shelf stability in reduced-salt matrices through modified hurdle technology combinations.
- Nutraceuticals:Mineral-fortified sodium replacers target health-conscious retail channels with dual-function positioning.
Salt Substitutes holds the largest share; momentum sits with Flavor Enhancers.
End User:
Cost tier stratification separates formulation-intensive buyers from specification-driven procurement, with technical consulting budgets correlating directly to product development sophistication.
- Food Manufacturers:Bread, processed meat, and dairy producers face mandatory Department of Health sodium caps. Gauteng's industrial corridor concentrates demand for rapid reformulation support as compliance windows narrow.
- Beverage Producers:Sports drinks and functional beverages require electrolyte-balanced sodium reduction without taste compromise.
- Health Sector:Hospital and institutional foodservice operators encounter mandatory sodium caps that packaged food channels do not yet serve, creating underpenetrated demand for compliant ingredient systems.
- Retailers:Private-label programs in Cape Town and Johannesburg now demand standalone formulation audits before awarding sodium-reduced product contracts.
Food Manufacturers dominates procurement volume; Health Sector is climbing the fastest.
Delivery Mode:
Volume concentration determines logistics configuration, with bulk channels serving production-scale buyers and retail-packaged formats addressing formulation trial requirements.
- Bulk:Tanker and tote deliveries serve high-volume bread and meat processing facilities with just-in-time inventory management.
- Retail Packaged:Branded consumer salt replacers target household sodium reduction through supermarket pharmacy channels.
- Online:Direct-to-manufacturer platforms accelerate sample-to-production timelines for mid-tier formulators lacking technical service relationships.
- Food Service:Pre-blended reduction systems supply contract catering operators with standardized sodium compliance.
Bulk commands the greatest throughput; Online is gaining share fastest.
Application:
Application maturity varies by reformulation difficulty, with water-binding requirements in processed meats creating steeper technical barriers than surface-seasoned snack applications.
- Processed Foods:Bread and meat matrices demand multi-functional sodium replacement preserving microbial stability, water-holding capacity, and flavor perception simultaneously. SABS certification timelines for novel mineral salt blends delay product launches by 12-18 months in this category.
- Sauces:Asian-style condiment producers in Durban represent underpenetrated demand for umami-based reduction systems that bypass potassium chloride metallic notes.
- Snacks:Surface-application salt replacers face lower technical barriers than matrix-integrated systems.
- Dairy Products:Fermentation-derived flavor enhancers from Western Cape yeast processing facilities can supply adjacent food corridors with reduced logistics costs.
Processed Foods holds the largest share; Sauces shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's sodium reduction ingredients consumption pattern diverges from developed markets through its heavy reliance on staple food reformulation rather than premium clean-label positioning. Bread and processed meat manufacturers drive procurement volume, while institutional channels remain underdeveloped relative to retail-packaged goods penetration.
Gauteng
Johannesburg and Pretoria host the densest concentration of bread and processed meat production facilities in South Africa. The Department of Health's sodium reduction regulations apply uniform compliance pressure across this industrial corridor. Technical formulation support demand concentrates in Midrand and Rosslyn industrial zones where mid-tier manufacturers lack in-house sensory science capabilities.
Western Cape
Cape Town's retail chain headquarters increasingly dictate sodium-reduced private-label specifications for national distribution. The country's national standards regulator maintains its certification laboratory in Pretoria, but Western Cape manufacturers face identical SABS documentation requirements. Fermentation-derived flavor enhancers from local yeast processing facilities supply adjacent dairy and sauce applications with reduced logistics costs.
KwaZulu-Natal
Durban's Asian-style condiment manufacturing cluster represents underpenetrated demand for umami-based sodium reduction systems. The provincial health inspectorate enforces Department of Health sodium limits with increasing frequency at sauce production facilities. Pietermaritzburg's smaller meat processing sector lags Gauteng in reformulation investment due to thinner technical service relationships.
Eastern Cape
Port Elizabeth's automotive manufacturing dominance leaves food processing infrastructure comparatively underdeveloped for sodium reduction ingredient demand. The provincial industrial development zones prioritize automotive supplier recruitment over food ingredient technical services. Grahamstown's institutional foodservice operations for correctional facilities face mandatory sodium caps that packaged food channels have not yet addressed.
South Africa Sodium Reduction Ingredients Market Competitive Landscape
Capability concentration sits with integrated flavor-system providers; scale advantage sits with bulk mineral salt distributors. The market structure compresses around two tiers: multinational ingredient houses with localized application labs, and regional commodity suppliers dependent on import channels. Strategic archetypes include full-system savory formulators, potassium chloride specialists, and fermentation-derived enhancer producers. Competitive moves center on technical service unbundling for retail chain procurement and backward integration into yeast processing capacity.
Within the multinational integrated tier, Cargill Inc and Kerry Group occupy positions anchored by global savory applications portfolios and localized taste-modulation laboratories respectively. Ajinomoto Co., Inc. represents the fermentation-derived enhancer archetype through umami-based sodium reduction technologies. These three companies exemplify the capability-scale tension: technical sophistication versus supply chain reach.
| Leading Market Players |
|---|
| Cargill Inc |
| Givaudan SA |
| Kerry Group |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Salt of the Earth Ltd |
| Ajinomoto Co., Inc. |
| NuTek Natural Ingredients |
| DSM NV |
| Others |
Value Network & Pricing Analysis
Durban's port corridor freight costs cascade through South African sodium reduction ingredient markets, amplifying price spreads between bulk potassium chloride imports and locally fermented flavor enhancers while Gauteng manufacturers absorb differential logistics burdens.
Pricing Analysis
Contract structures split between long-term offtake agreements for bulk mineral salts and project-based consulting fees for integrated flavor-system design. Price differentiation hinges on SABS certification tier and after-sales formulation support intensity. Cost compression runs through commodity potassium chloride tiers as currency fluctuation erodes importer margins. Mid-tier bakery manufacturers in Johannesburg exhibit highest price sensitivity, while premium processed meat accounts prioritize technical service over unit cost.
Supply Chain Analysis
Extended payment terms from yeast processing facilities in the Western Cape now anchor supplier financing arrangements for fermentation-derived enhancers. Geographic supply concentration draws from China for bulk potassium chloride, India for mineral salt precursors, and domestic Western Cape facilities for yeast extracts. Raw material dependencies rest on potash mining outputs, molasses feedstocks, and amino acid intermediates. Single-source vulnerability permeates potassium chloride channels given South Africa's absence of domestic potash extraction. Distribution runs through Johannesburg bulk terminals serving Gauteng's industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's sodium reduction ingredients sector sits in early-cycle expansion as Department of Health compliance deadlines force staple food reformulation at scale.
For Market Incumbents: Harden technical service relationships with Gauteng bread manufacturers before compliance windows narrow. Deepen backward integration into Western Cape yeast processing capacity to secure captive supply of clean-label enhancers. Cargill and Kerry Group application labs represent defensible moats against potassium chloride specialists.
For New Entrants and Emerging Players: Institutional foodservice operators in Eastern Cape correctional facilities and KwaZulu-Natal hospitals represent the most penetrable entry point given packaged food channel saturation. Asian-style condiment producers in Durban offer adjacent demand for umami-based systems. Direct-to-manufacturer online platforms bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational food ingredient parents seeking to divest non-core African market positions. Five-to-ten year viability hinges on regulatory enforcement persistence rather than consumer preference shifts. Monitor provincial health inspectorate staffing levels as inflection signal for compliance acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Processing | Western Cape fermentation capacity secures supply chain control for clean-label enhancer production. |
| Application Lab Expansion | Midrand technical facilities capture Gauteng manufacturer demand for rapid reformulation support. |
| SABS Certification Fast-Track | Accelerated safety dossier reviews compress 12-18 month approval timelines for novel mineral blends. |
| Institutional Channel Development | Hospital and correctional facility procurement bypasses retail chain buyer concentration. |
| Umami Technology Licensing | Ajinomoto-style amino acid systems penetrate underdeveloped Durban sauce manufacturing cluster. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ingredient procurement managers, sensory scientists, and SABS certification officers; and secondary validation through customs import records, Department of Health regulatory filings, and food manufacturer annual reports. Bottom-up triangulation cross-checked volume estimates against Gauteng industrial corridor production data and top-down expenditure modeling.
Forecast inputs span product type segmentation across salt substitutes and flavor enhancers, end-user channels from packaged food manufacturers to institutional foodservice, and application matrices including bread, processed meat, and sauce categories. CAGRs derive from regression analysis against regulatory compliance timeline intensity and historical reformulation adoption curves. Modeled variables incorporate SABS certification lag effects and potassium chloride price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in rand-dollar exchange rates or shipping cost indices would shift the trajectory. Forecasts reflect documented assumptions about enforcement intensity and manufacturer compliance investment capacity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cheese Ripening Enzymes Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Chickpea Fiber Market
Ingredients
Confectionery Ingredients Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Spelt Flour Market
Ingredients
Dry Molasses Products Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Arachidonic Acid Market
Ingredients
Rice Bran Oil Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Moringa Ingredients Market
Ingredients
Olive Oil Market
Ingredients
Soy Protein Concentrate Market