
 Direct Energy Medical Devices Market | 2026-2036
Direct Energy Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Energy Medical Devices Market Intelligence
Aftermarket service revenue for electrosurgical generators is reshaping profit pools across the Direct Energy Medical Devices landscape. Medtronic leverages its installed base of advanced energy platforms to capture recurring maintenance contracts. Boston Scientific Corporation anchors its position through specialized radiofrequency catheter servicing networks. Karl Storz competes by extending optical-energy hybrid device support into ambulatory settings.
Direct energy medical devices deliver controlled thermal, electrical, or acoustic energy to tissue for cutting, coagulation, ablation, or cosmetic modification, typically operating at frequencies between 300 kHz and 3 MHz for electrosurgical units with active electrode tips measuring 0.5–5 mm in diameter. These instruments serve primarily to reduce blood loss, shorten operative time, and enable minimally invasive access across surgical and aesthetic disciplines. Laser devices dominate capital expenditure budgets in ophthalmology and dermatology practices where precision requirements exclude mechanical alternatives. Electrosurgical devices occupy the highest shipment volumes in general surgery suites across hospital networks. Radiofrequency devices represent the fastest-expanding margin pool as outpatient pain management clinics upgrade from conventional injection therapies.
FDA 510(k) premarket notification requirements govern electrosurgical and radiofrequency device clearance in the United States, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for energy-based surgical tools sold in Europe. The FDA's evolving software-as-medical-device guidance increasingly captures AI-enabled energy delivery algorithms, forcing manufacturers to validate closed-loop control systems. Japan's PMDA enforces separate electrical safety and biocompatibility testing protocols that delay market entry for non-Japanese suppliers. Stakeholders must monitor how dual carbon goals in China reshape manufacturing location decisions for high-energy consumable electrodes.
Market Dynamics
Aftermarket service revenue for electrosurgical generators is reshaping profit pools across the Direct Energy Medical Devices landscape, forcing manufacturers to defend installed base positions through recurring maintenance contracts rather than one-time capital sales.
Growth Catalysts
- EU MDR compliance timelines:Stricter clinical evidence requirements for energy-based surgical tools are accelerating hospital replacement cycles for legacy electrosurgical equipment across German and French hospital networks.
- Radiofrequency catheter adoption:Outpatient pain management clinics in the United States are upgrading from conventional injection therapies to thermal ablation systems, expanding addressable procedure volumes.
- Optical-energy hybrid platforms:Ambulatory surgical centers are integrating laser-electrosurgical combination devices to reduce capital footprint and enable same-day discharge protocols.
Market Restraints
- Tungsten electrode supply concentration:High-purity electrode manufacturing concentrates in Chinese smelting corridors, exposing device makers to input cost volatility and dual carbon policy disruptions.
- FDA software-as-medical-device guidance:Evolving validation requirements for AI-enabled energy delivery algorithms are extending 510(k) clearance timelines and inflating regulatory compliance costs.
- Mechanical surgical instrument substitution:Advanced ultrasonic scalpels and plasma blades compete for vessel sealing applications in laparoscopic suites, compressing electrosurgical market penetration in premium segments.
Strategic Opportunities
- Japan PMDA electrical safety pathways:Dedicated biocompatibility testing protocols for non-Japanese suppliers create first-mover advantages for firms that pre-certify closed-loop control systems.
- Cosmetic laser convergence:Combination radiofrequency-microneedling platforms are capturing dermatology practice revenue previously fragmented across separate capital equipment purchases.
- India PLI scheme alignment:Domestic manufacturing incentives for medical electronics are lowering landed costs for electrosurgical generators serving South Asian hospital procurement.
Industry Challenges
- Biomedical engineer talent scarcity:Specialized expertise in RF impedance matching and tissue thermal modeling remains concentrated among aging technician cohorts in German and Swiss device clusters.
- Legacy generator integration complexity:Hospital IT departments face interoperability failures when connecting new energy platforms to existing electronic medical record systems and surgical scheduling software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Energy Medical Devices Market |
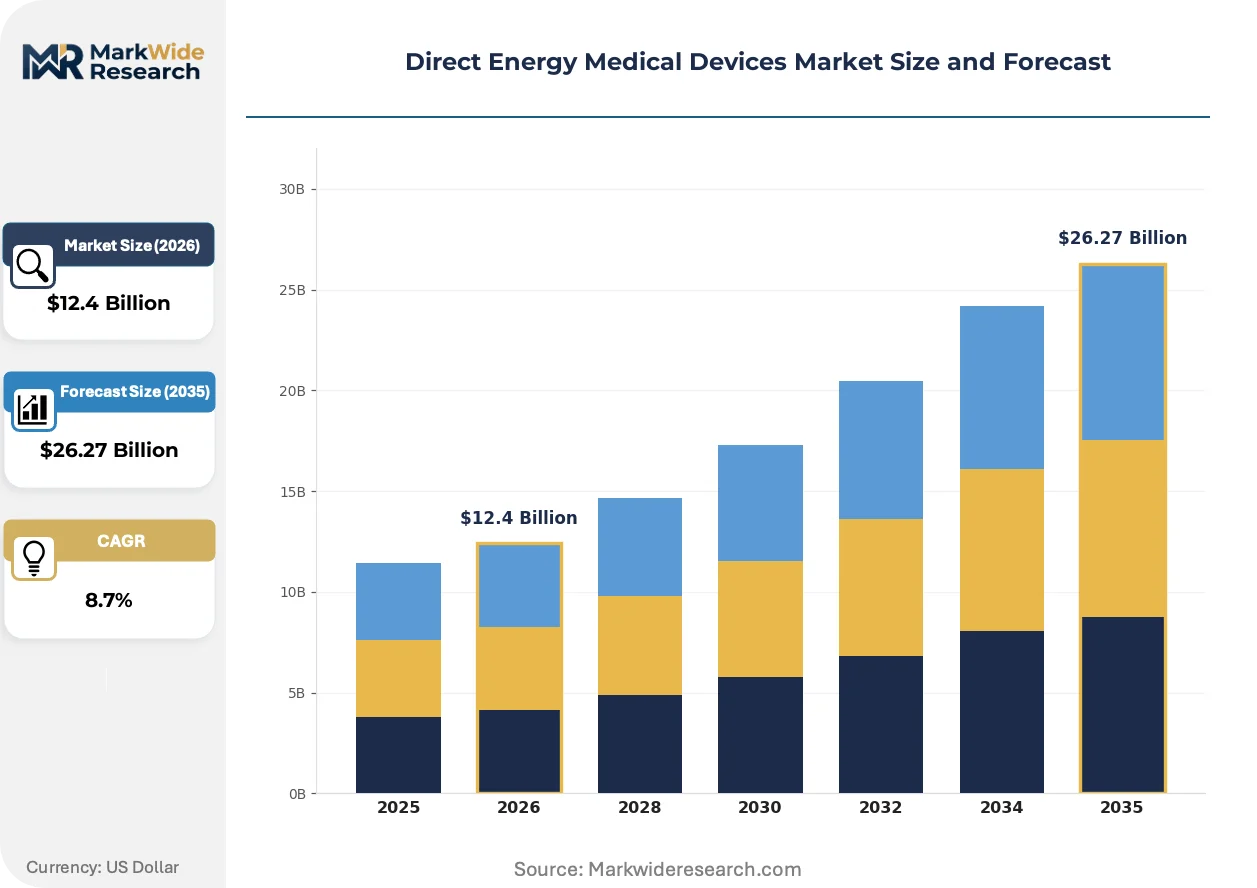
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Devices, Electrosurgical Devices, Radiofrequency Devices, Ultrasound Devices Application: Surgery, Pain Management, Aesthetic Procedures, Dermatology End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Technology: Energy-Based, Non-Energy-Based, Hybrid Systems, Handheld Devices |
| Companies Covered | Medtronic, CONMED Corporation, Boston Scientific Corporation, Ethicon, Olympus Corporation, Stryker Corporation, Karl Storz, B. Braun Melsungen AG, Microline Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Energy Medical Devices Market Strategic Shifts & Innovations
Closed-loop energy delivery algorithms are collapsing the historical trade-off between cutting speed and thermal spread, enabling precision tissue modification without specialized operator skill.
Radiofrequency ablation with real-time impedance monitoring is collapsing the performance gap between experienced and novice operators, allowing community hospitals to adopt complex cardiac and pain management procedures previously restricted to academic medical centers. General surgery suites across United States hospital networks are deploying these systems at accelerated replacement cycles. The technology is collapsing training barriers and expanding addressable physician pools beyond fellowship-trained specialists.
Japan's PMDA electrical safety and biocompatibility testing protocols are extending market entry timelines for non-Japanese suppliers while creating protected domestic windows for local manufacturers. Device firms must duplicate validation studies under JIS standards separate from IEC baselines, inflating regulatory capital requirements. Radiofrequency catheter manufacturers targeting Japanese pain management clinics are responding by establishing Yokohama-based regulatory affairs subsidiaries to compress approval cycles.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, forcing electrosurgical generator manufacturers to compete on transparent maintenance pricing rather than bundled lifetime cost models. Independent service organizations are capturing calibration and electrode replacement revenue previously captive to original equipment makers. This disintermediation is most visible in German outpatient surgical networks where procurement centralization has standardized three-year total cost of ownership evaluation frameworks.
Direct Energy Medical Devices Market Segmentation
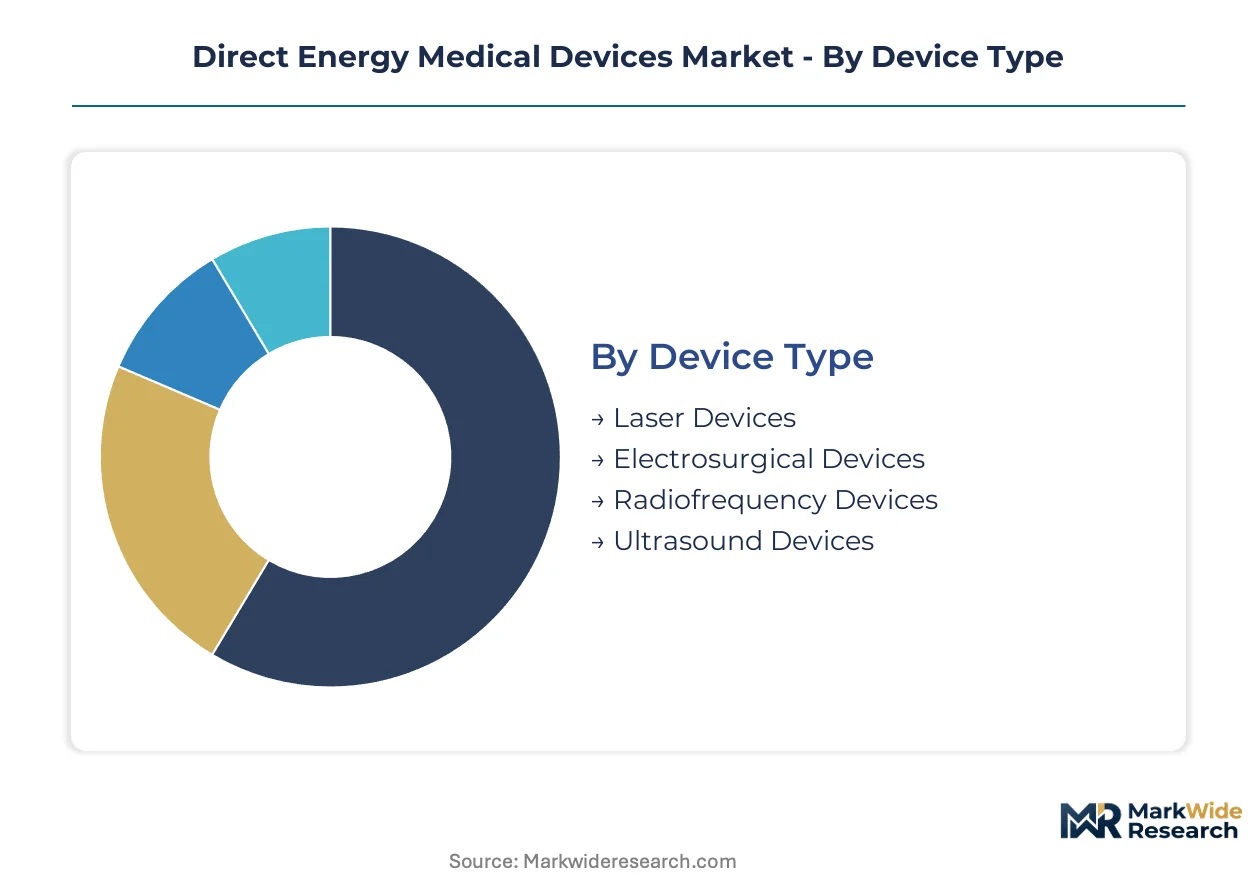
Aftermarket service intensity varies sharply across device configurations in the Direct Energy Medical Devices landscape. Procurement departments evaluate total cost of ownership differently for capital-heavy laser platforms versus consumable-dependent electrosurgical systems.
Device Type:
After-sales service contracts concentrate around electrosurgical generators with their recurring electrode and maintenance requirements, while laser devices demand less frequent but higher-value optical component replacement.
- Electrosurgical Devices:These instruments operate at frequencies between 300 kHz and 3 MHz with active electrode tips measuring 0.5–5 mm in diameter. German hospital networks are accelerating replacement cycles as EU MDR compliance deadlines approach for legacy equipment.
- Radiofrequency Devices:Thermal ablation systems with real-time impedance monitoring enable precise tissue modification. United States outpatient pain management clinics are upgrading from conventional injection therapies, expanding addressable procedure volumes beyond academic medical centers.
- Laser Devices:Capital expenditure dominance in ophthalmology and dermatology practices where precision requirements exclude mechanical alternatives.
- Ultrasound Devices:Acoustic energy delivery for tissue fragmentation and hemostasis in urological and orthopedic applications.
By volume, Electrosurgical Devices lead. By growth pace, Radiofrequency Devices are expanding most quickly.
Application:
Cost tier differentiation separates high-acuity surgical applications from elective aesthetic procedures, with reimbursement structures dictating capital allocation priorities.
- Surgery:General surgery suites across hospital networks deploy electrosurgical units for cutting and coagulation to reduce blood loss and shorten operative time. German and French hospital procurement centralization is standardizing three-year total cost of ownership frameworks.
- Pain Management:Radiofrequency ablation systems are displacing conventional injection therapies in community settings. Real-time impedance monitoring collapses training barriers, allowing adoption beyond fellowship-trained specialists.
- Aesthetic Procedures:Combination radiofrequency-microneedling platforms capture dermatology revenue previously fragmented across separate capital purchases.
- Dermatology:Laser precision requirements dominate where mechanical alternatives fail.
Surgery generates the highest absolute revenue. Pain Management is climbing the fastest as outpatient volumes expand.
End User:
Customer type determines procurement sophistication, with hospital networks leveraging scale for service unbundling while ambulatory centers prioritize capital footprint reduction.
- Hospitals:Large-scale procurement departments unbundle after-sales service contracts from capital equipment purchases. IT interoperability demands with electronic medical record systems complicate new energy platform integration.
- Ambulatory Surgical Centers:Optical-energy hybrid platforms reduce capital footprint and enable same-day discharge protocols. These facilities drive fastest adoption of combination laser-electrosurgical devices.
- Clinics:Outpatient pain management settings upgrade thermal ablation capabilities from conventional injection therapies.
- Research Institutions:Early evaluation of closed-loop energy delivery algorithms and AI-enabled control systems.
Hospitals dominate installed base. Ambulatory Surgical Centers are gaining share fastest as procedure migration accelerates.
Technology:
Maturity curves separate established energy-based modalities from emerging hybrid architectures, with regulatory validation requirements widening competitive moats.
- Energy-Based:Established thermal, electrical, and acoustic energy delivery systems governed by FDA 510(k) and EU MDR frameworks. Tungsten electrode supply concentration in Chinese smelting corridors exposes manufacturers to input cost volatility.
- Hybrid Systems:Laser-electrosurgical combinations integrate multiple energy modalities. Ambulatory surgical centers adopt these to reduce capital footprint and enable same-day discharge protocols.
- Non-Energy-Based:Mechanical alternatives including advanced ultrasonic scalpels and plasma blades competing for vessel sealing applications.
- Handheld Devices:Portable configurations for point-of-care and field applications.
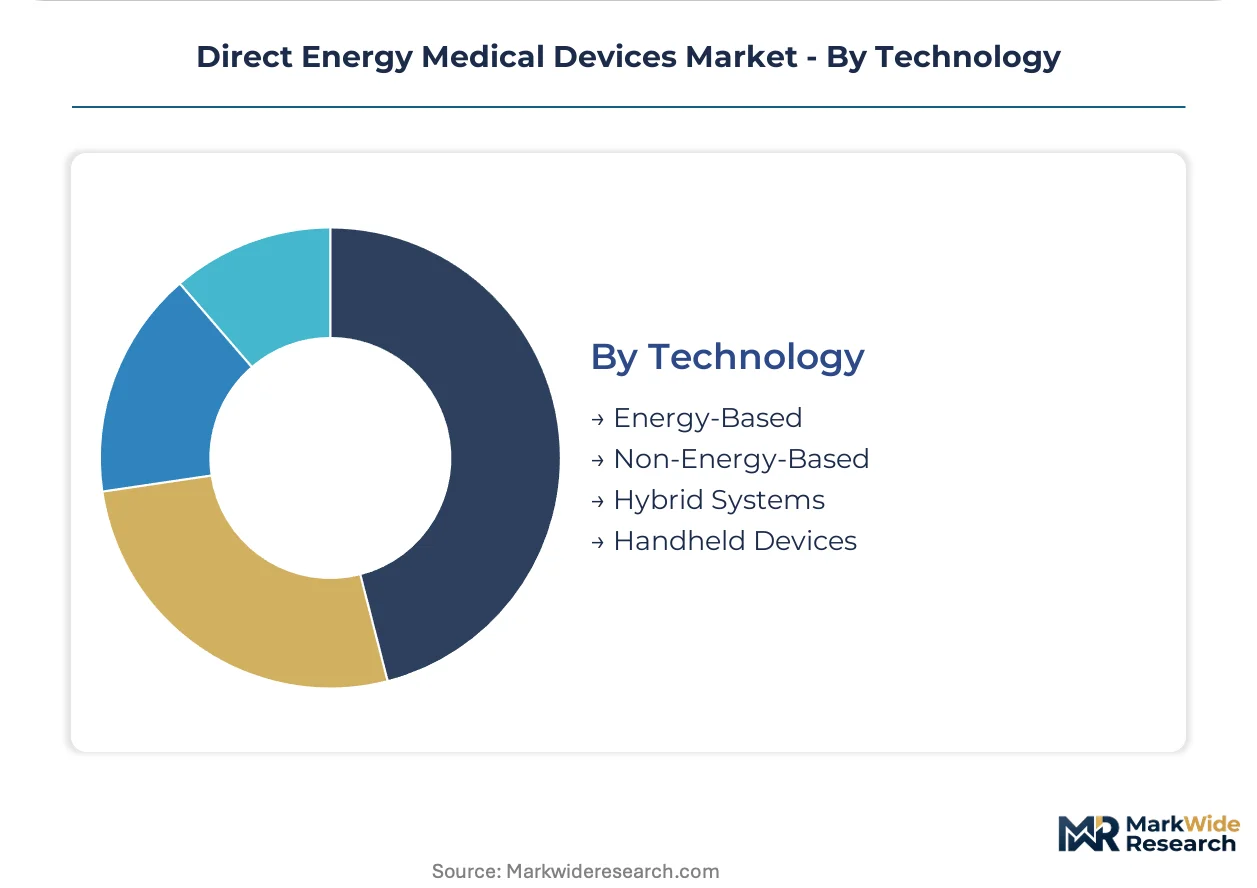
Energy-Based technology holds the largest installed base. Hybrid Systems show the steepest expansion trajectory as ambulatory adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement departments demonstrate the lowest price elasticity for electrosurgical platforms, while Indian public health tenders exhibit acute sensitivity to landed equipment costs. United States outpatient clinics occupy the middle ground, balancing reimbursement rates against total cost of ownership calculations.
United States
Outpatient pain management clinics are upgrading thermal ablation capabilities from conventional injection therapies. FDA software-as-medical-device guidance is extending 510(k) clearance timelines for AI-enabled energy delivery algorithms. Boston Scientific Corporation anchors specialized radiofrequency catheter servicing networks across the Midwest and Southeast surgical corridors.
Germany
Hospital networks are accelerating replacement cycles for legacy electrosurgical equipment as EU MDR compliance deadlines approach. The EU Medical Device Regulation mandates clinical evidence and post-market surveillance for energy-based surgical tools. Procurement centralization in Bavaria and North Rhine-Westphalia has standardized three-year total cost of ownership evaluation frameworks.
China
Dual carbon goals are reshaping manufacturing location decisions for high-energy consumable electrodes. The National Medical Products Administration enforces GB standards separate from IEC baselines for electrical safety testing. Tungsten electrode smelting concentrates in central Chinese industrial corridors, exposing device makers to input cost volatility.
Japan
Pain management clinics are adopting radiofrequency ablation systems with real-time impedance monitoring. The Pharmaceuticals and Medical Devices Agency enforces JIS standards for electrical safety and biocompatibility testing that delay market entry for non-Japanese suppliers. Yokohama-based regulatory affairs subsidiaries are compressing approval cycles for foreign catheter manufacturers.
India
Domestic manufacturing incentives under the Production Linked Incentive scheme are lowering landed costs for electrosurgical generators. The Central Drugs Standard Control Organization regulates medical device imports through licensing requirements. Maharashtra and Gujarat medical electronics clusters are capturing South Asian hospital procurement through localized assembly operations.
Direct Energy Medical Devices Market Key Industry Players
Integrated device conglomerates and specialized surgical technology firms split the market between installed base leverage and targeted clinical application depth. Consolidation pressures favor players with captive servicing networks capable of capturing recurring maintenance revenue. Three archetypes dominate: diversified medtech conglomerates with broad energy portfolios, focused electrosurgical specialists with regional density, and optical-energy hybrid innovators serving ambulatory migration. Competitive moves center on unbundling after-sales service contracts from capital sales and establishing Yokohama or Singapore regulatory subsidiaries to compress Asian approval timelines.
Within the diversified conglomerate tier, Medtronic and Boston Scientific Corporation exemplify installed base strategies that prioritize recurring maintenance contracts over one-time equipment sales. CONMED Corporation occupies a position among mid-scale surgical technology specialists with concentrated presence in North American hospital networks. Karl Storz represents the optical-energy hybrid archetype, extending device support into German and French ambulatory surgical settings where capital footprint reduction drives procurement decisions.
| Leading Market Players |
|---|
| Medtronic |
| CONMED Corporation |
| Boston Scientific Corporation |
| Ethicon |
| Olympus Corporation |
| Stryker Corporation |
| Karl Storz |
| B. Braun Melsungen AG |
| Microline Surgical |
| Others |
Cost & Logistics Intelligence
Undercapacity in high-purity tungsten electrode smelting across central Chinese industrial corridors is compressing supplier margins while amplifying pricing power for integrated device manufacturers with captive raw material positions. This utilization imbalance feeds directly into procurement negotiations, with hospital networks demanding longer service contract lock-ins to offset volatile consumable electrode costs.
Pricing Analysis
After-sales service contracts and recurring electrode replacement programs generate the dominant share of lifetime value across electrosurgical generator portfolios. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with closed-loop algorithms from legacy EU MDR transitional equipment and unbundled service offerings. Pricing pressure stems from procurement centralization in German hospital networks standardizing three-year total cost of ownership evaluations. Ambulatory surgical centers exhibit acute price sensitivity due to capital footprint constraints, while academic medical centers demonstrate lower elasticity for advanced energy platforms with training support.
Supply Chain Analysis
High-purity tungsten feedstock concentrates in Chinese smelting corridors, with secondary refining capacity anchored in Germany and Japan. Electrosurgical generator manufacturing draws from tungsten electrodes, ceramic insulators, and RF impedance matching components. Single-source vulnerability in Chinese tungsten concentrate exposes device makers to dual carbon policy disruptions and export license volatility. Distribution runs through hospital procurement departments, GPO contracts managers, and specialized surgical device distributors serving ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against advanced ultrasonic scalpels and plasma blade systems capturing vessel sealing applications in premium laparoscopic suites. Incumbents must fortify positions before mechanical alternatives erode electrosurgical penetration in high-margin surgical segments.
For Market Incumbents: Build captive servicing network moats by acquiring independent service organizations in German outpatient surgical corridors before procurement unbundling accelerates. Anchor installed base positions through RF impedance matching expertise and closed-loop algorithm validation investments that mechanical substitutes cannot replicate. Defend against ultrasonic scalpel substitution by embedding electrosurgical platforms into hospital IT infrastructure, complicating rip-and-replace decisions.
For New Entrants and Emerging Players: Build out regulatory affairs subsidiaries in Yokohama to compress PMDA approval cycles for radiofrequency catheter manufacturers targeting Japanese pain management clinics. Target underpenetrated community hospital settings in the United States Midwest where real-time impedance monitoring collapses training barriers for thermal ablation adoption. Pursue software-as-medical-device pre-certification pathways ahead of FDA guidance solidification to establish first-mover positioning in AI-enabled energy delivery.
For Investors and Strategic Acquirers: Capital is best deployed toward optical-energy hybrid innovators with ambulatory surgical center density and recurring maintenance contract visibility. Long-term viability hinges on manufacturers capturing service revenue disintermediation from original equipment makers as procurement centralization advances. Monitor FDA software-as-medical-device guidance finalization as the inflection signal for regulatory compliance cost escalation and competitive consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for AI-enabled energy delivery algorithms before guidance tightens validation requirements. |
| EU MDR Compliance Pathway | Preserves German and French hospital network access as legacy equipment replacement cycles concentrate. |
| Hospital System Partnership | Locks in three-year total cost of ownership contracts against independent service organization competition. |
| Software Companion Development | Captures closed-loop control system validation for electronic medical record interoperability demands. |
| Reimbursement Strategy | Aligns thermal ablation coding with outpatient pain management clinic upgrade incentives. |
Research Approach
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at device manufacturers, then refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up modeling of installed base replacement cycles and electrode consumption rates was cross-checked against top-down market sizing from capital equipment shipment data and service contract value pools.
Demand-supply balance modeling across the projection horizon incorporated procedure volume migration from inpatient to ambulatory settings, EU MDR compliance deadline impacts on replacement timing, and tungsten electrode supply concentration risks. Segmentation dimensions included device type, application specialty, end-user facility tier, and technology maturity curve. CAGRs were derived from weighted average of historical replacement cycle compression and forward-looking ambulatory adoption rates, with RF catheter growth assumptions stress-tested against pain management clinic expansion trajectories.
Stress conditions across Chinese dual carbon policy enforcement severity, FDA software-as-medical-device guidance finalization timing, and ultrasonic scalpel substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement stability and tungsten supply continuity. Cross-checking against hospital capital budget disclosure patterns and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Telehealth Device Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Europe Ventilator Market
Medical Devices
Global Nebulizers Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Surgical Helmet Systems Market