
 North America Smart Medical Devices Market | 2026-2036
North America Smart Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Medical Devices Market Insights
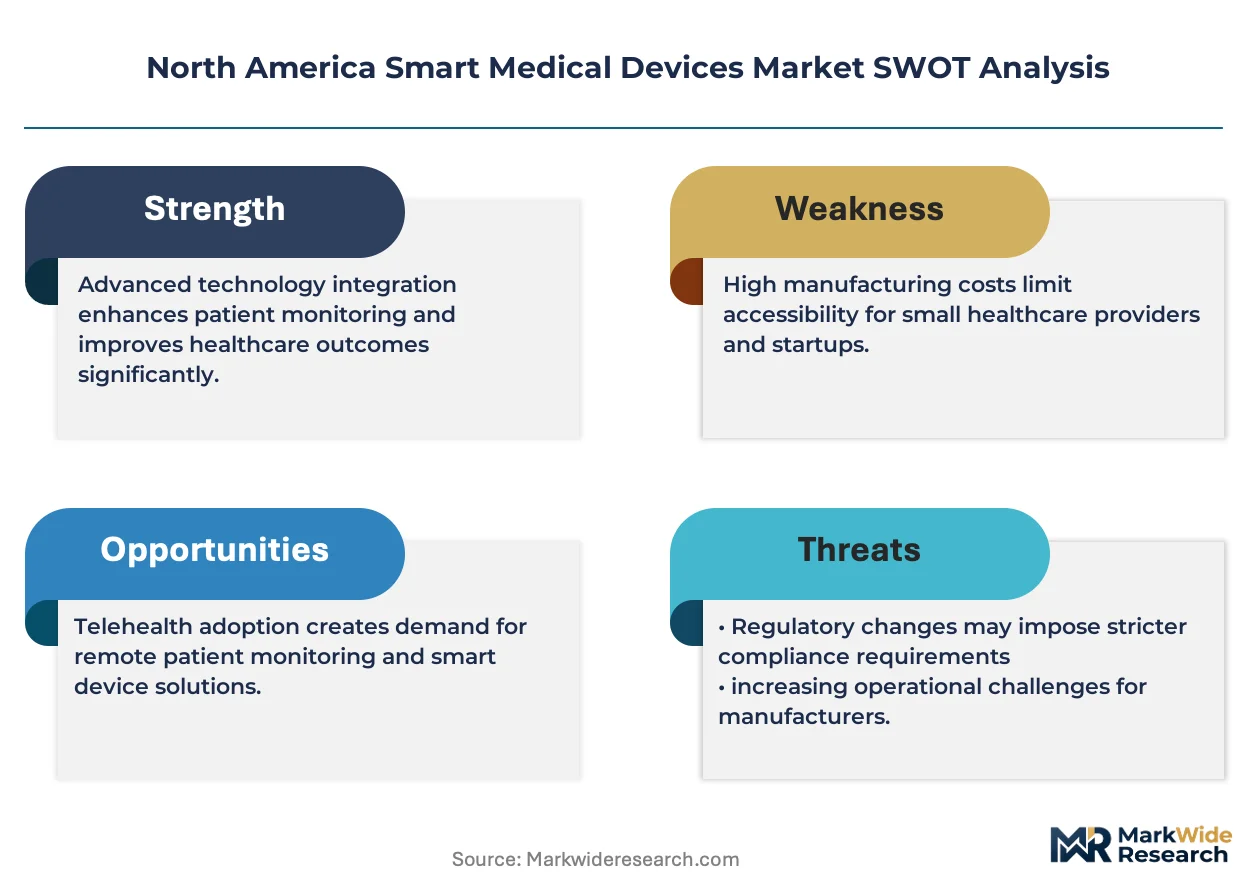
The FDA's software-as-a-medical-device framework is pivoting development priorities toward algorithm-validated diagnostics. Abbott Laboratories leverages its FreeStyle Libre platform to sustain leadership in continuous glucose monitoring. DexCom Inc anchors its competitive position through tight integration with insulin delivery ecosystems. Masimo Corp differentiates via advanced pulse oximetry and hospital-centric wearable architectures.
Smart medical devices combine embedded sensors, wireless connectivity protocols, and clinical-grade algorithms to capture physiological data outside traditional care settings. These systems typically process biometric signals through Bluetooth or Wi-Fi transmission to cloud-based analytics platforms for clinician review and intervention triggering. Wearable devices occupy the largest revenue pool, while home monitoring devices represent the fastest structural expansion as payers expand remote patient monitoring reimbursement codes. Diagnostic devices concentrate margin capture where AI-enabled image analysis commands premium pricing from radiology groups.
FDA premarket review, HIPAA data governance requirements, and FCC wireless device certifications collectively shape product development cycles and market access conditions for North American manufacturers. The Centers for Medicare & Medicaid Services maintains decisive influence through reimbursement determinations that directly determine commercial viability for connected care platforms. Stakeholders must monitor evolving FDA guidance on machine learning-enabled device modifications to anticipate compliance burdens and competitive positioning shifts.
Market Dynamics
FDA premarket review timelines for software-as-a-medical-device are compressing commercialization cycles while CMS reimbursement determinations for remote patient monitoring codes are expanding addressable patient populations.
Growth Catalysts
- CMS Remote Patient Monitoring Reimbursement:Expanded CPT billing codes enable physician practices to bill for continuous physiological monitoring outside hospital walls, accelerating outpatient adoption of connected glucose and cardiac sensors.
- Bluetooth Low Energy 5.3 Protocols:Extended transmission range and reduced power consumption enable wearable devices to maintain continuous cloud connectivity through patients' home Wi-Fi ecosystems without smartphone intermediaries.
- Integrated Hospital Networks in Texas and California:Large health systems deploy enterprise-wide remote monitoring platforms to reduce 30-day readmission penalties and capture value-based care bonuses.
Market Restraints
- HIPAA Data Governance Compliance:Cloud-based biometric storage requires end-to-end encryption architectures and business associate agreements that extend procurement cycles by 8-14 months for hospital IT departments.
- Semiconductor Concentration in Taiwan:Advanced biosensor chip fabrication depends on TSMC capacity allocation, creating supply vulnerability for pulse oximetry and continuous glucose monitoring module producers.
- Lithium-Ion Battery Chemistry Limitations:Wearable form factors constrain cell capacity, forcing trade-offs between device thickness and multi-day operation that limit patient adherence for overnight monitoring protocols.
Strategic Opportunities
- Underpenetrated Rural Medicare Markets:Federally qualified health centers in Appalachian and Southwestern regions lack specialist density, creating demand for asynchronous diagnostic platforms that triage cardiac and respiratory abnormalities.
- AI-Enabled Image Analysis Convergence:Integration of edge-computing neural networks with smartphone-connected dermatoscopes and otoscopes enables point-of-care diagnostic decisions without specialist consultation delays.
- Direct-to-Employer Distribution Channels:Self-insured corporations in manufacturing and logistics sectors purchase biometric monitoring subscriptions as occupational health investments to reduce workers' compensation claims.
Industry Challenges
- Machine Learning Validation Talent Scarcity:Clinical algorithm development requires dual expertise in biomedical signal processing and FDA 510(k) statistical validation protocols, a skill combination concentrated at select academic medical centers.
- Legacy EHR Integration Complexity:Proprietary data formats from Epic and Cerner systems necessitate expensive HL7 FHIR interface development for seamless biometric data ingestion into clinical workflows.
- Software Update Certification Burden:FDA guidance on predetermined change control plans remains unsettled, creating uncertainty for manufacturers deploying over-the-air algorithm improvements to deployed device fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Medical Devices Market |
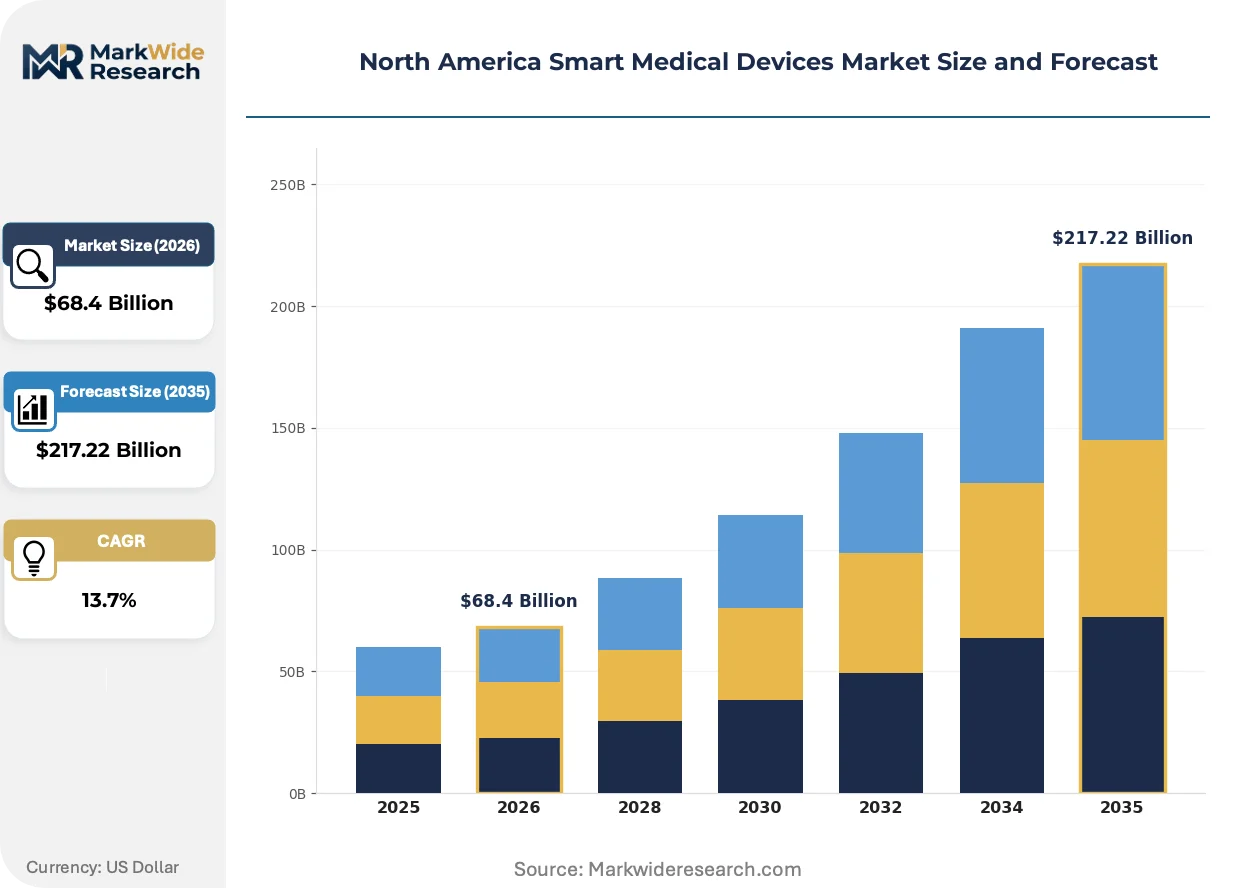
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $217.22 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Home Monitoring Devices, Diagnostic Devices Technology: Bluetooth, NFC, Wi-Fi, RFID Application: Chronic Disease Management, Rehabilitation, Remote Patient Monitoring, Medication Management End User: Hospitals, Home Care, Clinics, Pediatric Centers |
| Companies Covered | Medtronic PLC, Abbott Laboratories, Roche Holding AG, Garmin Ltd, DexCom Inc, GE Healthcare, Johnson & Johnson, Masimo Corp, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Medical Devices Market Trends and Innovations
Algorithm-validated diagnostics are migrating from centralized laboratories to ambulatory settings, compressing the distance between physiological event detection and clinical intervention.
Photoplethysmography-based continuous blood pressure monitoring is overtaking traditional cuff-based oscillometric methods in ambulatory hypertension management. Cardiology practices in California and Texas deploy wrist-worn sensors for 24-hour arterial pressure profiling without patient sleep disruption. The technology is overtaking conventional Holter monitoring volumes as payer contracts increasingly favor longitudinal data over episodic clinic measurements.
FDA's 2023 guidance on predetermined change control plans for machine learning-enabled devices establishes clearer pathways for algorithm updates without repeated 510(k) submissions. Manufacturers gain flexibility to deploy performance improvements to deployed glucose prediction and arrhythmia detection models. Cardiac monitoring wearables and diagnostic radiology platforms represent the earliest adopters, with sponsors filing modular software change protocols to reduce regulatory resubmission costs.
Hospital procurement departments now bundle remote patient monitoring subscriptions with existing medical-surgical supply contracts, displacing standalone digital health vendor relationships. Integrated delivery networks in the Midwest and Southeast negotiate enterprise pricing for multi-year biometric monitoring deployments across cardiology, endocrinology, and pulmonology service lines. Texas-based hospital systems demonstrate the most advanced contracting sophistication, incorporating outcome guarantees and shared savings provisions into vendor agreements.
North America Smart Medical Devices Market Segmentation
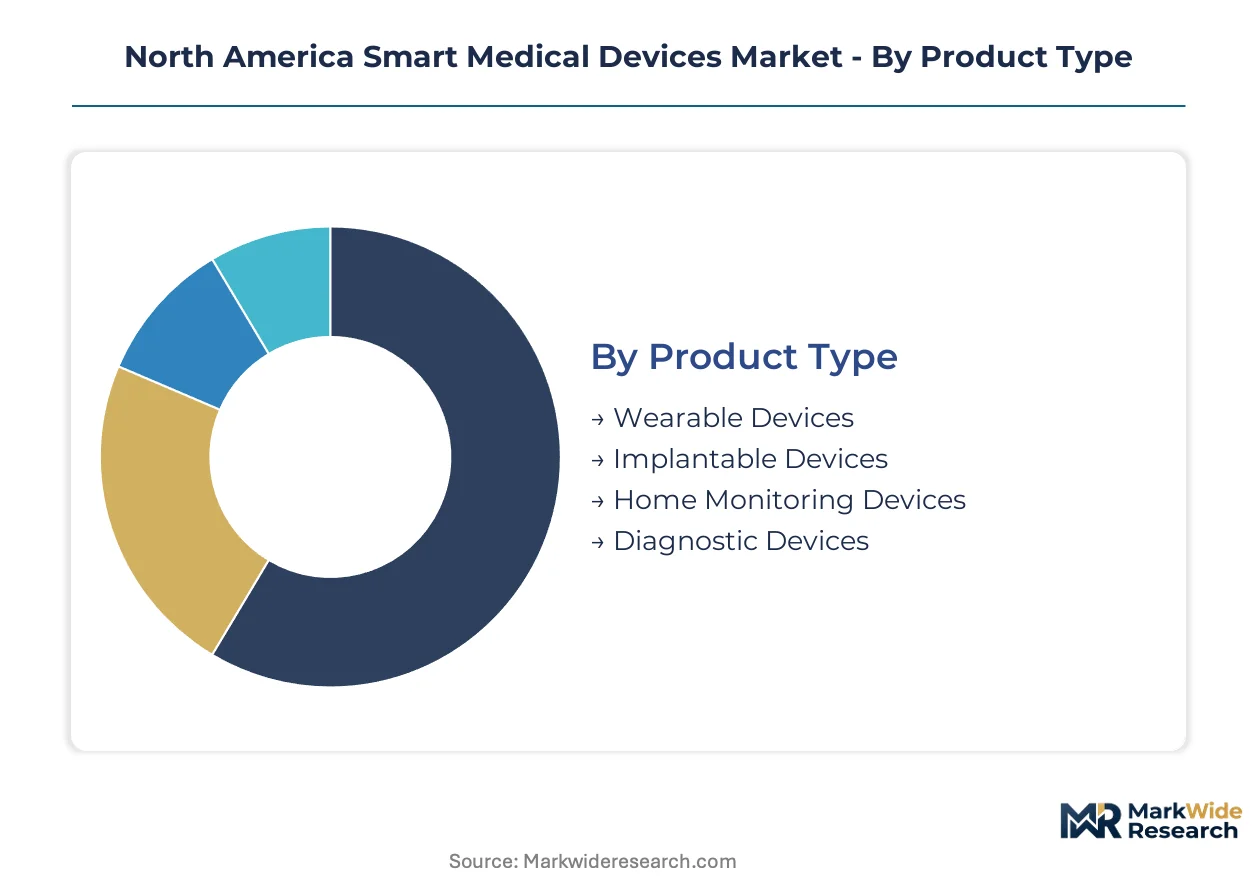
Smart medical device manufacturers align product architectures with specific reimbursement pathways and clinical workflow integration requirements. Segmentation reveals where FDA clearance complexity, CMS billing code eligibility, and health system procurement priorities intersect to determine commercial viability.
Product Type:
Replacement cycles vary sharply across form factors, with wearable sensors refreshing every 18-24 months while implantable systems demand decade-long reliability engineering.
- Wearable Devices:Continuous glucose monitors and cardiac event recorders integrate photoplethysmography and accelerometry into skin-adherent patches or wrist-worn formats. Texas and California hospital networks deploy enterprise contracts for ambulatory arrhythmia detection, with Abbott and DexCom capturing the largest placement volumes through integrated insulin delivery partnerships.
- Home Monitoring Devices:Pulse oximetry, blood pressure cuffs, and spirometry systems transmit biometric streams via Bluetooth Low Energy to cloud analytics platforms. Federally qualified health centers in Appalachian regions purchase asynchronous diagnostic subscriptions to compensate for specialist scarcity, accelerating the fastest structural expansion in this category.
- Implantable Devices:Cardiac resynchronization therapy defibrillators and neurostimulators incorporate wireless telemetry for remote parameter adjustment without clinic visits.
- Diagnostic Devices:Smartphone-connected dermatoscopes, otoscopes, and portable ultrasound probes enable point-of-care image capture with AI-enabled preliminary interpretation.
Volume placements concentrate in wearable continuous monitoring systems; the faster expansion belongs to home monitoring devices gaining reimbursement traction under expanded RPM CPT codes.
Technology:
Connectivity protocol selection hinges on power budget, transmission range, and hospital IT security architecture compatibility.
- Bluetooth:Low Energy 5.3 protocols dominate wearable glucose and cardiac sensors, enabling 100-meter transmission range with sub-milliamp power draw. Masimo and DexCom firmware stacks prioritize Bluetooth mesh resilience for uninterrupted cloud synchronization through home Wi-Fi gateways.
- Wi-Fi:Stationary home monitoring hubs and diagnostic imaging devices leverage 802.11ax for high-bandwidth physiological data upload, particularly where video-enabled telehealth encounters require synchronous clinician-patient interaction.
- NFC:Implantable device interrogation and medication adherence blister packs utilize near-field coupling for zero-power patient authentication and dosing verification.
- RFID:Asset tracking and surgical instrument sterilization workflows embed passive tags for supply chain visibility within integrated delivery networks.
Bluetooth dominates ambulatory wearable shipments; Wi-Fi is climbing the fastest as home monitoring systems displace smartphone-tethered architectures.
Application:
Clinical use case prioritization follows CMS reimbursement determination timelines and FDA 510(k) predicate device availability.
- Chronic Disease Management:Diabetes, hypertension, and heart failure protocols drive the largest revenue pool through continuous physiological monitoring with automated alert thresholds. California cardiology practices deploy 24-hour blood pressure profiling wristbands, displacing conventional Holter monitoring volumes as payer contracts favor longitudinal data capture.
- Remote Patient Monitoring:Post-acute discharge surveillance and outpatient exacerbation prevention command premium pricing where 30-day readmission penalties create health system financial exposure. Texas-based integrated delivery networks negotiate outcome-guaranteed vendor contracts spanning multi-year biometric monitoring deployments.
- Rehabilitation:Orthopedic recovery and stroke therapy monitoring utilize motion capture and muscle activation sensors to quantify functional improvement.
- Medication Management:Connected inhalers and insulin pens record dosing events with timestamps to verify adherence patterns.
Chronic disease management captures the deepest revenue concentration; remote patient monitoring is expanding most quickly as Medicare Advantage plans broaden risk-based contracting.
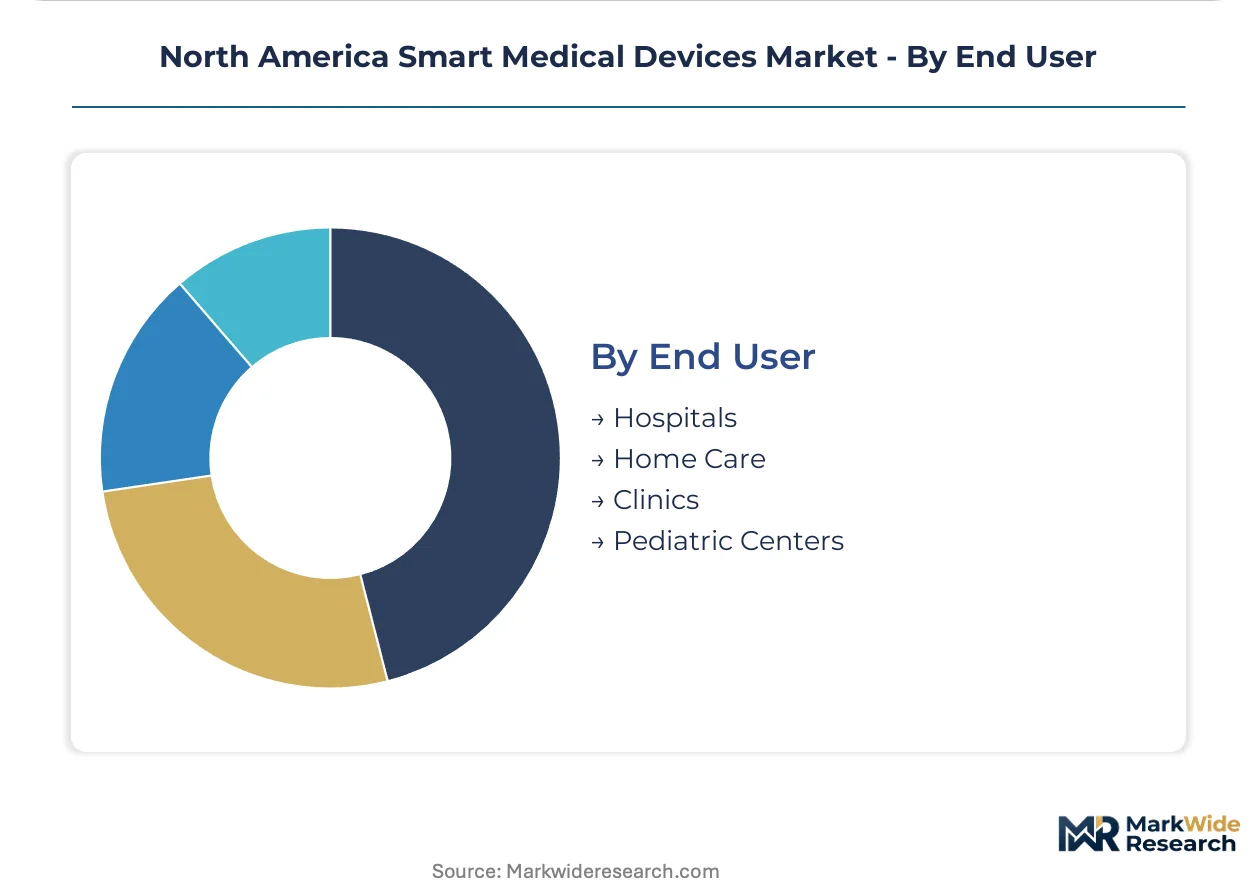
End User:
Procurement authority and reimbursement eligibility fragment across care settings with divergent IT integration capabilities.
- Hospitals:Enterprise-wide remote monitoring platforms consolidate cardiology, endocrinology, and pulmonology service lines under single vendor relationships. Midwest and Southeast integrated delivery networks demonstrate advanced contracting sophistication with shared savings provisions.
- Home Care:Medicare-certified home health agencies deploy biometric monitoring kits for post-acute patients, with reimbursement contingent on documented clinical interaction time.
- Clinics:Independent physician practices purchase standalone glucose and cardiac sensor subscriptions where CPT billing codes enable direct reimbursement without hospital facility fees.
- Pediatric Centers:Cystic fibrosis and congenital heart defect monitoring requires specialized form factors and algorithm validation distinct from adult populations.
Hospital procurement concentrates the largest contract values; home care is gaining share fastest as Medicare Advantage and managed Medicaid plans expand in-home benefit designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in coastal technology corridors while consumption spreads across integrated hospital networks and Medicare-eligible populations. Regulatory harmonization through FDA and Health Canada frameworks shapes cross-border product strategies. Texas and California anchor the largest procurement volumes through enterprise health system contracts.
United States
Texas-based hospital systems deploy enterprise-wide remote monitoring platforms with outcome guarantees, while California cardiology practices pioneer 24-hour ambulatory blood pressure profiling. FDA software-as-a-medical-device guidance accelerates commercialization timelines for algorithm-validated diagnostics. The Boston-Cambridge corridor anchors continuous glucose monitoring R&D clusters with tight insulin delivery ecosystem integration.
Canada
Health Canada premarket review aligns with FDA predicate device pathways, enabling synchronized North American launches for Bluetooth-enabled cardiac sensors. Ontario's provincial health plans expand remote patient monitoring reimbursement for post-acute heart failure management. Toronto-Waterloo health technology clusters specialize in AI-enabled image analysis for point-of-care dermatoscopy.
Mexico
Federally qualified health centers in northern border states pilot asynchronous diagnostic platforms for cardiac triage, leveraging US FDA-cleared devices under regulatory equivalence protocols. Mexico City's private hospital networks adopt enterprise monitoring contracts for medical tourism patient cohorts. Guadalajara's medical device manufacturing zones assemble pulse oximetry modules for re-export to US hospital supply chains.
North America Smart Medical Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established FDA regulatory infrastructure and hospital procurement relationships. Abbott Laboratories and DexCom Inc anchor the continuous glucose monitoring segment through integrated insulin delivery partnerships. Three archetypes dominate: diversified conglomerates with multi-therapeutic portfolios, specialized diabetes and cardiac monitoring pure-plays, and diversified technology companies leveraging consumer wearable expertise. Competitive moves concentrate on strategic partnerships with insulin pump manufacturers and geographic expansion into Medicare Advantage-contracted health systems.
Within the diversified conglomerate tier, Medtronic PLC and Abbott Laboratories represent archetypal players with established cardiac and diabetes device portfolios. DexCom Inc exemplifies the specialized pure-play model with focused continuous glucose monitoring positioning. Garmin Ltd occupies a distinct position bridging consumer fitness wearable expertise with clinical-grade sensor development. Masimo Corp anchors the hospital-centric monitoring architecture segment.
| Leading Market Players |
|---|
| Medtronic PLC |
| Abbott Laboratories |
| Roche Holding AG |
| Garmin Ltd |
| DexCom Inc |
| GE Healthcare |
| Johnson & Johnson |
| Masimo Corp |
| Stryker |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) clearance tiering bifurcates device economics between algorithm-validated premium platforms and commodity sensor modules, concentrating margin capture with established regulatory infrastructure while forcing price compression on undifferentiated hardware. This divergence manifests in procurement patterns: hospital systems negotiate outcome-based subscriptions for cleared diagnostics while home monitoring devices compete on unit economics constrained by CMS reimbursement ceilings.
Pricing Analysis
Margin tightening in wearable glucose sensors reflects CMS RPM code reimbursement caps that compress ASPs for continuous monitoring hardware. Three-tier pricing structure across premium algorithm-validated, standard FDA-cleared, and economy consumer-grade tiers separates hospital enterprise contracts from direct-to-consumer channels. Price differentiation rests on FDA predicate device availability and integrated insulin delivery ecosystem bundling. Independent physician practices exhibit highest price sensitivity due to direct CPT billing exposure, while integrated delivery networks leverage volume scale for preferential tier placement.
Supply Chain Analysis
Dual-sourcing mandates from Texas and California hospital systems require qualified secondary suppliers for Bluetooth Low Energy chipsets and lithium-polymer cells, extending qualification cycles. Advanced biosensor fabrication draws from Taiwan, South Korea, and domestic US foundries, with pulse oximetry module assembly concentrated in Guadalajara medical device zones. Raw material dependencies include silicon carbide substrates, rare-earth magnet alloys for implantable telemetry, and medical-grade lithium cobalt oxide. Single-source vulnerability concentrates in TSMC capacity allocation for neural network accelerator chips. Distribution runs through GPO contracts with Premier and Vizient, supplemented by direct hospital system procurement for enterprise monitoring deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-a-medical-device compliance costs erect a barrier-to-entry moat favoring incumbents with established 510(k) statistical validation protocols and predicate device libraries.
For Market Incumbents: Hedge against algorithm obsolescence by acquiring edge-computing neural network specialists with FDA predetermined change control plan experience. Secure captive supply of Bluetooth 5.3 chipsets through foundry partnerships in South Korea to offset Taiwan concentration risk. Reinforce hospital procurement relationships with outcome-guaranteed contracts incorporating 30-day readmission penalty sharing. For New Entrants and Emerging Players: Enter via asynchronous diagnostic platforms for federally qualified health centers in Appalachian and Southwestern rural markets where specialist scarcity creates reimbursement-advantaged white space. Target Medicare Advantage risk-based contracting channels with biometric monitoring subscriptions priced below hospital facility fee structures. Pursue direct-to-employer occupational health distribution to bypass GPO procurement complexity. For Investors and Strategic Acquirers: Re-rating potential sits with specialized pure-plays possessing FDA-cleared algorithm platforms and integrated insulin delivery partnerships given CMS reimbursement expansion catalysts. Long-term viability over the projection horizon favors acquisition targets with proprietary photoplethysmography signal processing IP and hospital-centric wearable architectures. Monitor FDA guidance finalization on machine learning-enabled device modifications as inflection signal for algorithm update revenue model viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Enables over-the-air algorithm deployment without repeated 510(k) resubmission costs. |
| Hospital System Enterprise Partnership | Texas-based integrated delivery networks negotiate multi-year outcome-guaranteed monitoring contracts. |
| Bluetooth Low Energy 5.3 Firmware Stack Development | Masimo and DexCom prioritize mesh resilience for uninterrupted cloud synchronization. |
| Insulin Delivery Ecosystem Integration | Abbott and DexCom sustain competitive positioning through tight pump manufacturer partnerships. |
| CMS Reimbursement Strategy Expansion | Remote patient monitoring CPT code eligibility determines commercial viability for connected care platforms. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, CMS reimbursement determination schedules, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee members, and regulatory affairs leads at algorithm-enabled device sponsors. Secondary validation drew from FDA MAUDE adverse event databases, CMS Medicare claims data, hospital procurement databases, and SEC 10-K filings of publicly traded device manufacturers. Bottom-up unit shipment estimates across wearable, home monitoring, implantable, and diagnostic form factors triangulated against top-down health system IT spending allocations.
Input-output matrices mapped sensor component costs, regulatory compliance expenditures, and reimbursement pathway eligibility across product type, connectivity protocol, clinical application, and end-user setting dimensions. CAGRs were derived from logistic diffusion curves fitted to historical placement volumes and payer coverage expansion trajectories. Forecast inputs incorporated Bluetooth protocol adoption cycles, lithium-ion energy density improvement curves, and FDA guidance evolution on machine learning-enabled modifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or CMS reimbursement code retraction scenarios. Deviation in FDA predetermined change control plan guidance finalization would shift competitive positioning materially between algorithm-validated and locked-device architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
General Surgery Devices Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Europe Otoscope Market
Medical Devices
Urine Flow Meters Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Anesthesia Vaporizers Market
Medical Devices
Micro Syringes Market