
 United States Ultrasound Devices Market | 2026-2036
United States Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ultrasound Devices Market Analytics
Aftermarket service revenue is reconfiguring margin pools across the United States ultrasound landscape. GE Healthcare leverages its extensive field engineering network to sustain recurring service contracts. Siemens Healthineers anchors premium installed base profitability through predictive maintenance platforms. Koninklijke Philips N.V. competes on remote diagnostic capabilities that reduce equipment downtime.
Ultrasound devices generate acoustic images through piezoelectric transducer arrays operating at frequencies between two and fifteen megahertz, with beamforming algorithms processing reflected echoes for real-time visualization of soft tissue structures, blood flow, and fetal development. Diagnostic ultrasound systems command the largest revenue share among product types, while portable and wireless configurations represent the fastest-expanding segment as ambulatory sites prioritize capital efficiency. Cardiology and obstetrics applications generate the most procedure volume, though musculoskeletal imaging is gaining traction in sports medicine clinics seeking to replace costlier MRI referrals.
FDA 510(k) premarket notification requirements govern device safety and efficacy submissions, while the FDA's software-as-a-medical-device framework increasingly shapes AI-integrated ultrasound analytics. The Centers for Medicare and Medicaid Services reimbursement policies directly influence hospital purchasing timelines and technology upgrade decisions. Stakeholders must monitor evolving FDA guidance on machine-learning-enabled diagnostic tools and state-level certificate-of-need regulations that constrain imaging capacity expansion.
Market Dynamics
FDA 510(k) clearance pathways for AI-enabled diagnostic software are compressing product commercialization timelines while hospital fleet replacement cycles concentrate procurement decisions among consolidated health systems in Texas, California, and Florida.
Growth Catalysts
- Point-of-care adoption:Emergency medicine departments are deploying portable ultrasound systems to accelerate triage decisions and reduce CT scan dependency for trauma assessment.
- AI integration frameworks:The FDA's software-as-a-medical-device pathway is streamlining algorithmic diagnostic tools that automate image interpretation and workflow optimization.
- Musculoskeletal imaging expansion:Sports medicine clinics are substituting ultrasound for MRI referrals to cut patient costs and appointment backlogs.
Market Restraints
- Piezoelectric crystal supply concentration:Transducer manufacturing depends on specialized ceramic suppliers concentrated in East Asia, exposing OEMs to input volatility and logistics disruption.
- Certificate-of-need constraints:State-level CON regulations in 35 states limit imaging capacity expansion and suppress incremental equipment purchases by blocking new facility approvals.
- Technical resolution ceilings:Acoustic physics boundaries at higher frequencies restrict penetration depth, constraining ultrasound utility in obese patient populations and deep-tissue diagnostics.
Strategic Opportunities
- Rural health clinic penetration:Federally qualified health centers in Mississippi, Alabama, and rural Texas remain underpenetrated for point-of-care cardiac and obstetric screening.
- Remote diagnostic platforms:Cloud-based image transmission and AI-assisted telesonography enable specialist interpretation without on-site radiologist presence.
- CMS reimbursement expansion:Medicare coverage determinations for lung ultrasound and guided procedures are creating new billable service lines for hospital outpatient departments.
Industry Challenges
- Sonographer workforce scarcity:The American Registry for Diagnostic Medical Sonography reports credentialing bottlenecks as training program capacity lags behind imaging volume growth.
- Legacy PACS integration friction:Hospital IT departments face middleware complexity when connecting wireless handheld devices to existing picture archiving and communication infrastructure.
- AI validation timeline compression:Machine-learning algorithm developers must complete clinical evidence generation within narrow FDA submission windows before predicate device clearances expire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ultrasound Devices Market |
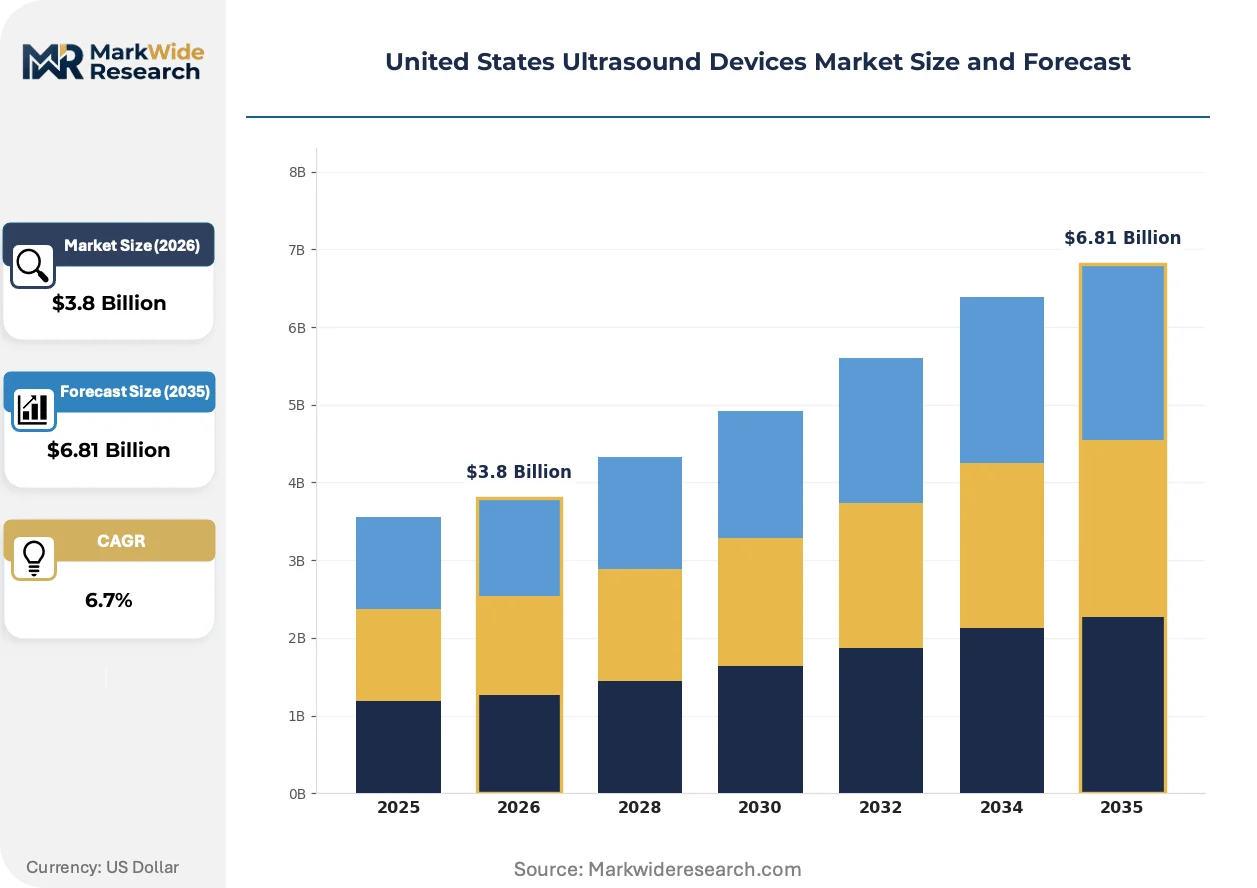
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, Portable Ultrasound, 3D/4D Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Research Laboratories Technology: Digital Ultrasound, Analog Ultrasound, Hybrid Ultrasound, Wireless Ultrasound Application: Cardiology, Obstetrics, Urology, Musculoskeletal |
| Companies Covered | Canon Medical Systems, Mindray Medical International Limited, GE Healthcare, Butterfly Network, Samsung Medison Co., Ltd., Koninklijke Philips N.V., FUJIFILM SonoSite, Inc., Clarius Mobile Health, Siemens Healthineers AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ultrasound Devices Market Evolving Landscape
Ultrasound technology trajectories center on miniaturization, algorithmic automation, and service model restructuring that decouples hardware ownership from diagnostic utility.
Capacitive micromachined ultrasound transducers are migrating from research laboratories into commercial handheld devices. Emergency departments and ambulatory surgical centers are adopting CMUT-based probes for cardiac and abdominal imaging at price points below traditional piezoelectric cart systems. The technology is migrating from premium hospital installations toward cost-sensitive point-of-care settings, compressing average selling prices while expanding addressable procedure volume.
The FDA's software-as-a-medical-device framework is reshaping regulatory obligations for algorithm developers. Pre-market submission requirements now encompass continuous learning systems and locked algorithm versions, extending compliance timelines for AI-enabled ultrasound analytics. Cardiology applications face the steepest evidentiary burdens as predicate device comparisons require matched demographic cohorts.
Aftermarket service unbundling is altering capital equipment economics. Health systems are negotiating component-level maintenance contracts and remote technical support subscriptions rather than comprehensive service agreements. This pattern is most visible in California and Florida where large integrated delivery networks command procurement leverage and internal biomedical engineering capacity.
United States Ultrasound Devices Market Segmentation
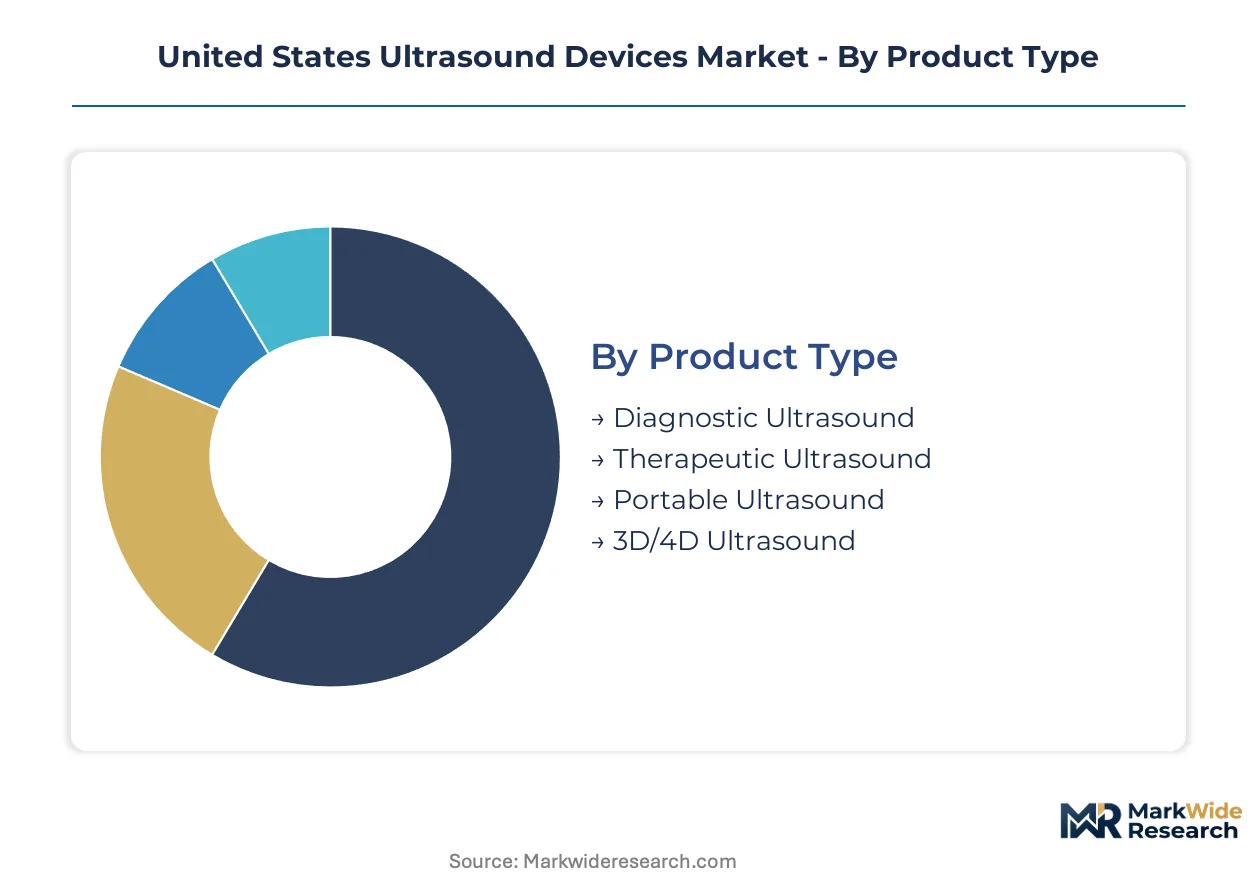
Ultrasound device segmentation reveals distinct procurement patterns across care settings and clinical applications. Product configurations, end-user infrastructure, and imaging protocols create divergent margin structures that OEMs must navigate through specialized go-to-market strategies.
Product Type:
Clinical use-case spectrum spans stationary diagnostic suites to handheld point-of-care deployment, with each tier commanding different capital allocation cycles and service attachment rates.
- Diagnostic Ultrasound:Cart-based systems integrate high-channel-count beamformers with specialized transducer arrays for deep-tissue visualization. Hospital radiology departments in Texas and California drive replacement demand as health system consolidations standardize fleet specifications across multi-site networks.
- Portable Ultrasound:Battery-powered devices with CMUT or advanced piezoelectric architectures enable bedside and field deployment. Emergency medicine departments in Florida are expanding procurement for trauma triage, displacing CT dependency for hemodynamic assessment.
- Therapeutic Ultrasound:Focused acoustic energy systems target tissue ablation and drug delivery applications. Sports medicine clinics adopt these for targeted musculoskeletal intervention.
- 3D/4D Ultrasound:Volumetric acquisition systems render real-time fetal and cardiac motion. Maternal-fetal medicine practices prioritize these for anomaly screening protocols.
Established volume favors diagnostic ultrasound; emerging adoption favors portable ultrasound.
End User:
Customer infrastructure maturity determines equipment specifications and financing preferences across the care continuum.
- Hospitals:Integrated delivery networks command centralized procurement leverage, negotiating enterprise service agreements that bundle multiple modalities. Academic medical centers in urban Texas markets prioritize research-compatible platforms with open API architectures.
- Clinics:Federally qualified health centers in rural Mississippi and Alabama present underpenetrated demand for point-of-cardiac and obstetric screening. These sites favor lease structures over capital purchase to preserve liquidity.
- Diagnostic Centers:Independent imaging facilities compete on throughput metrics, driving demand for workflow-optimized systems with automated measurement packages.
- Research Laboratories:Preclinical and translational research sites require specialized high-frequency transducers and raw data export capabilities for algorithm development.
Hospital procurement dominates absolute unit volume; clinic expansion offers the steepest trajectory for portable system placement.
Technology:
Signal processing architecture separates legacy installed base from next-generation platforms competing on image quality and connectivity.
- Digital Ultrasound:Software-defined beamforming enables post-processing optimization and AI integration. New installations in California health systems increasingly specify fully digital architectures for interoperability with enterprise imaging networks.
- Wireless Ultrasound:Probe-to-tablet transmission eliminates cable management constraints in sterile fields and crowded emergency bays. Adoption concentrates in ambulatory surgical centers seeking spatial flexibility.
- Hybrid Ultrasound:Mixed-signal systems bridge analog front-ends with digital back-ends, serving cost-sensitive buyers transitioning from legacy platforms.
- Analog Ultrasound:Discrete component architectures persist in secondary markets and developing-world exports from US refurbishment operations.
Digital platforms anchor replacement demand; wireless configurations are climbing the fastest among new modality purchases.
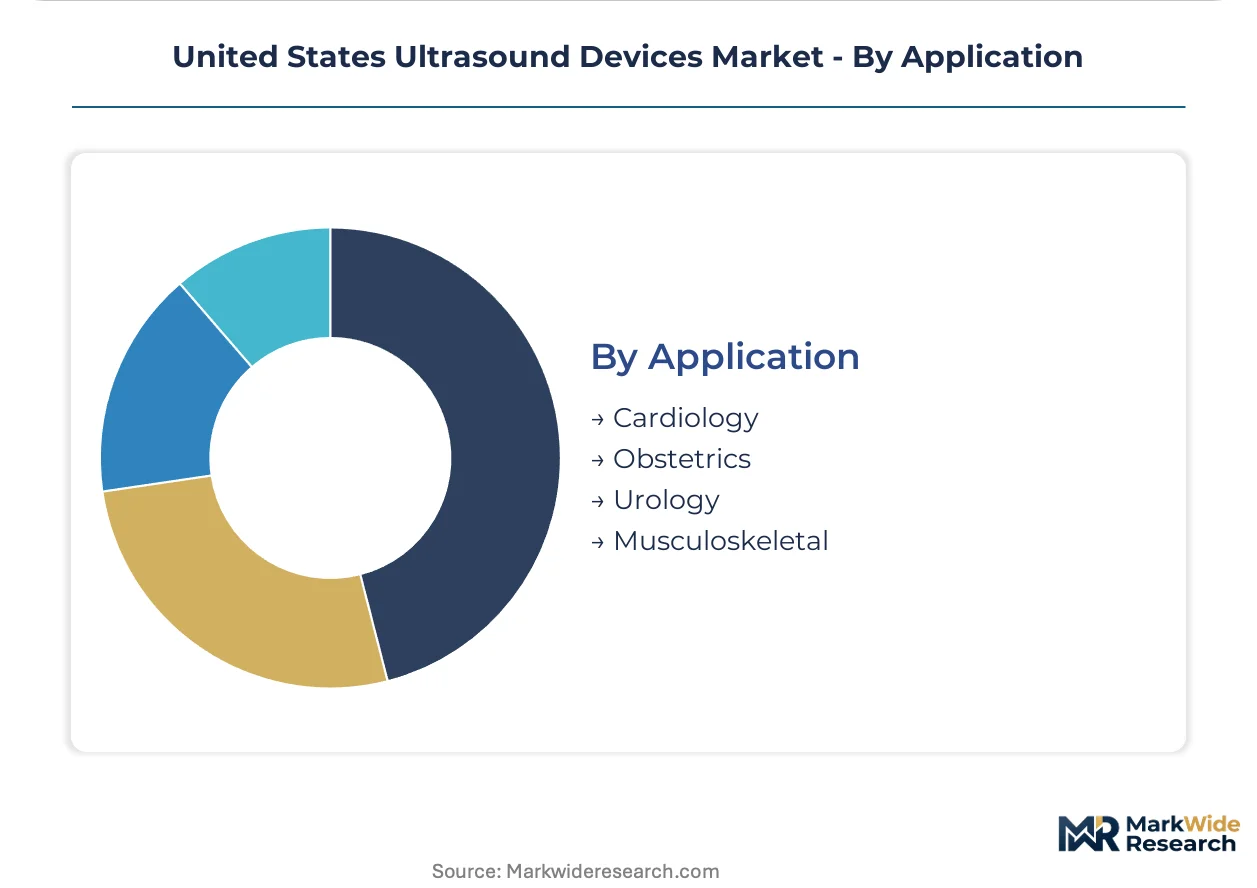
Application:
Clinical specialty requirements dictate transducer frequency selection, examination protocols, and reimbursement coding complexity.
- Cardiology:Phased-array and continuous-wave Doppler systems quantify valvular function and hemodynamics. Hospital outpatient departments in Florida pursue CMS reimbursement expansion for point-of-care cardiac assessment.
- Obstetrics:Curved-array abdominal probes dominate fetal biometry and anatomical survey procedures. Volume concentrates in maternal-fetal medicine subspecialty practices.
- Musculoskeletal:High-frequency linear arrays visualize tendons, ligaments, and peripheral nerves. Sports medicine clinics in Texas substitute these for MRI referrals to compress patient cost and appointment backlog.
- Urology:Transrectal and transabdominal probes support prostate assessment and renal evaluation. Urology group practices drive dedicated system procurement.
Cardiology and obstetrics sustain procedure volume leadership; musculoskeletal imaging gains share fastest among outpatient substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultrasound device procurement patterns diverge sharply across US states, with consolidated health systems in Texas and California driving fleet standardization while rural Mississippi and Alabama clinics lag in point-of-care adoption despite federal qualification status.
Texas
Large integrated delivery networks in Houston and Dallas-Fort Worth are standardizing ultrasound fleets across multi-site radiology departments following recent hospital consolidations. State-level Medicaid expansion discussions influence outpatient imaging reimbursement timelines for maternal-fetal medicine practices. The Texas Medical Center cluster anchors research-compatible platform demand with open API specifications for academic medical centers.
California
Health systems in Los Angeles and the Bay Area negotiate enterprise service agreements that unbundle component-level maintenance from comprehensive contracts. FDA software-as-a-medical-device submissions from Silicon Valley algorithm developers face extended compliance timelines for continuous learning systems. The state's certificate-of-need regulations constrain independent imaging facility expansion in saturated urban markets.
Florida
Emergency medicine departments in Miami and Tampa are expanding portable ultrasound procurement to displace CT dependency for trauma triage and hemodynamic assessment. CMS reimbursement expansion for point-of-care cardiac evaluation is driving hospital outpatient department purchasing decisions. The state's large retiree population concentrates cardiology procedure volume in metropolitan hospital networks.
Mississippi and Alabama
Federally qualified health centers in rural counties remain underpenetrated for point-of-care cardiac and obstetric screening despite qualifying for capital equipment subsidies. State workforce development programs are attempting to address sonographer training bottlenecks through community college partnerships. The Memphis-Nashville medical corridor influences referral patterns for subspecialty ultrasound services in northern Mississippi counties.
United States Ultrasound Devices Market Competitive Landscape
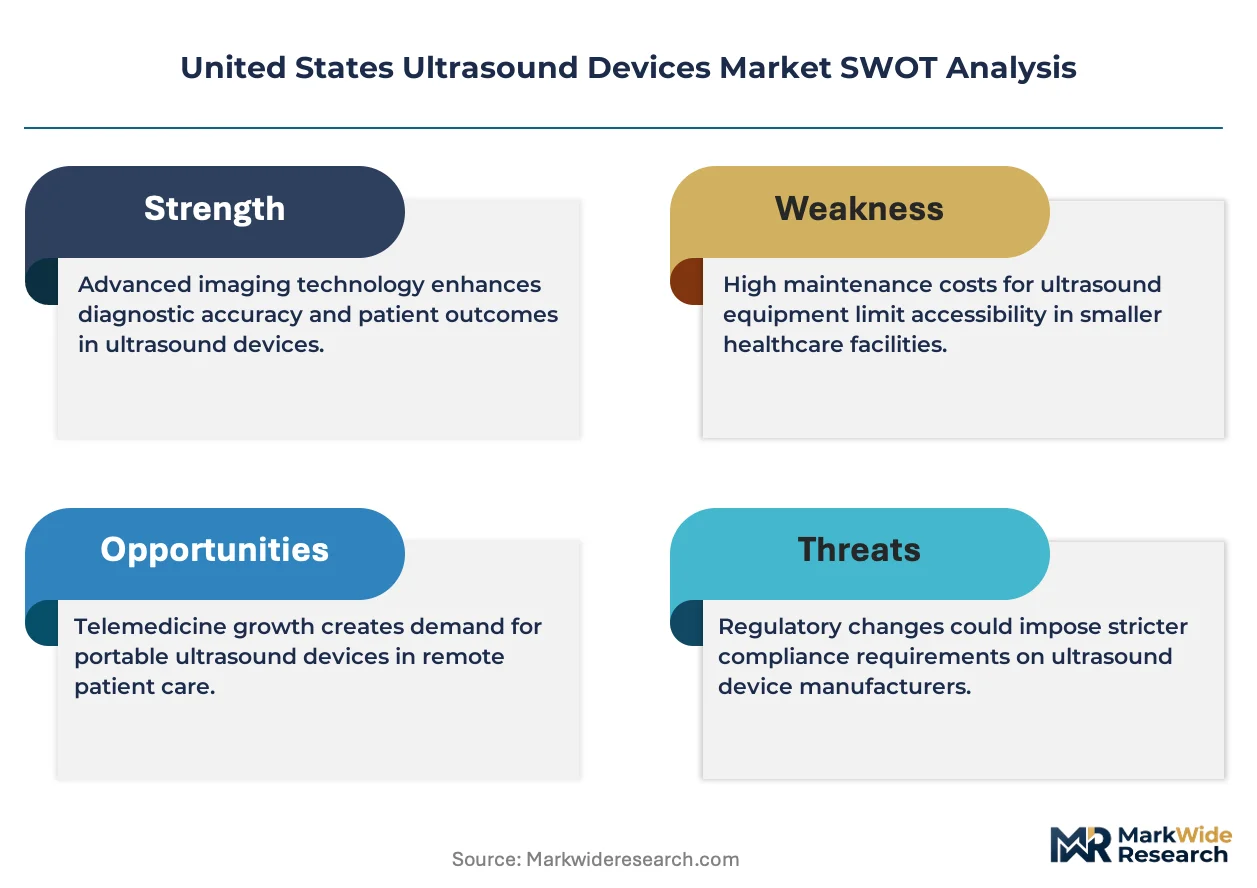
Capability concentration sits with diversified imaging conglomerates; scale advantage sits with consolidated health system procurement leverage. The vendor landscape organizes into three tiers: full-modality conglomerates with service network density, handheld specialists competing on capital efficiency, and emerging algorithm developers seeking FDA software-as-a-medical-device clearance. Dominant competitive moves include predictive maintenance platform deployment and remote diagnostic capability integration.
Within the diversified conglomerate tier, GE Healthcare, Siemens Healthineers AG, and Koninklijke Philips N.V. occupy positions defined by installed base scale and field engineering network coverage. GE Healthcare exemplifies the service-revenue archetype through recurring contract structures. Siemens Healthineers AG anchors premium-tier positioning via predictive maintenance platforms. Koninklijke Philips N.V. represents the remote diagnostics vector with cloud-enabled technical support subscriptions.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Mindray Medical International Limited |
| GE Healthcare |
| Butterfly Network |
| Samsung Medison Co., Ltd. |
| Koninklijke Philips N.V. |
| FUJIFILM SonoSite, Inc. |
| Clarius Mobile Health |
| Siemens Healthineers AG |
| Others |
Value Network & Pricing Analysis
Trans-Pacific freight corridors from Shanghai to Long Beach anchor cost dynamics across the ultrasound device landscape, where concentrated piezoelectric ceramic sourcing in East Asia feeds downstream price stratification between premium cart-based systems and economy handheld configurations.
Pricing Analysis
Long-term service contracts dominate hospital procurement, with enterprise agreements bundling hardware, installation, and predictive maintenance across multi-year terms. Price differentiation separates FDA-cleared AI-enabled platforms from basic imaging systems through software subscription tiers and after-sales support depth. Pricing pressure stems from CMUT-based handheld entrants compressing entry-level margins. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers prioritize interoperability over unit cost.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment constrain domestic beamformer chip fabrication capacity, forcing US OEMs to source from Taiwan, South Korea, and Japan. Transducer assembly draws from specialized lead zirconate titanate suppliers concentrated in China and Japan, with probe housing plastics sourced from German and US chemical processors. Single-source vulnerability concentrates in high-frequency array substrates. Distribution runs through GPO contracts and direct health system agreements rather than independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's software-as-a-medical-device pathway is compressing commercialization timelines for AI-integrated diagnostics, creating asymmetric opportunities for algorithm-native entrants against hardware-centric incumbents.
For Market Incumbents: Entrench installed base profitability through predictive maintenance platform deployment and remote diagnostic capability integration. Consolidate service contract renewals before handheld specialists achieve critical mass in emergency medicine departments. Deepen backward integration into transducer manufacturing to offset East Asian ceramic supply volatility. For New Entrants and Emerging Players: Pursue rural health clinic penetration in Mississippi and Alabama where federally qualified health centers remain underpenetrated for point-of-care cardiac screening. Target sports medicine clinics substituting ultrasound for MRI referrals. Lead with lease-based financing to preserve clinic liquidity and accelerate adoption velocity. For Investors and Strategic Acquirers: Cloud-native algorithm developers with FDA 510(k) clearances represent the most defensible acquisition profile for long-term positioning. Monitor CMS reimbursement determinations for lung ultrasound and guided procedures as the primary inflection signal for outpatient department purchasing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates AI algorithm commercialization under streamlined predicate device pathways. |
| Hospital System Partnership | Locks enterprise procurement leverage through multi-site fleet standardization agreements. |
| CMUT Manufacturing Scale-Up | Reduces handheld system cost structures to displace piezoelectric cart systems. |
| Reimbursement Strategy | Secures CMS coverage for point-of-care cardiac and lung ultrasound procedures. |
| Software Companion Development | Enables locked-algorithm AI integration with continuous learning system compliance. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and emergency medicine clinicians combined with FDA 510(k) databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up unit shipment estimates triangulate against top-down health system capital expenditure tracking.
Calibration against historical replacement cycle patterns and health system consolidation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions span product configuration, end-user infrastructure, application specialty, and state-level regulatory environment. CAGRs derive from procedure volume elasticity to reimbursement expansion and fleet age distribution analysis. Sonographer workforce growth constraints and AI validation timeline compression serve as industry-specific demand-side inputs.
Sensitivities concentrate around FDA guidance evolution on continuous learning systems and state-level certificate-of-need regulation changes. Forecasts reflect assumptions on health system consolidation velocity and CMUT technology maturation. Material shifts in piezoelectric ceramic supply chain configuration or CMS coverage determinations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Contraceptive Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Cardiopulmonary Bypass System Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Light Therapy Beauty Devices Market