
 Canada Continuous Glucose Monitoring Market | 2026-2036
Canada Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Continuous Glucose Monitoring Market Insights
Subscription-based leasing for CGM hardware is tilting competitive dynamics toward asset-light entrants. Abbott Diabetes Care leverages its vertically integrated sensor manufacturing to sustain margin control across Canadian provinces. Dexcom Inc. anchors its position through direct-to-consumer digital channels that bypass traditional distribution.
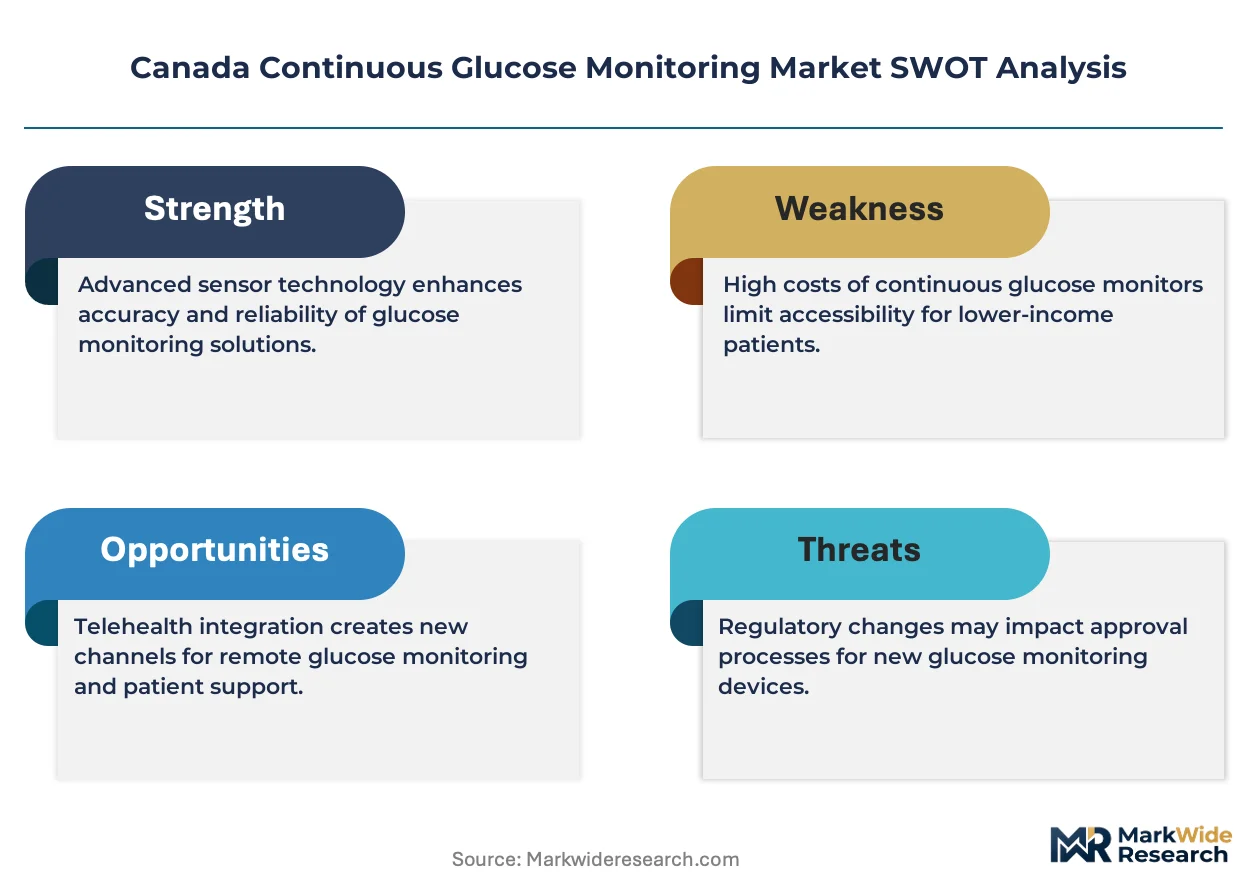
Continuous glucose monitoring comprises electrochemical sensor systems that measure interstitial glucose via enzyme-mediated reactions, transmitting data to receiver devices or software applications for real-time metabolic tracking. Wearable sensors dominate installed base volumes while software applications capture expanding recurring revenue pools. Electrochemical technology leads clinical reliability standards, though optical platforms attract development investment from research institutions seeking non-invasive alternatives.
Health Canada and the FDA jointly shape device approval pathways, with Health Canada's Software as a Medical Device guidance directly enabling smartphone-integrated CGM platforms. Provincial formularies in Ontario and British Columbia determine reimbursement scope, constraining home care adoption where coverage gaps persist. Stakeholders must monitor evolving provincial funding decisions and interoperability mandates that will determine which technology configurations achieve scalable deployment.
Market Dynamics
Health Canada's Software as a Medical Device framework is compressing approval timelines for smartphone-integrated CGM platforms, accelerating competitive entry by asset-light software developers and eroding incumbent hardware margins.
Growth Catalysts
- Ontario provincial formulary expansion:Reimbursement coverage for wearable sensors in hospital corridors drives institutional procurement volume.
- Electrochemical sensor miniaturization:Enzyme-mediated reaction systems achieve 14-day wear duration, reducing patient burden and clinical visit frequency.
- Vancouver diabetes clinic network density:Concentrated specialist infrastructure enables rapid patient onboarding and real-world evidence generation.
Market Restraints
- Platinum electrode supply concentration:Electrochemical sensor fabrication depends on precious metal sourcing from limited North American refiners.
- Interstitial calibration drift:Enzyme degradation limits sensor accuracy beyond manufacturer-stated wear periods.
- Provincial reimbursement fragmentation:British Columbia and Quebec maintain divergent coverage criteria, complicating national rollout strategies.
Strategic Opportunities
- Alberta home care penetration:Private-pay segments in Calgary and Edmonton remain underserved by provincial formulary gaps.
- Optical glucose sensing convergence:Near-infrared spectroscopy platforms integrate with existing wearables for non-invasive validation.
- Direct-to-consumer pharmacy channels:Shoppers Drug Mart and London Drugs expand retail distribution beyond hospital procurement.
Industry Challenges
- Biomedical sensor engineering talent scarcity:Electrochemistry and MEMS fabrication expertise concentrates in Toronto-Waterloo corridor, constraining expansion.
- Health Canada SaMD validation timelines:Software updates require recurring regulatory submission, compressing product iteration cycles.
- Legacy glucometer installed base inertia:Fingerstick habituation among Type 2 populations slows wearable conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Continuous Glucose Monitoring Market |
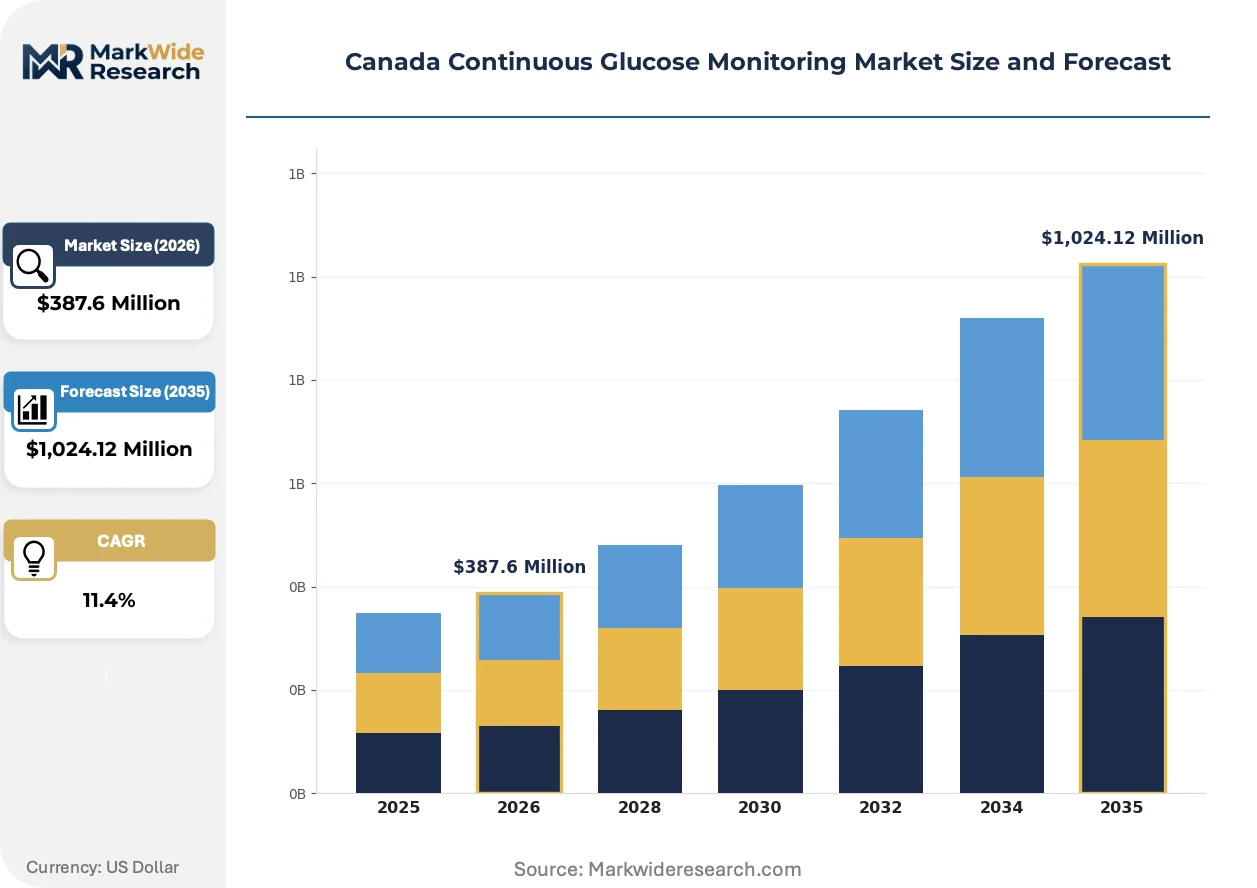
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
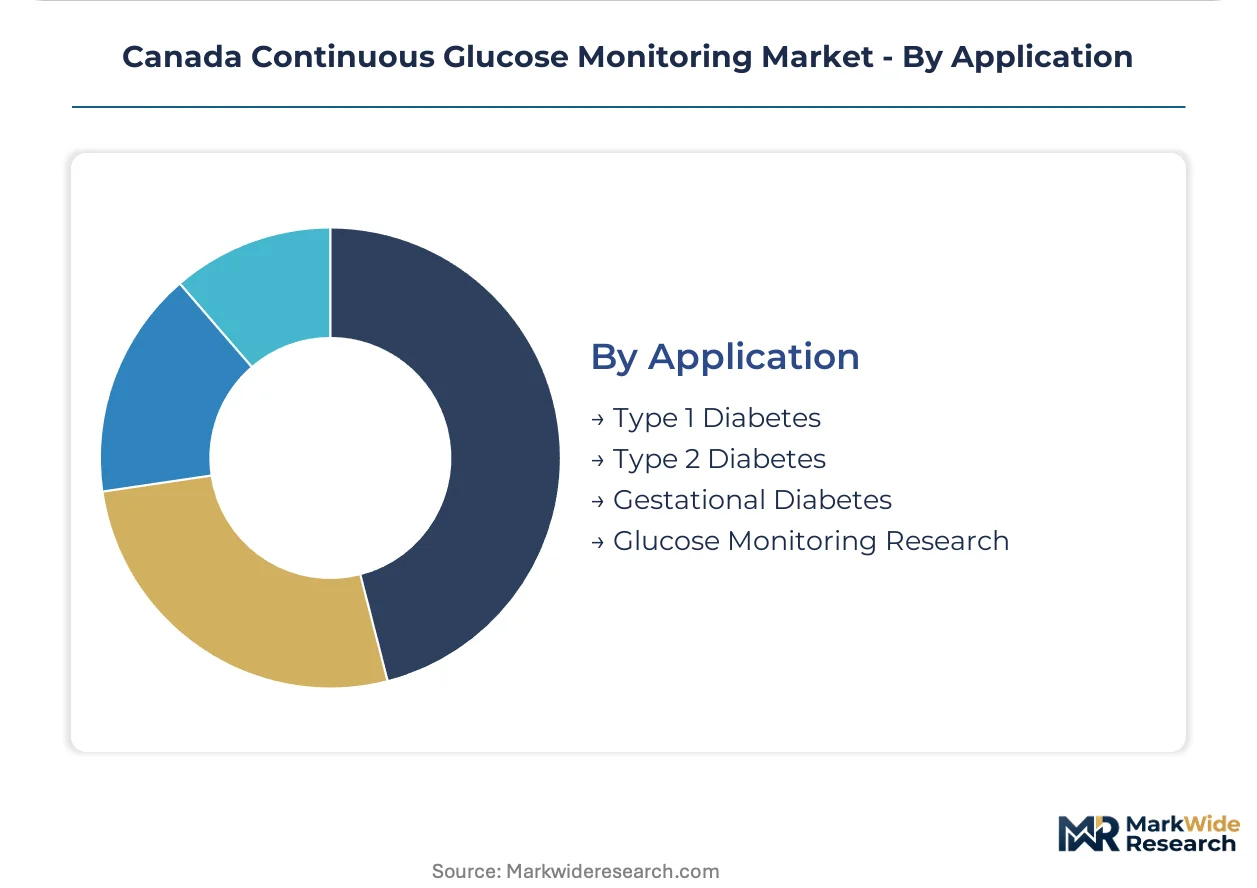
| Segmentation | Product Type: Wearable Sensors, Transmitters, Software Applications, Receiver Devices Technology: Electrochemical, Optical, Enzymatic, Fluorescent End User: Hospitals, Home Care, Diabetes Clinics, Research Institutions Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Glucose Monitoring Research |
| Companies Covered | Abbott Diabetes Care, Dexcom Inc., Medtronic PLC, Ascensia Diabetes Care, GlySens, F. Hoffmann-La Roche, Senseonics, Medtronic of Canada Ltd, Abbott Canada, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Continuous Glucose Monitoring Market Trends and Innovations
Sensor virtualization and algorithmic glucose prediction are displacing hardware-centric business models across Canadian diabetes management. Platform economics now favor recurring software revenue over disposable sensor sales.
Artificial intelligence-enabled predictive algorithms now generate glucose trajectory forecasts from continuous data streams. Endocrinology clinics in Toronto's hospital corridor deploy these tools for proactive insulin dosing adjustments. This capability is virtualizing the diagnostic function of specialist consultations, compressing appointment volumes while expanding patient panel sizes.
Health Canada's 2023 SaMD guidance amendment explicitly recognizes machine learning-based glucose prediction as a standalone medical device function. Manufacturers must submit algorithm change control protocols for pre-market approval. Smartphone-integrated platforms from domestic developers face accelerated review pathways compared to hardware-modification submissions.
Patient acquisition patterns now favor subscription-based hardware leasing over upfront device purchase. Direct-to-consumer digital channels bypass traditional durable medical equipment distributors, capturing margin previously allocated to provincial tender processes. This channel rotation is most visible in British Columbia, where private insurance coverage gaps drive out-of-pocket payment behavior.
Canada Continuous Glucose Monitoring Market Segmentation
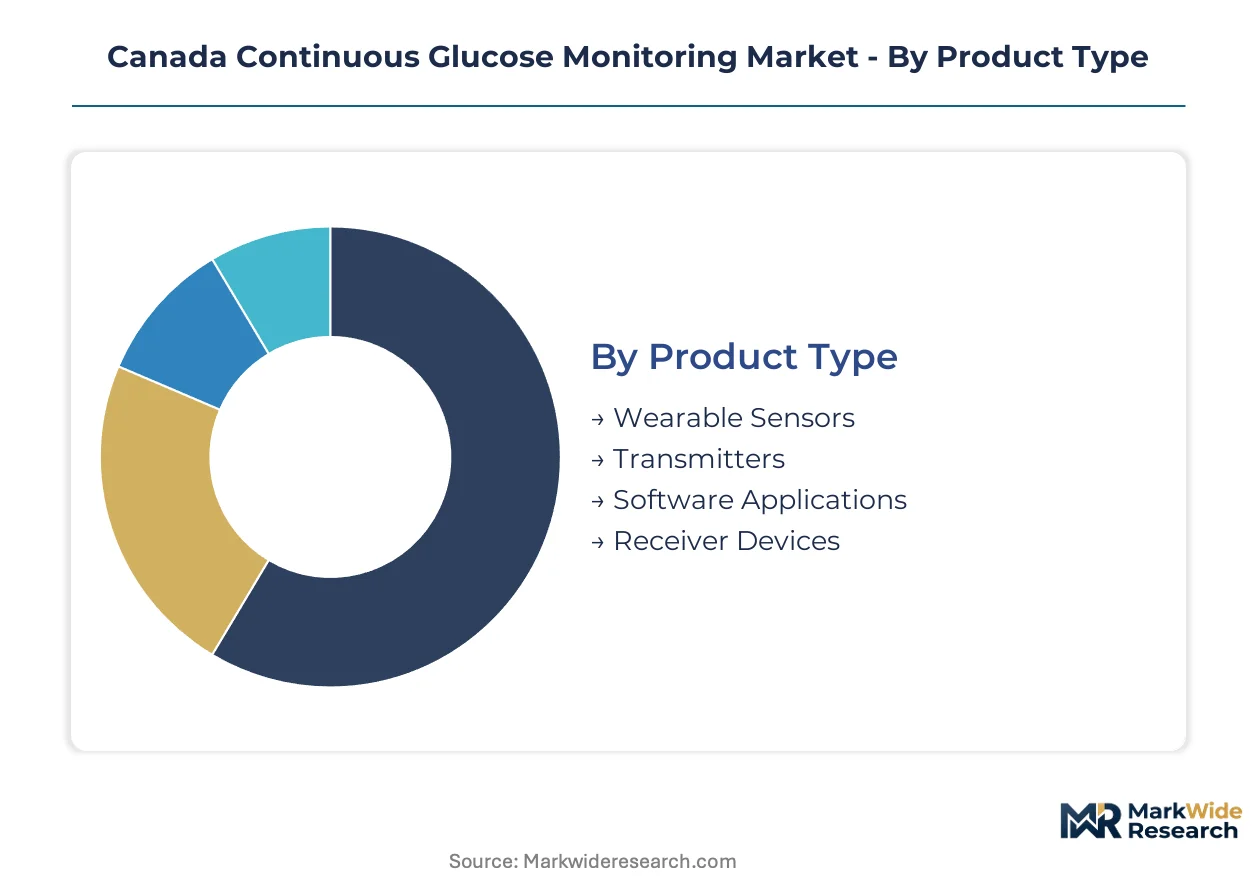
Segmentation in the Canadian CGM market reveals divergent hardware refresh cycles and software update velocities. Product type and technology categories show the widest spread between rapid-turnover consumables and multi-year durable equipment investments.
Product Type:
Wearable sensors turn over every 14 days while receiver devices persist for 3-4 years, creating fundamentally different revenue recognition patterns across the installed base.
- Wearable Sensors:Electrochemical enzyme-mediated strips with platinum electrodes and adhesive biocompatible polymers form the recurring revenue core. Toronto's hospital corridor and Vancouver diabetes clinic networks drive institutional procurement volume through provincial formulary coverage in Ontario and British Columbia.
- Software Applications:Smartphone-integrated platforms transmit real-time glucose data and algorithmic predictions to patients and clinicians. Health Canada's SaMD framework accelerates approval timelines for these asset-light offerings, compressing competitive entry cycles against hardware incumbents.
- Transmitters:Bluetooth-enabled relay devices bridge sensor-to-phone communication with 90-day battery lifecycles.
- Receiver Devices:Dedicated handheld displays serve patients without smartphone access or clinical settings requiring standalone systems.
Wearable sensors dominate installed base. Software applications are where expansion concentrates.
Technology:
Cost tiers separate clinically validated electrochemical platforms from developmental optical alternatives seeking non-invasive breakthroughs.
- Electrochemical:Enzyme-mediated glucose oxidation at platinum electrodes delivers 14-day clinical accuracy with established manufacturing scale. Abbott Diabetes Care leverages vertically integrated sensor fabrication to sustain margin control across Canadian provinces.
- Optical:Near-infrared spectroscopy and Raman scattering platforms pursue non-invasive glucose detection through skin transillumination. Research institutions in the Toronto-Waterloo corridor attract development investment despite unresolved signal-to-noise challenges in interstitial fluid measurement.
- Enzymatic:Glucose oxidase and glucose dehydrogenase biocatalyst formulations determine sensor longevity and calibration stability.
- Fluorescent:Boronic acid-based glucose-binding polymers enable continuous optical readout with reduced oxygen dependence.
Electrochemical technology anchors current revenue. Optical platforms are climbing the fastest in development investment share.
End User:
Application context determines reimbursement pathway complexity and patient acquisition cost structures across the care continuum.
- Hospitals:Acute care settings in Ontario and Quebec deploy CGM for glycemic management in surgical and ICU populations. Provincial tender processes favor multi-year supply contracts with established manufacturers.
- Home Care:Self-monitoring patients in Alberta and Manitoba face private-pay requirements where provincial formulary gaps persist. Dexcom Inc. anchors position through direct-to-consumer digital channels that bypass traditional distribution in these coverage-limited markets.
- Diabetes Clinics:Specialist-led onboarding in Vancouver and Toronto concentrates real-world evidence generation for algorithm validation.
- Research Institutions:Academic medical centers pilot next-generation optical and closed-loop artificial pancreas configurations.
Hospitals dominate institutional procurement volume. Home care is where private-pay expansion concentrates.
Application:
Patient population characteristics drive sensor performance requirements and pricing tolerance across diabetes phenotypes.
- Type 1 Diabetes:Insulin-dependent patients require continuous data for dosing decisions and hypoglycemia alerts. Intensive glucose control mandates drive highest sensor utilization rates and lowest price sensitivity among Canadian CGM users.
- Type 2 Diabetes:Larger patient population with fingerstick habituation and variable insulin dependence. Legacy glucometer installed base inertia slows wearable conversion despite expanding provincial coverage for intensive management subsets.
- Gestational Diabetes:Temporary monitoring needs during pregnancy create 6-9 month utilization windows with obstetric clinic referral pathways.
- Glucose Monitoring Research:Prediabetes and metabolic syndrome studies employ CGM for glycemic variability characterization in non-diabetic populations.
Type 1 diabetes anchors clinical utilization intensity. Type 2 diabetes represents the steepest expansion trajectory for addressable population scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's CGM market relies heavily on imported sensor hardware and transmitter electronics, with domestic value-add concentrated in software integration and regulatory compliance services. Provincial procurement patterns create distinct regional demand clusters rather than a unified national market.
Ontario
Toronto's hospital corridor drives institutional procurement volume through expanded provincial formulary coverage for wearable sensors in acute care settings. Health Canada's SaMD framework accelerates approvals for smartphone-integrated platforms developed by Ontario-based software developers. The Waterloo-Toronto technology corridor concentrates biomedical sensor engineering talent and MEMS fabrication expertise.
Quebec
Montreal's diabetes research institutions pilot next-generation optical sensing configurations and closed-loop artificial pancreas systems. Provincial tender processes in Quebec favor multi-year supply contracts with established manufacturers for hospital CGM deployment. The Greater Montreal area anchors French-language patient education and clinical onboarding infrastructure.
British Columbia
Vancouver's diabetes clinic network density enables rapid patient onboarding and real-world evidence generation for algorithm validation. Private insurance coverage gaps in this province drive out-of-pocket payment behavior and direct-to-consumer channel adoption. The Pacific region's tech-savvy patient population accelerates smartphone-integrated platform uptake.
Alberta
Calgary and Edmonton home care segments remain underserved by provincial formulary gaps, creating private-pay expansion opportunities. Alberta Health Services procurement runs through centralized tender processes that favor hardware leasing models over capital purchases. The province's energy-sector wealth correlates with higher tolerance for non-reimbursed diabetes technology expenditures.
Canada Continuous Glucose Monitoring Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated sensor manufacturers and asset-light software developers leveraging Health Canada's accelerated SaMD pathways. Hardware incumbents compete on manufacturing scale and platinum electrode supply security, while software entrants compress margins through subscription-based leasing models. Three archetypes dominate: integrated device manufacturers with captive sensor fabrication, digital health platforms with algorithmic differentiation, and regional distribution specialists with provincial tender expertise. Competitive moves center on backward integration into precious metal sourcing and strategic partnerships with pharmacy retail chains.
Within the integrated manufacturing tier, Abbott Diabetes Care and Dexcom Inc. exemplify divergent channel strategies. Abbott leverages vertically integrated sensor fabrication to sustain margin control across Canadian provinces through traditional distribution. Dexcom anchors position through direct-to-consumer digital channels that bypass provincial tender processes, particularly in coverage-limited markets. Medtronic PLC occupies a position spanning both hardware manufacturing and algorithmic software development, reflecting hybrid archetype consolidation.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Dexcom Inc. |
| Medtronic PLC |
| Ascensia Diabetes Care |
| GlySens |
| F. Hoffmann-La Roche |
| Senseonics |
| Medtronic of Canada Ltd |
| Abbott Canada |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in platinum electrode fabrication across North American refiners tightens supplier leverage and sustains premium pricing for electrochemical sensor components. Health Canada's SaMD approval velocity accelerates software platform entry, compressing hardware margins while sensor manufacturing constraints limit supply elasticity.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels in provincial tender processes. Price differentiation hinges on Health Canada SaMD certification tier and after-sales algorithm update bundling. Cost compression in the transmitter segment intensifies as Bluetooth module commoditization accelerates. Home care patients in Alberta exhibit highest price sensitivity due to private-pay formulary gaps, while Ontario hospital systems demonstrate lowest sensitivity under expanded reimbursement coverage.
Supply Chain Analysis
Contract manufacturing for electrochemical sensors concentrates with Abbott's vertically integrated captive facilities and select North American EMS providers serving Dexcom's transmitter assembly. Geographic supply concentration spans the United States for platinum electrode sourcing, Malaysia for adhesive polymer substrates, and Taiwan for Bluetooth chipset fabrication. Raw material dependencies center on precious metal electrodes, biocompatible medical-grade polymers, and MEMS fabrication equipment. Single-source vulnerability in platinum refining from limited North American suppliers poses structural risk. Distribution runs through provincial tender processes for hospital procurement and direct-to-consumer digital channels for private-pay segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-as-a-Medical-Device platforms represent the dominant service-attach opportunity, with algorithmic glucose prediction subscriptions expanding faster than disposable sensor hardware across Canadian provinces.
For Market Incumbents: Entrench control over platinum electrode supply through long-term offtake agreements with North American refiners. Deepen in-house production of enzymatic sensor formulations to defend margin position against asset-light software entrants exploiting Health Canada's accelerated SaMD pathways. Prioritize certification investment in machine learning algorithm change control protocols to maintain regulatory moats.
For New Entrants and Emerging Players: Establish a beachhead in Alberta's private-pay home care segment where provincial formulary gaps persist and incumbent hardware coverage remains thin. Target Calgary and Edmonton's energy-sector affluent patient populations with direct-to-consumer subscription models. Leverage pharmacy retail partnerships with Shoppers Drug Mart for retail distribution beyond hospital procurement channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among asset-light software developers with Health Canada SaMD approvals and algorithmic differentiation. Long-term viability over a multi-year horizon favors platforms with installed base data network effects over pure hardware manufacturers facing platinum supply constraints. Monitor Health Canada provincial formulary expansion decisions as the primary inflection indicator for addressable market scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada SaMD Acceleration | Compresses approval timelines for smartphone-integrated platforms versus hardware modifications. |
| Platinum Supply Agreement | Secures electrode fabrication capacity against North American refiner concentration risk. |
| Pharmacy Retail Partnership | Expands patient acquisition beyond Ontario and British Columbia hospital procurement corridors. |
| Algorithm Change Control Investment | Enables iterative machine learning updates under pre-approved regulatory protocols. |
| Provincial Formulary Expansion | Unlocks institutional procurement volume in Quebec and Alberta coverage gaps. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with endocrinologists at Toronto's hospital corridor, biomedical engineers in the Waterloo-Toronto technology cluster, hospital procurement managers across Ontario and British Columbia, and regulatory affairs specialists navigating Health Canada's SaMD framework. Secondary validation drew from Health Canada medical device licensing databases, provincial formulary coverage decisions, FDA 510(k) predicate filings, and hospital supply chain procurement records. Bottom-up sensor shipment estimates triangulated against top-down provincial healthcare expenditure allocations.
Calibration against historical reimbursement expansion patterns and technology adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user setting, and provincial regulatory cluster. CAGRs derived from fitted growth curves incorporating electrochemical sensor wear duration improvements and software platform penetration rates. Industry-specific inputs encompassed platinum electrode supply constraints and Health Canada SaMD approval velocity.
Sensitivities concentrate around provincial formulary expansion timing, platinum supply disruption scenarios, and optical glucose sensing technological breakthroughs. Forecasts reflect documented assumptions regarding reimbursement policy continuity and regulatory pathway stability. Quarterly review of Health Canada approval decisions and provincial tender award notifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market