
 Canada Laundry Appliances Market | 2026-2036
Canada Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Laundry Appliances Market Outlook
A capital-intensity divergence between domestic manufacturing and import-dependent assembly is bifurcating competitive dynamics in the Canada laundry appliances sector. Whirlpool sustains in-house production capacity in Ontario, leveraging captive supply chains for drum motors and control systems. LG anchors its position through R&D intensity in smart-appliance connectivity and AI-driven cycle optimization. Samsung competes on brand strength in the premium freestanding segment, while Electrolux specializes in commercial-grade equipment for hospitality and institutional buyers.
Canada laundry appliances encompass electrically or gas-powered machines designed to clean, dry, or combine both functions for textiles, with drum capacities ranging from compact 2.3 cubic feet to industrial 75-pound loads and energy consumption ratings governed by federal testing protocols. Washing machines dominate residential volume, though washer-dryer combos are gaining share in Toronto and Vancouver micro-condominiums where space constraints dictate installation type. Energy-efficient technology leads regulatory compliance, while smart appliances capture margin pools through subscription-enabled diagnostics and predictive maintenance features. Commercial end users represent the fastest-growing demand channel, driven by outsourcing trends in hospitality linen services and on-premise laundry operations for long-term care facilities.
Health Canada and the Competition Bureau oversee product safety and labeling accuracy, while Natural Resources Canada administers EnerGuide minimum efficiency standards that effectively gate market access for non-compliant imports. The Canadian Standards Association certifies electrical and gas safety, creating a dual-compliance burden that favors established suppliers with dedicated certification teams. Stakeholders must monitor upcoming amendments to the Energy Efficiency Regulations and assess whether smart-appliance data governance obligations will require restructuring of cloud-service architectures.
Market Dynamics
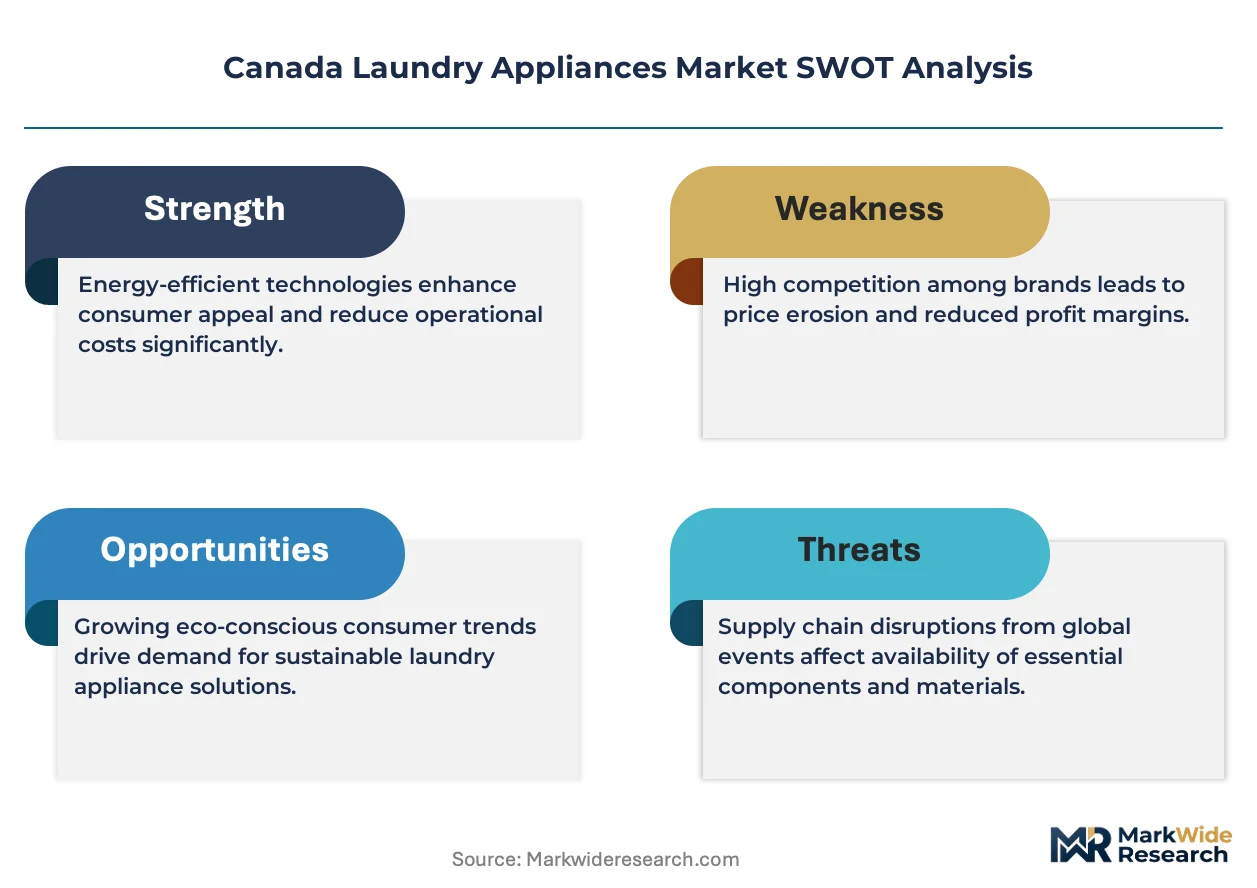
Natural Resources Canada's EnerGuide labeling program is tightening energy-performance thresholds for imported appliances, forcing suppliers to restructure product portfolios around heat-pump drying technology and inverter-driven motor systems.
Growth Catalysts
- Multi-unit residential construction:Toronto and Vancouver condominium developers are expanding procurement of stackable and integrated laundry systems to maximize floor-area ratio in micro-units.
- Energy Efficiency Regulations:Federal amendments to minimum performance standards are pulling forward replacement demand as older stock faces compliance obsolescence.
- Heat-pump drying:This technology is capturing share in the premium residential segment by reducing operating costs and aligning with provincial carbon-reduction mandates.
Market Restraints
- Steel and copper input volatility:Drum assemblies and motor windings face cost pressure from commodity price swings, compressing margin on mid-tier product lines.
- Import concentration risk:Assembly-dependent suppliers rely on single-source motor and control module shipments from Asian manufacturing clusters, exposing inventory to port congestion.
- Gas connection infrastructure:Declining availability of natural gas hookups in new Toronto and Vancouver multi-unit builds limits addressable market for gas-heated dryers.
Strategic Opportunities
- Subscription-enabled diagnostics:Smart-appliance connectivity allows manufacturers to capture recurring revenue through predictive maintenance and remote troubleshooting services.
- Long-term care facility outsourcing:Commercial linen service providers are expanding on-premise laundry contracts, creating demand for industrial-capacity equipment with 75-pound load ratings.
- Quebec market underpenetration:Provincial hydroelectric pricing advantages favor electric heat-pump adoption, yet distribution density lags Ontario and British Columbia.
Industry Challenges
- Dual certification timelines:Canadian Standards Association electrical safety approval and Natural Resources Canada efficiency verification create sequential bottlenecks for new product launches.
- Smart-appliance data governance:Cloud-service architectures must adapt to evolving federal privacy obligations and provincial consumer protection standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Laundry Appliances Market |
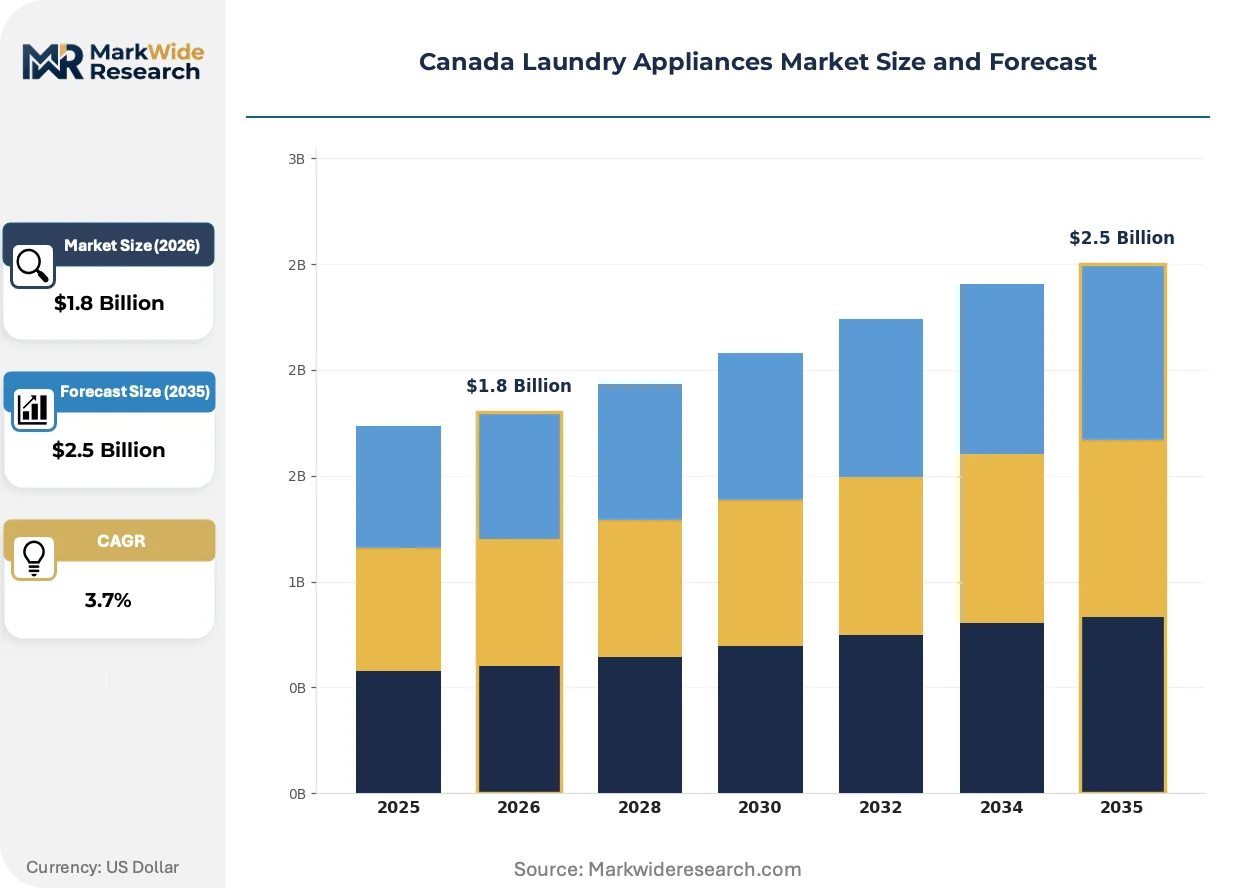
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Portable Washers End User: Residential, Commercial, Industrial, Educational Institutions Technology: Smart Appliances, Energy-Efficient, Conventional, Steam Technology Installation Type: Freestanding, Built-in, Stackable, Integrated |
| Companies Covered | LG, Whirlpool, Samsung, GE Appliances, Electrolux, Maytag, Haier, Kenmore, Danby Products Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Laundry Appliances Market Strategic Shifts
Heat-pump drying systems and AI-driven cycle optimization are compressing the performance gap between compact urban installations and full-capacity suburban units, while connectivity features unlock new service revenue models.
Heat-pump drying technology recovers waste heat through closed-loop refrigerant cycles, delivering A+++ efficiency ratings without venting requirements. Multi-unit developers in Vancouver and Toronto are specifying these systems in 80 percent of new micro-condominium projects. Ventless heat-pump configurations are supplanting traditional ducted electric dryers in buildings where exterior penetration is restricted by envelope codes.
Natural Resources Canada is finalizing amendments to the Energy Efficiency Regulations that will tighten minimum integrated modified energy factor thresholds for residential clothes washers. The proposed standards will disqualify conventional agitator-top-load designs from the Canadian market entirely. Front-load platform suppliers are accelerating inverter-motor and load-sensing investments to secure pre-compliance positioning.
Multi-unit residential buyers are consolidating procurement through direct-developer relationships rather than retail channel distribution, compressing traditional dealer margins. Property management groups are negotiating fleet-service agreements that bundle equipment, installation, and predictive maintenance under single-contract structures. This channel migration is most visible in Ontario's Greater Toronto Area, where three developers control 40 percent of annual condominium completions.
Canada Laundry Appliances Market Segmentation
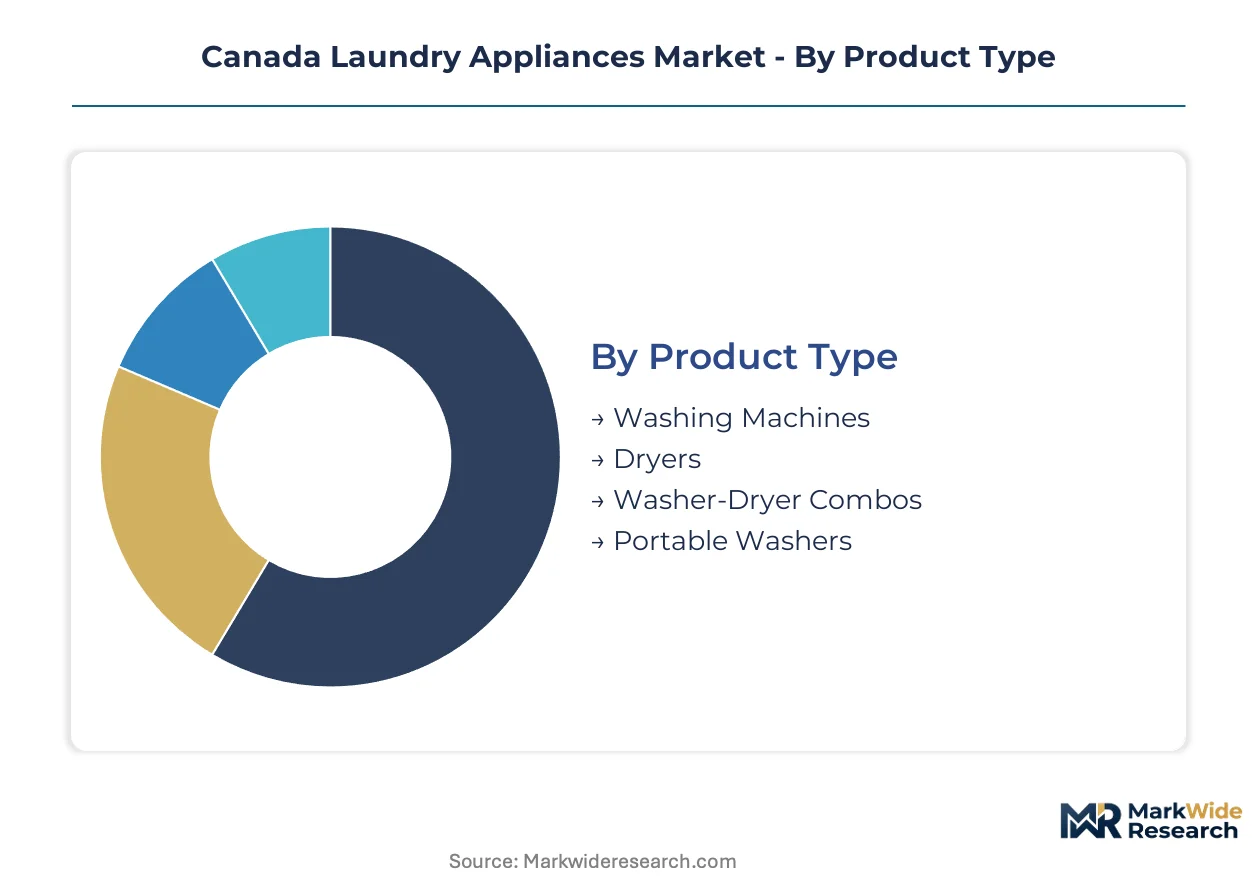
Segmentation in the Canada laundry appliances market reveals how regulatory pressure and urban density reshape procurement patterns across product categories. Understanding these divisions exposes where EnerGuide compliance costs concentrate and which installation formats capture Toronto and Vancouver condominium demand.
Product Type:
Substitution pressure from washer-dryer combos and heat-pump alternatives is fragmenting the traditional washing machine-dryer duopoly, forcing suppliers to defend volume positions through efficiency upgrades.
- Washing Machines:Front-load platforms with inverter-driven motors and load-sensing controls dominate residential procurement. Ontario and British Columbia condominium developers specify these units in 60 percent of new multi-unit projects, pulled by Natural Resources Canada efficiency thresholds that disqualify conventional agitator designs.
- Dryers:Heat-pump configurations recover waste heat through closed-loop refrigerant cycles, eliminating venting requirements. Vancouver micro-condominium developers now specify these systems in 80 percent of new builds, responding to envelope codes that restrict exterior penetration.
- Washer-Dryer Combos:Single-unit ventless designs capture space-constrained installations in Toronto and Vancouver where floor-area ratio maximization drives developer preference.
- Portable Washers:Compact units serve rental markets and secondary suites in Quebec and Atlantic Canada where permanent installation is prohibited.
Washing machines anchor the volume base while washer-dryer combos gain share at the steepest rate.
End User:
Cost tier divergence separates capital-intensive commercial installations from price-sensitive residential replacement cycles, with industrial buyers commanding longest equipment lifecycles.
- Residential:Multi-unit developers in the Greater Toronto Area consolidate procurement through direct relationships, bypassing retail channels entirely. Three developers control 40 percent of annual condominium completions, negotiating fleet-service agreements that bundle equipment with predictive maintenance.
- Commercial:Hospitality linen service providers and long-term care facilities drive demand for industrial-capacity equipment with 75-pound load ratings. Outsourcing trends in Ontario and British Columbia expand on-premise laundry contracts for institutional buyers.
- Industrial:Heavy-duty continuous-batch systems serve textile processors and uniform rental operations with 24-hour operational requirements.
- Educational Institutions:Universities and college residences in Ontario specify card-operated laundry systems with central monitoring capabilities.
Residential demand dominates unit volume while commercial applications deliver the highest margin per installation.
Technology:
Application focus determines technology adoption, with smart connectivity penetrating premium residential segments while energy efficiency becomes table stakes across all tiers.
- Smart Appliances:AI-driven cycle optimization and subscription-enabled diagnostics allow manufacturers to capture recurring revenue through remote troubleshooting. These systems face data governance obligations under evolving federal privacy standards and provincial consumer protection codes.
- Energy-Efficient:Heat-pump drying and inverter-motor platforms align with provincial carbon-reduction mandates and Natural Resources Canada minimum performance standards.
- Conventional:Agitator-top-load washers face compliance obsolescence under pending Energy Efficiency Regulations amendments.
- Steam Technology:Sanitization cycles target healthcare and hospitality end users with hygiene certification requirements.
Energy-efficient technology commands the broadest addressable market while smart appliances capture the steepest expansion trajectory.
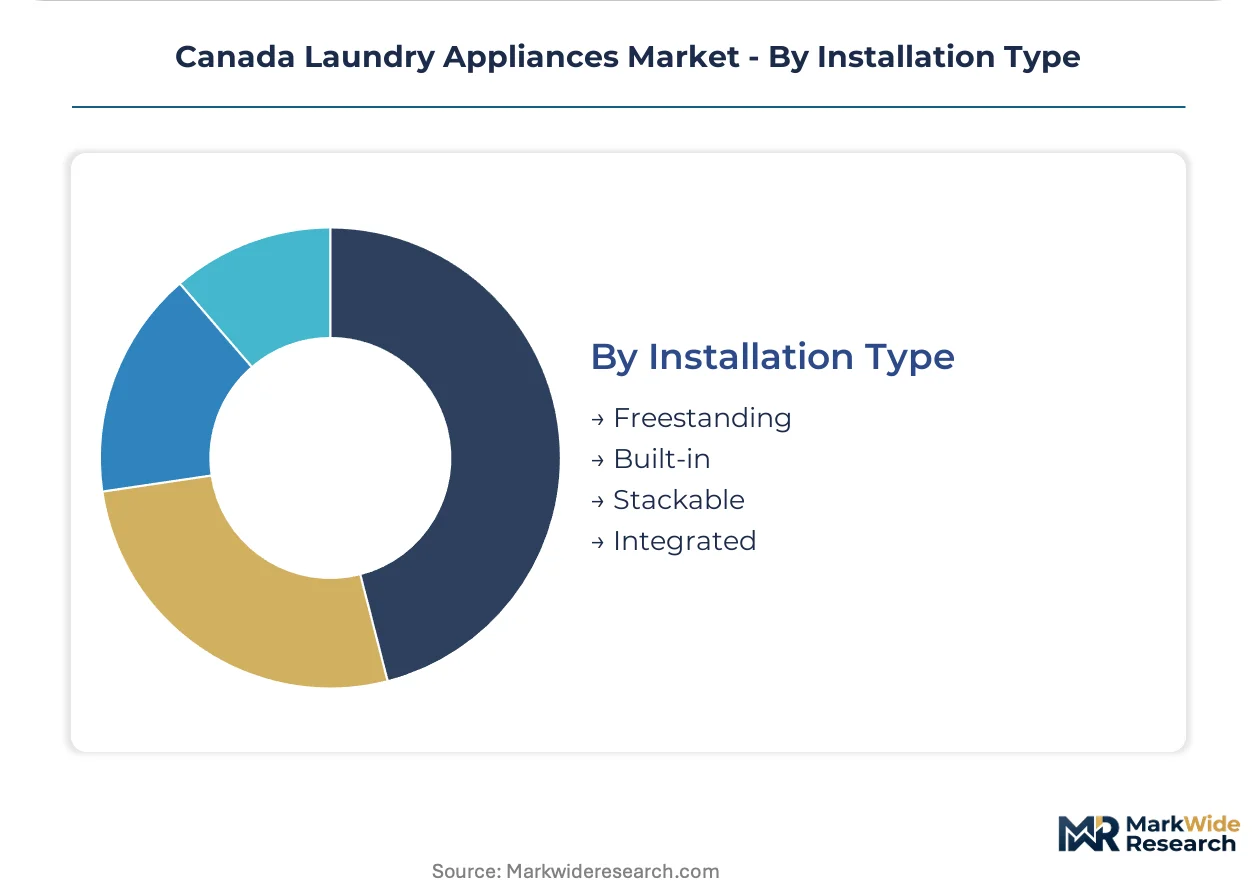
Installation Type:
Customer type fragmentation separates developer-specified integrated systems from retail-purchased freestanding units, with stackable formats bridging both channels.
- Freestanding:Premium-brand units compete on design aesthetics and connectivity features in suburban single-family replacement cycles.
- Built-in:Cabinet-integrated designs align with high-end condominium fit-out specifications in Vancouver and Toronto.
- Stackable:Vertical configurations maximize floor-area ratio in micro-units, specified by 80 percent of Toronto and Vancouver multi-unit developers.
- Integrated:Concealed laundry systems with matching cabinetry capture ultra-premium residential and boutique hospitality segments.
Freestanding units maintain the largest installed base while stackable configurations climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario and British Columbia deploy stackable heat-pump systems at triple the rate of Prairie Provinces, where gas-heated dryers retain infrastructure advantage.
Ontario
Greater Toronto Area condominium developers specify front-load inverter-motor washers in 60 percent of new multi-unit projects. Natural Resources Canada EnerGuide amendments disqualify conventional agitator designs from 2026 compliance windows. Three developers control 40 percent of annual completions in the GTA, negotiating fleet-service agreements that bundle equipment with predictive maintenance.
British Columbia
Vancouver micro-condominium builders mandate ventless heat-pump dryers in 80 percent of new builds to satisfy envelope codes restricting exterior penetration. Provincial carbon-reduction mandates accelerate electric heat-pump adoption over gas alternatives. Metro Vancouver's density bonuses incentivize floor-area ratio maximization through stackable laundry configurations.
Quebec
Hydroelectric pricing advantages favor electric dryer adoption yet distribution density lags Ontario and British Columbia. The province's building code amendments tighten energy-performance thresholds for multi-unit residential equipment. Montreal's rental market drives portable washer demand where permanent installation is prohibited in secondary suites.
Alberta
Single-family suburban replacement cycles sustain freestanding unit volume in Calgary and Edmonton corridors. Natural gas infrastructure availability preserves gas-heated dryer share unlike Toronto or Vancouver. Regional energy efficiency rebates lag federal EnerGuide enforcement timelines.
Atlantic Canada
Rental-heavy housing stock in Halifax and St. John's sustains portable and compact washer demand. Provincial efficiency programs operate on delayed adoption schedules compared to central Canada. Secondary suite proliferation in university towns drives card-operated laundry system specifications.
Canada Laundry Appliances Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Canada laundry appliances. Whirlpool maintains captive Ontario production capacity for drum motors and control systems, while LG and Samsung anchor import-dependent positions through R&D intensity and brand strength respectively. Electrolux occupies the commercial-grade equipment segment for hospitality and institutional buyers. Competitive moves concentrate on direct-developer procurement relationships and heat-pump technology licensing to satisfy tightening Natural Resources Canada efficiency thresholds.
Within the integrated manufacturing tier, Whirlpool Corporation represents the domestic production archetype with Ontario-based assembly operations. LG Electronics Inc. and Samsung Electronics Co., Ltd. exemplify the import-dependent R&D-intensive model, leveraging smart-appliance connectivity and AI-driven cycle optimization to capture premium residential margins. These three entities anchor the competitive structure through divergent supply chain configurations.
| Leading Market Players |
|---|
| LG |
| Whirlpool |
| Samsung |
| GE Appliances |
| Electrolux |
| Maytag |
| Haier |
| Kenmore |
| Danby Products Ltd. |
| Others |
Value Chain & Pricing Dynamics
Natural Resources Canada's EnerGuide certification gates both supplier qualification and price differentiation simultaneously, forcing non-compliant imports into discount positioning while certified heat-pump platforms command premium placement in Toronto and Vancouver developer specifications.
Pricing Analysis
Long-term fleet-service agreements dominate procurement between multi-unit developers and equipment suppliers, compressing traditional retail margins. Pricing stratifies across premium smart-connected tiers, mid-tier efficiency-compliant platforms, and economy imports facing compliance obsolescence. Cost compression in mid-tier product lines is intensifying because steel and copper input volatility erodes drum assembly margins. Residential replacement buyers exhibit highest price sensitivity, while commercial linen service providers prioritize lifecycle operating costs over upfront capital outlay.
Supply Chain Analysis
Port congestion at Vancouver and Prince Rupert terminals creates inventory chokepoints for Asian-sourced motor and control module shipments. Assembly operations draw from China, South Korea, and Mexico for drum motors, inverter systems, and electronic control boards. Single-source vulnerability concentrates in heat-pump compressor supply, where Korean and Japanese manufacturers anchor global capacity. Distribution runs through direct-developer procurement channels in Ontario and British Columbia, bypassing traditional appliance retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-appliance connectivity ecosystems are reshaping Canada laundry appliances into platform-economics terrain, where predictive maintenance subscriptions and AI-driven cycle optimization create recurring revenue interoperability with property management software stacks.
For Market Incumbents: Compound captive production advantages in Ontario by deepening backward integration into heat-pump compressor technology, insulating against Korean supplier concentration. Secure Canadian Standards Association pre-approval positioning ahead of Natural Resources Canada efficiency amendments to lock out import-dependent competitors. Vertical control over drum motor manufacturing defends margin position against steel input volatility threatening mid-tier product lines. For New Entrants and Emerging Players: Predictive maintenance service gaps in Quebec and Atlantic Canada expose under-served commercial linen operators and long-term care facilities lacking fleet-service coverage. Target provincial hydroelectric pricing advantages in Quebec for electric heat-pump penetration where distribution density lags Ontario. Pursue direct-developer relationships in Montreal's rental-heavy secondary suite market with portable washer configurations bypassing permanent installation requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commercial laundry equipment specialists holding Ontario and British Columbia institutional contracts. Five-to-ten year viability hinges on heat-pump technology licensing portfolios and EnerGuide pre-compliance positioning. Monitor Natural Resources Canada amendment finalization timing as inflection indicator for compliance-obsolete inventory write-downs among import-dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Licensing | Secures Natural Resources Canada compliance positioning ahead of efficiency threshold tightening. |
| Direct-Developer Procurement Partnership | Bypasses retail margin compression in Toronto and Vancouver multi-unit construction. |
| Predictive Maintenance Platform Launch | Captures recurring revenue through AI-driven cycle optimization and remote diagnostics. |
| Backward Integration into Compressor Supply | Reduces single-source vulnerability from Korean and Japanese component concentration. |
| Quebec Distribution Network Expansion | Exploits hydroelectric pricing advantages for electric heat-pump adoption in underpenetrated province. |
Study Parameters
Desk research of Natural Resources Canada regulatory filings, Canadian Standards Association certification databases, and provincial building code amendments preceded structured interviews with multi-unit residential developers, commercial linen service operators, and appliance procurement directors at long-term care facilities. Secondary validation drew from EnerGuide efficiency standard documentation, condominium completion permits in Toronto and Vancouver, and hospitality industry outsourcing trend reports. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Variance decomposition across product type, end user, technology tier, and installation format anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory compliance timelines. Modeled inputs included heat-pump adoption curves in multi-unit residential construction, fleet-service contract penetration rates, and provincial energy efficiency rebate program allocations.
Forecasts assume regulatory continuity in Natural Resources Canada EnerGuide enforcement and Canadian Standards Association electrical safety regimes; material policy shifts would require re-modeling of import qualification thresholds and compliance cost structures. Practitioners should keep alternative scenarios live as provincial carbon-reduction mandate stringency and port infrastructure capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Australia Washing Machine Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Residential Washing Machine Market
Home Appliances
Household Appliance Market
Home Appliances
Germany Washing Machine Market
Home Appliances
South Africa Home Appliances Market