
 Workout Clothes Market | 2026-2036
Workout Clothes Market Size, Share, and Industry Trends Forecast 2026-2036
Workout Clothes Market Analytics
Aftermarket service revenue from repair and resale platforms is narrowing the traditional gap between premium retail and secondary channels. Nike leverages direct-to-consumer digital infrastructure to control pricing across regions. Lululemon Athletica anchors its margin pool in technical fabric R&D rather than volume manufacturing. Columbia Sportswear Company competes through specialized outdoor-performance positioning that commands seasonal loyalty.
Workout clothes are engineered garments constructed from moisture-wicking synthetic blends or performance-treated natural fibers, typically incorporating elastane for stretch recovery and flatlock seams to reduce friction during repetitive motion. Their primary commercial purpose is to regulate thermoregulation and reduce physical impedance across exercise modalities. Leggings and sports bras within the product type category carry the highest margin density due to technical construction requirements and repeat purchase frequency. Polyester dominates the fabric type landscape for its durability and sublimation-print compatibility, though spandex blends are capturing share in high-compression applications. The usage occasion dimension shows yoga and casual wear converging as athleisure erodes formal boundaries between gym and street contexts.
The US Federal Trade Commission enforces textile labeling standards that mandate fiber content disclosure, while the EU REACH regulation restricts hazardous chemical inputs in dye and finishing processes. China's SAMR oversees national standards for textile safety that affect import eligibility and domestic production compliance. Stakeholders must monitor how diverging chemical safety thresholds between regulatory regimes reshape sourcing decisions and regional manufacturing footprints.
Market Dynamics
REACH enforcement by ECHA is compressing dye-house capacity across Europe while China's SAMR tightens import testing protocols, forcing brands to dual-source certified fabric from Vietnam and Indonesia to maintain cross-border shipment eligibility.
Growth Catalysts
- EU REACH chemical restrictions:Mandatory substitution of azo dyes and PFAS finishes is accelerating certified supply chain partnerships between brands and Bluesign-approved mills.
- Boutique studio merchandise procurement:SoulCycle and Barry's Bootcamp are expanding private-label apparel as member retention tools, creating captive demand for small-batch technical production.
- Seamless knitting automation:Whole-garment 3D knitting from Shima Seiki equipment is reducing cut-and-sew labor costs while enabling zero-waste pattern construction.
Market Restraints
- Petroleum-based input volatility:Polyester chip prices track crude oil futures, compressing margin stability for mid-tier brands without long-term polymer contracts.
- Concentrated elastane supply:Spandex fiber production clusters in China and South Korea, creating single-source vulnerability for compression garment manufacturers.
- Biodegradability-performance tradeoff:Cellulosic alternatives to synthetic wicking fabrics degrade tensile strength after repeated wash cycles, limiting replacement rates.
Strategic Opportunities
- India domestic manufacturing:PLI scheme incentives for technical textiles are attracting sewing automation investments in Tiruppur and Surat clusters.
- Textile-to-textile chemical recycling:Carbios enzymatic depolymerization paired with polyester regeneration is enabling closed-loop feedstock for performance fabrics.
- Resale platform integration:ThredUp and Depop partnerships allow brands to capture secondary-market margin while controlling authentication standards.
Industry Challenges
- Technical pattern engineering talent:Compression fit algorithm specialists command premium salaries, constraining scaling for emerging direct-to-consumer entrants.
- Multi-standard certification timelines:Simultaneous OEKO-TEX, bluesign, and GOTS approvals extend product development cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workout Clothes Market |
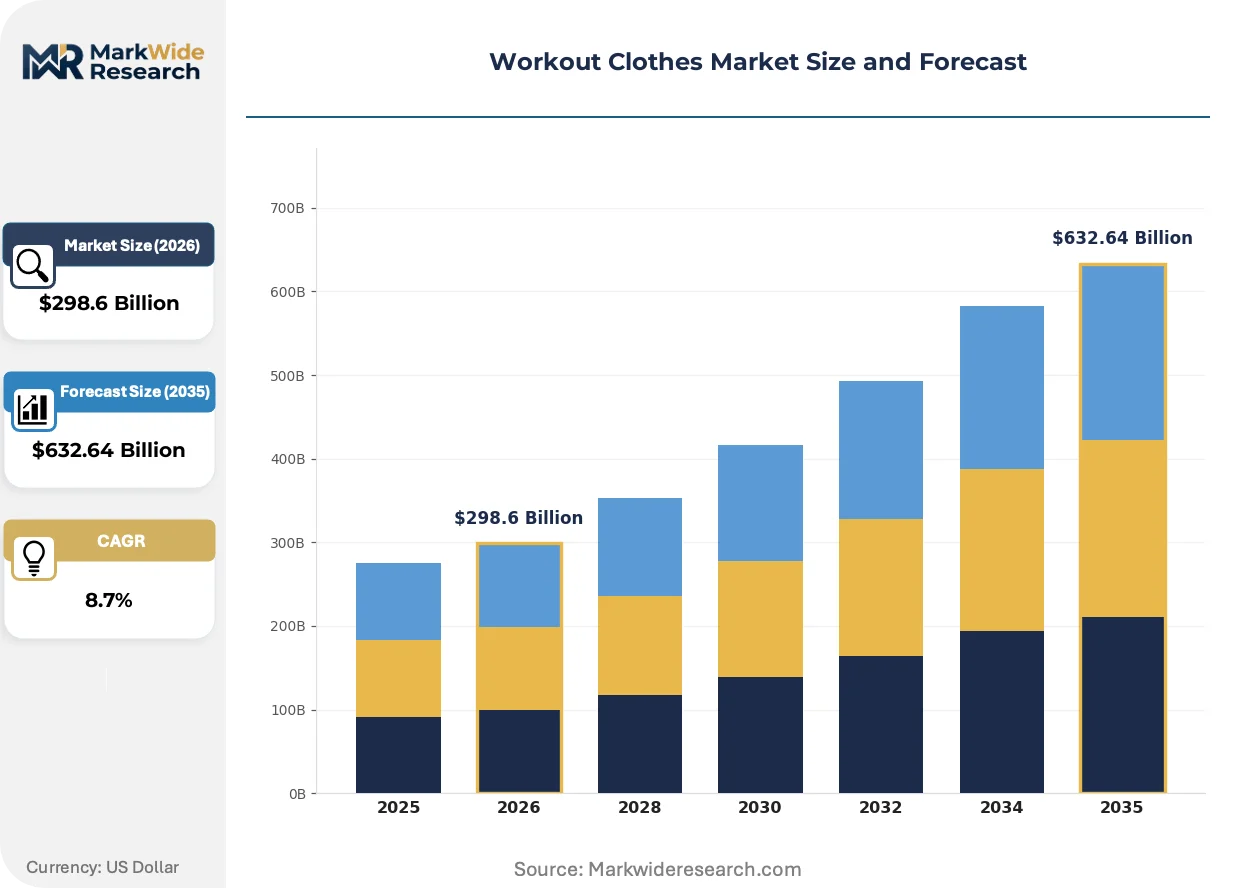
| Market Size in 2026 | $298.6 Billion |
| Market Size in 2035 | $632.64 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shorts, T-Shirts, Leggings, Sports Bras Fabric Type: Spandex, Cotton, Polyester, Nylon Target Audience: Men, Women, Children, Athletes Usage Occasion: Fitness, Yoga, Running, Casual Wear |
| Companies Covered | Nike, Adidas, Lululemon Athletica, Columbia Sportswear Company, Anta Sports, Li Ning Group, Puma, Gymshark, Athleta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workout Clothes Market Evolving Landscape
Performance fabric development is pivoting from petroleum-dependent synthetics toward bio-engineered alternatives and closed-loop chemical processes. Regulatory chemical restrictions and consumer material transparency demands are converging to reshape upstream R&D allocation.
Biopolymer feedstocks derived from agricultural waste streams are migrating from pilot-scale production to commercial volume. Algae-based polyester alternatives from Keel Labs and mango-fiber cellulose from Fruitex are securing shelf space at REI and Decathlon. This migration from niche sustainability marketing to cost-competitive bulk procurement is compressing the premium pricing window for conventional petroleum-based performance fabrics.
EU REACH Annex XVII restrictions on microplastic shedding from synthetic textiles are mandating filtration upgrades at municipal wastewater facilities in France and Germany. Industrial consequence includes pre-treatment certification requirements for imported garments entering Dutch and Belgian ports. Yoga and swimwear categories face the steepest compliance costs due to high elastane content and direct skin-contact classification.
Repair and resale service unbundling is fragmenting the traditional retail-channel relationship. Patagonia's Worn Wear and Lululemon's Like New programs capture post-purchase customer data while reducing new-unit production forecasts. This behavior shift concentrates in coastal US metropolitan markets and Scandinavian capitals where circular-economy literacy correlates with household apparel expenditure levels.
Workout Clothes Market Segmentation
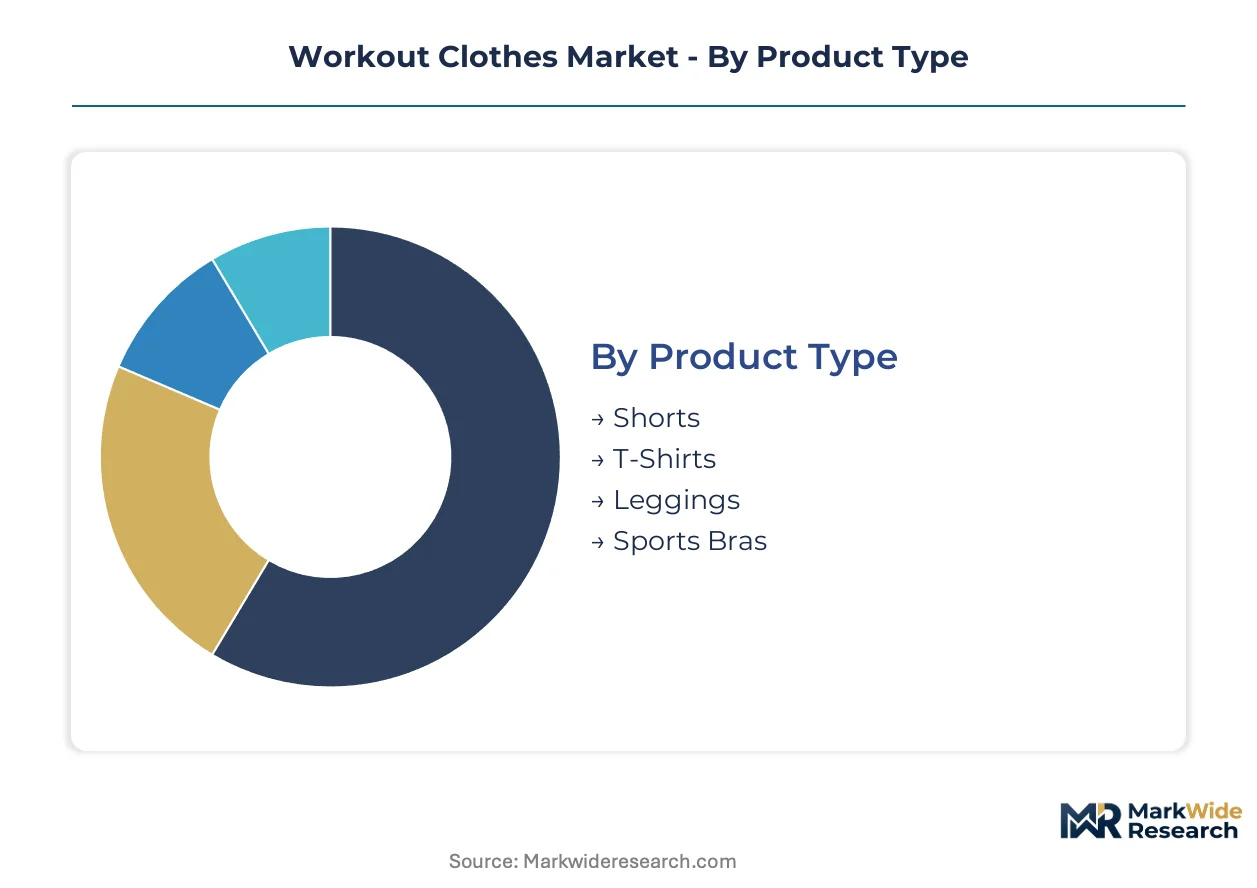
Workout clothes segmentation tracks how technical specifications, demographic targeting, and activity-specific engineering create distinct margin pools. Purchase frequency and replacement cycles vary dramatically across these dimensions, reshaping inventory planning and marketing spend allocation.
Product Type:
Replacement velocity separates these segments: sports bras and leggings turn over fastest due to elastic fatigue, while shorts and T-shirts enjoy longer functional lifespans.
- Leggings:High-compression knit constructions with flatlock seams and gusseted crotches dominate technical specifications. Demand concentrates in yoga studio retail channels and direct-to-consumer subscriptions, driven by repeat purchase patterns tied to fabric pilling thresholds.
- Sports Bras:Encapsulation and compression hybrid designs with moisture-wicking linings and adjustable straps define the category. Growth clusters in high-impact training segments across boutique fitness memberships, constrained by sizing complexity that elevates return rates.
- Shorts:Built-in liner configurations and anti-chafe seam placements serve running and CrossFit modalities. Marathon registration volumes in Berlin and Chicago drive seasonal procurement spikes.
- T-Shirts:Sublimation-printed polyester or triblend constructions with anti-odor treatments anchor team sports and gym uniform contracts. Bulk institutional orders from university athletic departments sustain volume manufacturing.
Leggings dominate installed base. Sports bras are where expansion concentrates.
Fabric Type:
Raw material cost tiers stratify competitive positioning, with petroleum-derived synthetics facing margin pressure against certified natural alternatives.
- Polyester:Sublimation-compatible filament yarns with wicking finishes and UV protection ratings define performance specifications. China's Zhejiang province hosts the densest concentration of dye-sublimation printing capacity, attracting brand sourcing offices from Decathlon and REI.
- Spandex:Elastane blends delivering 15-30% stretch recovery for compression applications command premium pricing. Supply vulnerability concentrates in South Korea's Hyosung facilities and select Chinese state-owned producers, constraining scaling for emerging brands.
- Nylon:Abrasion-resistant filament constructions serve outdoor and swim crossover applications. REACH-compliant dyeing requirements in EU markets elevate certification costs for imported finished goods.
- Cotton:Performance-treated ring-spun or combed varieties with enzyme washes compete in casual-athleisure convergence. India's Maharashtra ginning clusters supply organic-certified feedstock for GOTS-labeled collections.
Polyester commands volume leadership. Spandex captures the steepest expansion trajectory.
Target Audience:
Demographic purchasing power and channel access create divergent margin architectures across these segments.
- Women:Technical construction requirements for sports bras and leggings elevate average unit economics. Lululemon's direct-to-consumer infrastructure and Nike's member apps concentrate digital wallet share in this segment.
- Men:Team sports uniform contracts and gym-loyalty program subscriptions sustain bulk order flows. Compression base-layer demand from CrossFit and HYROX participation drives incremental volume.
- Athletes:Federations and professional team procurement offices mandate certified performance specifications with batch testing documentation. Anti-doping compliance requirements extend to fabric chemistry disclosure.
- Children:Growth-spurt-driven replacement cycles and school physical education mandates create predictable seasonal demand. Flame-retardant and chemical-safety certifications constrain supplier qualification pools.
Women anchor revenue concentration. Athletes deliver the highest per-unit margins.
Usage Occasion:
Activity-specific biomechanical demands determine technical specification depth and pricing tolerance.
- Yoga:Four-way stretch requirements and minimal seam placement for floor contact define construction priorities. Studio retail partnerships with teacher training programs create captive distribution channels.
- Running:Reflective detailing, chafe-resistant linings, and weather-adaptive layering systems dominate R&D allocation. Marathon expo retail and specialty run-shop networks sustain premium positioning.
- Casual Wear:Athleisure convergence erodes technical-performance thresholds in favor of aesthetic versatility. Social commerce discovery through Instagram and TikTok Shop accelerates trend-cycle compression.
- Fitness:General gym training accommodates broader sizing ranges and lower price points. Big-box sporting goods and Amazon private-label penetration concentrates volume here.
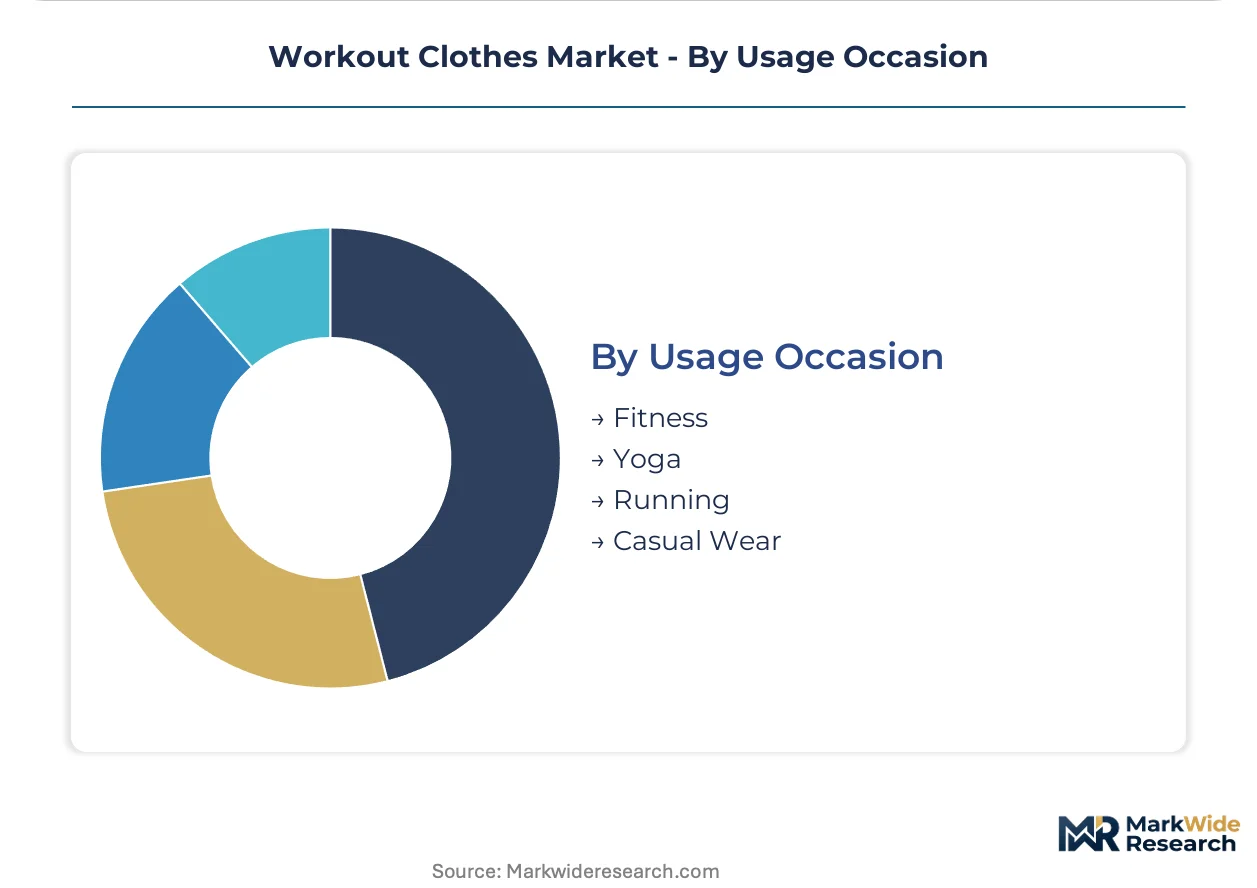
Casual Wear dominates unit volume. Yoga commands the highest margin density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: European buyers prioritize certified chemical safety, US consumers favor direct-to-consumer brand relationships, and Asian markets blend domestic manufacturing scale with rising per-capita fitness participation.
United States
Boutique fitness studio expansion and marathon event registrations drive apparel procurement cycles. The FTC enforces mandatory fiber content disclosure under textile labeling standards. Portland, Oregon hosts concentrated outdoor-performance brand headquarters and technical fabric R&D operations.
China
Domestic sportswear brands are scaling captive manufacturing while per-capita gym membership rises in tier-one cities. SAMR oversees national textile safety standards affecting both import eligibility and domestic production compliance. Zhejiang province maintains the densest concentration of dye-sublimation printing capacity serving international brand sourcing offices.
Germany
Running event participation and outdoor recreation culture sustain premium technical apparel demand. ECHA REACH Annex XVII restrictions on microplastic shedding mandate pre-treatment certification for imported garments entering Dutch and Belgian ports. Bavaria clusters specialized outdoor-performance retail and distribution infrastructure.
India
School physical education mandates and youth sports league expansion create predictable seasonal demand for children's athletic wear. The PLI scheme for technical textiles attracts sewing automation investments. Tiruppur and Surat clusters are consolidating dyeing and finishing capacity with Bluesign certification upgrades.
South Korea
HYROX and CrossFit participation growth drives compression base-layer demand among urban fitness consumers. MFDS regulates chemical safety in skin-contact textiles alongside import testing protocols. Hyosung facilities near Seoul anchor concentrated elastane fiber production serving regional garment manufacturers.
Workout Clothes Market Competitive Landscape
Capability concentration sits with technical fabric specialists; scale advantage sits with vertically integrated sportswear conglomerates. The market structures around three tiers: global sportswear houses with direct-to-consumer infrastructure, premium athleisure specialists anchored in R&D differentiation, and emerging direct-to-consumer entrants leveraging social commerce discovery. Dominant competitive moves include strategic partnerships with certified dye houses and portfolio diversification into repair and resale service integration.
Within the premium technical tier, Lululemon Athletica and Nike occupy positions defined by contrasting margin architectures—one anchored in proprietary fabric development, the other in digital pricing control across regions. Anta Sports represents the scale-driven domestic champion model, consolidating Chinese manufacturing capacity while expanding retail footprint. Columbia Sportswear Company exemplifies specialized outdoor-performance positioning that commands seasonal loyalty through technical credibility rather than fashion velocity.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Lululemon Athletica |
| Columbia Sportswear Company |
| Anta Sports |
| Li Ning Group |
| Puma |
| Gymshark |
| Athleta |
| Others |
Value Network & Pricing Analysis
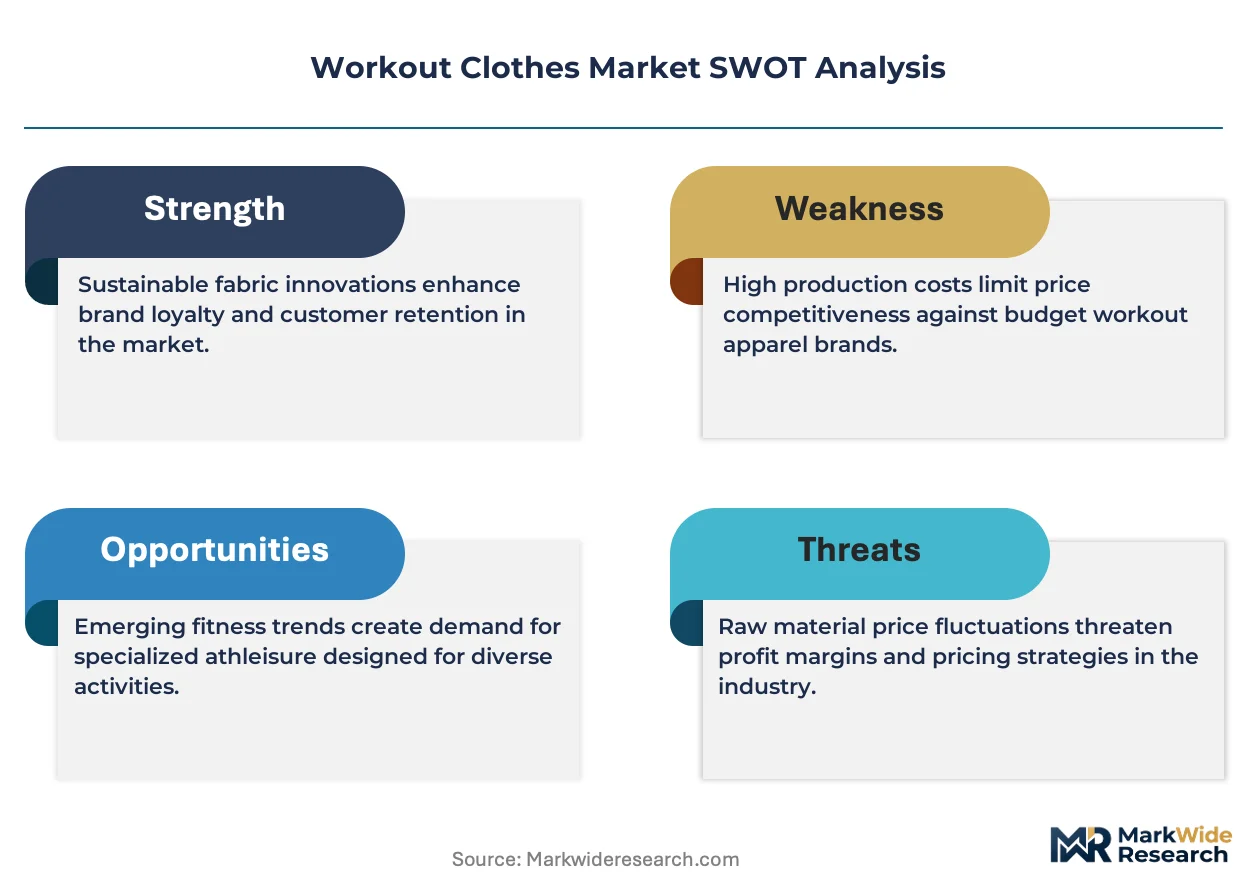
Petroleum-based input volatility determines both tiered pricing spreads across premium, standard, and economy levels and the geographic shape of polyester sourcing. Crude oil futures tracking compresses margin stability for mid-tier brands lacking long-term polymer contracts while pushing procurement offices toward dual-source arrangements in Vietnam and Indonesia.
Pricing Analysis
Long-term offtake contracts dominate raw material procurement for volume manufacturers while spot purchasing serves emerging direct-to-consumer entrants testing demand. Three-tier pricing structure across premium, standard, and economy levels separates Bluesign-certified technical collections from uncertified bulk production and private-label economy lines. Pricing pressure stems from elastane supply concentration in Hyosung facilities and select Chinese state-owned producers. Boutique fitness studios show least price sensitivity due to member retention value of branded merchandise; general gym training segments concentrate price sensitivity through Amazon private-label penetration.
Supply Chain Analysis
Contract manufacturing capacity clusters with Shenzhou International and Luen Thai in Vietnam, Youngone in Bangladesh, and vertically integrated operations in China's Zhejiang province. Polyester chip and spandex fiber feedstock draws from petroleum derivatives and concentrated elastane production in South Korea. Single-source vulnerability in elastane supply creates structural risk for compression garment scaling. Distribution runs through direct-to-consumer digital infrastructure, boutique studio retail partnerships, and marathon expo seasonal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to marathon event registration volumes and boutique studio expansion cycles. Fitness participation rebounds from pandemic-era lows drive replacement velocity in leggings and sports bra categories.
For Market Incumbents: Pre-empt emerging direct-to-consumer entrants by securing exclusive Bluesign-certified mill partnerships before REACH enforcement tightens dye-house capacity. Backward integration into seamless knitting automation via Shima Seiki equipment procurement reduces cut-and-sew labor exposure. Channel control through repair and resale platform integration captures secondary-market margin while reducing new-unit production forecast risk.
For New Entrants and Emerging Players: Build out social commerce discovery infrastructure targeting casual wear athleisure convergence where technical-performance thresholds erode fastest. India's PLI scheme for technical textiles offers the most penetrable geography with Tiruppur cluster automation investments and predictable seasonal demand from school physical education mandates. Go-to-market through TikTok Shop and Instagram storefronts accelerates trend-cycle compression without legacy wholesale overhead.
For Investors and Strategic Acquirers: EU REACH Annex XVII microplastic shedding restrictions reshape the acquisition landscape toward certified supply chain assets with pre-treatment documentation. Long-term viability favors targets with textile-to-textile chemical recycling partnerships enabling closed-loop feedstock. Watch HYROX and CrossFit participation growth as inflection signal for compression base-layer demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluesign Certification Investment | REACH compliance secures EU market access amid ECHA enforcement tightening. |
| Direct-to-Consumer Digital Infrastructure | Nike's member apps demonstrate pricing control across regional markets. |
| Seamless Knitting Automation | Shima Seiki equipment reduces labor costs while enabling zero-waste construction. |
| Resale Platform Integration | ThredUp partnerships capture secondary-market margin with authentication standards. |
| Biopolymer Feedstock Migration | Keel Labs algae-based alternatives compress petroleum-dependent synthetic premiums. |
Research Methodology
Cross-validation between primary interviews with brand sourcing managers, boutique studio procurement leads, and textile mill technical directors anchors the qualitative findings against secondary validation. Sourcing executives at Decathlon and REI, dye-house compliance officers, and marathon event organizers provided operational perspective. Secondary sources include ECHA REACH enforcement notices, SAMR textile safety standard updates, customs records from Zhejiang and Tiruppur clusters, and SEC 10-K disclosures from listed sportswear conglomerates. Bottom-up demand modeling from product-type replacement cycles triangulates with top-down market sizing.
Calibration against historical marathon registration volumes and boutique studio expansion rates tests projection sensitivity across the analysis window. Segmentation dimensions span product type, fabric technology tier, target demographic purchasing power, and usage occasion biomechanical intensity. CAGRs derive from elasticity-adjusted demand curves incorporating REACH compliance cost pass-through assumptions. Inputs include elastane supply concentration metrics and PLI scheme incentive uptake rates in Indian technical textile clusters.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by domestic Chinese champions or accelerated biopolymer scale-up by agricultural waste processors would shift outcomes. Quarterly review of ECHA enforcement actions, SAMR import testing protocol updates, and HYROX event calendar expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Athleisure Market
Sportswear
Sports Socks for Children Market
Sportswear
Activewear Market
Sportswear
Cycling Wear Market
Sportswear
Global Women Active Wear Market
Sportswear
Cycling Apparel Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
North America Dancewear Market
Sportswear
Casual Sportswear Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Bicycle Apparels Market
Sportswear
Athleisure Wear Market
Sportswear
Europe Dancewear Market