
 South Korea Major Home Appliances Market | 2026-2036
South Korea Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Major Home Appliances Market Analytics
A capital-intensity divergence between integrated semiconductor foundry operators and assembly-focused OEMs is rotating competitive advantage toward in-house chip design and refrigerant compressor manufacturing. Samsung Electronics leverages captive semiconductor production to anchor smart appliance ecosystems across premium refrigerator and air conditioner lines. LG Electronics sustains global compressor technology leadership through its dedicated appliance components division. Coway specializes in water purification and air care appliances, occupying a defensible niche in residential health-conscious segments.
Major home appliances encompass electrically powered domestic machines—refrigeration systems using vapor-compression cycles with R600a or R32 refrigerants, front-loading washers with direct-drive motors rated above 80% energy efficiency, convection ovens with ceramic or catalytic self-cleaning liners, and inverter-driven split-system air conditioners—designed for food preservation, textile cleaning, thermal cooking, and climate control in household and commercial environments. Refrigerators command the largest revenue pool among product types, though air conditioners generate the highest replacement frequency in coastal humidity zones. Smart appliances and IoT-enabled technology segments attract disproportionate R&D allocation as manufacturers embed AI-driven energy optimization and remote diagnostics, while conventional technology retains volume dominance in price-sensitive rental housing and industrial canteen procurement.
The Ministry of Trade, Industry and Energy (METI) enforces MEPS (Minimum Energy Performance Standards) and mandatory energy efficiency labeling that disqualifies sub-tier imports from retail placement, while the Korean Agency for Technology and Standards (KATS) administers KC certification for electromagnetic compatibility and electrical safety in connected appliances. MFDS oversight of antimicrobial materials used in refrigerator linings and water-contact surfaces adds compliance layers for health-claim positioning. Stakeholders must monitor evolving refrigerant phase-down schedules under the Kigali Amendment's national implementation plan and assess whether local inverter motor capacity can absorb surge demand from heat-pump dryer adoption without import dependency.
Market Dynamics
METI's tightened MEPS standards and mandatory energy labeling are compressing the addressable market for conventional compressor technology while accelerating inverter motor adoption across Seoul's apartment replacement cycles.
Growth Catalysts
- Heat-pump dryer technology:Residential complexes in Busan's industrial belt are specifying heat-pump dryers for new-build laundry facilities, displacing conventional vented units under stricter building energy codes.
- Kigali Amendment phase-down schedule:South Korea's national implementation plan for hydrofluorocarbon reduction is forcing refrigerant transitions toward R32 and R600a, creating replacement demand for compatible compressor systems.
- Smart apartment integration:Seoul metropolitan corridor developers are bundling IoT-enabled appliance packages into premium housing stock, pulling connected refrigerator and air conditioner volumes.
Market Restraints
- Copper and rare-earth magnet cost volatility:Inverter compressor manufacturing depends on neodymium magnet supply concentrated in Chinese processing facilities, exposing margin structures to input price swings.
- Import dependency for heat-pump dryer compressors:Domestic inverter motor capacity has not scaled to match projected heat-pump dryer demand, forcing reliance on Japanese and European component suppliers.
- Technical limitation in low-temperature heat-pump performance:Heat-pump dryers exhibit efficiency degradation below 5°C ambient conditions, restricting deployment in unheated utility spaces during Seoul winters.
Strategic Opportunities
- Jeolla Province underpenetration:Rural housing stock in South Korea's southwest maintains higher conventional appliance penetration, creating whitespace for inverter technology diffusion as grid infrastructure modernizes.
- MFDS antimicrobial certification:Health-conscious positioning through refrigerator lining and water-contact surface certification opens premium pricing in Seoul's high-income districts.
- AI-driven predictive maintenance convergence:Embedding machine learning diagnostics into compressor control systems enables service contract bundling and remote failure prevention.
Industry Challenges
- Inverter motor design talent scarcity:Domestic engineering programs produce insufficient specialists in permanent magnet motor topology optimization, forcing competition for limited expertise.
- KC certification timeline compression:KATS electromagnetic compatibility testing queues extend lead times for connected appliance launches, compressing product development windows.
- Legacy refrigerant service infrastructure:Existing technician certification and recovery equipment networks require wholesale reconfiguration to handle flammable R600a and higher-pressure R32 systems safely.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Major Home Appliances Market |
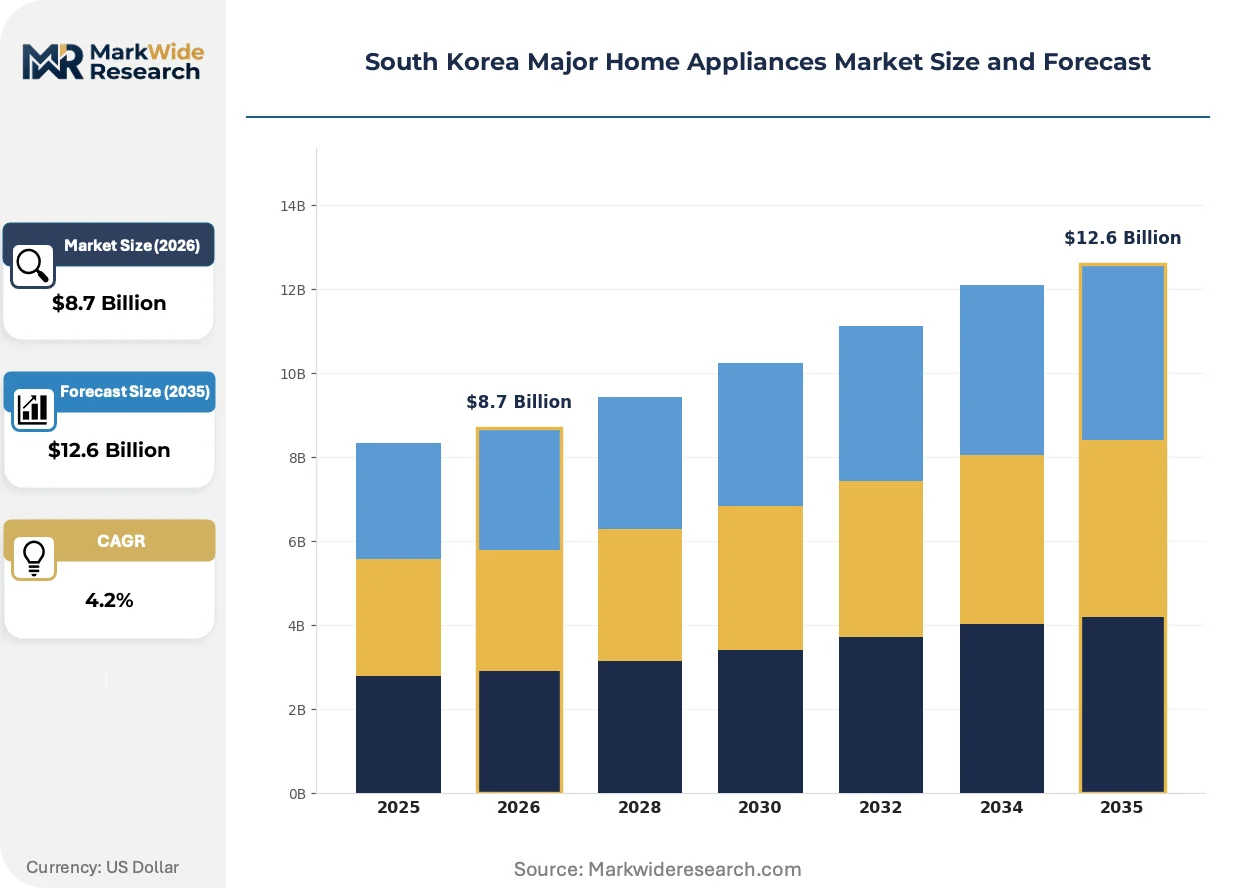
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Ovens, Air Conditioners Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Conventional End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | SK Magic, Cuckoo Electronics, LG Electronics, Hyosung TNC, Daewoo Electronics, Samsung Electronics, Coway, Hanil Electronics, Winia Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Major Home Appliances Market Evolving Landscape
Three intersecting developments are restructuring competitive advantage: compressor technology miniaturization, regulatory pressure on refrigerant chemistry, and procurement centralization through property developer bundling.
Inverter-driven variable-speed compressors are miniaturizing. These systems modulate cooling output through brushless DC motor control rather than binary on-off cycling. Seoul apartment developers are specifying them for premium unit packages to meet energy performance guarantees. The technology is miniaturizing mechanical footprints while expanding capacity ranges, enabling side-by-side refrigerator configurations previously requiring larger compressor housings.
METI's MEPS enforcement and Kigali Amendment alignment are tightening refrigerant constraints. Sub-tier imports failing efficiency thresholds face retail placement disqualification. Air conditioner manufacturers are responding with R32 transition roadmaps and heat exchanger redesigns to maintain coefficient of performance ratings under reduced refrigerant charge volumes.
Property developer procurement consolidation is displacing individual consumer channel volume. Major Seoul housing project tenders specify integrated appliance packages with unified control interfaces and centralized warranty administration. This concentrates demand among suppliers capable of multi-category fulfillment and IoT platform interoperability, compressing standalone retail transaction flows in the metropolitan corridor.
South Korea Major Home Appliances Market Segmentation
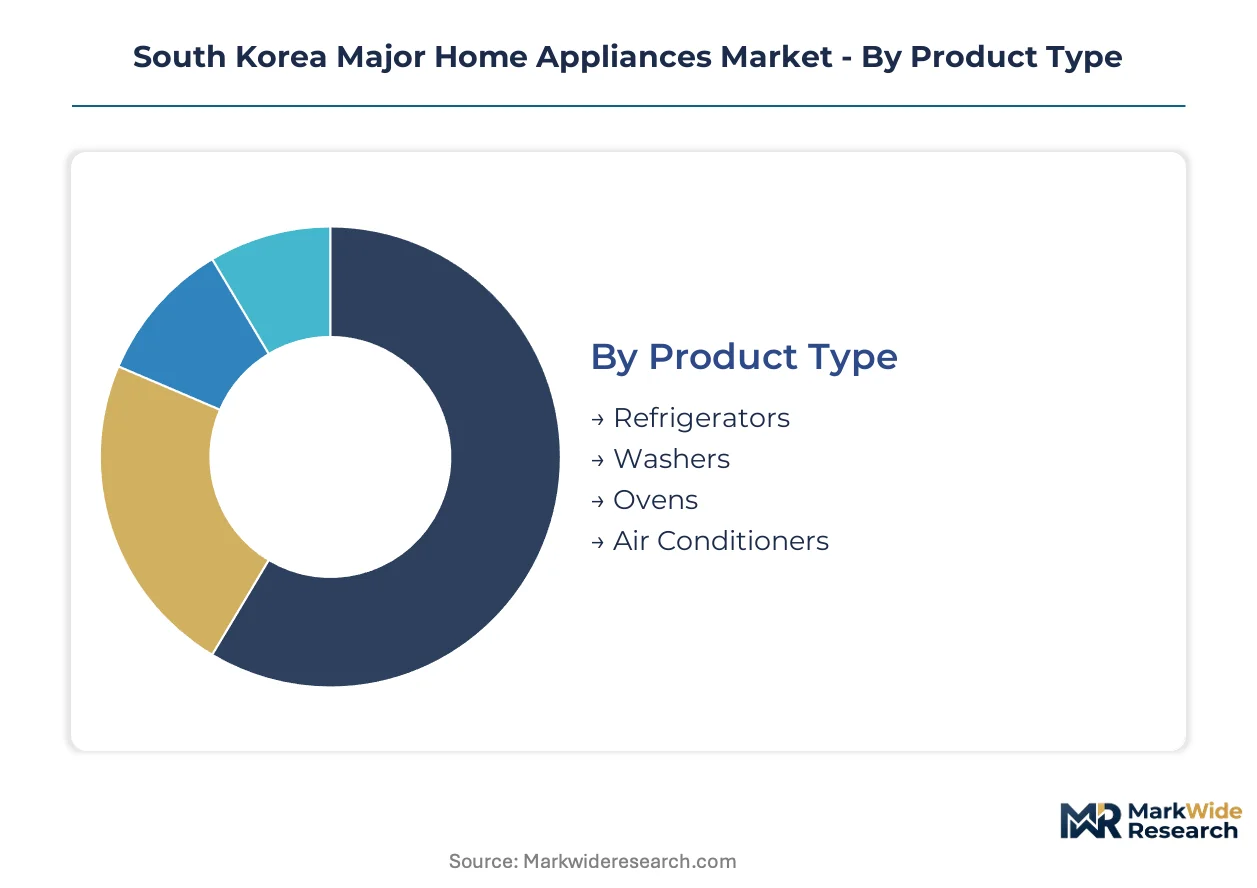
South Korea's appliance segmentation reflects regulatory pressure from METI's MEPS standards and KATS certification requirements. Distinct compliance thresholds across product categories and technology tiers create divergent competitive arenas for manufacturers and channel partners.
Product Type:
METI's energy labeling mandates apply differentially across cooling, cleaning, cooking, and climate control equipment, with refrigeration systems facing the most stringent efficiency thresholds under current standards.
- Refrigerators:Vapor-compression systems using R600a or R32 refrigerants with inverter-driven compressors dominate Seoul apartment replacement cycles. Seoul metropolitan corridor developers specify these for premium housing packages to meet building energy performance guarantees under tightened codes.
- Air Conditioners:Inverter-driven split systems generate the highest replacement frequency in coastal humidity zones around Busan. Kigali Amendment refrigerant phase-down schedules force transitions toward lower-GWP alternatives, accelerating compressor system turnover in existing housing stock.
- Washers:Front-loading direct-drive motors rated above 80% energy efficiency satisfy METI labeling requirements for residential placement.
- Ovens:Convection systems with ceramic or catalytic self-cleaning liners serve compact Seoul kitchen configurations.
Refrigerators handle the majority of throughput; air conditioners are gaining share fastest on replacement frequency in coastal zones.
Technology:
Cost tier differentiation separates premium connected systems from price-sensitive conventional equipment, with certification complexity driving margin stratification across the four technology tiers.
- Smart Appliances:AI-driven energy optimization and remote diagnostics embedded in refrigerator and air conditioner lines attract disproportionate R&D allocation. Seoul's smart apartment developers bundle these for unified control interfaces, pulling volume through property developer procurement consolidation.
- IoT-Enabled:Connected compressor control systems enable predictive maintenance service contracts. KATS electromagnetic compatibility testing queues extend lead times for these launches, compressing product development windows against certification backlogs.
- Energy-Efficient:Inverter compressors and heat-pump dryers satisfy METI's tightened MEPS standards for retail placement eligibility.
- Conventional:Binary on-off compressor technology retains volume dominance in price-sensitive rental housing and industrial canteen procurement outside Seoul's premium corridors.
Conventional technology still moves the largest unit volumes; smart appliances are climbing the fastest on developer bundling demand.
End User:
Application context determines performance requirements, with residential replacement cycles, commercial durability needs, and industrial duty cycles creating distinct specification environments.
- Residential:Seoul's dense apartment complexes drive replacement demand for connected kitchen and laundry equipment with space-constrained footprints. METI labeling standards push households toward inverter compressors during natural replacement windows.
- Commercial:Hospitality projects in Busan's industrial belt require integrated appliance packages with centralized warranty administration. Heat-pump dryer specifications for new-build laundry facilities displace conventional vented units under stricter building energy codes.
- Hospitality:Premium hotel developments in the Seoul metropolitan corridor specify multi-category fulfillment with IoT platform interoperability.
- Industrial:Canteen and food service operations in manufacturing zones maintain conventional technology penetration due to procurement cost constraints.
Residential channels process the highest transaction volume; commercial hospitality is expanding most quickly on new-build project specifications.
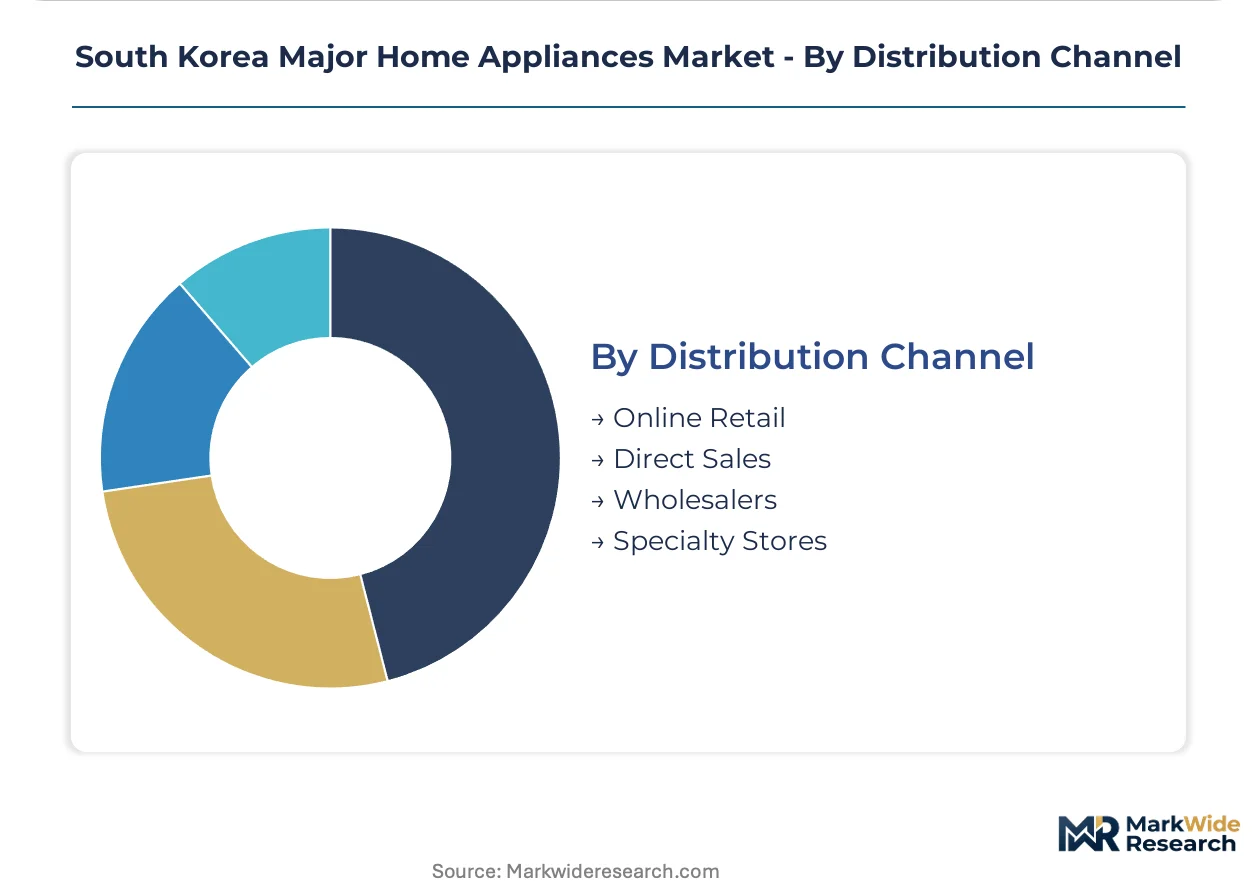
Distribution Channel:
Customer type and purchase scale reshape channel economics, with bulk procurement from property developers displacing individual retail transactions in the metropolitan corridor.
- Direct Sales:Property developer procurement consolidation concentrates demand among suppliers capable of multi-category fulfillment. Major Seoul housing project tenders specify integrated packages with unified control interfaces, compressing standalone retail flows.
- Online Retail:Connected appliance purchases through digital channels accelerate in Seoul's high-income districts where health-conscious positioning and MFDS antimicrobial certification drive premium pricing.
- Specialty Stores:Physical showrooms in Seoul and Busan demonstrate inverter technology advantages to replacement-cycle households.
- Wholesalers:Bulk supply to Jeolla Province rural housing stock maintains conventional appliance penetration as grid infrastructure modernizes.
Direct sales channels manage the largest contract values; online retail is gaining share fastest on connected appliance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across South Korea's urban hierarchy. Seoul apartment buyers absorb premium pricing for connected appliances, while Jeolla Province rural households remain price-sensitive on conventional equipment replacement cycles.
Seoul Capital Area
Seoul's dense apartment complexes drive replacement demand for inverter compressors and heat-pump dryers. METI's tightened MEPS standards disqualify sub-tier imports from retail placement, pushing households toward certified energy-efficient models. Gangnam and Songpa district developers bundle IoT-enabled appliance packages into premium housing tenders.
Busan-Ulsan
Coastal humidity zones around Busan generate the highest air conditioner replacement frequency nationwide. The industrial belt's new-build hospitality projects specify integrated appliance packages with centralized warranty administration. Stricter building energy codes in Ulsan's manufacturing zones mandate heat-pump dryers for commercial laundry facilities.
Daegu-Gyeongbuk
Daegu's textile and machinery heritage sustains industrial canteen procurement of conventional appliances with cost-constrained specifications. KATS electromagnetic compatibility testing facilities in the region compress lead times for connected appliance launches targeting the southeastern corridor. Gumi's electronics cluster supplies compressor control system components upstream.
Daejeon-Sejong
Sejong's planned administrative city construction pulls multi-category appliance fulfillment for government housing stock. The Korean Agency for Technology and Standards maintains headquarters here, streamlining KC certification processes for regional manufacturers. Daejeon's research institutes feed inverter motor design talent into adjacent industrial zones.
Gwangju-Honam
Jeolla Province's rural housing stock maintains higher conventional appliance penetration, creating whitespace for inverter technology diffusion. Grid infrastructure modernization in Honam's agricultural counties is expanding addressable demand for energy-efficient replacement cycles. Gwangju's smaller appliance assemblers serve price-sensitive rental housing markets.
South Korea Major Home Appliances Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South Korea's appliance sector. Integrated semiconductor foundry operators anchor premium smart appliance ecosystems, while assembly-focused OEMs compete on scale in conventional equipment tiers. Three strategic archetypes dominate: captive component manufacturers with in-house compressor production, specialized health-appliance niche players, and diversified electronics conglomerates with multi-category portfolios. Competitive moves concentrate on backward integration into refrigerant compressor manufacturing and strategic partnerships with property developers for bundled procurement contracts.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics exemplify integrated production models. Samsung leverages captive semiconductor fabrication to anchor connected appliance platforms. LG sustains compressor technology leadership through dedicated appliance components divisions. Coway occupies a defensible specialist position in residential health-conscious segments, representing the niche-focused archetype with concentrated water purification and air care expertise.
| Leading Market Players |
|---|
| SK Magic |
| Cuckoo Electronics |
| LG Electronics |
| Hyosung TNC |
| Daewoo Electronics |
| Samsung Electronics |
| Coway |
| Hanil Electronics |
| Winia Electronics |
| Others |
Value Network & Pricing Analysis
R32 refrigerant substitution for legacy hydrofluorocarbons is simultaneously redrawing component sourcing maps and compressing margin structures across compressor manufacturing tiers. This chemistry transition forces air conditioner makers toward redesigned heat exchangers and higher-pressure systems, amplifying cost differentials between domestic inverter motor producers and import-dependent assemblers while METI's MEPS enforcement tightens retail placement eligibility.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now capture lifetime value beyond initial unit sales. Pricing stratifies across premium smart-appliance tiers with IoT bundling, standard inverter-equipped lines meeting MEPS thresholds, and economy conventional units for rental housing procurement. Price differentiation hinges on KATS KC certification status and METI energy label grade. Cost compression in economy tiers is intensifying because Chinese component imports face disqualification from retail channels. Industrial canteen buyers exhibit highest price sensitivity; Seoul property developers show lowest sensitivity due to energy-performance guarantee requirements.
Supply Chain Analysis
Inventory buffers for neodymium magnets and copper windings have compressed to eight-week cycles as demand volatility outpaces procurement agility. Component sourcing concentrates in China for rare-earth magnet processing, Japan for precision inverter drives, and domestic Korean facilities for final compressor assembly. Raw material dependencies include neodymium, copper, and specialized electrical steel laminations. Single-source vulnerability in Chinese magnet supply creates tariff-exposure risk. Distribution runs through direct developer procurement contracts in Seoul, specialty retail in Busan, and wholesale channels penetrating Jeolla Province rural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat-pump dryer technology diffusion represents a high-growth disruption as stricter building energy codes force refrigerant and motor architecture transitions across residential and commercial installations. METI's Kigali Amendment alignment and MEPS tightening create regulatory momentum that compresses conventional equipment viability windows.
For Market Incumbents: Secure captive compressor manufacturing capacity to offset import dependency for heat-pump dryer systems. Lock multi-year procurement contracts with Seoul property developers before certification backlogs extend lead times. Defend against emerging Chinese OEMs by accelerating R600a-compatible production lines and pre-empting KATS electromagnetic compatibility testing queues.
For New Entrants and Emerging Players: Lead with antimicrobial-certified water purification systems targeting Gangnam and Songpa district health-conscious households. Penetrate Jeolla Province rural replacement cycles through wholesaler partnerships as grid modernization expands addressable demand. Position on MFDS certification as a premium pricing lever against established brands.
For Investors and Strategic Acquirers: Capital is best deployed toward component-specialist archetypes with in-house inverter motor design capability and established KATS certification track records. Long-term viability centers on backward integration into refrigerant compressor manufacturing rather than assembly-only operations. Monitor heat-pump dryer adoption rates in Busan new-build projects as inflection signal for domestic inverter motor capacity adequacy.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive production of inverter motors and refrigerant systems reduces import dependency and secures MEPS compliance. |
| Smart Apartment Developer Partnership | Direct procurement contracts with Seoul housing project tenders concentrate volume and displace retail channel fragmentation. |
| R32 Refrigerant Transition Roadmap | Alignment with Kigali Amendment phase-down schedules maintains retail placement eligibility under METI enforcement. |
| AI-Driven Predictive Maintenance Platform | Remote diagnostics embedded in connected appliances enable recurring service revenue and compressor control optimization. |
| MFDS Antimicrobial Certification Investment | Health-claim positioning through refrigerator lining certification opens premium pricing in Seoul high-income districts. |
Research Methodology
A standing panel of compressor engineering directors, METI regulatory affairs specialists, property developer procurement managers, and KATS certification auditors provided ongoing calibration throughout data collection. Primary interviews with appliance component suppliers and Seoul apartment developer technical teams combined with secondary validation from customs trade records, KC certification databases, and METI energy labeling disclosures. Bottom-up unit shipment modeling and top-down value aggregation triangulated market size estimates across product categories and technology tiers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, technology tier, end-use application, and regional demand cluster. CAGRs were derived from replacement cycle analysis and new-build housing stock projections. Forecast inputs incorporated refrigerant phase-down schedules, inverter motor capacity expansion timelines, and property developer bundling penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained METI enforcement intensity or accelerated Kigali Amendment timelines would require recalibration. Forecasts reflect documented assumptions regarding copper and rare-earth magnet price stability, KATS certification processing speeds, and heat-pump dryer technical performance in sub-5°C conditions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Refrigerator Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
White Goods Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Europe White Goods Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
India Refrigerator Market
Home Appliances
Built-In Appliance Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
Range Hood Market