
 Neonatal Hearing Screening Devices Market | 2026-2036
Neonatal Hearing Screening Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Hearing Screening Devices Market Outlook
Hospital maternity units and outpatient birthing centers are bifurcating procurement patterns for neonatal hearing screening devices. Natus Medical leverages integrated data-management platforms to anchor its position in large health-system contracts. MAICO Diagnostics competes through specialized handheld otoacoustic emissions systems designed for point-of-care workflows.
Neonatal hearing screening devices detect auditory pathway function in newborns through otoacoustic emissions measurement, auditory brainstem response recording, or automated audiometric testing, typically operating at stimulus levels between 35 and 85 dB SPL to identify congenital sensorineural deficits before language-development windows close. The product-type dimension shows otoacoustic emissions equipment commanding the installed base due to speed and non-invasiveness, while auditory brainstem response systems capture margin pools in NICU referrals and diagnostic follow-up. Wireless technology is displacing analog configurations in hospital settings where EMR integration and remote telemetry reduce nursing workload.
The FDA regulates these devices as Class II medical devices under 21 CFR 874, requiring 510(k) clearance for acoustic stimulus output safety and algorithm validation, while the Joint Commission mandates universal newborn hearing screening as part of perinatal care accreditation standards. State-level Medicaid early-hearing-detection programs create reimbursement infrastructure that shapes hospital purchasing cycles. Stakeholders must monitor evolving FDA guidance on artificial-intelligence-based diagnostic algorithms and state Medicaid fee-schedule adjustments that could redirect volume between hospitals and diagnostic laboratories.
Market Dynamics
Universal newborn hearing screening mandates are tightening procurement specifications across hospital maternity wards, forcing equipment vendors to prioritize EMR integration and automated workflow compatibility over standalone device performance metrics.
Growth Catalysts
- Medicaid early-hearing-detection reimbursement:State-level fee schedules in the United States create institutional pull for screening platforms by covering procedure costs for universal newborn protocols.
- Otoacoustic emissions miniaturization:Handheld probe technology enables point-of-care deployment in outpatient birthing centers previously limited to hospital-based audiology departments.
- Joint Commission perinatal accreditation:Mandatory universal hearing screening as a condition of hospital certification drives replacement cycles for non-automated legacy equipment.
Market Restraints
- Disposable probe-tip supply concentration:Single-use otoacoustic emissions consumables face sourcing vulnerability from concentrated Asian manufacturing clusters, creating inventory risk for high-throughput screening programs.
- Auditory brainstem response equipment cost structure:Electrode arrays and signal-processing hardware for NICU-grade diagnostic follow-up require capital outlays that constrain community hospital penetration.
- FDA 510(k) algorithm validation timelines:Artificial-intelligence-based diagnostic enhancements face extended clearance pathways for acoustic stimulus safety verification, delaying feature rollouts.
Strategic Opportunities
- Rural health clinic penetration:Federally qualified health centers in the United States represent under-screened birth cohorts where tele-audiology linkages could extend reach without capital-intensive equipment placement.
- Home-birth midwife integration:Portable screening devices create channel innovation through direct-to-provider distribution models bypassing traditional hospital procurement committees.
- Cloud-based data registries:State public health surveillance systems offer regulatory tailwind through mandated reporting infrastructure that favors connected-device platforms over offline systems.
Industry Challenges
- Pediatric audiology technician scarcity:Specialized training requirements for otoacoustic emissions interpretation create workforce bottlenecks limiting screening program expansion in underserved regions.
- Legacy analog system integration:Hospital IT departments face complexity bridging 1990s-era standalone audiometers to contemporary HL7 FHIR data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Hearing Screening Devices Market |
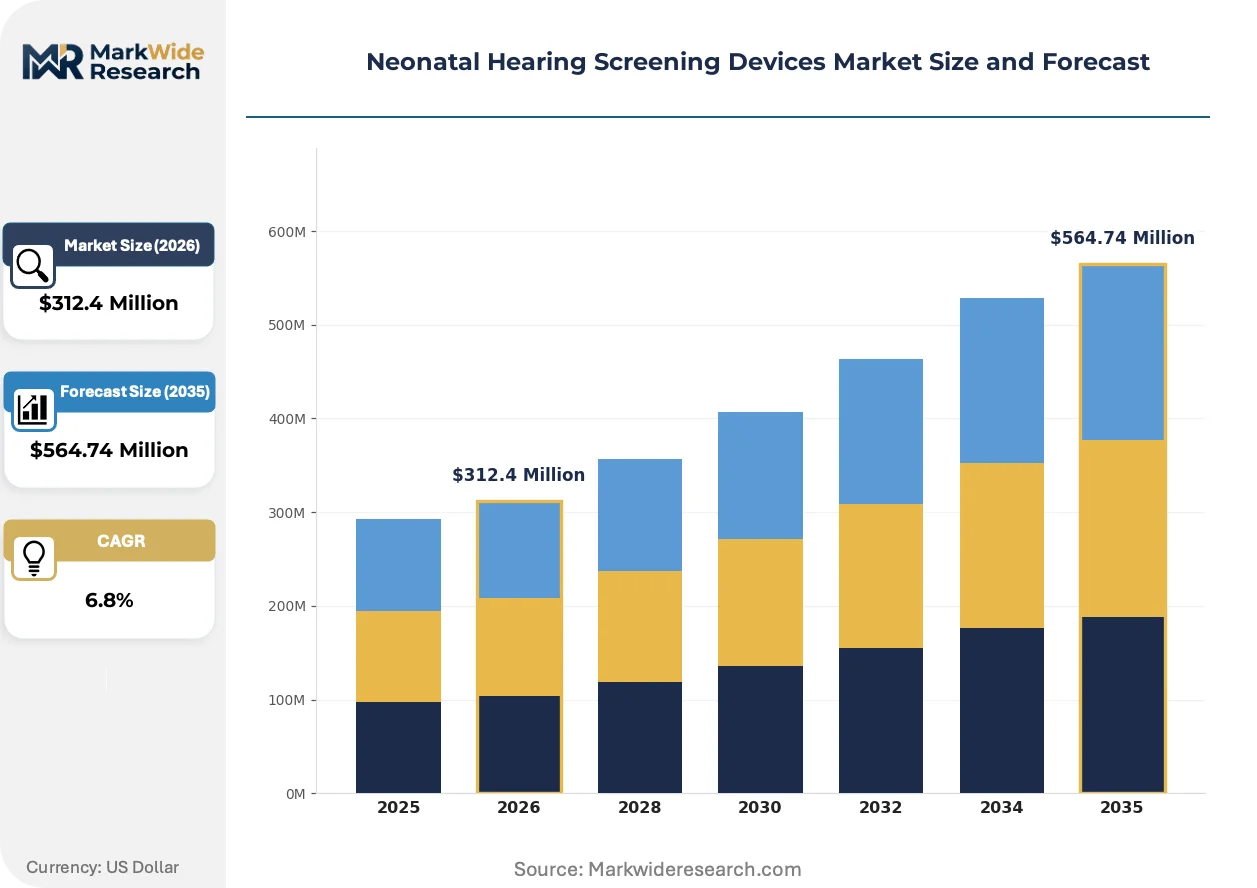
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Otoacoustic Emissions, Auditory Brainstem Response, Automated Audiometry, Tuning Fork End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Technology: Wireless, Digital, Analog, Hybrid Service Type: Routine Screening, Diagnostic Testing, Follow-Up Services, Data Management |
| Companies Covered | Natus Medical, MAICO Diagnostics, Interacoustics A/S, Path Medical, Intelligent Hearing Systems, Vivosonic, Grason-Stadler, Hill-Rom, Echodia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Hearing Screening Devices Market Strategic Shifts
Artificial-intelligence diagnostic algorithms and wireless telemetry are compressing the traditional separation between screening and diagnostic workflows, enabling real-time remote specialist consultation that reconfigures staffing models across maternity care delivery networks.
Machine-learning pattern recognition for otoacoustic emissions waveform analysis is decomposing the historical distinction between technician-operated screening devices and audiologist-interpreted diagnostic equipment. Large health systems in California and Texas are piloting nurse-staffed protocols with automated pass-refer decisions, compressing specialist labor requirements and accelerating throughput during peak birth-volume periods.
The FDA's evolving guidance on software-as-a-medical-device classification for AI-based hearing screening algorithms is tightening validation requirements for algorithm update pathways. Device manufacturers must now submit predetermined change control plans for machine-learning model revisions, extending development cycles but reducing post-market surveillance burden for validated platforms.
Hospital purchasing committees are consolidating vendor relationships through multi-year managed equipment service agreements that bundle device placement, disposable supply, and remote technical support into per-screen pricing. This model displaces capital purchase cycles with operational expenditure structures, concentrating procurement influence among integrated health systems with sufficient birth volume to justify exclusive supplier arrangements.
Neonatal Hearing Screening Devices Market Segmentation
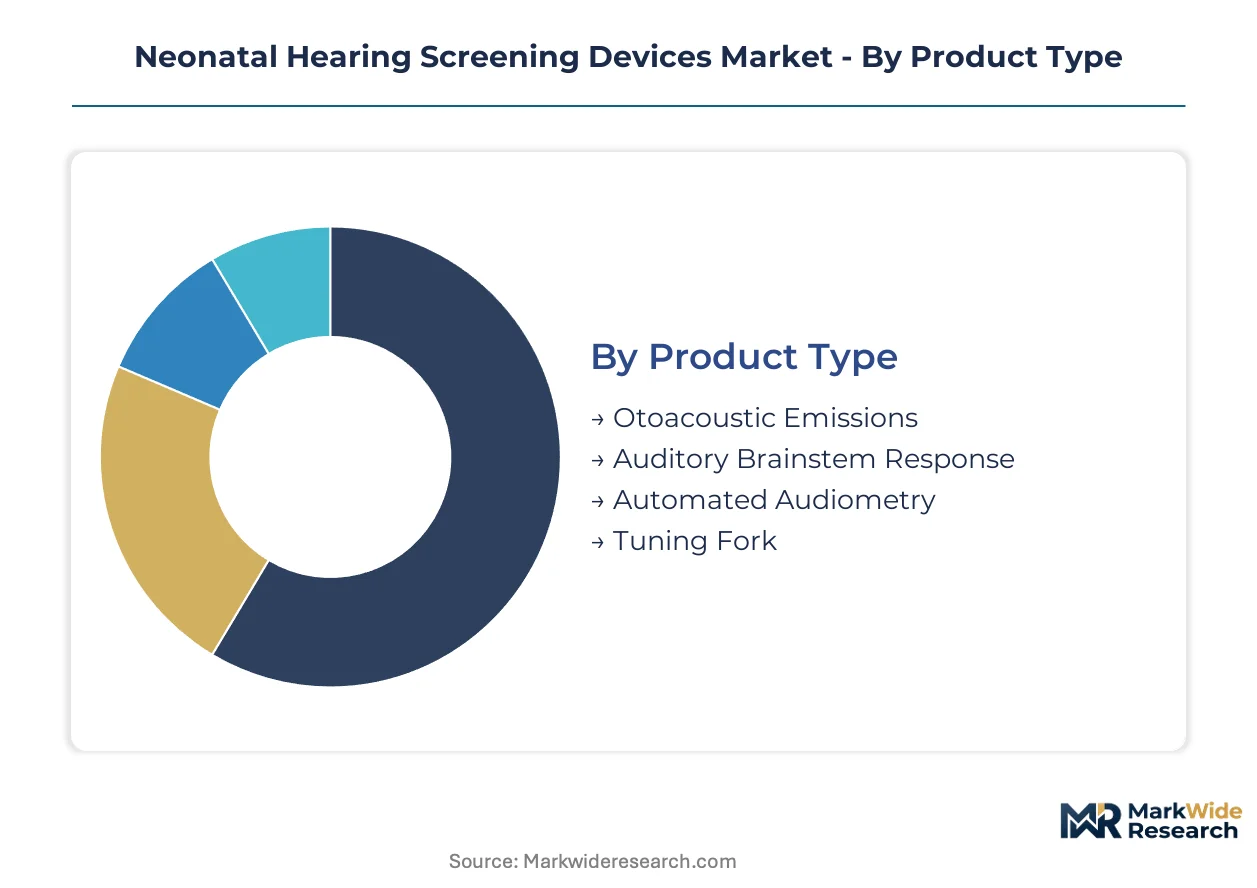
Neonatal hearing screening device segmentation reflects divergent procurement economics across maternity care settings. Product architecture, connectivity standards, and service bundling reshape vendor positioning across hospital systems and outpatient networks.
Product Type:
FDA 510(k) clearance pathways differentiate acoustic stimulus platforms by validation complexity and clinical claim scope.
- Otoacoustic Emissions:Miniaturized probe systems measure cochlear outer hair cell function through transient or distortion-product stimuli at 35-85 dB SPL. Hospital maternity wards in the United States concentrate procurement here for rapid bedside throughput compatible with Joint Commission mandates.
- Auditory Brainstem Response:Electrode-based systems record neural pathway responses to click or tone-burst stimuli, requiring NICU-grade signal isolation. Diagnostic laboratories and tertiary referral centers absorb capital intensity for definitive threshold estimation in high-risk neonates.
- Automated Audiometry:Algorithm-driven threshold-seeking protocols reduce operator dependence for follow-up testing in community clinic settings.
- Tuning Fork:Mechanical frequency generators persist in resource-limited international markets lacking electronic device infrastructure.
Established volume favors Otoacoustic Emissions; emerging adoption favors Auditory Brainstem Response.
End User:
Reimbursement infrastructure and birth volume density determine equipment specification tiers across care delivery sites.
- Hospitals:Maternity units with 2,000+ annual births justify integrated data-management platforms with HL7 FHIR connectivity. Medicaid early-hearing-detection program fee schedules in the United States anchor procurement cycles for automated screening workflows.
- Clinics:Outpatient birthing centers and federally qualified health centers prioritize handheld wireless probes for point-of-care deployment without dedicated audiology staffing.
- Home Care:Direct-to-midwife distribution models bypass traditional procurement committees for home-birth cohorts in under-screened rural counties.
- Diagnostic Laboratories:Centralized referral hubs aggregate failed screening cases for confirmatory auditory brainstem response testing with specialist interpretation.
Procurement concentration sits with Hospitals; channel innovation targets Home Care.
Technology:
EMR integration requirements and nursing workload reduction drive connectivity architecture decisions.
- Wireless:Bluetooth and Wi-Fi-enabled probes transmit results directly to electronic medical records, eliminating manual documentation in high-throughput screening programs.
- Digital:Signal-processing platforms with automated pass-refer algorithms compress specialist labor requirements in nurse-staffed protocols.
- Analog:Standalone audiometers face replacement pressure from health-system consolidation of vendor relationships.
- Hybrid:Configurations pairing digital signal acquisition with analog output stages serve transitional upgrade paths for legacy equipment users.
Replacement cycles favor Wireless; budget constraints sustain Hybrid.
Service Type:
Per-screen pricing models and managed equipment service agreements restructure revenue recognition across device lifecycles.
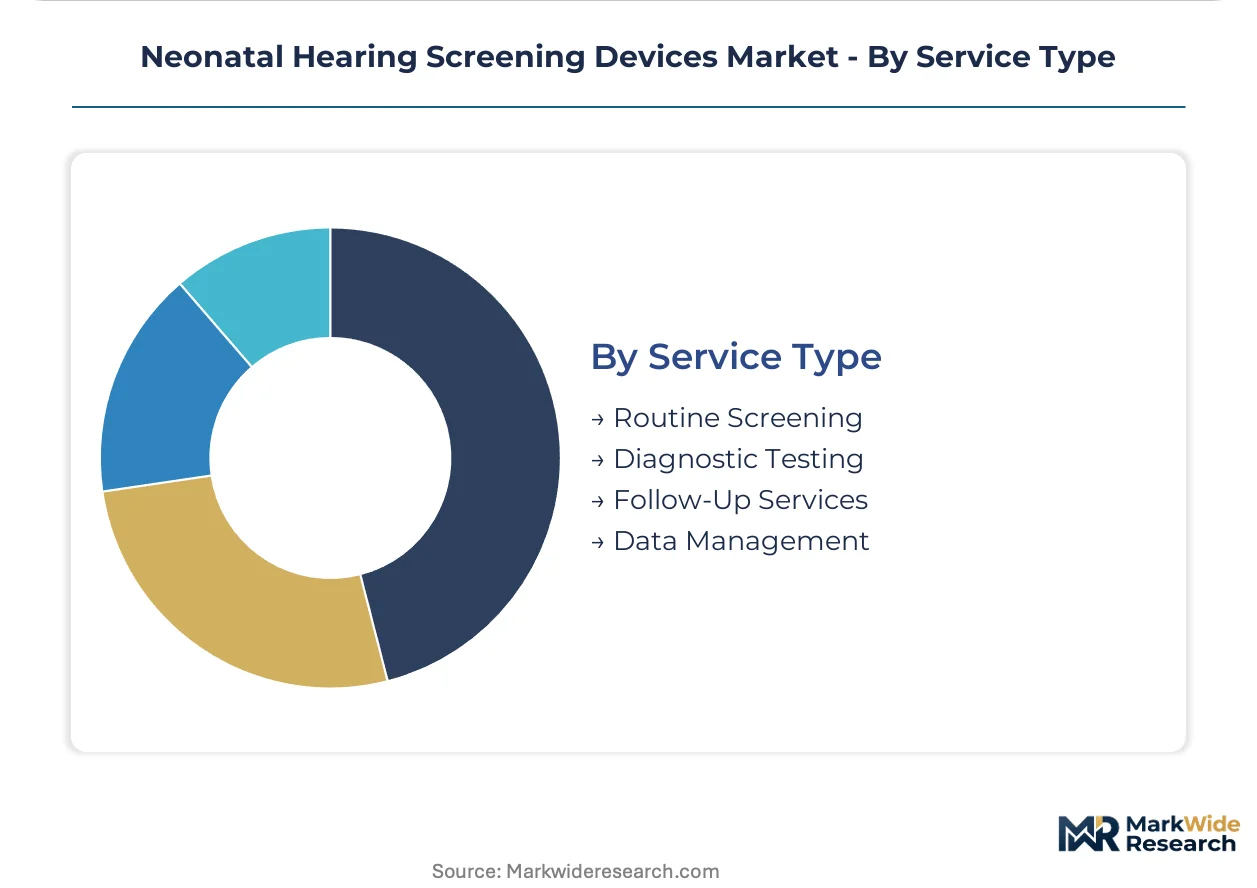
- Routine Screening:Universal newborn protocols mandated by state legislation and Joint Commission accreditation generate recurring volume with standardized procedural codes.
- Diagnostic Testing:Confirmatory auditory brainstem response and diagnostic otoacoustic emissions capture margin pools in NICU referrals and failed-screen follow-up.
- Follow-Up Services:Tracking and recall systems for infants lost to documentation gaps address public health surveillance requirements.
- Data Management:Cloud-based registries and state-mandated reporting infrastructure favor connected-device platforms with automated submission protocols.
Revenue stability rests with Routine Screening; margin expansion targets Diagnostic Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States concentrate purchasing authority for neonatal hearing screening devices, while decentralized maternity networks in Germany and Japan generate distinct specification requirements for point-of-care deployment.
United States
Medicaid early-hearing-detection program fee schedules drive institutional procurement cycles across hospital maternity wards. The Joint Commission mandates universal newborn hearing screening as a condition of perinatal care accreditation, tightening replacement timelines for legacy equipment. Texas and California health systems pilot nurse-staffed automated protocols, compressing specialist labor requirements during peak birth-volume periods.
Germany
Outpatient birthing centers concentrate demand for handheld wireless probes compatible with statutory health insurance reimbursement frameworks. The country's national medical device regulator enforces MDR compliance timelines for algorithm-validated screening platforms. Bavarian hospital networks consolidate vendor relationships through multi-year managed equipment service agreements bundling device placement with disposable supply.
Japan
Metropolitan Tokyo maternity units prioritize EMR-integrated platforms with HL7 FHIR connectivity for high-throughput screening programs. METI guidelines on software-as-a-medical-device classification shape validation requirements for AI-based diagnostic algorithms. Osaka-based diagnostic laboratories aggregate failed screening cases for confirmatory auditory brainstem response testing with specialist interpretation.
United Kingdom
NHS England newborn hearing screening program specifications standardize procurement across maternity units with 2,000+ annual births. The MHRA regulates device clearance under UKCA marking requirements post-Brexit, diverging from EU MDR harmonization timelines. London health system trusts negotiate exclusive supplier arrangements consolidating device placement, consumables, and remote technical support into per-screen pricing.
India
Federally qualified health centers in Maharashtra and Karnataka represent under-screened birth cohorts where tele-audiology linkages could extend reach without capital-intensive equipment placement. CDSCO medical device registration requirements create compliance thresholds for imported screening platforms. Tamil Nadu hospital clusters source handheld otoacoustic emissions systems through centralized state procurement tenders prioritizing cost efficiency over connectivity features.
Neonatal Hearing Screening Devices Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with audiology divisions alongside specialized diagnostic equipment manufacturers. Market structure concentrates around integrated health-system contracts with multi-year service agreements displacing capital purchase cycles. Two strategic archetypes dominate: platform vendors bundling device placement with cloud-based data management, and handheld specialists targeting point-of-care workflows in outpatient settings. Competitive moves center on exclusive supplier arrangements with large birth-volume health systems and algorithm licensing partnerships for AI-based diagnostic enhancements.
Within the diversified medical technology tier, Natus Medical and Hill-Rom occupy positions anchoring large health-system procurement committees through integrated data-management platforms. MAICO Diagnostics exemplifies the handheld specialization archetype, representing German engineering-focused competitors targeting point-of-care deployment in decentralized maternity networks. Interacoustics A/S sits within the Nordic diagnostic equipment tradition, reflecting regional consolidation patterns among European audiology specialists.
| Leading Market Players |
|---|
| Natus Medical |
| MAICO Diagnostics |
| Interacoustics A/S |
| Path Medical |
| Intelligent Hearing Systems |
| Vivosonic |
| Grason-Stadler |
| Hill-Rom |
| Echodia |
| Others |
Value Chain & Pricing Dynamics
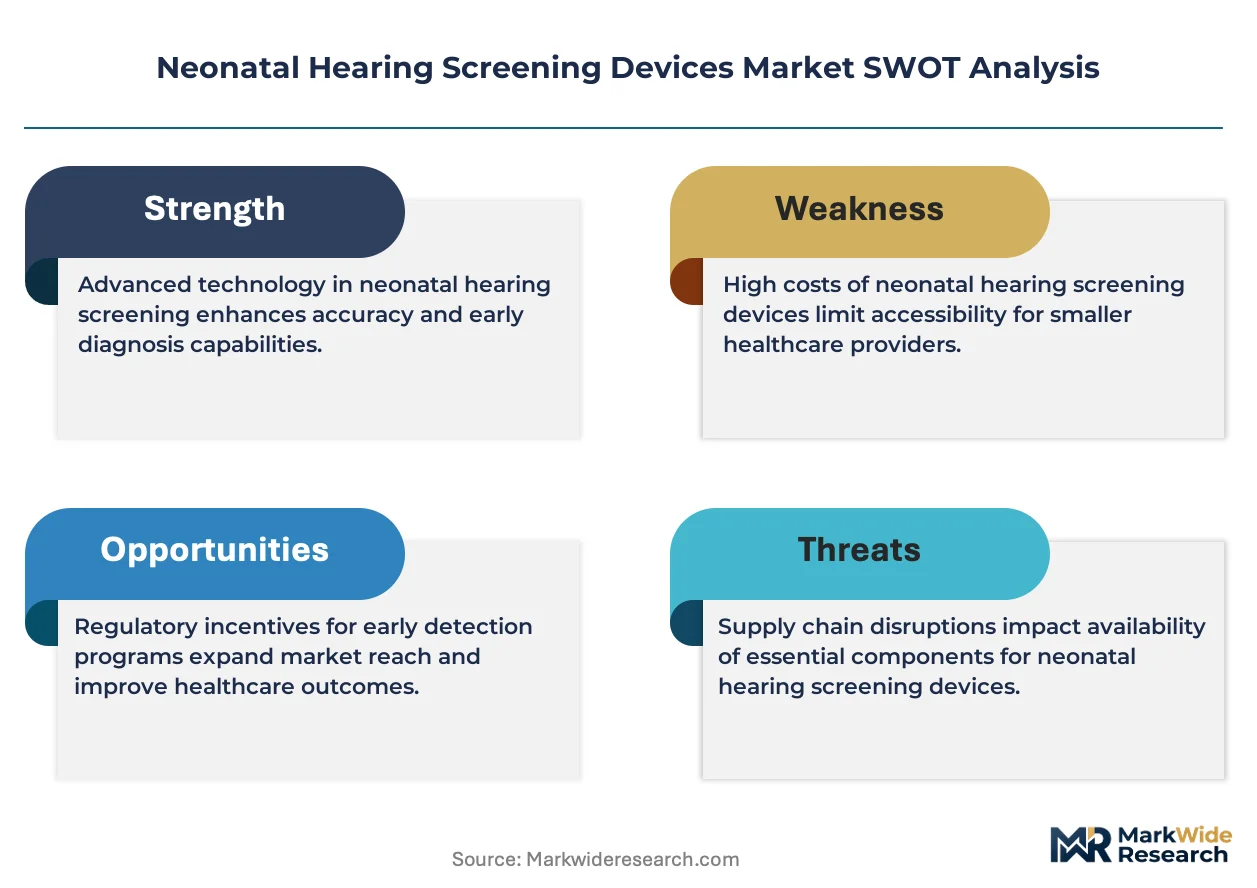
FDA 510(k) clearance pathways gate both supply qualification and price differentiation simultaneously, with algorithm-validated platforms commanding premium positioning over legacy analog systems while disposable probe-tip sourcing constraints compress margins at the consumables tier.
Pricing Analysis
Three-generation pricing stratification separates wireless EMR-integrated platforms from digital signal-processing workhorses and residual analog configurations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and HL7 FHIR connectivity depth. Cost compression in the analog tier intensifies because health-system consolidation favors managed service agreements bundling hardware, disposables, and remote support. Federally qualified health centers and rural clinics exhibit highest price sensitivity; tertiary referral centers with NICU-grade diagnostic mandates show lowest.
Supply Chain Analysis
Single-use otoacoustic emissions probe-tip manufacturing concentrates in Chinese and Malaysian production clusters, creating inventory vulnerability for high-throughput screening programs. Electrode arrays for auditory brainstem response systems draw from Japanese and German component suppliers, while signal-processing chipsets feed from Taiwanese foundries. Tariff exposure runs through Asian manufacturing corridors for disposable consumables. Distribution runs through hospital purchasing committees and GPO contracts in the United States, with direct-to-midwife channels emerging for home-birth segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as cloud-based data registries and state-mandated reporting infrastructure favor connected-device ecosystems over standalone equipment, compressing vendor margins into recurring service streams.
For Market Incumbents: Consolidate vendor relationships with large birth-volume health systems through exclusive multi-year managed equipment service agreements that bundle device placement, disposable supply, and remote technical support. Deepen backward integration into probe-tip manufacturing to offset Asian supply concentration risks. Anchor defensive positioning against handheld specialists by accelerating FDA submissions for AI-based diagnostic algorithm enhancements. For New Entrants and Emerging Players: Midwife-staffed home-birth networks and federally qualified health centers in under-screened rural counties represent service-layer gaps where incumbents under-serve with hospital-centric sales architectures. Tele-audiology linkage platforms for remote specialist consultation offer the most penetrable wedge. Pursue direct-to-provider distribution models bypassing traditional procurement committees, paired with per-screen pricing that converts capital expenditure barriers into operational budgets. For Investors and Strategic Acquirers: FDA software-as-a-medical-device guidance evolution reshapes the acquisition landscape by extending validation timelines for machine-learning model revisions while reducing post-market surveillance burden for validated platforms. Five-to-ten year viability favors platform vendors with cloud-based data registry integration and state public health surveillance contracts. Target acquisition archetypes: handheld specialists with wireless probe miniaturization IP and established midwife channel relationships. Watch state Medicaid fee-schedule adjustments as volume-shift signal between hospital and diagnostic laboratory settings.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Submission | Predetermined change control plans for machine-learning diagnostics reduce post-market surveillance burden under evolving FDA guidance. |
| Managed Equipment Service Agreement | Per-screen pricing bundles displace capital purchase cycles, concentrating procurement influence among integrated health systems. |
| Probe-Tip Manufacturing Integration | Backward integration into single-use consumables mitigates Asian supply concentration vulnerability for high-throughput programs. |
| Tele-Audiology Platform Launch | Remote specialist consultation compresses staffing bottlenecks in underserved rural counties and home-birth networks. |
| State Registry Data Integration | Automated HL7 FHIR submission protocols capture public health surveillance infrastructure mandates favoring connected devices. |
Study Parameters
Cross-validation between primary interviews with hospital purchasing committee members, biomedical engineers, and audiology department directors and secondary sources including FDA 510(k) filings, CMS Medicare reimbursement databases, and state early-hearing-detection program specifications anchors the qualitative findings. Bottom-up triangulation across device shipment data and top-down reconciliation against Medicaid fee-schedule expenditure patterns validate volume estimates.
Sensitivity analysis frames the analytical approach across the projection horizon, with segmentation dimensions spanning product architecture, end-user setting, connectivity technology, and service bundling model. CAGRs derive from birth cohort projections, equipment replacement cycle analysis, and reimbursement policy trajectory modeling. Forecast inputs incorporate Joint Commission accreditation mandate timelines and state-level universal newborn hearing screening legislation adoption curves.
Underlying assumptions cover Medicaid reimbursement stability, disposable probe-tip supply continuity, and FDA algorithm validation pathway predictability, with deviation risk concentrated in state budget pressures affecting early-hearing-detection program funding and AI-based diagnostic software classification shifts. Practitioners should keep alternative scenarios live as reimbursement policy and regulatory guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Medical Goggle Market
Medical Devices
Radial Compression Devices Market
Medical Devices
Interlaminar Device Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
Global Closed System Transfer Devices Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Ablation Devices Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
United Kingdom Ultrasound Devices Market