
 UAE Laundry Appliances Market | 2026-2036
UAE Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Laundry Appliances Market Analytics
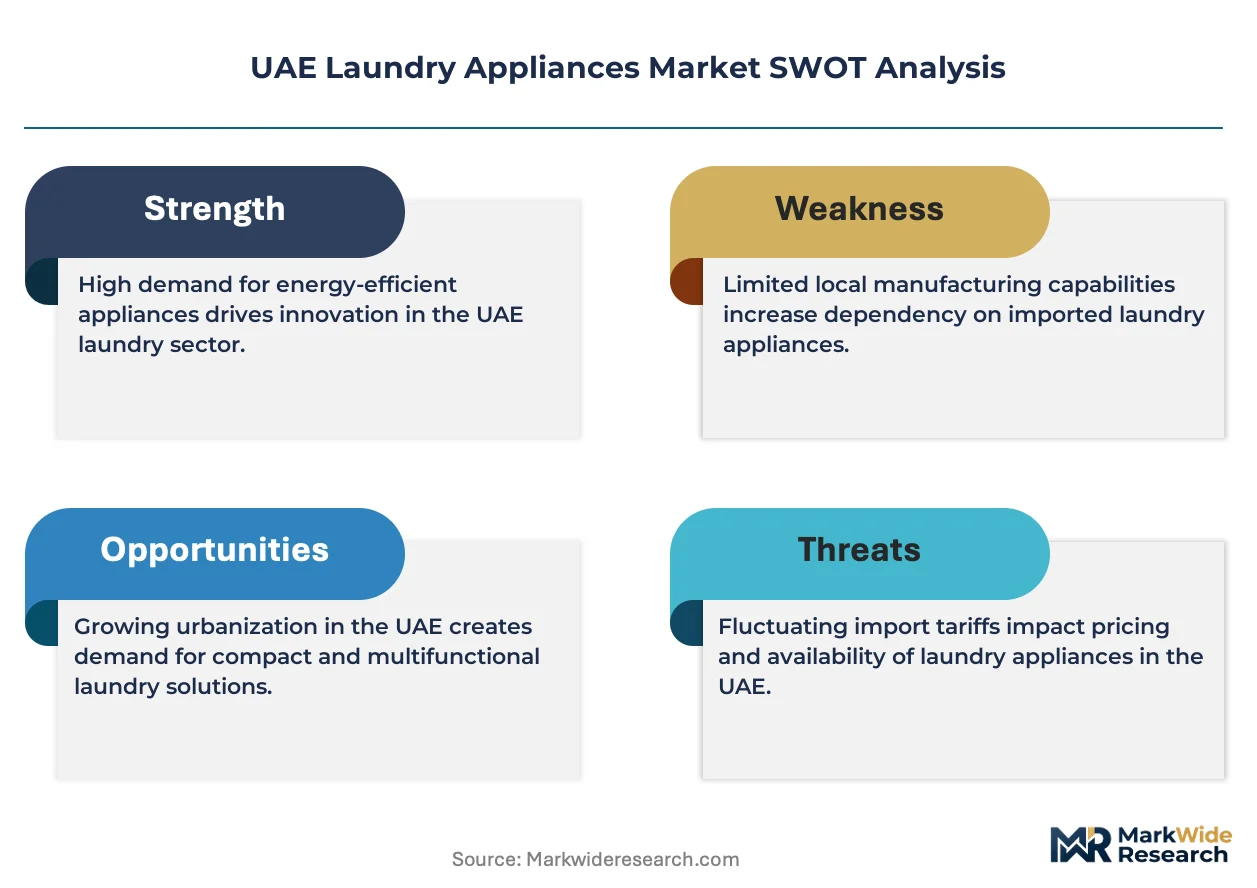
Multi-source procurement among hotel chains and property management groups is hardening as commercial operators seek supply resilience against single-brand dependency. LG Electronics leverages its smart appliance ecosystem to anchor premium positions in Dubai's hospitality sector. Samsung Electronics competes through connected laundry platforms that integrate with building management systems. Bosch differentiates via energy-efficient front-load engineering that aligns with federal efficiency benchmarks.
Laundry appliances encompass electromechanical systems designed for textile cleaning, dehydration, or combined wash-dry cycles, typically operating at drum speeds of 1,000–1,600 RPM for front-load configurations and employing either vented condensation or heat-pump drying technologies. These systems serve residential, commercial, and industrial end users requiring hygienic fabric processing at scale. Washing machines retain the dominant revenue position due to replacement cycles in residential towers and commercial laundries, while smart appliances represent the fastest-expanding technology segment as IoT-enabled remote diagnostics and utility integration gain traction among UAE property developers. Energy-efficient models command margin premiums in both retail and project channels where ESMA compliance shapes bidding criteria.
MOHAP oversees appliance safety and energy labeling requirements that manufacturers must satisfy for UAE market entry, while ESMA mandates efficiency ratings that directly influence procurement decisions in government and commercial tenders. The country's national standards regulator enforces electromagnetic compatibility and water consumption thresholds that narrow the importable product set. Stakeholders must monitor evolving smart grid integration standards and water tariff structures that will determine which technology configurations retain cost advantages across residential and commercial deployment scenarios.
Market Dynamics
Commercial hospitality operators in Dubai and Abu Dhabi are accelerating in-house laundry capacity investments to capture margin from outsourced linen services, while MOHAP efficiency mandates redirect procurement specifications toward connected, energy-rated equipment configurations.
Growth Catalysts
- ESMA efficiency mandates:Federal efficiency benchmarks now shape bidding criteria across government and commercial tenders, elevating demand for certified energy-rated machines.
- Hospitality linen cost control:Hotel operators across Dubai's hotel corridor are expanding captive laundry facilities to reduce third-party service expenditures.
- IoT integration requirements:Smart appliance platforms enabling remote diagnostics and utility management are becoming standard in new property developments.
Market Restraints
- Import product narrowing:Electromagnetic compatibility and water consumption thresholds enforced by the national standards regulator restrict the importable equipment set.
- Water tariff exposure:Escalating water tariffs in the Emirates compress operating margins for high-throughput commercial installations.
- Heat-pump technology cost premium:Energy-efficient drying configurations command 25-40% capital cost premiums versus vented condensation alternatives.
Strategic Opportunities
- Healthcare corridor expansion:Abu Dhabi's medical district presents underpenetrated demand for hygienic textile processing at institutional scale.
- Smart grid convergence:Integration of laundry appliances with building energy management systems opens utility-sponsored procurement channels.
- After-sales service unbundling:Remote diagnostic capabilities enable predictive maintenance contracts as standalone revenue streams.
Industry Challenges
- Technician certification gaps:Shortage of qualified service personnel for IoT-enabled equipment diagnostics limits deployment velocity.
- Legacy system integration friction:Property management systems in older hospitality assets require costly middleware for smart appliance connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Laundry Appliances Market |
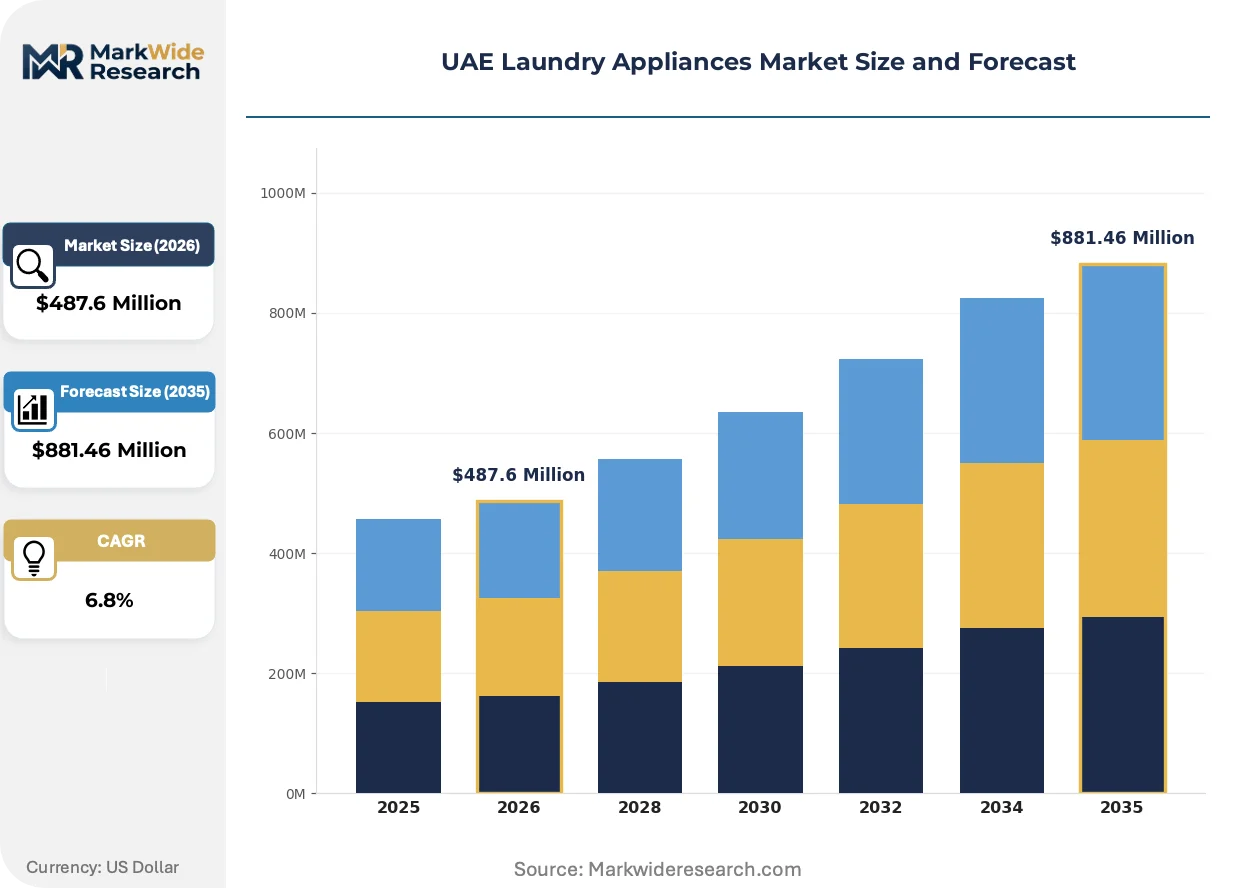
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Portable Washers End User: Residential, Commercial, Industrial, Hospitality Technology: Smart Appliances, Energy-Efficient, Top Load, Front Load Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | LG Electronics, Samsung Electronics, Whirlpool Corporation, Electrolux AB, Bosch, Haier Group, Panasonic Corporation, Hitachi Appliances Inc, Nikai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Laundry Appliances Market Evolving Landscape
Equipment specifications across the Emirates are pivoting from standalone functionality toward integrated building systems, with efficiency certification and connectivity becoming primary selection criteria rather than secondary features.
Heat-pump drying technology is expanding into commercial hospitality installations as operators seek to reduce water and energy operating expenditures. Front-load configurations with variable drum speeds between 1,000-1,600 RPM are displacing conventional vented systems in premium hotel developments. This technology compression is enabling smaller equipment footprints while maintaining throughput requirements.
MOHAP appliance safety and energy labeling requirements are tightening procurement specifications for market entry. Manufacturers must satisfy electromagnetic compatibility and water consumption thresholds that narrow importable product ranges. Commercial operators in Dubai's hospitality sector are responding by pre-qualifying suppliers against these evolving benchmarks.
Multi-source procurement patterns are hardening among hotel chains and property management groups seeking supply resilience. Single-brand dependency is giving way to diversified vendor relationships across equipment categories. This behavioral shift is most visible in Dubai's hotel corridor, where procurement teams now split orders across two or three qualified suppliers.
UAE Laundry Appliances Market Segmentation
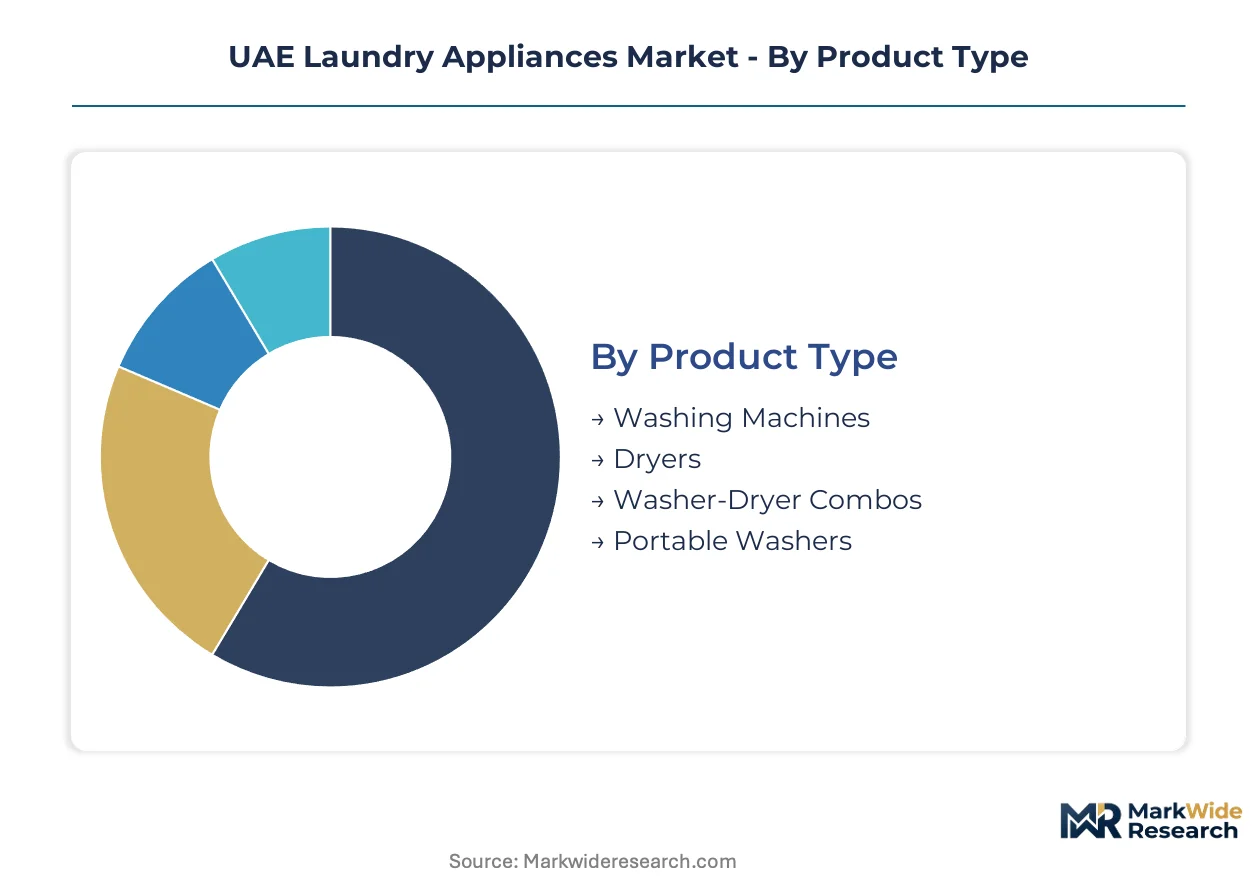
Equipment procurement across the Emirates fragments across four distinct dimensions that reshape vendor go-to-market strategies. Product configuration, end-use intensity, technology integration depth, and channel access each command separate pricing logic and service requirements.
Product Type:
Standardization dominates at the mass-market tier while custom engineering prevails in commercial throughput applications.
- Washing Machines:Front-load configurations with 1,000–1,600 RPM drum speeds anchor both residential tower replacements and commercial laundry installations. Dubai's hospitality corridor drives demand for high-capacity units with stainless steel drums and programmable cycle controls.
- Dryers:Heat-pump and vented condensation systems split the market by operating cost sensitivity. Heat-pump configurations command capital premiums but reduce water-energy expenditures for high-throughput operators in Abu Dhabi's hotel districts.
- Washer-Dryer Combos:Space-constrained residential towers in Sharjah and Ajman favor these units despite longer cycle times and reduced load capacity versus standalone configurations.
- Portable Washers:Compact top-load units serve labor accommodation camps and temporary hospitality installations where permanent plumbing is unavailable.
Most installed capacity flows through Washing Machines. Expansion is steepest in Dryers as hospitality operators retrofit heat-pump configurations.
End User:
Volume scale inversely correlates with margin intensity across this category.
- Residential:Individual households in Dubai's freehold towers and Abu Dhabi's master-planned communities drive replacement cycles averaging 7-10 years. ESMA efficiency labeling shapes retail purchase decisions.
- Commercial:Independent laundromats and linen service operators across the Emirates require 15-50 kg capacity machines with continuous-duty motors and coin-payment integration.
- Industrial:Textile processors and central laundry facilities demand 100+ kg batch washers with automated chemical dosing and tunnel finishing systems.
- Hospitality:Captive laundry investments by Dubai's four- and five-star properties emphasize throughput reliability and brand-standard fabric finish quality over capital cost minimization.
Commercial operators deploy the largest unit volumes. Hospitality end-use is climbing fastest as hotel chains internalize linen processing.
Technology:
Certification grade separates premium procurement from commodity bidding.
- Smart Appliances:IoT-enabled platforms with remote diagnostics and utility management integration are becoming mandatory in new Dubai property developments. These systems connect to building energy management infrastructure.
- Energy-Efficient:ESMA-certified machines with optimized water consumption and heat-pump drying meet federal procurement criteria for government and commercial tenders.
- Top Load:Conventional agitator and impeller designs retain price-sensitive residential segments and commercial operators prioritizing capital expenditure over operating cost.
- Front Load:Horizontal-axis engineering with variable-speed drives dominates premium residential and all commercial hospitality specifications due to superior water extraction and fabric handling.
Front Load configurations represent the dominant installed base. Smart Appliances are gaining share fastest as MOHAP mandates tighten and property developers standardize on connected infrastructure.
Distribution Channel:
Project channel concentration versus retail fragmentation defines competitive access.
- Online Retail:E-commerce platforms serve replacement demand in residential segments with standardized delivery logistics and price transparency.
- Offline Retail:Appliance showrooms in Dubai's electronics districts and mall anchors provide tactile evaluation for premium residential purchases.
- Direct Sales:Manufacturer-led project teams engage hospitality and healthcare procurement with engineered solutions, installation supervision, and service contracting.
- Wholesalers:Bulk distributors supply independent commercial laundries and property maintenance contractors with inventory availability and credit terms.
Direct Sales captures the highest-value hospitality contracts. Online Retail is expanding most quickly as residential replacement cycles digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality corridor anchors UAE laundry equipment demand through captive laundry investments by four- and five-star properties seeking linen cost control.
Dubai
Hotel operators across Downtown Dubai and Dubai Marina are expanding in-house laundry capacity to reduce outsourced linen expenditures. ESMA efficiency mandates shape procurement specifications for new equipment installations. Jebel Ali's logistics zone concentrates distribution infrastructure serving commercial laundries throughout the emirate.
Abu Dhabi
Healthcare corridor expansion in Al Reem Island and Yas Island drives demand for hygienic textile processing at institutional scale. MOHAP appliance safety requirements tighten market entry standards for imported equipment. The medical district's central laundry facilities require continuous-duty machines with automated chemical dosing systems.
Sharjah
Residential tower developments in Al Nahda and Muwaileh favor space-constrained washer-dryer combos despite longer cycle times. Federal water consumption thresholds enforced by the national standards regulator narrow available product ranges. Industrial zones host independent commercial laundries serving labor accommodation camps.
Northern Emirates
Ajman and Ras Al Khaimah property developments prioritize capital-efficient top-load configurations in mid-market residential segments. Escalating water tariffs compress operating margins for high-throughput commercial installations. Free zone manufacturing facilities supply portable washers to temporary hospitality infrastructure.
UAE Laundry Appliances Market Competitive Landscape
Global majors compete with regional champions across distribution channel access and service network density. The vendor base clusters around three tiers: integrated electronics conglomerates with smart appliance ecosystems, specialized laundry equipment manufacturers with commercial engineering depth, and regional distributors with project channel relationships. Dominant competitive moves include backward integration into component manufacturing and predictive maintenance service contracting.
Within the integrated electronics tier, LG Electronics and Samsung Electronics exemplify platform-centric positioning through connected laundry systems. Bosch occupies a position among European engineering specialists emphasizing energy-efficient front-load configurations. These three anchors represent divergent strategic archetypes: ecosystem integration, building management system compatibility, and regulatory compliance engineering.
| Leading Market Players |
|---|
| LG Electronics |
| Samsung Electronics |
| Whirlpool Corporation |
| Electrolux AB |
| Bosch |
| Haier Group |
| Panasonic Corporation |
| Hitachi Appliances Inc |
| Nikai |
| Others |
Value Network & Pricing Analysis
Captive service contracting by LG Electronics and Samsung Electronics anchors pricing power across Dubai's hospitality procurement channel, tying equipment margins to long-term maintenance revenue streams rather than transactional unit sales. This backward integration into after-sales infrastructure allows integrated conglomerates to defend premium positioning against specialized manufacturers lacking comparable service density.
Pricing Analysis
Input-cost pass-through from stainless steel drums and variable-speed drive motors shapes pricing dynamics across equipment tiers. Three-tier pricing structure across premium smart-connected, standard energy-efficient, and economy top-load levels stratifies the market by certification grade and IoT integration depth. Pricing pressure stems from escalating water tariffs compressing operating margins for high-throughput commercial operators, forcing capital expenditure trade-offs toward heat-pump configurations. Independent commercial laundries exhibit highest price sensitivity, while hospitality operators prioritize throughput reliability over capital cost minimization.
Supply Chain Analysis
Reverse-logistics flows for drum motor refurbishment and control board remanufacturing remain underdeveloped across the Emirates, creating aftermarket service gaps. Manufacturing concentration centers on China, South Korea, and Germany for precision drive components and heat-pump compressor assemblies. The supply chain draws from copper winding supplies, electronic control modules, and corrosion-resistant drum alloys as critical inputs. Single-source vulnerability in semiconductor-based motor controllers presents structural risk given global chip allocation constraints. Distribution runs through Jebel Ali logistics zones serving project-channel direct sales and wholesale inventory stocking for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE laundry appliances market functions as a geographic-arbitrage play between Dubai's premium hospitality specifications and Sharjah's price-sensitive residential towers, with ESMA efficiency mandates creating regulatory differentiation that favors certified suppliers in government-linked procurement channels.
For Market Incumbents: Extend predictive maintenance service contracts as standalone revenue streams to counter margin compression from hardware commoditization. Deepen backward integration into heat-pump compressor manufacturing to reduce dependency on Korean and German component suppliers. Secure MOHAP pre-certification for next-generation smart grid integration standards ahead of mandate tightening.
For New Entrants and Emerging Players: Capture the healthcare corridor expansion in Abu Dhabi's medical district where hygienic textile processing demand outpaces established vendor coverage. Target independent commercial laundries in Sharjah's industrial zones with capital-efficient top-load configurations and flexible credit terms. Deploy wholesaler partnerships as the primary go-to-market angle to bypass incumbent-dominated direct sales channels.
For Investors and Strategic Acquirers: Roll-up economics work for regional service networks with dense technician footprints because predictive maintenance capabilities command recurring revenue multiples unavailable to pure equipment vendors. Acquisition targets should demonstrate installed base concentration in hospitality or healthcare verticals with multi-year service contract backlogs. Monitor ESMA efficiency mandate enforcement intensity as the signal to watch for procurement specification inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Contracting | Transforms transactional equipment sales into recurring revenue streams with hospitality operators. |
| Heat-Pump Technology Licensing | Enables mid-tier manufacturers to meet ESMA efficiency benchmarks without captive R&D investment. |
| Smart Grid Integration Partnership | Connects appliance platforms with Dubai building energy management infrastructure for utility-sponsored procurement. |
| Healthcare Corridor Distribution Expansion | Captures underpenetrated demand for hygienic textile processing in Abu Dhabi's medical district. |
| Technician Certification Program Development | Addresses qualified service personnel shortages limiting IoT-enabled equipment deployment velocity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospitality procurement directors, commercial laundry operators, biomedical engineers at healthcare facilities, and aftermarket service technicians with secondary validation. Secondary sources included ESMA efficiency certification databases, MOHAP appliance safety filings, customs import records for laundry equipment, and property development pipeline disclosures from Dubai and Abu Dhabi master planners. Bottom-up equipment shipment tracking and top-down hospitality capacity expansion estimates were triangulated to anchor volume assumptions.
Segment-weighting approaches distributed total market value across product type, end-use intensity, technology integration depth, and distribution channel dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating replacement cycle dynamics, new property development pipelines, and regulatory mandate phase-in schedules across the projection horizon. Forecast inputs included water tariff escalation trajectories, MOHAP smart appliance integration timelines, and hospitality linen internalization rates by property tier.
Water tariff policy reversals, MOHAP mandate delay or acceleration, and heat-pump technology cost curve movements are the dominant revision risks for forecast trajectories. Practitioners should monitor ESMA enforcement intensity, hospitality occupancy recovery patterns, and semiconductor allocation dynamics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
China Major Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
Green Smart Household Appliances Market
Home Appliances
UAE Major Home Appliances Market