
 United States Home Appliances Market | 2026-2036
United States Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United States Home Appliances Market Outlook
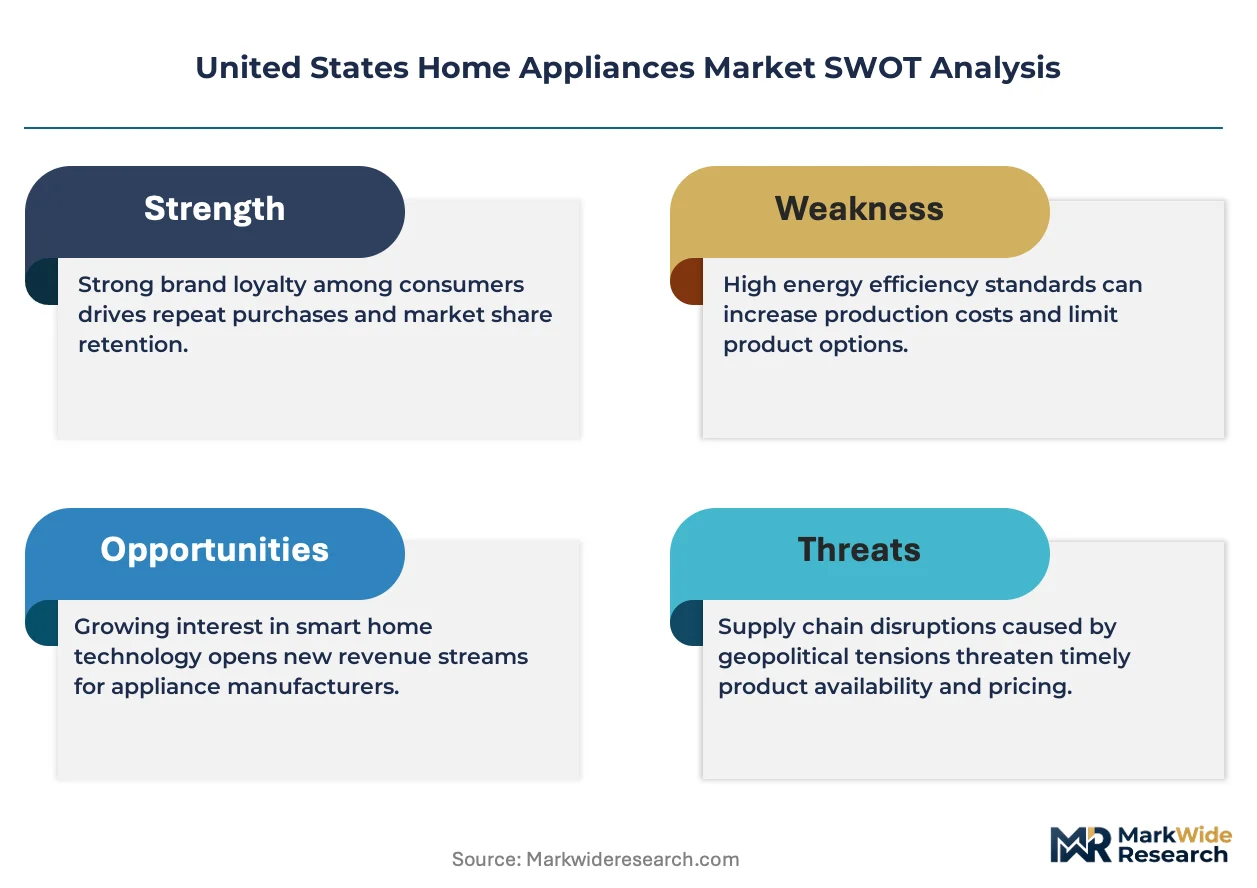
DOE appliance efficiency standards is restructuring the cost-of-entry calculus for manufacturers serving the United States. Whirlpool Corporation leverages its North American manufacturing footprint to absorb compliance-driven component upgrades. LG Electronics anchors its position through in-house compressor and motor production. Samsung Electronics differentiates via ecosystem integration across refrigeration and laundry platforms.
United States home appliances comprise electromechanical devices designed for domestic tasks such as food preservation, garment cleaning, and meal preparation, typically operating on 120V residential circuits with EnergyGuide-labeled consumption metrics. Refrigerators and washing machines command the largest installed base and replacement revenue pools, while smart appliances represent the fastest-growing technology segment as Wi-Fi connectivity and voice control become standard expectations. The end-user split between suburban households and apartment dwellers creates divergent form-factor requirements, with compact and stackable configurations gaining traction in multi-unit dwellings.
EPA ENERGY STAR certification, DOE minimum efficiency standards, and NHTSA-related logistics emissions rules collectively shape product design priorities and distribution compliance burdens for the United States market. The Inflation Reduction Act's electrification incentives directly alter consumer payback calculations for heat-pump dryers and induction ranges. Stakeholders must track how state-level building code amendments in California and New York propagate efficiency thresholds faster than federal timelines.
Market Dynamics
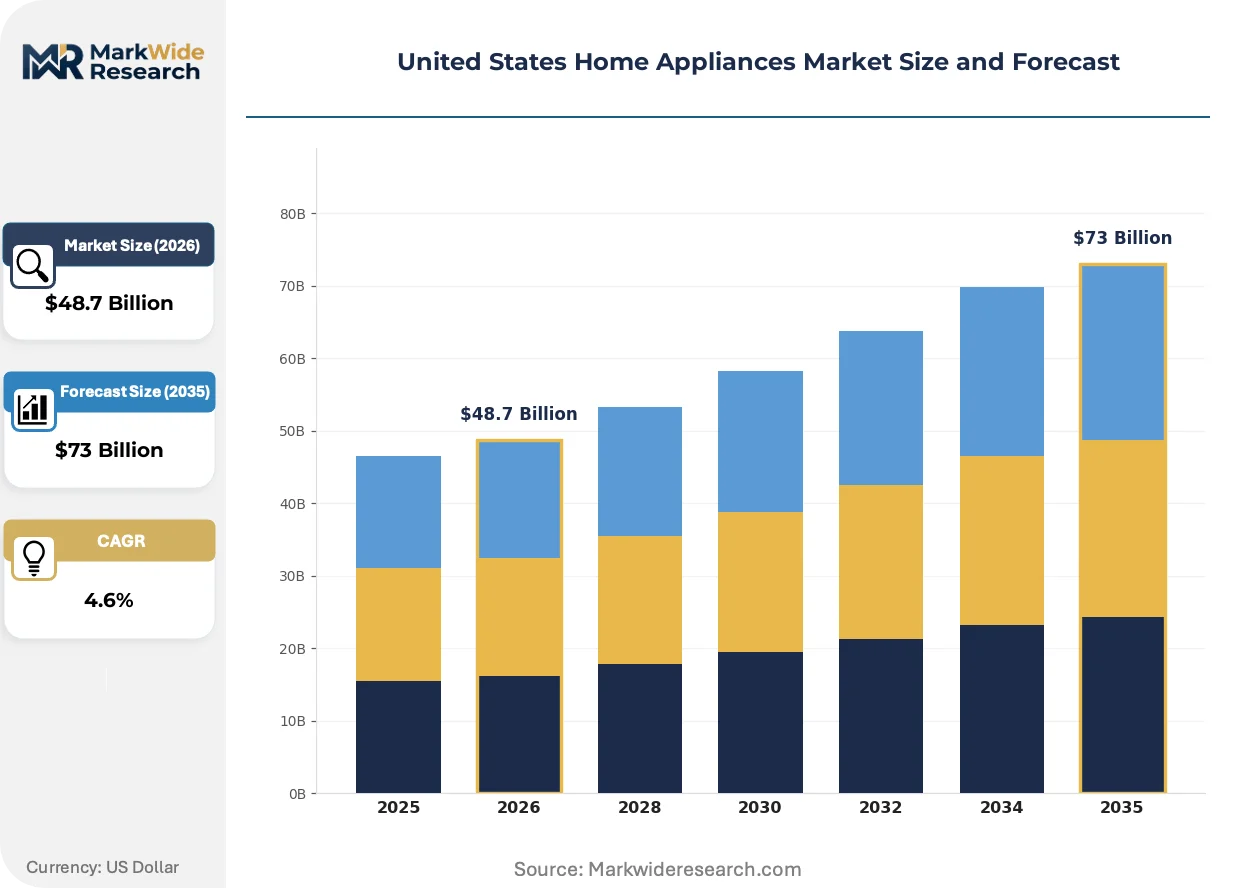
The Inflation Reduction Act's electrification rebates are compressing replacement cycles and redirecting consumer capital toward heat-pump-enabled appliance categories, restructuring manufacturer portfolio priorities and channel inventory planning across the United States.
Growth Catalysts
- Inflation Reduction Act rebates:Federal incentives for heat-pump dryers and induction ranges accelerate payback calculations for energy-efficient upgrades in Sun Belt metropolitan areas.
- Wi-Fi connectivity standardization:Smart kitchen and laundry platforms are capturing replacement demand as voice control and app integration become baseline consumer expectations.
- Texas and Florida construction:New single-family housing permits in these states concentrate demand for connected appliance suites during overlapping replacement and new-purchase cycles.
Market Restraints
- Copper and rare-earth magnet costs:Compressor motor and induction coil input volatility squeezes margin structures for mid-tier product lines.
- DOE efficiency rule acceleration:Compliance-driven component redesigns compress development timelines and raise certification costs ahead of federal implementation dates.
- Heat-pump dryer space constraints:Ventless installation requirements limit adoption in multi-unit dwellings and older residential stock with inadequate electrical capacity.
Strategic Opportunities
- California and New York building codes:State-level efficiency thresholds that outpace federal timelines create early-mover positioning for compliant product portfolios.
- Apartment-dweller form factors:Compact stackable configurations for multi-unit dwellings address an underserved segment with distinct spatial and electrical constraints.
- EPA ENERGY STAR certification convergence:Tiered efficiency labeling creates channel differentiation and pricing authority in big-box and direct-to-consumer channels.
Industry Challenges
- Embedded systems engineering talent:Shortages in firmware and IoT security expertise delay smart platform rollouts and connected-service monetization.
- Legacy 120V circuit compatibility:Heat-pump and induction technologies require electrical infrastructure upgrades that fragment addressable household penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Home Appliances Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Refrigerators, Dishwashers, Ovens Technology: Smart Appliances, Energy-Efficient, Traditional, Hybrid End User: Urban Households, Suburban Households, Apartment Dwellers, Single Family Homes Price Tier: Premium, Mid-Range, Budget, Economic |
| Companies Covered | Whirlpool Corporation, Electrolux Group, LG Electronics, Haier Smart Home, BSH Home Appliances Corporation, Samsung Electronics, Frigidaire, Maytag, GE Appliances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Home Appliances Market Strategic Shifts
Connectivity and electrification are converging to redefine appliance architecture, with software-enabled functionality and heat-pump mechanics displacing legacy electromechanical designs across kitchen and laundry categories.
Heat-pump drying technology is expanding into residential laundry as a replacement for conventional vented electric and gas dryers. Suburban households in new construction are adopting these systems fastest due to installation flexibility and rebate stacking. This shift is expanding into builder-specified packages and multi-appliance bundled sales, compressing standalone dryer margins while elevating whole-suite pricing power.
DOE minimum efficiency standards are forcing compressor and motor redesigns across refrigeration and laundry platforms. Manufacturers must retool production lines and validate components against stricter test procedures before federal effective dates. The regulatory pressure is concentrating most intensely on top-mount refrigerator and standard clothes washer categories, where baseline energy consumption thresholds are tightening fastest.
Voice control and app-based diagnostics are becoming standard purchase criteria rather than premium differentiators. Big-box retailers are bundling installation and extended warranty services to capture recurring revenue streams previously reserved for manufacturer service networks. This behavioral shift is most visible in suburban Sun Belt markets where new construction buyers expect seamless smart-home integration from move-in date.
United States Home Appliances Market Segmentation
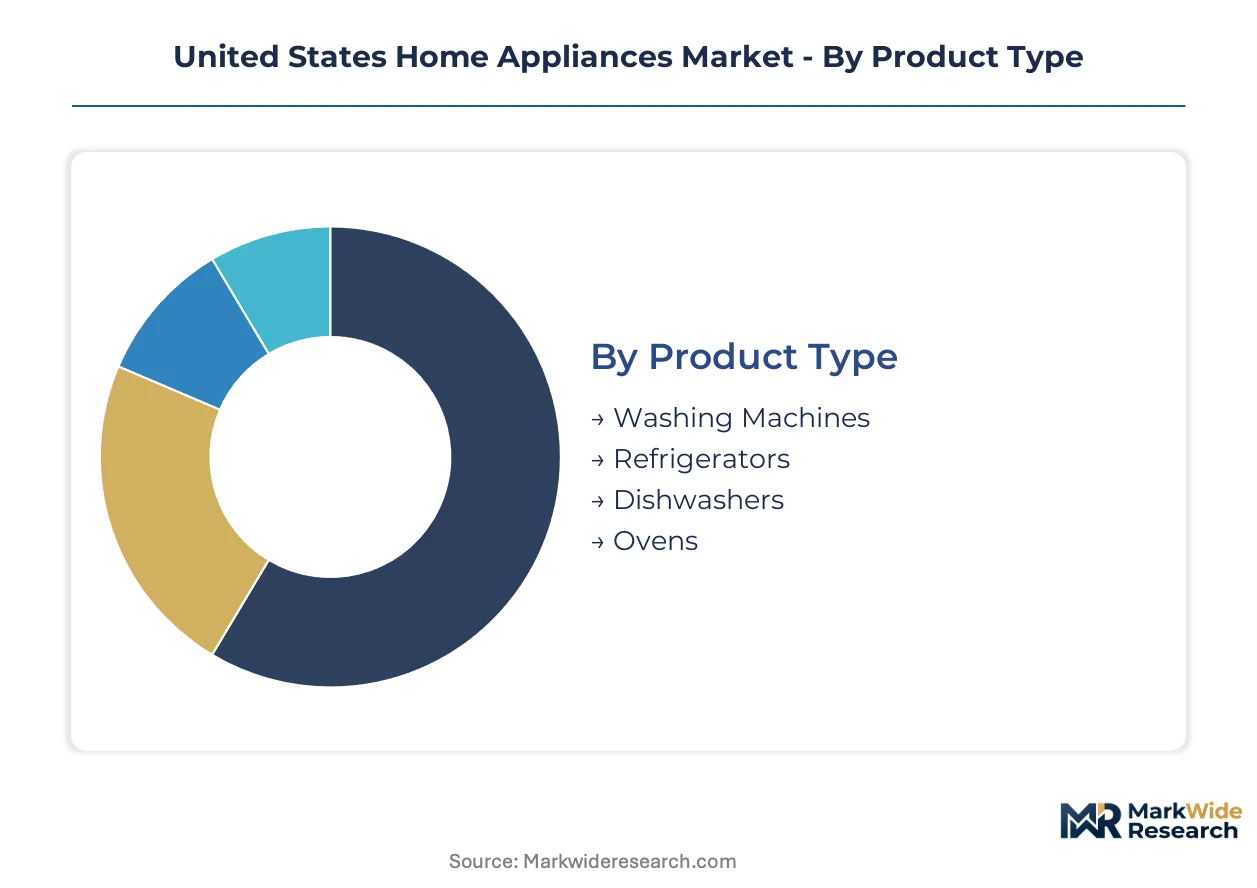
Segmentation in the United States home appliances market reveals how electrification mandates, connectivity standards, and housing stock variations create distinct demand clusters. Manufacturers must align product specifications with circuit infrastructure, rebate eligibility, and installation constraints across divergent household types.
Product Type:
Refrigeration and laundry platforms anchor the technology investment cycle as DOE efficiency rules force compressor and motor redesigns ahead of compliance deadlines.
- Refrigerators:Top-mount and French-door configurations dominate replacement revenue. EPA ENERGY STAR tiered labeling concentrates demand in suburban Sun Belt households where rebate stacking accelerates upgrade cycles.
- Washing Machines:Front-load drum mechanics and variable-speed drives define the efficiency frontier. Texas and Florida new construction specifications favor large-capacity units with connected diagnostics for builder-specified packages.
- Dishwashers:Quiet-operation decibel ratings and soil-sensor automation differentiate mid-tier offerings. Apartment dwellers in multi-unit dwellings drive compact under-counter demand where space constraints limit full-size adoption.
- Ovens:Induction coil and convection fan technologies split the market between electrical infrastructure upgrade requirements. Single-family homeowners in California and New York face accelerated replacement timelines from state-level building code amendments.
Mature deployment sits with refrigerators and washing machines. Newer deployment is concentrated in induction-enabled ovens and connected dishwashers.
Technology:
Cost tier stratification separates compliance-driven efficiency investments from premium connectivity upgrades.
- Smart Appliances:Wi-Fi modules and voice-control integration require firmware engineering capabilities that concentrate among major manufacturers. Suburban households in new construction expect seamless app-based diagnostics and energy monitoring from move-in date.
- Energy-Efficient:Heat-pump mechanics and inverter-driven compressors meet DOE test procedure thresholds. The Inflation Reduction Act's electrification rebates compress payback calculations for qualifying dryers and refrigeration platforms.
- Traditional:Electromechanical controls and standard-efficiency motors serve replacement demand in older residential stock with inadequate electrical capacity for heat-pump or induction loads.
- Hybrid:Partial connectivity with basic efficiency upgrades occupies the mid-market price band. Apartment dwellers select these configurations where circuit limitations prevent full electrification retrofits.
Volume concentration favors traditional and energy-efficient categories. Steepest expansion trajectory belongs to smart appliances as Wi-Fi standardization erodes premium pricing.
End User:
Application requirements diverge sharply between single-family installation flexibility and multi-unit spatial constraints.
- Single Family Homes:Full-size appliance suites with connected kitchen and laundry platforms dominate this segment. Texas and Florida construction permits concentrate demand for builder-specified packages during overlapping replacement and new-purchase cycles.
- Suburban Households:Two-car garage electrical panels support heat-pump dryer and induction range adoption. EPA ENERGY STAR certification drives tiered purchasing decisions in big-box retail channels.
- Apartment Dwellers:Compact stackable configurations and ventless drying mechanics address spatial and circuit limitations. Multi-unit dwellings in Sun Belt metropolitan areas create underserved demand for 24-inch width and combined washer-dryer units.
- Urban Households:High-rise electrical infrastructure and property management procurement patterns favor standardized mid-tier offerings with extended warranty coverage.
Margin structure peaks with suburban households. Fastest volume gains are emerging from apartment dwellers as rental stock modernization accelerates.
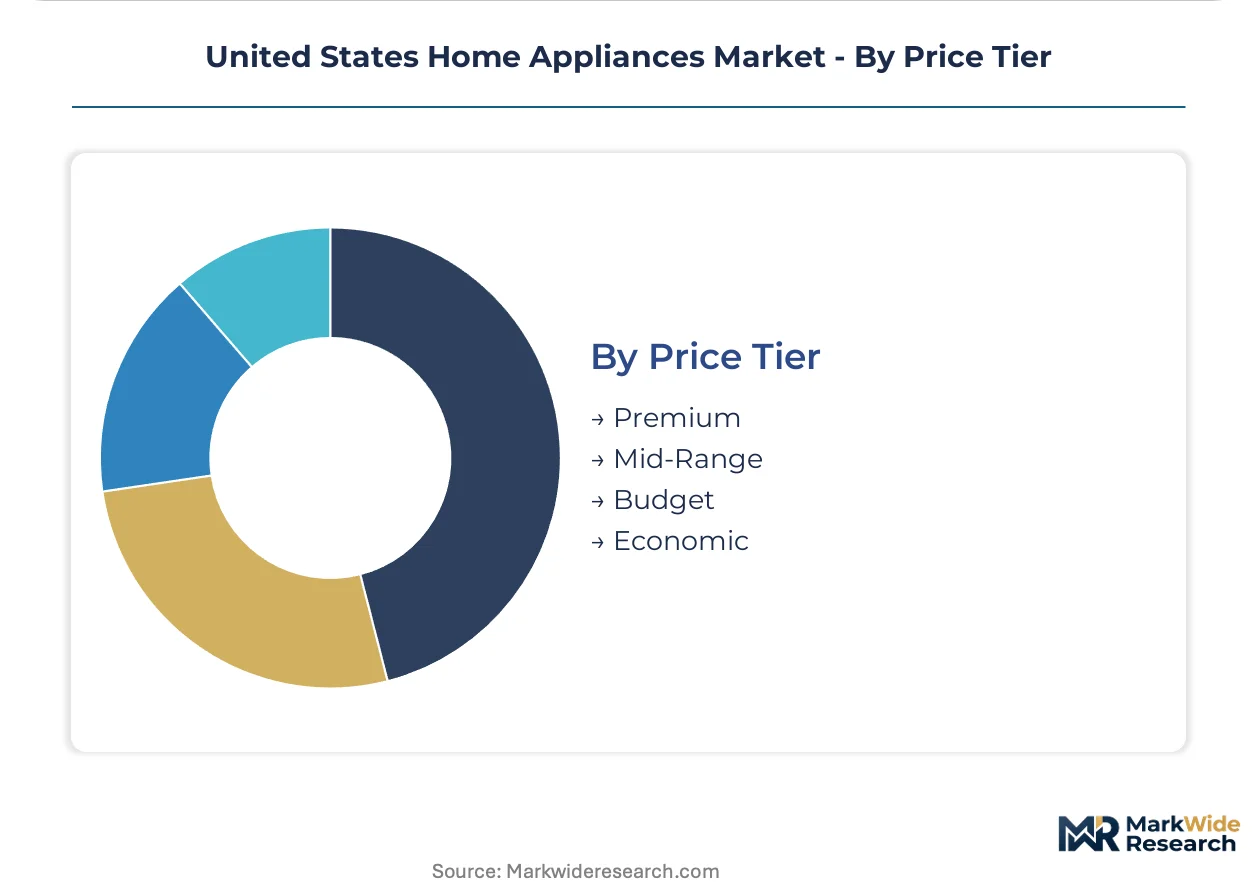
Price Tier:
Customer type and margin profile stratify across certification grade and feature bundling rather than pure component cost.
- Premium:Full ecosystem integration with voice control, app diagnostics, and extended warranty coverage. Suburban new construction buyers accept bundled suite pricing for seamless smart-home integration.
- Mid-Range:Selective connectivity with EPA ENERGY STAR certification meets rebate eligibility thresholds. Single-family replacement cycles concentrate in this tier as IRA incentives redirect capital toward efficiency upgrades.
- Budget:Basic efficiency compliance with limited feature sets serves price-sensitive replacement demand. Older residential stock in Texas and Florida relies on these offerings where electrical upgrades are deferred.
- Economic:Entry-level electromechanical designs with minimal connectivity serve rental property and emergency replacement scenarios. Channel inventory concentrates in big-box retail for immediate availability.
Revenue concentration sits with premium and mid-range tiers. Volume leadership belongs to budget and economic segments as replacement cycles compress in inflation-sensitive households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Sun Belt metropolitan areas where new construction and replacement cycles overlap, with Texas and Florida single-family homeowners driving connected kitchen suite upgrades.
California
State-level building code amendments accelerate efficiency thresholds faster than federal timelines, forcing manufacturer portfolio adjustments. CARB emissions rules and Title 24 energy standards reshape induction range and heat-pump dryer specifications. Los Angeles and San Francisco Bay Area households anchor premium-tier adoption for EPA ENERGY STAR-certified connected appliances.
Texas
New single-family housing permits in Dallas-Fort Worth and Houston concentrate demand for builder-specified appliance packages. ERCOT grid reliability concerns elevate interest in energy-efficient refrigeration and variable-speed HVAC-adjacent laundry systems. Austin and San Antonio metro areas exhibit fastest smart-home integration adoption among new construction buyers.
Florida
Humidity-driven replacement cycles compress refrigerator and dehumidifier-enabled appliance turnover in Miami and Tampa markets. Hurricane resilience building codes influence standby power and grid-interactive feature prioritization. Orlando and Jacksonville construction corridors drive volume for mid-range connected suites in suburban developments.
New York Metro
Local Law 97 carbon caps and state electrification mandates accelerate induction range and heat-pump dryer adoption in multi-unit dwelling retrofits. Constrained electrical infrastructure in pre-war housing stock fragments addressable penetration for high-draw appliances. Brooklyn and Queens rental modernization programs create compact form-factor demand.
Southeast (Georgia/Carolinas)
Atlanta and Charlotte new construction corridors replicate Texas-Florida demand patterns for connected kitchen suites. Lower electricity rates relative to Northeast markets delay heat-pump premium payback calculations. Savannah and Charleston ports facilitate import logistics for Asian-manufactured components serving regional distribution networks.
United States Home Appliances Market Competitive Environment
North American producers anchor mid-tier manufacturing and distribution infrastructure; Asian electronics conglomerates hold ecosystem integration and component captive supply advantages. The vendor base stratifies across three tiers: diversified conglomerates with in-house compressor and motor production, regional specialists with North American assembly footprints, and private-label assemblers serving price-sensitive channels. Dominant competitive moves include backward integration into core electromechanical components and strategic partnerships with smart-home platform operators.
Within the diversified conglomerate tier, Whirlpool Corporation and LG Electronics exemplify archetypes of regional manufacturing leverage versus vertical component control. Samsung Electronics occupies a position emphasizing cross-platform ecosystem integration. Among European-rooted specialists, Electrolux Group and BSH Home Appliances Corporation represent premium-tier positioning through design differentiation and energy efficiency certification concentration.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Electrolux Group |
| LG Electronics |
| Haier Smart Home |
| BSH Home Appliances Corporation |
| Samsung Electronics |
| Frigidaire |
| Maytag |
| GE Appliances |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation across EPA ENERGY STAR certification tiers manifests in parallel supply chain configurations, with rebate-eligible efficiency grades commanding dedicated component sourcing while budget tiers draw from standardized electromechanical suppliers. The Inflation Reduction Act's electrification incentives compress payback calculations for heat-pump-enabled categories, redirecting procurement capital toward inverter-driven compressor and induction coil suppliers while fragmenting margin structures across compliance-driven versus legacy product lines.
Pricing Analysis
Volume concentration in budget and economic tiers runs counter to margin capture in premium and mid-range segments, with certification grade and after-sales service bundling as the primary price differentiation drivers. Pricing pressure stems from copper and rare-earth magnet input volatility squeezing mid-tier product lines. First-time buyers in apartment-dweller segments exhibit highest price sensitivity, while suburban new construction buyers accept bundled suite pricing for seamless smart-home integration.
Supply Chain Analysis
Workforce availability constraints in Mexico, China, and South Korea shape manufacturing location decisions for compressor and motor assembly operations. The industry draws from copper wiring, rare-earth magnets, and semiconductor-grade Wi-Fi modules as critical inputs. Tariff exposure on Chinese-sourced induction coils and control boards presents structural supply chain risk. Distribution runs through big-box retail channels, direct-to-consumer platforms, and builder-specified procurement networks serving new construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States home appliances market sits in a technology-transition phase as heat-pump mechanics and inverter-driven compressors displace legacy electromechanical designs across refrigeration and laundry platforms. This displacement is restructuring manufacturer portfolio priorities and channel inventory planning.
For Market Incumbents: Hedge against margin compression in standard-efficiency categories by accelerating backward integration into compressor and motor production. Secure captive supply of rare-earth magnets and copper winding capacity before input volatility intensifies. Channel control through extended warranty bundling with big-box retailers defends service revenue streams against emerging platform competitors.
For New Entrants and Emerging Players: Begin with compact stackable configurations for apartment dwellers in Sun Belt metropolitan areas, where spatial and circuit constraints have left demand underserved. Target 24-inch width and combined washer-dryer units for multi-unit dwelling retrofits. A direct-to-consumer go-to-market angle with installation partnerships bypasses incumbent retail slotting advantages.
For Investors and Strategic Acquirers: Re-rating potential sits with firmware engineering specialists given smart appliance platform rollouts accelerating voice control and app-based diagnostics as baseline expectations. Long-term viability over a multi-year horizon favors targets with in-house IoT security capabilities and EPA ENERGY STAR certification concentration. The signal to watch is state-level building code amendments in California and New York outpacing federal timelines, creating early-mover positioning premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Production | Captive motor manufacturing absorbs DOE compliance-driven component upgrade costs for Whirlpool and LG. |
| Smart Home Platform Integration | Samsung's cross-platform ecosystem connectivity captures suburban new construction buyers expecting seamless voice control. |
| Compact Form Factor Development | 24-inch stackable configurations address apartment-dweller spatial constraints in Texas and Florida multi-unit dwellings. |
| EPA ENERGY STAR Tier Concentration | Tiered efficiency labeling creates channel differentiation and pricing authority in big-box retail channels. |
| Builder-Specified Package Partnerships | New construction procurement in Dallas-Fort Worth and Houston corridors locks in multi-appliance bundled sales volume. |
Study Parameters
Multi-period observation of DOE efficiency standard implementation timelines, IRA rebate uptake patterns, and Wi-Fi connectivity adoption curves anchored the trend analysis, supplemented by interviews with appliance manufacturing executives, big-box retail category buyers, HVAC contractor network heads, and multi-family property management procurement directors. Secondary validation drew from EPA ENERGY STAR certification databases, DOE compliance filings, customs import records for compressor components, and SEC 10-K disclosures from listed manufacturers. Bottom-up unit shipment modeling and top-down consumer expenditure analysis were triangulated against channel inventory checks.
Segment-weighting across product type, technology tier, end-user household structure, and price band informed the analytical framework over the projection horizon. Refrigeration and laundry platform volumes were modeled separately from emerging induction-enabled oven categories. CAGRs were derived from replacement cycle compression rates intersecting with new construction permit flows and electrification incentive eligibility thresholds. Heat-pump dryer adoption curves and smart appliance Wi-Fi penetration rates served as category-specific forecast inputs.
Underlying measurement precision varies by segment; smart appliance connectivity metrics carry tighter precision than hybrid category definitions where partial electrification muddles classification. Forecasts reflect documented assumptions regarding IRA rebate continuity, copper price stabilization, and state-level code amendment propagation timelines. Material deviation in DOE implementation schedules or ERCOT grid reliability events warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Mexico Major Home Appliance Market
Home Appliances
Bahrain Major Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Household Appliance Market
Home Appliances
Japan Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market