
 Latin America Home Appliances Market | 2026-2036
Latin America Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Home Appliances Market Foresight
Consumer leasing and installment financing through retail chains is rewriting competitive access across Latin America. Whirlpool Corporation leverages its captive distribution network to sustain volume leadership in Mexico and Central America. Mabe anchors production scale through its Monterrey manufacturing base, while LG Electronics competes aggressively on inverter technology across Brazilian metro markets.
Latin America home appliances encompass electrically powered machines for domestic food preservation, cleaning, cooking, and climate management, typically operating on 127V or 220V regional standards with energy efficiency ratings governed by national testing protocols. Refrigerators command the largest product type share due to tropical climate requirements and food safety norms, while washing machines represent the fastest-growing segment as piped water access expands in peri-urban Brazil. The online sales channel is capturing incremental share from traditional retail, though offline wholesale still dominates commercial volume to hotels and restaurants.
INMETRO certification requirements in Brazil, Mexico's CONUEE energy standards, and Argentina's IRAM safety protocols collectively elevate compliance costs and filter out informal imports. These frameworks push manufacturers toward higher-efficiency compressors and refrigerant transitions, tightening market access for uncertified suppliers. Stakeholders must monitor how regulatory harmonization across Mercosur and the Pacific Alliance reshapes cross-border sourcing and local assembly requirements.
Market Dynamics
Inverter compressor technology is compressing replacement cycles across Brazilian and Mexican urban households, while INMETRO and CONUEE energy mandates force simultaneous refrigerant transitions and efficiency upgrades.
Growth Catalysts
- INMETRO labeling mandates:Brazil's energy certification requirements accelerate replacement demand for Class A refrigerators in São Paulo metro households.
- Piped water expansion:Washing machine penetration rises in peri-urban Brazil as municipal infrastructure reaches previously unserved districts.
- Installment financing proliferation:Retail chain credit programs unlock premium appliance uptake across Mexico City's formal employment zones.
Market Restraints
- Copper and steel input volatility:Compressor and cabinet manufacturing faces margin pressure from commodity price swings in Latin American sourcing markets.
- Import dependency concentration:Argentina's limited local assembly capacity creates vulnerability to foreign exchange fluctuations for finished goods.
- R-290 refrigerant technical limitations:Flammability constraints restrict charge sizes and complicate technician training for hydrocarbon-based systems.
Strategic Opportunities
- Colombian market underpenetration:Bogotá and Medellín metro areas show sub-40% inverter refrigerator adoption versus São Paulo's 65%.
- Online channel convergence:Marketplace platforms capture incremental share from traditional retail in Chile's Santiago corridor.
- Mercosur regulatory harmonization:Unified testing protocols reduce certification duplication costs for cross-border manufacturers.
Industry Challenges
- Technician certification bottlenecks:INMETRO and IRAM refrigerant handling licenses face 90-day processing delays in Brazil and Argentina.
- Legacy 127V infrastructure integration:Dual-voltage product lines complicate inventory management and service parts logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Home Appliances Market |
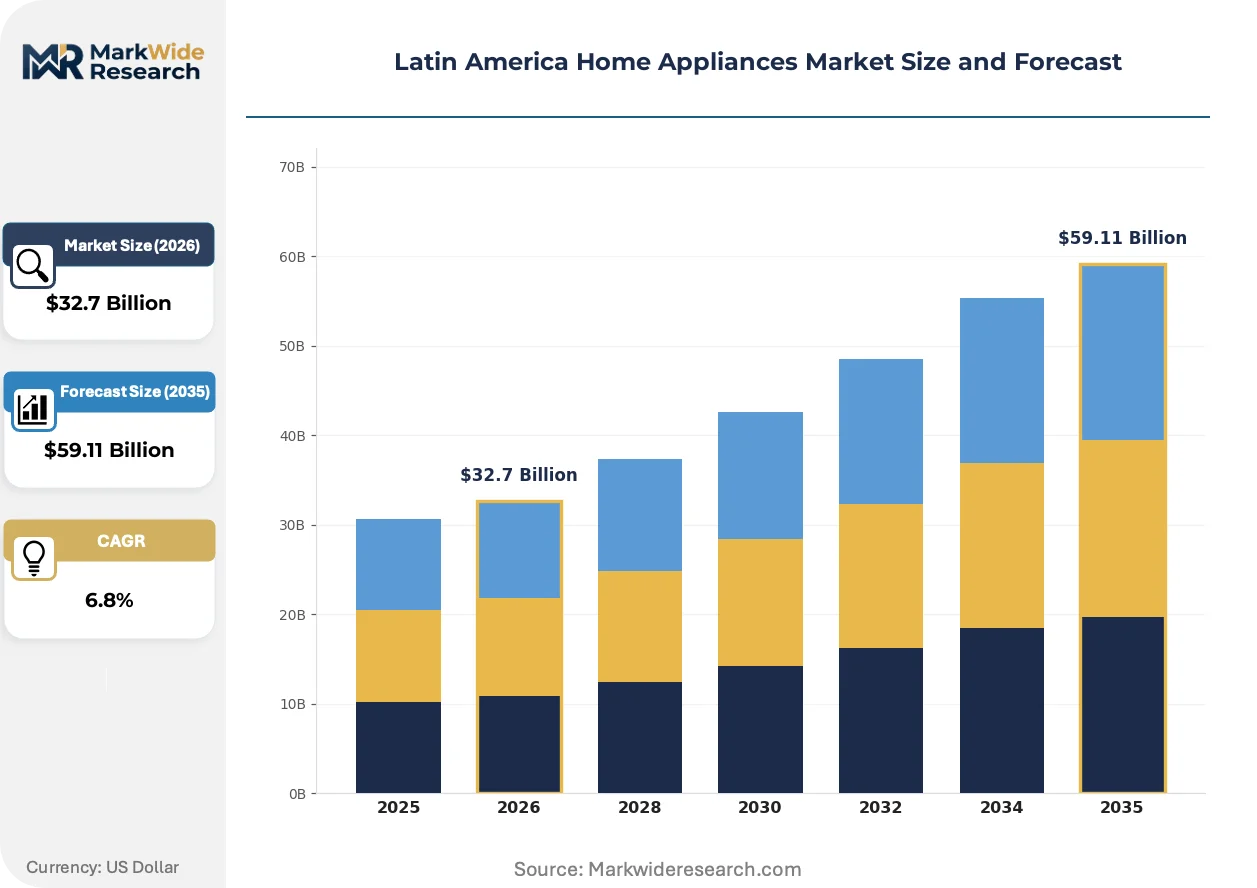
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Ovens End User: Households, Restaurants, Hotels, Retail Stores Sales Channel: Online, Offline, Retail, Wholesale Brand: LG, Samsung, Whirlpool, Electrolux |
| Companies Covered | Whirlpool Corporation, Bosch, LG Electronics, Miele, AEG, Samsung, Panasonic Corporation, Mabe, AB Electrolux, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Home Appliances Market Shifts & Advancements
Inverter-driven efficiency standards and digital retail integration are restructuring how appliances reach Latin American households and commercial buyers.
Variable-speed compressor technology is migrating from fixed-frequency systems to optimize energy consumption in tropical climates. Brazilian and Mexican urban households adopting inverter refrigerators reduce electricity expenditure by 30-40% versus conventional units. This migration from legacy compressor architectures is compressing replacement cycles and elevating price floors across the São Paulo–Mexico City corridor.
CONUEE energy standards in Mexico mandate minimum efficiency thresholds for imported and domestically manufactured refrigeration equipment. The framework eliminates sub-Standard B products from formal retail channels and forces manufacturers to consolidate SKUs around certified platforms. Mexican commercial buyers—hotels and restaurants—now specify CONUEE-compliant units in procurement tenders, filtering out uncertified suppliers.
Consumer financing unbundling is separating appliance acquisition from traditional banking relationships. Retail chains in Brazil and Mexico now originate installment credit in-house, bypassing commercial bank intermediation. This channel shift concentrates volume with vertically integrated retailers and compresses margins for independent distributors in secondary cities.
Latin America Home Appliances Market Segmentation
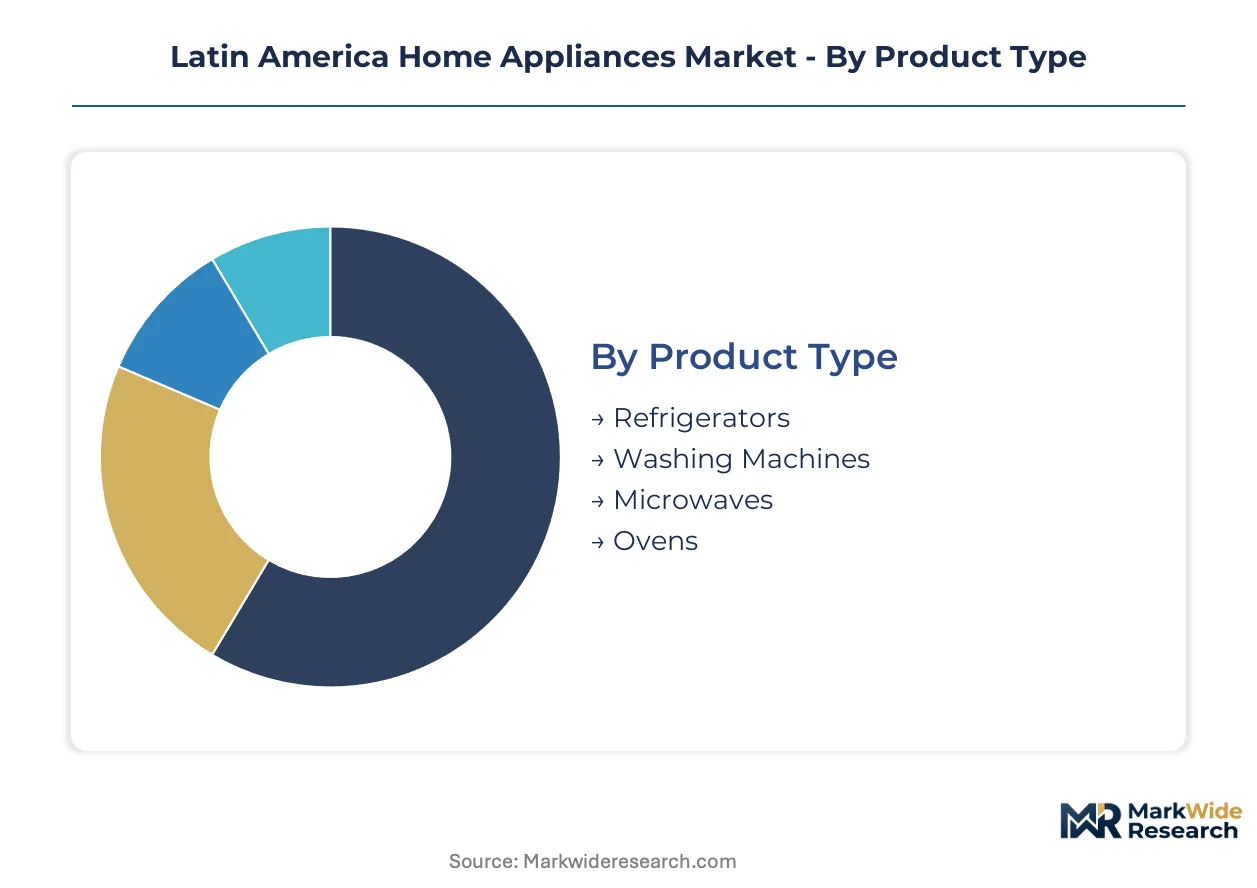
Latin America's home appliances market segments along four distinct axes that determine pricing power, distribution strategy, and regulatory exposure. Product type and sales channel dynamics dominate volume allocation, while end-user concentration and brand positioning shape margin capture across the São Paulo–Mexico City corridor.
Product Type:
Mature refrigeration platforms anchor revenue stability while emerging washing machine penetration drives expansion in peri-urban districts.
- Refrigerators:Compressor-based cooling systems operating on 127V or 220V regional standards with INMETRO Class A certification commanding premium positioning. São Paulo metro households concentrate replacement demand for inverter compressor units as electricity tariffs rise and energy labeling mandates tighten.
- Washing Machines:Front-load and top-load configurations requiring piped water infrastructure and drainage compatibility. Peri-urban Brazil shows the steepest expansion trajectory as municipal water networks extend into previously unserved districts outside Belo Horizonte and Salvador.
- Microwaves:Countertop and built-in variants with magnetron power ratings from 600W to 1200W.
- Ovens:Electric convection and gas-powered units for residential baking and roasting applications.
Refrigerators handle the majority of throughput; washing machines are gaining share fastest as infrastructure gaps close.
End User:
Volume concentration shifts from household replacement cycles toward commercial procurement tenders with CONUEE and INMETRO compliance requirements.
- Households:Urban nuclear families and multi-generational units purchasing through installment financing programs. Mexico City's formal employment zones concentrate premium appliance uptake via retail chain credit origination.
- Restaurants:Food service operators specifying certified refrigeration equipment in procurement contracts. São Paulo and Rio de Janeiro commercial corridors drive demand for high-capacity inverter compressors with reduced energy expenditure profiles.
- Hotels:Hospitality chains requiring uniform room appliance specifications across properties.
- Retail Stores:Appliance resellers and independent distributors serving secondary cities with limited brand direct presence.
Households absorb the dominant volume share; restaurants are expanding most quickly as commercial tenders formalize certification requirements.
Sales Channel:
Credit integration depth separates high-touch retail networks from transactional wholesale and emerging digital platforms.
- Online:Marketplace platforms with logistics partnerships for last-mile delivery in Chile's Santiago corridor and Brazilian state capitals. Digital payment infrastructure and installment options compress friction for standard-tier product acquisition.
- Offline:Brick-and-mortar retail with in-house financing origination bypassing commercial bank intermediation. Vertically integrated chains in Mexico and Brazil concentrate volume through captive credit programs and service bundling.
- Retail:Brand-flagged stores and multi-brand outlets with demonstration capacity and immediate fulfillment.
- Wholesale:Distributor networks supplying independent retailers and commercial buyers with volume pricing and extended payment terms.
Offline retail channels command the dominant transaction flow; online platforms show the steepest climb in incremental share capture.
Brand:
Manufacturing footprint and distribution integration determine competitive access across national certification regimes.
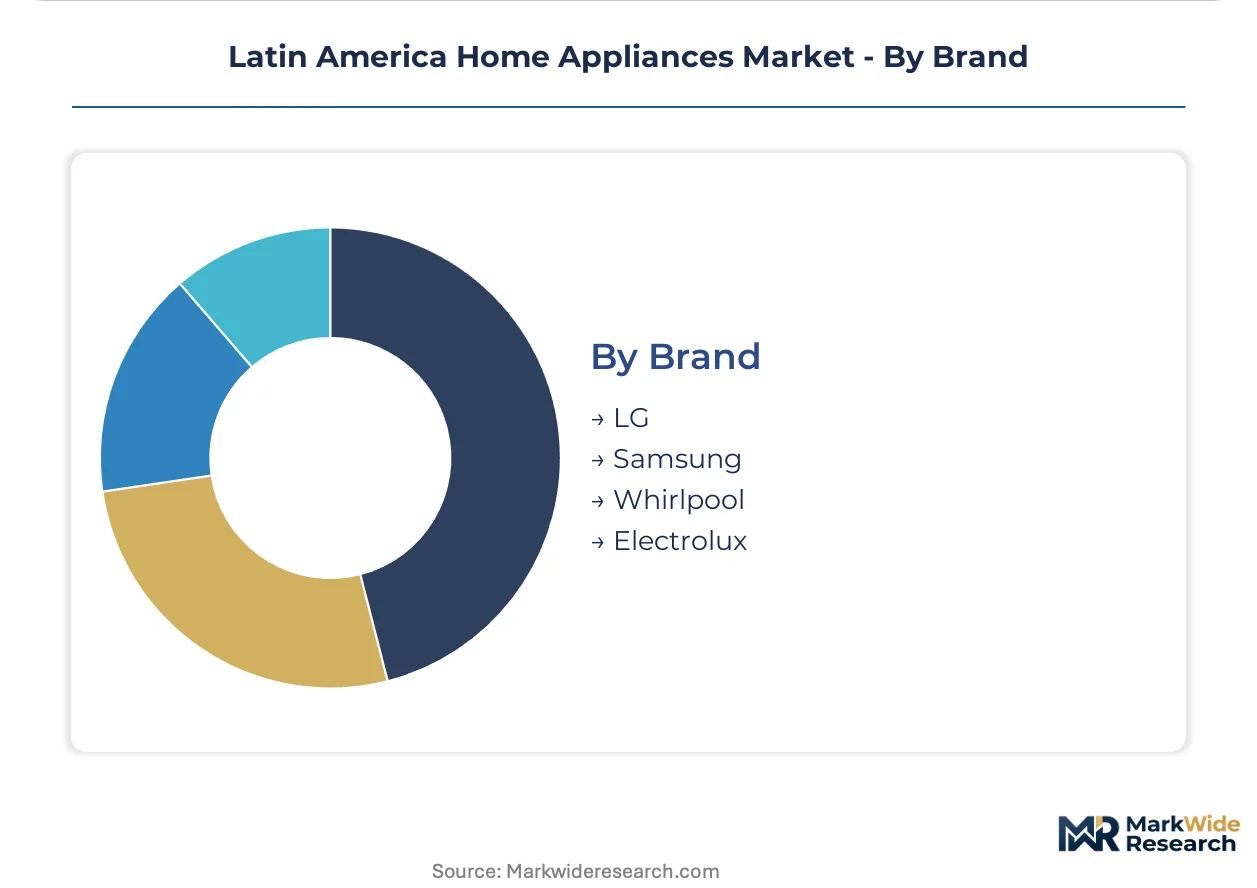
- LG:Korean electronics conglomerate competing aggressively on inverter technology deployment across Brazilian metro markets with localized assembly capacity.
- Samsung:Integrated appliance and consumer electronics portfolio leveraging regional supply chain scale for cost positioning in mid-tier segments.
- Whirlpool:North American multinational sustaining volume leadership through captive distribution networks in Mexico and Central America.
- Electrolux:Swedish appliance specialist with European design heritage targeting premium urban households in Buenos Aires and Santiago.
Whirlpool and LG handle the majority of established market throughput; Samsung is climbing fastest on integrated electronics-appliance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency varies sharply across Latin America, with local assembly capacity concentrated in Brazil and Mexico while Argentina and Chile rely heavily on finished goods imports. This trade imbalance shapes regulatory responses and manufacturing investment patterns.
Brazil
São Paulo metro households drive replacement demand for INMETRO Class A certified refrigerators as electricity tariffs climb. INMETRO energy labeling mandates eliminate sub-efficient models from formal retail channels. The Campinas industrial corridor anchors compressor manufacturing and inverter technology assembly for regional supply.
Mexico
Mexico City's formal employment zones concentrate premium appliance uptake through retail chain installment financing. CONUEE energy standards mandate minimum efficiency thresholds for domestic and imported refrigeration equipment. The Monterrey manufacturing base sustains captive production scale for North American and regional export markets.
Argentina
Buenos Aires households face appliance price volatility tied to foreign exchange fluctuations for finished imports. IRAM safety protocols and refrigerant handling certification requirements filter out uncertified suppliers. Limited local assembly capacity concentrates distribution through formal retail networks in the capital corridor.
Chile
Santiago's marketplace platforms capture incremental share from traditional retail through digital payment infrastructure and logistics partnerships. National energy efficiency standards align with regional Mercosur harmonization efforts. The Valparaíso port cluster handles import throughput for Andean market redistribution.
Colombia
Bogotá and Medellín metro areas show sub-40% inverter refrigerator adoption, creating expansion headroom for efficient technology penetration. Municipal water infrastructure expansion in peri-urban districts enables washing machine penetration growth. The Bogotá-Sabana industrial zone hosts limited final assembly operations dependent on imported components.
Latin America Home Appliances Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: multinational manufacturers with captive regional assembly, mid-scale regional specialists leveraging geographic proximity, and import-dependent distributors serving price-sensitive segments. Strategic archetypes include vertically integrated appliance conglomerates, electronics conglomerates diversifying into white goods, and regional manufacturing platforms optimized for tariff-advantaged production. Capacity expansion and certification-driven portfolio consolidation represent the dominant competitive moves.
Among North American and European multinationals, Whirlpool Corporation and AB Electrolux exemplify the vertically integrated archetype through captive distribution networks and regional manufacturing footprints. LG Electronics occupies a position representing the electronics conglomerate model, competing on inverter technology deployment across Brazilian metro markets. Mabe anchors the regional manufacturing specialist tier through its Monterrey production base serving Mexico and Central American markets.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Bosch |
| LG Electronics |
| Miele |
| AEG |
| Samsung |
| Panasonic Corporation |
| Mabe |
| AB Electrolux |
| Others |
Supply & Pricing Matrix
The Monterrey manufacturing cluster anchors regional compressor assembly capacity and feeds downstream pricing power to Mexican distributors serving Central American markets. Brazilian buyers in São Paulo metro corridors face elevated landed costs as INMETRO certification requirements filter out uncertified imports and compress supply alternatives.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in Latin American home appliances. Price differentiation rests on INMETRO Class A certification status and captive distribution integration, with certified inverter compressors commanding premiums over conventional units. Cost compression in economy tiers is intensifying because steel and copper input volatility squeezes cabinet and compressor margins. Small independent retailers in secondary Brazilian cities show highest price sensitivity, while hospitality chains in Mexico City demonstrate lowest sensitivity due to energy payback calculations.
Supply Chain Analysis
Contract manufacturing concentration sits with Mabe's Monterrey complex and LG's Brazilian assembly platforms, supplemented by Whirlpool's captive facilities in Mexico. Geographic supply concentration centers on Brazil, Mexico, and China for compressor components and electronic controls. Raw material dependencies draw from Chilean copper, Brazilian steel, and imported refrigerant gases. Single-source vulnerability in inverter controller chips creates exposure to semiconductor allocation constraints. Distribution runs through vertically integrated retail chains with in-house financing origination, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among retail chains with captive credit origination, fragmenting independent distributor influence across secondary Latin American cities.
For Market Incumbents: Pre-empt channel disintermediation by deepening captive financing penetration in Colombian and Chilean metro corridors before retail chains consolidate further. Compressor technology substitution from fixed-frequency to inverter platforms threatens legacy SKU viability; accelerate backward integration into controller electronics to secure semiconductor allocation priority.
For New Entrants and Emerging Players: Pursue Bogotá and Medellín inverter refrigerator segments where sub-40% penetration lags São Paulo's 65% adoption curve. Target peri-urban Brazilian washing machine corridors as municipal water infrastructure extends. Deploy direct online marketplace partnerships with logistics enablers to bypass entrenched retail chain gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional manufacturing specialists with Mercosur tariff-advantaged assembly and INMETRO certification infrastructure. Long-term viability hinges on refrigerant transition execution and technician training scale. Monitor CONUEE-INMETRO regulatory harmonization progress as inflection signal for cross-border sourcing consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive inverter technology production secures supply priority for Brazilian Class A certification compliance. |
| Certification-Driven SKU Consolidation | INMETRO and CONUEE mandates force elimination of sub-efficient models, streamlining portfolio complexity. |
| Retail Chain Financing Integration | In-house credit origination concentrates volume with vertically integrated distributors, displacing bank intermediaries. |
| Online Marketplace Platform Partnership | Digital payment infrastructure and logistics partnerships capture incremental share in Chile's Santiago corridor. |
| Technician Certification Scale-Up | IRAM and INMETRO refrigerant handling licenses reduce service bottlenecks for hydrocarbon-based R-290 systems. |
Research Methodology
Operator-level perspectives from appliance manufacturing plant managers, retail chain category buyers, compressor procurement leads, and INMETRO certification engineers anchored the qualitative base. Secondary validation drew from customs trade databases, SEC 10-K filings of listed appliance manufacturers, CONUEE energy standard disclosures, and Nielsen retail audit data. Bottom-up shipment triangulation across Brazilian and Mexican metro corridors converged with top-down macroeconomic elasticity modeling.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, sales channel integration depth, end-user concentration, and regional regulatory cluster. CAGRs derived from historical replacement cycle compression rates and efficiency mandate phase-in schedules. Industry-specific forecast inputs incorporated electricity tariff elasticity and piped water infrastructure expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real and Mexican peso exchange rates, regional interest rate trajectories, and commodity price volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and certification processing timelines. Quarterly review of INMETRO certification backlogs, retail chain credit origination volumes, and compressor import duty adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
India Laundry Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
China Laundry Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Japan Home Appliances Market
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
Australia Washing Machine Market