
 Smart Home Hardware Market | 2026-2036
Smart Home Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Hardware Market Intelligence
Silicon carbide power semiconductors are displacing traditional silicon MOSFETs and is rebalancing energy efficiency economics across smart thermostat and lighting control architectures. Amazon.com Inc. leverages its Alexa voice ecosystem to anchor consumer lock-in across speaker and display categories. Samsung Electronics Co Ltd sustains integrated hardware-software pipelines through its SmartThings platform and appliance cross-selling. Google LLC competes on AI inference density, embedding Tensor chips directly into Nest hardware to reduce cloud dependency.
Smart home hardware encompasses connected physical devices deployed in residential environments, incorporating microcontrollers with sub-1 GHz and 2.4 GHz radio transceivers, edge AI accelerators, and solid-state relays for load switching, designed to automate environmental control, security monitoring, and media distribution. Wi-Fi and Zigbee connectivity modules command the largest installed base due to router ubiquity and mesh reliability, while Z-Wave retains premium positioning in professionally monitored security installations where sub-GHz penetration through building materials matters. Security cameras and smart lights capture disproportionate margin pools as homeowners prioritize visible deterrence and circadian lighting programs.
The FCC governs radio frequency emissions and spectrum allocation for unlicensed IoT bands in the United States, while the EU AI Act imposes risk-classification obligations on biometric-enabled security cameras sold in Europe. BIS certification requirements in India create compliance friction for imported smart switches and sensors, favoring local assembly partnerships. Stakeholders must monitor whether Matter certification mandates harden into retailer gatekeeping requirements that exclude non-compliant legacy devices from shelf access.
Market Dynamics
Matter protocol certification is hardening into a de facto gatekeeping mechanism across retail channels, forcing legacy device manufacturers into costly compliance sprints or wholesale platform abandonment.
Growth Catalysts
- FCC spectrum allocation:Expanded unlicensed access in the 6 GHz band enables Wi-Fi 6E mesh deployments that reduce latency for security camera streaming and whole-home audio synchronization.
- Silicon carbide semiconductors:These wide-bandgap materials slash switching losses in smart thermostat relay circuits, extending device lifespan and reducing thermal management costs for manufacturers.
- German building codes:Mandatory smart meter gateways in new residential construction create captive demand for interoperable home energy management hardware.
Market Restraints
- Memory chip supply concentration:DDR4 and NAND flash sourcing remains concentrated among Korean and Taiwanese foundries, exposing smart speaker and display manufacturers to allocation volatility.
- BIS certification friction:India's Bureau of Indian Standards mandates local testing for RF-emitting devices, extending time-to-market by 4-6 months for imported sensors and switches.
- Sub-GHz interference:Z-Wave's 800-900 MHz bands face encroachment from cellular IoT and utility AMI networks, degrading reliability in professionally monitored security installations.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing attract contract assembly of smart switches and sensors, bypassing BIS import barriers through local value-added operations.
- Age-in-place healthcare:Fall detection and medication adherence sensors represent an underpenetrated application category as aging populations in Japan and Italy resist institutional care transitions.
- EU AI Act biometric restrictions:Risk-classification obligations on facial recognition cameras create first-mover advantage for privacy-preserving radar-based presence detection technologies.
Industry Challenges
- Matter certification backlog:Testing lab capacity constraints delay product launches by 8-12 weeks, compressing holiday season revenue windows for hardware vendors.
- Embedded systems talent scarcity:Firmware engineering for ultra-low-power microcontrollers remains concentrated among semiconductor vendors, forcing OEMs into costly licensing arrangements or poaching wars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Hardware Market |
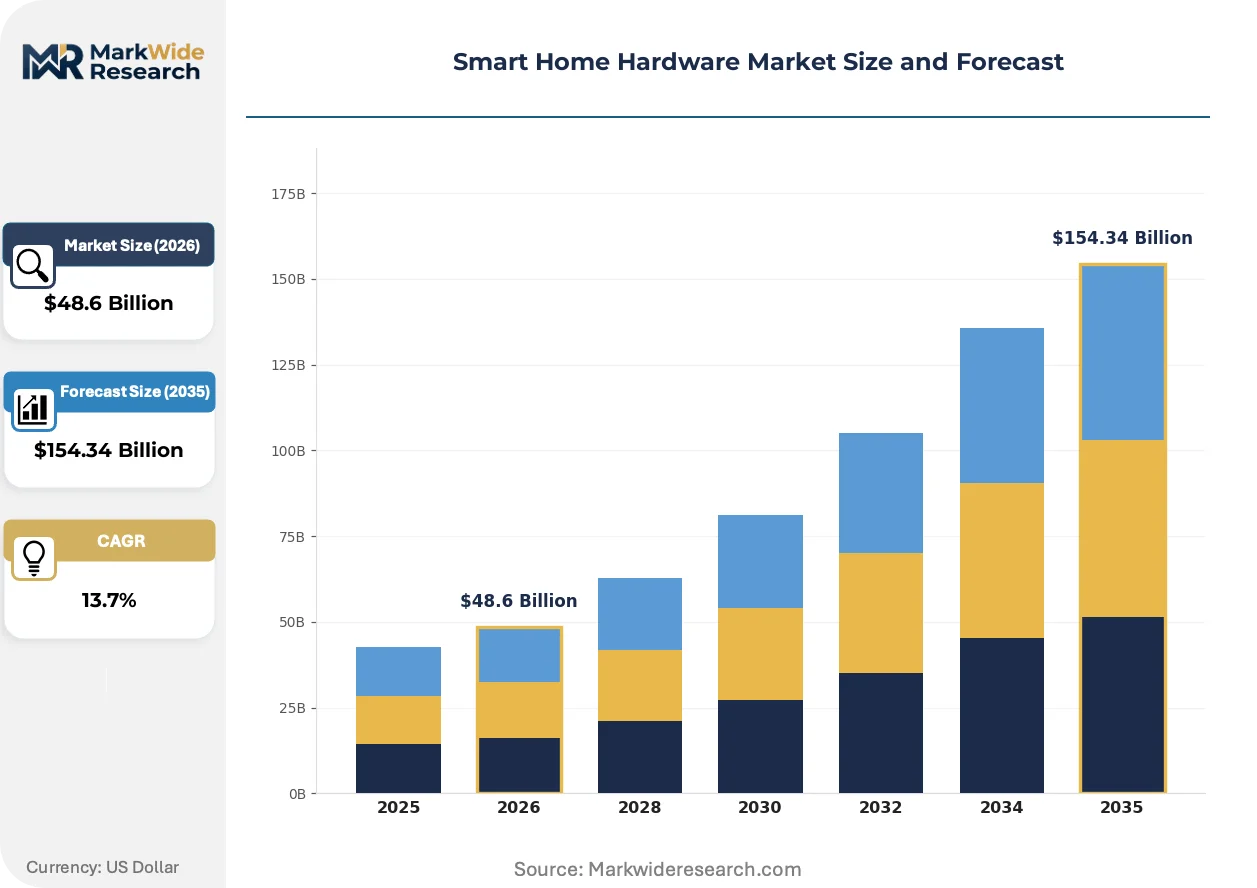
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $154.34 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Smart Thermostats, Security Cameras, Smart Lights Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth Application: Home Automation, Energy Management, Security, Entertainment End User: Homeowners, Renters, Developers, Facility Managers |
| Companies Covered | Google LLC, Amazon.com Inc., Honeywell International Inc., Schneider Electric SE, Johnson Controls International plc, Samsung Electronics Co Ltd, ABB Ltd., Apple Inc., Legrand SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Hardware Market Strategic Shifts & Innovations
Edge inference architectures are compressing cloud dependency while protocol convergence and procurement centralization reshape how hardware reaches residential endpoints.
Silicon carbide MOSFETs is overtaking traditional silicon power devices in smart lighting and climate control hardware. High-end thermostat manufacturers have adopted SiC-based solid-state relays for silent, rapid load switching. This transition is overtaking incumbent suppliers who lack wide-bandgap packaging expertise, consolidating procurement leverage among vertically integrated semiconductor houses.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on biometric-enabled security cameras sold in Europe. Hardware vendors must maintain technical documentation and human oversight protocols for facial recognition features. German and French retailers are already delisting non-compliant legacy inventory ahead of enforcement deadlines.
Property developers in the United States and China are consolidating smart home specification decisions at the portfolio level rather than project level. Lennar and Country Garden now mandate Matter-certified device ecosystems across thousands of annual unit completions. This centralization is squeezing smaller OEMs who lack certification resources or direct developer relationships.
Smart Home Hardware Market Segmentation
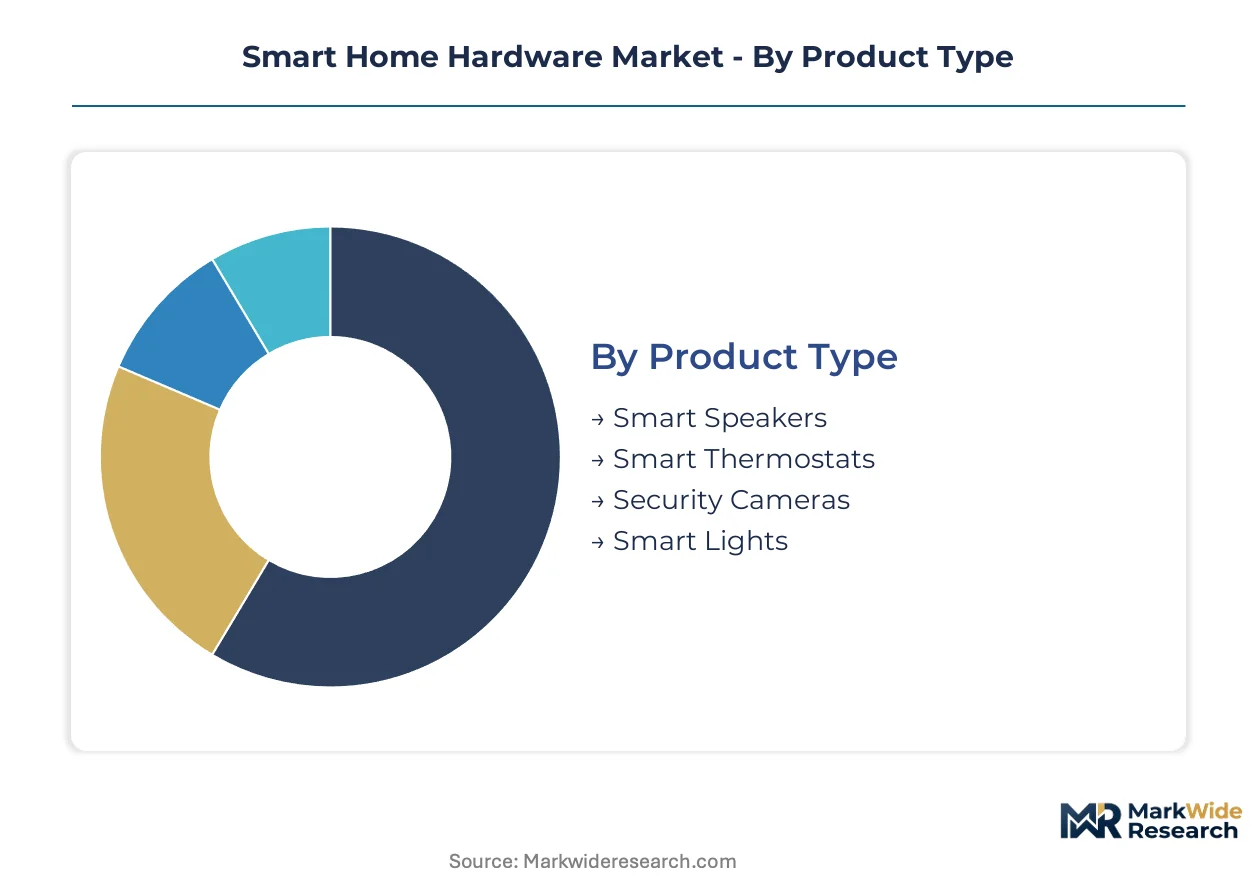
Smart home hardware segmentation reveals how technical specifications, connectivity protocols, and buyer economics fragment procurement patterns across residential deployments. Understanding these axes exposes where margin pools concentrate and which specification tiers command pricing power.
Product Type:
Device category determines semiconductor content, power architecture, and replacement cadence across residential installations.
- Smart Speakers:These voice-activated devices integrate far-field microphone arrays with edge AI accelerators for local wake-word processing. Demand concentrates among homeowners in the United States seeking Alexa and Google Assistant ecosystem lock-in, constrained by memory chip allocation volatility from Korean foundries.
- Security Cameras:Biometric-enabled units with on-device inference engines process facial recognition without cloud round-trips. German and French retailers are delisting non-compliant legacy inventory ahead of EU AI Act enforcement deadlines for biometric risk classification.
- Smart Thermostats:Climate control hardware incorporating silicon carbide solid-state relays for silent load switching.
- Smart Lights:Circadian-tunable LED drivers with Zigbee or Thread mesh networking for whole-home synchronization.
Mature deployment sits with Smart Thermostats. Newer deployment is concentrated in Security Cameras.
Technology:
Radio frequency selection shapes penetration through building materials, mesh reliability, and certification complexity for device manufacturers.
- Wi-Fi:2.4 GHz and 5 GHz bands dominate due to router ubiquity in existing homes, with 6 GHz Wi-Fi 6E expanding for latency-sensitive video streaming. United States FCC spectrum allocation in the 6 GHz band enables whole-home audio synchronization previously constrained by congestion.
- Zigbee:2.4 GHz mesh protocol with self-healing network topology and sub-100ms latency for lighting control. Chinese property developers at Country Garden mandate Matter-certified Zigbee ecosystems across thousands of annual unit completions.
- Z-Wave:Sub-GHz protocol optimized for penetration through walls in professionally monitored security installations.
- Bluetooth:Low-energy variant for direct phone-to-device commissioning and temporary guest access scenarios.
Volume leadership belongs to Wi-Fi. Steepest expansion trajectory is climbing with Zigbee as Matter protocol convergence accelerates.
Application:
Use-case focus determines sensor fusion requirements, cloud dependency, and integration depth with utility or entertainment systems.
- Home Automation:Cross-device orchestration platforms coordinating lighting, climate, and security through centralized hubs. United States property developers at Lennar now specify portfolio-level Matter-certified ecosystems rather than project-by-project procurement.
- Energy Management:Smart meter gateway integration and load-shifting hardware responding to utility pricing signals. German building codes mandate gateway compatibility in new residential construction, creating captive demand for interoperable controllers.
- Security:Professionally monitored intrusion detection with cellular backup and emergency service dispatch integration.
- Entertainment:Multi-room audio distribution and display synchronization with streaming service integration.
Revenue concentration rests with Home Automation. Fastest share gain is occurring in Energy Management.
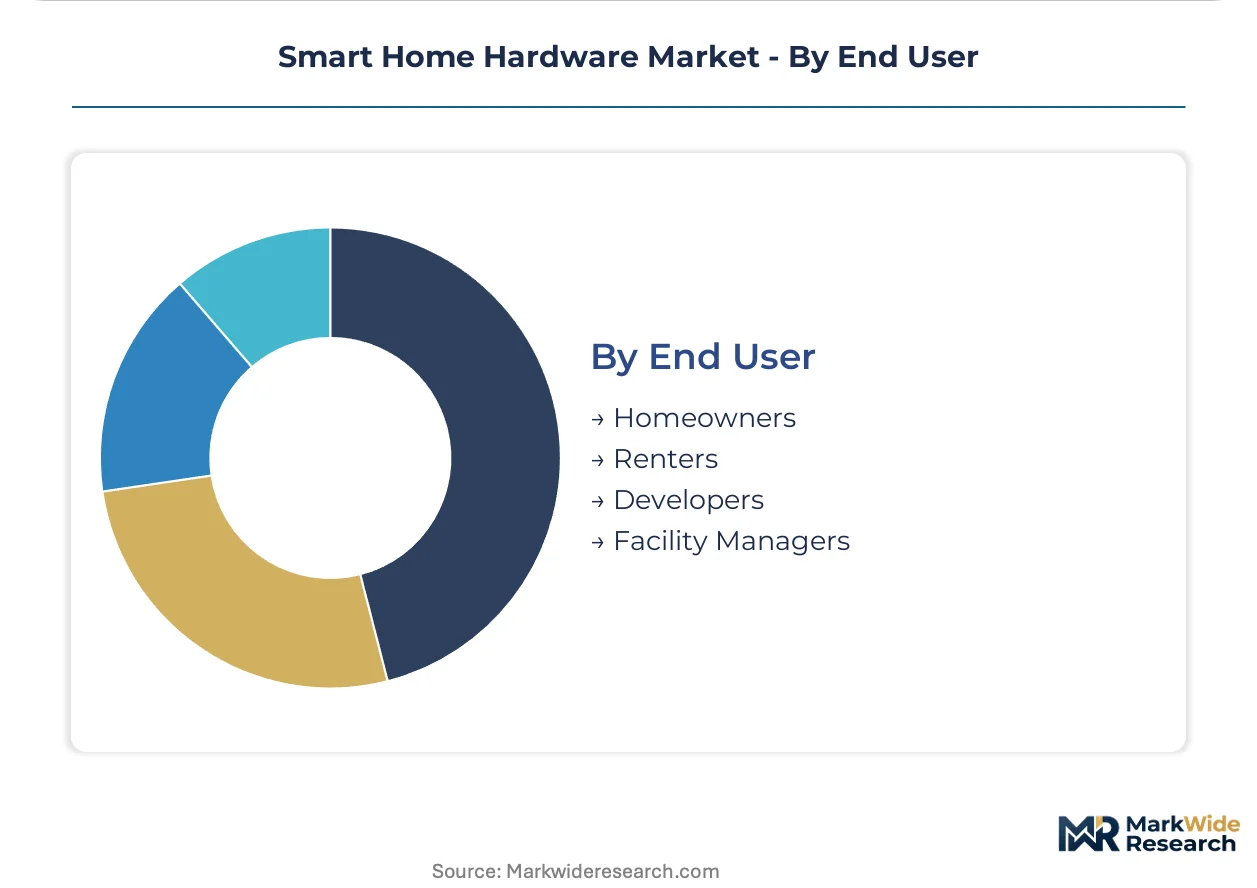
End User:
Buyer type dictates specification authority, installation channel, and price sensitivity across residential deployment modes.
- Homeowners:Primary decision-makers for retrofit installations, prioritizing visible deterrence through security cameras and circadian lighting programs. United States homeowners drive disproportionate margin capture in premium camera and lighting categories.
- Developers:Portfolio-level specification authority consolidating across thousands of annual unit completions in China and the United States. Centralized procurement squeezes smaller OEMs lacking direct developer relationships or certification resources.
- Renters:Portable, non-permanent devices favoring battery power and adhesive mounting without electrical work.
- Facility Managers:Multi-tenant building oversight requiring centralized dashboard access and maintenance scheduling tools.
Purchase volume aggregates with Developers. Margin expansion is strongest among Homeowners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, China, and Germany as primary adoption centers for smart home hardware, with each market shaped by distinct regulatory frameworks and infrastructure maturity.
United States
FCC spectrum allocation in the 6 GHz band enables Wi-Fi 6E mesh deployments for latency-sensitive security streaming. Property developers at Lennar mandate Matter-certified ecosystems across portfolio-level procurement decisions. Silicon Valley and Austin clusters anchor voice-activated speaker manufacturing and edge AI accelerator design.
China
Country Garden and other developers specify centralized smart home specifications across thousands of annual unit completions. MIIT oversees radio frequency certification for Zigbee and Thread protocol devices under national GB standards. Shenzhen and Hangzhou manufacturing corridors concentrate microcontroller and connectivity module production.
Germany
Mandatory smart meter gateways in new residential construction create captive demand for interoperable energy management hardware. The EU AI Act imposes risk-classification obligations on biometric-enabled security cameras sold across Europe. Munich and Stuttgart industrial clusters specialize in silicon carbide power semiconductor packaging for thermostat applications.
India
Production-linked incentive schemes attract contract assembly of smart switches and sensors, bypassing BIS import barriers through local value-added operations. TRAI governs spectrum allocation for unlicensed IoT bands alongside BIS certification requirements for RF-emitting devices. Bangalore and Hyderabad electronics manufacturing corridors expand capacity for Matter-certified device production.
Japan
Age-in-place healthcare applications drive demand for fall detection and medication adherence sensors as aging populations resist institutional care transitions. METI promotes energy efficiency standards for connected home appliances under national JIS frameworks. Osaka and Nagoya industrial clusters focus on ultra-low-power microcontroller design for battery-operated sensor applications.
Smart Home Hardware Market Key Industry Players
Platform ecosystem consolidation dominates the current landscape as voice assistant providers and appliance manufacturers battle for consumer lock-in. The vendor base stratifies across three tiers: technology conglomerates with integrated hardware-software pipelines, electrical infrastructure specialists with B2B channel dominance, and component-focused OEMs supplying white-label devices. Two archetypes anchor competitive positioning: ecosystem orchestrators leveraging data network effects, and interoperability specialists capitalizing on Matter protocol standardization. M&A activity and vertical integration into semiconductor sourcing represent the dominant competitive moves.
Within the ecosystem orchestrator tier, Amazon.com Inc. and Google LLC anchor voice-activated consumer hardware strategies, while Samsung Electronics Co Ltd exemplifies integrated appliance-to-platform pipelines. Schneider Electric SE and ABB Ltd. occupy positions among electrical infrastructure specialists serving developer and facility management channels. These five entities represent the competitive anchors across consumer-facing and B2B deployment modes.
| Leading Market Players |
|---|
| Google LLC |
| Amazon.com Inc. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Johnson Controls International plc |
| Samsung Electronics Co Ltd |
| ABB Ltd. |
| Apple Inc. |
| Legrand SA |
| Others |
Cost & Logistics Intelligence
Silicon carbide wafer costs cascade through thermostat and lighting hardware tiers, with wide-bandgap semiconductor premiums concentrating in German-engineered climate control units while standard silicon devices populate mass-market Zigbee sensor deployments.
Pricing Analysis
Volume leadership in Wi-Fi modules compresses per-unit margins to commodity levels, while Matter-certified Zigbee ecosystems command three-tier pricing structure across premium, standard, and economy levels based on certification grade and developer channel access. Price differentiation rests on interoperability compliance and thermal management specifications, with silicon carbide-based solid-state relays sustaining premium positioning. Pricing pressure stems from memory chip allocation volatility at Korean foundries, squeezing smart speaker manufacturers most acutely. Homeowners in the United States show least price sensitivity for visible security cameras, whereas renters prioritize sub-$50 battery-powered entry points.
Supply Chain Analysis
Workforce availability for ultra-low-power microcontroller firmware engineering concentrates in Shenzhen and Bangalore corridors, tethering OEMs to semiconductor vendor licensing arrangements or costly talent poaching. Raw material flows draw from Taiwanese DDR4 foundries, Chinese LED driver assembly, and German silicon carbide packaging operations. Single-source vulnerability sits with Zigbee chipset suppliers facing Matter certification backlog delays. Distribution runs through property developer procurement offices in the United States and China, bypassing traditional retail for new construction volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where testing lab capacity for Matter certification props pricing power for compliant device vendors.
For Market Incumbents: Acquire embedded systems engineering talent pools to reduce dependency on semiconductor vendor firmware licensing. Secure direct procurement relationships with silicon carbide packaging houses in Munich and Stuttgart to defend thermostat margin position against emerging wide-bandgap competitors. Matter certification backlog delays threaten holiday revenue windows; captive testing capacity buffers this exposure. For New Entrants and Emerging Players: Capture age-in-place healthcare sensor white space in Japan and Italy, where fall detection and medication adherence applications remain underpenetrated. Target India's PLI scheme corridors for contract assembly partnerships that bypass BIS import friction. Go-to-market leverage rests on radar-based presence detection that satisfies EU AI Act biometric restrictions without facial recognition compliance burdens. For Investors and Strategic Acquirers: Matter protocol mandate enforcement by major retailers is the leading indicator that interoperability-compliant device vendors will consolidate procurement leverage. Long-term viability favors vertically integrated players with captive semiconductor sourcing and direct developer channel relationships. Acquisition targets include ultra-low-power microcontroller design shops and Matter certification testing facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Investment | Retailer shelf access for smart home hardware increasingly requires compliance verification. |
| Silicon Carbide Supply Agreement | German automotive packaging expertise transfers to thermostat relay applications. |
| Property Developer Partnership | Portfolio-level procurement at Lennar and Country Garden locks in volume commitments. |
| Edge AI Accelerator Acquisition | Local inference capability reduces Nest and Alexa cloud dependency costs. |
| India PLI Scheme Localization | Bangalore assembly bypasses TRAI and BIS import barriers for RF-emitting devices. |
Research Approach
Multi-period observation of Matter certification queue lengths, silicon carbide adoption rates in climate control hardware, and property developer procurement centralization anchored the trend analysis, supplemented by interviews with smart home platform engineering directors, semiconductor vendor product managers, property developer specification leads, and retail category buyers. Secondary validation drew from FCC spectrum allocation filings, EU AI Act implementation guidance, SEC 10-K disclosures by ecosystem orchestrators, and MIIT GB standard certification databases. Bottom-up device shipment modeling triangulated against top-down construction completion data.
Input-output matrix framing structured volume projections across product type, connectivity protocol, application use-case, and buyer archetype dimensions, with CAGRs derived from segment-level adoption curves and replacement cadence assumptions. Semiconductor content per unit, certification lag times, and developer specification capture rates fed industry-specific forecast inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Matter protocol enforcement timing, memory chip foundry allocation volatility, and EU AI Act biometric restriction expansion. Assumptions reflect current regulatory trajectories and supply chain configurations. Material deviation in FCC spectrum reallocation, BIS certification requirement relaxation, or retailer delisting enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Mexico Kitchen Appliances Products Market
Consumer Goods
Lip Care Market
Consumer Goods
Hand Gloves Market
Consumer Goods
Smart Speaker Market
Consumer Goods
Home Fragrance Diffusers Market
Consumer Goods
Dog Bed Covers Market
Consumer Goods
Refrigerator Door Seal Market
Consumer Goods
Global Residential Water Heaters Market
Consumer Goods
Cosmetic Pencil and Pen Market
Consumer Goods
Asia-Pacific Pet Food Market
Consumer Goods
Leather Footwear Market
Consumer Goods
North America Washing Machine Market
Consumer Goods
Beauty Oils Market
Consumer Goods
Electric Corkscrew Market
Consumer Goods
China Pet Clothing Market
Consumer Goods
Canada Laundry Appliances Market