
 Canada Smart Home Market | 2026-2036
Canada Smart Home Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Smart Home Market Insights
Modular smart home packaging is rebalancing buyer choice across the Canadian market. Samsung Electronics leverages its appliance-to-mobile ecosystem to anchor whole-home integration strategies. Ecobee specializes in climate control hardware that competes aggressively through utility partnership channels. Amazon.com extends its Alexa-enabled device portfolio to dominate voice-first home automation adoption.
Canada smart home systems comprise networked sensors, actuators, and control interfaces that communicate through Wi-Fi, Zigbee, Z-Wave, or Bluetooth protocols to automate lighting, climate, security, and entertainment functions. These installations typically integrate with cloud platforms and mobile applications to enable remote monitoring, predictive energy optimization, and interoperable device management across residential and commercial environments. Smart Security Systems command substantial investment as property crime concerns and insurance premium incentives push homeowners toward monitored entry and surveillance solutions. Smart Thermostats represent the fastest-expanding product category because provincial utility rebate programs in Ontario and British Columbia directly subsidize installation costs. Energy Management applications concentrate margin pools by generating recurring software subscription revenue alongside hardware sales.
Health Canada regulates electromagnetic emissions and data privacy standards for connected residential devices, while the Canadian Radio-television and Telecommunications Commission oversees telecommunications infrastructure that underpins cloud-dependent smart home services. The Office of the Privacy Commissioner of Canada enforces consent frameworks for biometric and behavioral data collection from security cameras and health monitoring sensors. Stakeholders must monitor evolving provincial energy efficiency mandates and interoperability certification requirements that will determine which technology ecosystems gain preferential access to subsidized retrofit programs.
Market Dynamics
Utility-sponsored rebate programs in Ontario and British Columbia are compressing smart thermostat adoption cycles and forcing hardware vendors to restructure channel economics around certified installer networks rather than retail distribution.
Growth Catalysts
- Provincial Energy Efficiency Mandates:Ontario's Green Energy Act and British Columbia's CleanBC program mandate performance standards that directly subsidize smart home retrofits, pulling demand forward from replacement cycles.
- Insurance Premium Incentives:Monitored security systems now trigger material premium reductions from major Canadian property insurers, converting passive homeowner interest into active procurement.
- Zigbee and Matter Protocol Convergence:Interoperability standards are collapsing ecosystem lock-in effects, enabling multi-vendor installations that previously faced integration friction.
Market Restraints
- Semiconductor Supply Concentration:Wi-Fi and Bluetooth module fabrication concentrates in East Asian foundries, exposing Canadian distributors to extended lead times during capacity constraints.
- Cybersecurity Compliance Burden:Health Canada and CRTC device certification timelines add six to nine months to product launch schedules, compressing effective revenue windows before technology obsolescence.
- Copper and Lithium Price Volatility:Battery-dependent sensors and wired infrastructure face input cost instability that hardware vendors struggle to pass through in price-sensitive residential segments.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick lack equivalent utility rebate density, creating whitespace for provincial government partnership programs that Ontario and BC vendors have already proven.
- Aging-in-Place Health Monitoring:Fall detection and medication adherence sensors represent an emerging application category where Health Canada regulatory clarity is still forming, offering first-mover positioning.
- Multi-Unit Developer Pre-Installation:Toronto and Vancouver condominium developers are bundling smart infrastructure into base specifications, creating captive supply relationships that bypass traditional retail channels entirely.
Industry Challenges
- Certified Installer Network Scarcity:CRTC-mandated telecommunications licensing requirements for integrated security systems limit the pool of qualified technicians, constraining deployment velocity in suburban markets.
- Legacy HVAC Integration Complexity:Hydronic heating systems prevalent in older Quebec and Ontario housing stock require specialized gateway hardware that adds cost and failure points to thermostat upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Smart Home Market |
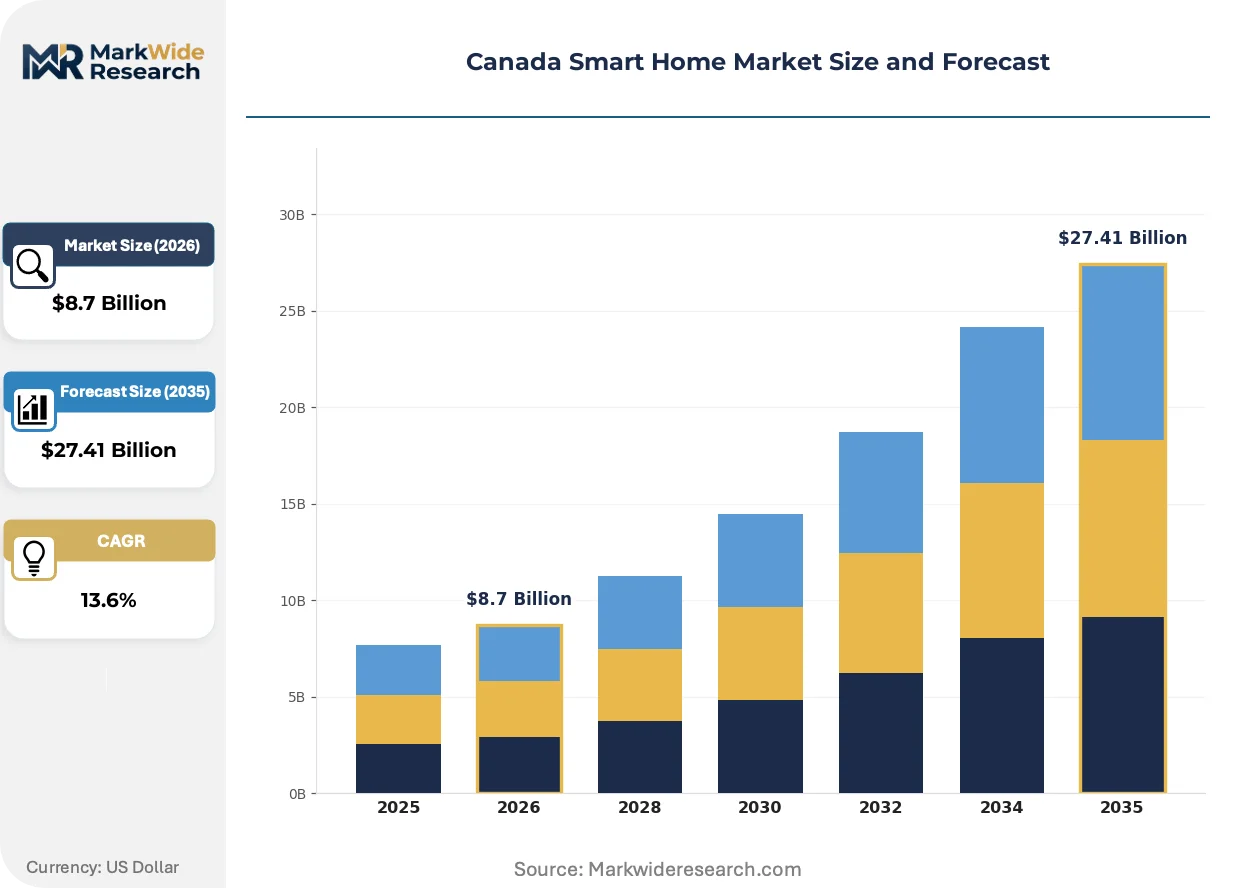
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Thermostats, Smart Security Systems, Smart Appliances Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential, Commercial, Hospitality, Retail Application: Energy Management, Home Security, Entertainment Control, Health Monitoring |
| Companies Covered | Samsung Electronics, LG Electronics, Google, Amazon.com, Apple, Honeywell International, Schneider Electric, TELUS, Ecobee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Smart Home Market Trends and Innovations
Matter protocol adoption is dissolving ecosystem boundaries that previously segmented competitive positioning, while regulatory pressure on data residency is forcing cloud architecture redesigns.
Thread mesh networking is expanding into whole-home device backbones by enabling battery-operated sensors to relay signals through mains-powered routers. Multi-unit residential developers in Vancouver are specifying Thread-native infrastructure during pre-drywall phases to avoid retrofit costs. This topology is expanding into segments previously served by proprietary Zigbee implementations, compressing margin pools for hub-centric vendors.
Health Canada tightened electromagnetic emissions testing requirements for connected devices under its Radio Standards Specification framework, extending certification timelines by four to six months. Hardware manufacturers are responding by front-loading regulatory submission work into product development cycles rather than treating certification as a final gate. Smart security cameras with biometric capabilities face the most pronounced compliance burden under this regime.
Homeowners are consolidating vendor relationships around single-ecosystem purchases rather than assembling best-of-breed device collections. Retail channels report basket composition shifting toward three-device starter kits over individual sensor sales, compressing unit economics for standalone product specialists. Quebec and Ontario markets exhibit this concentration most visibly, where French-language voice assistant support has become a non-negotiable filter.
Canada Smart Home Market Segmentation
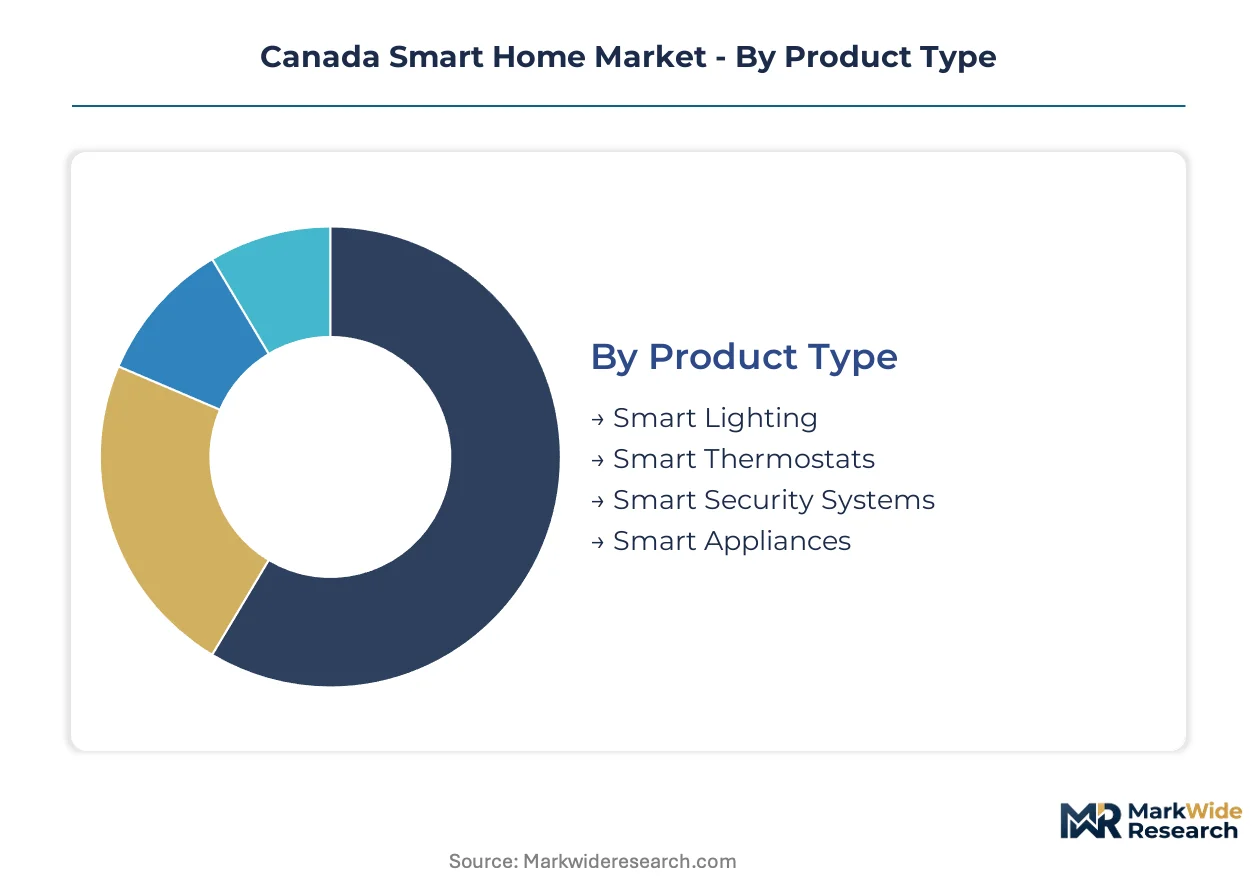
Smart home segmentation in Canada reflects distinct procurement patterns across utility-subsidized retrofits, new construction bundles, and insurance-linked security upgrades. Buyers prioritize either energy cost reduction or property protection, creating divergent technology requirements and channel economics.
Product Type:
Cost tier differentiation separates mass-market retrofit purchasers from premium new-construction buyers seeking integrated whole-home systems.
- Smart Thermostats:Climate control hardware with occupancy sensing and utility API integration dominates Ontario and British Columbia retrofit activity. Provincial rebate programs in these provinces compress payback periods to under two years, accelerating replacement cycles in older housing stock.
- Smart Security Systems:Monitored entry sensors, surveillance cameras, and professional dispatch services concentrate demand in Toronto and Vancouver metropolitan areas. Insurance premium reductions of 10-20% from major Canadian property insurers convert passive interest into active procurement for detached homeowners.
- Smart Lighting:Connected LED fixtures and automated dimming systems appeal to design-conscious buyers in new construction segments.
- Smart Appliances:Refrigerators, dishwashers, and laundry equipment with remote monitoring capabilities anchor premium kitchen renovation projects.
Smart thermostats lead volumes today; smart security systems are gaining share fastest.
Technology:
Application environment dictates protocol selection, with whole-home coverage requirements favoring mesh topologies over point-to-point solutions.
- Zigbee:Low-power mesh networking standard enables battery-operated sensors to relay signals through mains-powered routers across large residential footprints. Multi-unit developers in Vancouver specify Zigbee-native infrastructure during pre-drywall phases to eliminate retrofit costs.
- Wi-Fi:Ubiquitous protocol for cloud-connected cameras and voice assistants leverages existing residential broadband infrastructure. Bandwidth-intensive video streaming applications in suburban Ontario markets drive preference for Wi-Fi 6-enabled device portfolios.
- Z-Wave:Sub-GHz frequency mesh protocol optimized for reliable penetration through walls in older Quebec housing stock with hydronic heating systems.
- Bluetooth:Short-range protocol dominates portable device pairing and initial setup workflows for consumer-configured installations.
Wi-Fi retains the largest installed base; Zigbee is climbing the fastest as Matter protocol convergence accelerates multi-vendor compatibility.
End User:
Customer type determines procurement channel, with institutional buyers favoring pre-installation contracts and individual consumers selecting retail or certified installer pathways.
- Residential:Single-family homeowners and condominium purchasers constitute the core demand pool, concentrated in Ontario and British Columbia utility rebate territories. Aging-in-place applications in Quebec drive emerging demand for health monitoring sensor networks.
- Commercial:Office building operators and property management firms deploy access control and energy optimization systems at portfolio scale.
- Hospitality:Hotel chains implement guest room automation for operational efficiency and brand differentiation.
- Retail:Store operators utilize smart lighting and climate control to reduce operating expenditures across multi-location footprints.
Residential commands absolute volume; commercial is expanding most quickly as building automation converges with residential technology platforms.
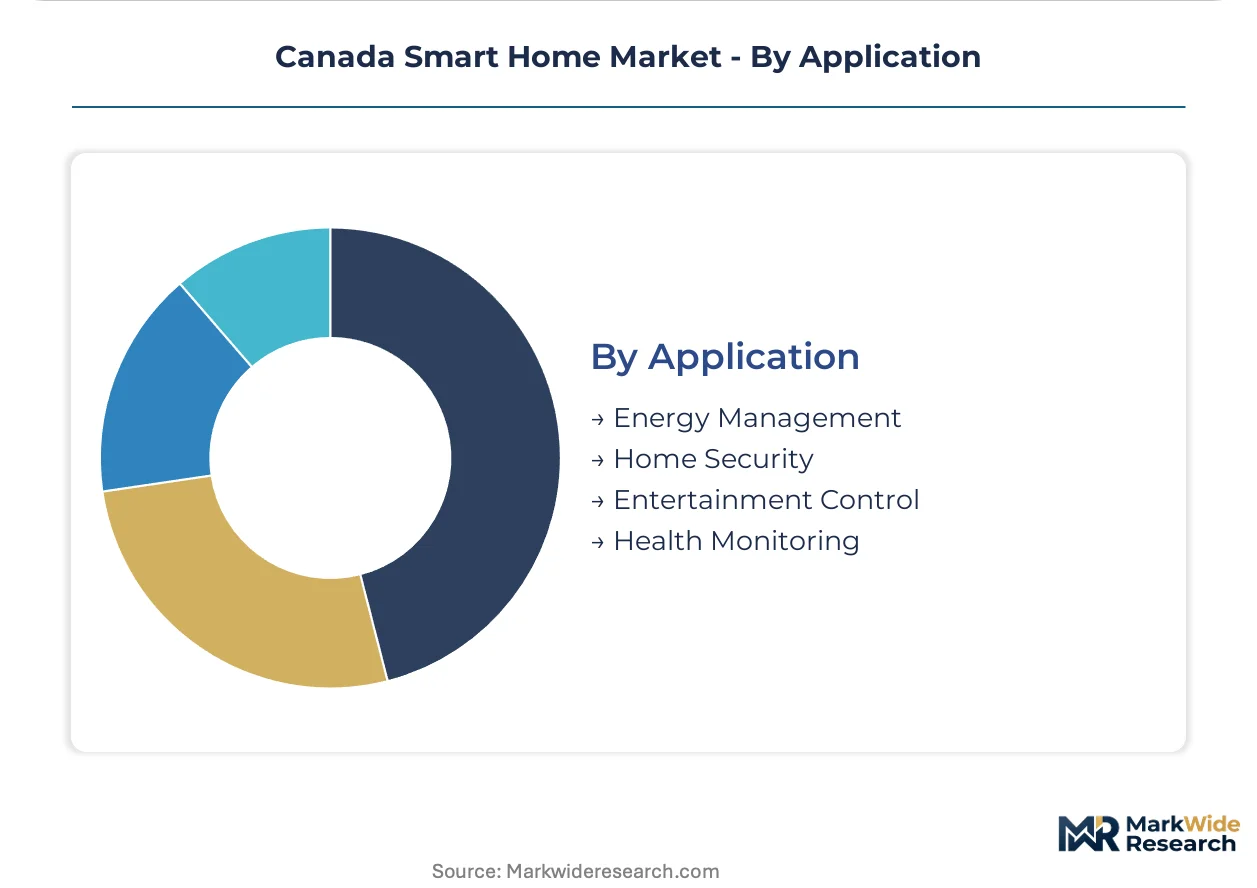
Application:
Margin structure varies sharply by application, with hardware-only deployments capturing less value than subscription-linked service models.
- Energy Management:Utility-integrated load balancing and predictive optimization software generates recurring subscription revenue alongside thermostat hardware sales. Ontario's Green Energy Act and British Columbia's CleanBC program directly subsidize these installations, pulling demand forward from natural replacement cycles.
- Home Security:Professional monitoring services with police dispatch integration command premium monthly fees. Insurance premium incentives from Canadian property insurers accelerate adoption in high-property-crime postal codes.
- Entertainment Control:Whole-home audio and unified remote systems appeal to luxury renovation segments.
- Health Monitoring:Fall detection and medication adherence sensors represent an emerging category where Health Canada regulatory clarity is still forming.
Energy management leads current deployment value; health monitoring shows the steepest expansion trajectory as demographic aging intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart home technology in Canada first achieved commercial scale through Ontario utility partnerships in the early 2010s, establishing a regulatory and subsidy template that other provinces later adapted. The market now exhibits sharp geographic concentration tied to provincial energy policy divergence and metropolitan construction cycles.
Ontario
The Green Energy Act and subsequent provincial efficiency programs created the deepest retrofit subsidy environment in Canada. Toronto's condominium development pipeline generates captive pre-installation demand for whole-building automation systems. The Independent Electricity System Operator administers rebate verification processes that hardware vendors must navigate to access subsidized customer segments.
British Columbia
CleanBC program mandates accelerate smart thermostat penetration in single-family housing stock across the Lower Mainland. Vancouver multi-unit developers specify native Thread infrastructure during pre-drywall phases to eliminate retrofit costs. BC Hydro's tiered rebate structure rewards higher-efficiency device selections with steeper subsidies.
Quebec
Hydronic heating prevalence in older Montreal and Quebec City housing stock creates integration complexity for thermostat vendors. French-language voice assistant requirements filter product availability more aggressively than elsewhere in Canada. Hydro-Québec's residential demand response pilots signal emerging utility engagement comparable to Ontario and BC programs.
Alberta
Deregulated retail electricity markets produce fragmented utility sponsorship compared to centralized provincial programs elsewhere. Calgary and Edmonton new construction markets emphasize security system bundling over energy management due to lower natural gas heating costs. The Alberta Utilities Commission maintains lighter touch device certification requirements than Health Canada's federal framework.
Atlantic Canada
Nova Scotia and New Brunswick lack equivalent rebate density, creating whitespace for provincial government partnership programs that Ontario and BC vendors have already proven. Efficiency Nova Scotia operates the region's most developed retrofit incentive structure. Saint John and Halifax metropolitan areas show emerging developer interest in pre-installed smart infrastructure for differentiated condominium offerings.
Canada Smart Home Market Competitive Landscape
Premium-margin players sit above commodity-margin players across ecosystem integration depth, with whole-home platform vendors capturing recurring software revenue while hardware specialists compete on utility channel access. The vendor base separates into three strategic archetypes: diversified electronics conglomerates with appliance-to-mobile ecosystems, climate control specialists leveraging utility partnership channels, and voice-first platform operators extending device portfolios. Consolidation pressure operates through certified installer network acquisitions and Matter protocol certification races.
Within the diversified electronics tier, Samsung Electronics and LG Electronics occupy positions anchored by appliance manufacturing scale and mobile ecosystem integration. Among platform-native operators, Amazon.com exemplifies voice-first home automation adoption strategies. Ecobee represents the climate specialist archetype competing through provincial utility rebate channel penetration rather than retail distribution dominance.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Amazon.com |
| Apple |
| Honeywell International |
| Schneider Electric |
| TELUS |
| Ecobee |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up certified installer networks in Ontario and British Columbia are consolidating channel control and compressing margin pools for hardware vendors who lack direct utility rebate program access. This ownership concentration simultaneously tightens pricing discipline at the retail tier and redirects supply flow toward pre-approved contractor ecosystems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Canadian market by integration complexity and certification status. Price differentiation hinges on Health Canada Radio Standards Specification compliance tier and utility rebate program eligibility, with certified devices commanding substantial premiums over uncertified alternatives. Pricing pressure stems from semiconductor module cost volatility in East Asian foundries, compressing margins for economy-tier sensor manufacturers. Residential retrofit buyers in Atlantic Canada exhibit the highest price sensitivity, while Toronto and Vancouver multi-unit developers demonstrate minimal elasticity due to pre-installation bundling economics.
Supply Chain Analysis
Health Canada and CRTC certification gating extends product launch timelines by six to nine months, forcing hardware vendors to front-load regulatory submission work into development cycles. Wi-Fi and Bluetooth module fabrication concentrates in Taiwan, South Korea, and China, exposing Canadian distributors to extended lead times during foundry capacity constraints. Battery-dependent sensors and wired infrastructure draw from copper and lithium supply chains subject to commodity price instability. Single-source vulnerability in Zigbee and Thread chipset supply creates bottleneck risk. Distribution runs through certified installer networks rather than traditional retail channels in Ontario and British Columbia rebate territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Ontario's mature utility rebate infrastructure and Atlantic Canada's underpenetrated provinces, where the absence of equivalent subsidy density creates 40-60% higher effective hardware costs for end users.
For Market Incumbents: Cement dominance in Ontario and British Columbia utility channels through exclusive rebate program partnerships that lock out competing hardware vendors. Acquire certified installer networks in Toronto and Vancouver to capture margin pools currently flowing to independent contractors. Matter protocol certification investment represents the critical defensive lever against ecosystem-agnostic entrants threatening platform lock-in. For New Entrants and Emerging Players: Provincial government partnership programs in Nova Scotia and New Brunswick offer the most penetrable whitespace, where Efficiency Nova Scotia operates the region's only developed retrofit incentive structure. Target aging-in-place health monitoring applications in Quebec, where Health Canada regulatory clarity remains unsettled and first-mover positioning is achievable. Go-to-market execution should prioritize direct-to-developer sales for Atlantic Canada condominium pre-installation specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among climate control hardware specialists lacking utility channel depth but possessing Matter-compliant product portfolios ready for rebate program expansion. Long-term viability across the projection horizon hinges on regulatory navigation capability rather than pure technology differentiation. The signal to watch is provincial energy efficiency mandate expansion into Alberta and Atlantic Canada, which would re-rate channel-constrained vendors overnight.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Eliminates ecosystem lock-in friction and unlocks multi-vendor installation contracts across Ontario and British Columbia. |
| Utility Rebate Program Partnership | Secures preferential access to subsidized customer segments administered by IESO and BC Hydro verification processes. |
| Certified Installer Network Acquisition | Captures margin pools currently flowing to independent contractors and constrains competitor channel access. |
| Atlantic Canada Provincial Lobbying | Accelerates subsidy program development in Nova Scotia and New Brunswick before incumbent footprint establishment. |
| Health Monitoring Sensor Development | Positions for first-mover advantage in Quebec aging-in-place applications pending Health Canada regulatory clarity. |
Research Methodology
Bottom-up residential and commercial procurement modeling reconciled against top-down semiconductor and module supply tracking forms the analytical core of this study. Primary interviews with smart home platform engineers, utility rebate program administrators, certified installer network operators, and multi-unit residential developers combined with secondary validation from Health Canada Radio Standards Specification filings, CRTC telecommunications licensing databases, IESO and BC Hydro rebate verification records, and provincial energy efficiency mandate documentation.
Historical trendline analysis of smart thermostat replacement cycles and security system insurance-linked adoption patterns informed the projection framework across the analysis window. Segmentation modeling incorporated product type, protocol technology, end-user category, and application function dimensions. CAGRs derived from utility rebate program expansion trajectories, multi-unit residential construction pipelines in Toronto and Vancouver, and Matter protocol adoption velocity among major ecosystem vendors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to provincial energy policy divergence, semiconductor foundry capacity allocation shifts, and Health Canada cybersecurity certification timeline extensions. Deviation in Atlantic Canada subsidy program development velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Sustainable Footwear Market
Consumer Goods
India Vegan Cosmetics Market
Consumer Goods
Sandals Market
Consumer Goods
Global Silk Pajamas Market
Consumer Goods
Italy Baby Care Products Market
Consumer Goods
Global Facial Cleanser Market
Consumer Goods
Toys and Games Market
Consumer Goods
Italy Digital Showers Market
Consumer Goods
GCC Organic and Natural Pet Food Market
Consumer Goods
Mexico Hair Care Market
Consumer Goods
US Induction Cookware Market
Consumer Goods
Aquarium Supplies Market
Consumer Goods
Kitten Milk Replacer and Formula Market
Consumer Goods
Bathrobe Market
Consumer Goods
Spain Dermocosmetics Market
Consumer Goods
Waterproof Speaker Market