
 Canada Food Enzymes Market | 2026-2036
Canada Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Enzymes Market Outlook
Clean-label enzyme specifications are collapsing the gap between conventional and premium ingredient tiers across Canadian food manufacturing. Novozymes A/S leverages its microbial platform to dominate specialty protease supply for dairy processors in Quebec. Kerry Group Plc anchors its position through backward integration into enzyme fermentation, securing captive supply for its Canadian flavor systems division. BASF SE differentiates via lipase concentrates tailored to trans-fat reduction mandates in Ontario bakery operations.
Food enzymes comprise protein-based biocatalysts, typically operating at 30–70°C and pH 4.0–8.0, that accelerate hydrolysis, oxidation, or polymerization reactions without becoming consumed in the process. These catalysts derive from microbial fermentation, plant extraction, or animal tissue processing, and serve primarily to modify texture, extend shelf life, or enhance nutritional profiles in processed foods. Proteases command the largest product-type position due to entrenched demand in Canadian cheese manufacturing and meat tenderization, while lipases generate the fastest growth trajectory as bakers reformulate for reduced saturated-fat claims. Application-level margin pools concentrate in dairy, where enzyme-assisted cheese ripening shortens production cycles and lowers whey disposal costs for processors in Ontario.
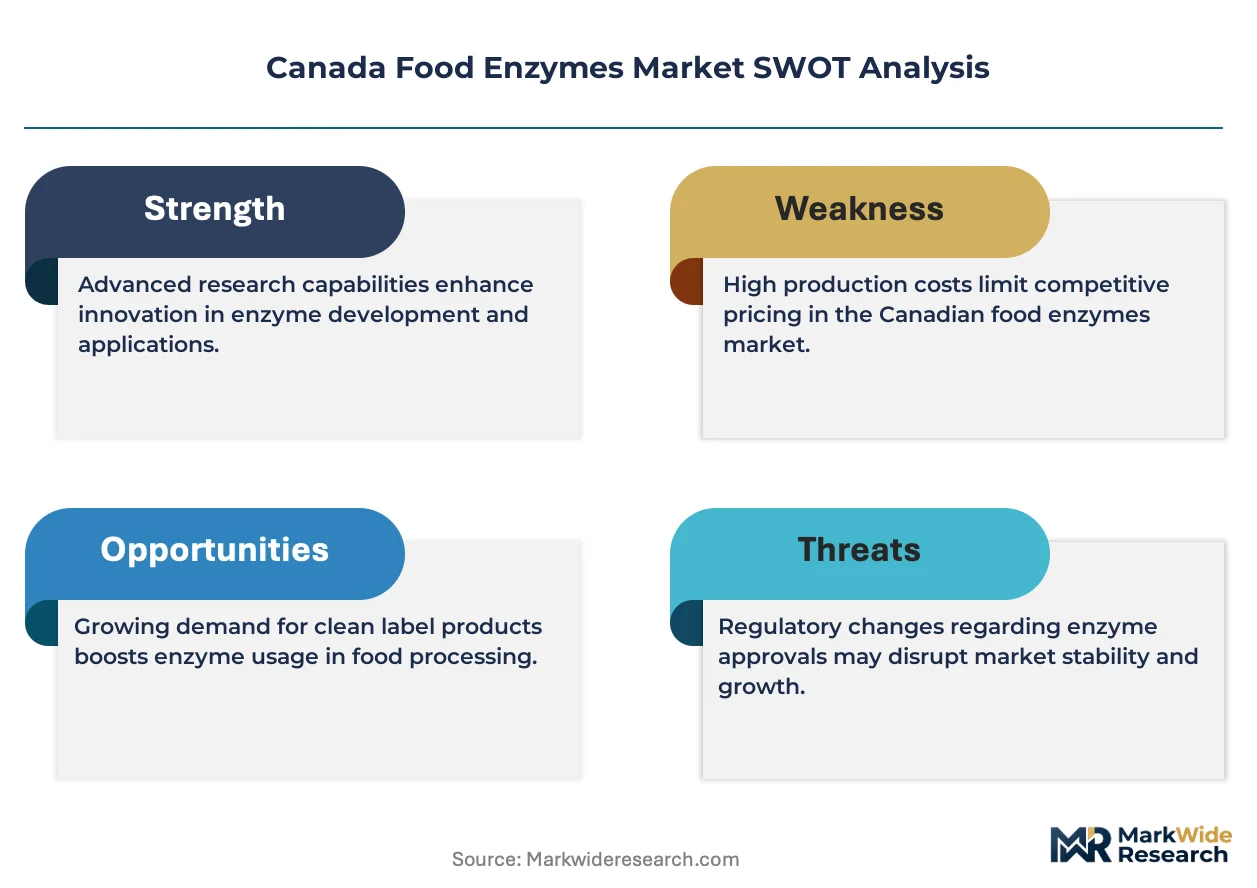
Health Canada and the Canadian Food Inspection Agency administer the Safe Food for Canadians Regulations and Novel Food approvals, which mandate pre-market safety assessments for genetically engineered enzyme strains and determine label declarations. The CFIA's commodity-specific requirements for meat processing enzymes additionally dictate maximum usage levels and residue testing protocols, creating compliance thresholds that favor suppliers with established Canadian regulatory dossiers. Stakeholders must monitor pending amendments to the Food and Drug Regulations that could expand mandatory enzyme source labeling, as this would reshape procurement criteria for food manufacturers seeking supply-chain transparency.
Market Dynamics
Health Canada's Novel Food Regulations are compressing approval timelines for genetically engineered enzyme strains, forcing suppliers to front-load regulatory dossiers while processors accelerate reformulation cycles to capture clean-label premiums.
Growth Catalysts
- Clean-label mandates:Canadian bakery manufacturers are replacing chemical conditioners with amylase and lipase systems to meet retailer ingredient-blacklist requirements. This substitution cascade is pulling volume into enzyme categories.
- CFIA residue protocols:The Canadian Food Inspection Agency's updated testing frameworks for meat-processing enzymes have validated protease efficacy, embedding these biocatalysts into standard operating procedures across Ontario abattoirs.
- Quebec dairy cluster concentration:Enzyme-assisted cheese ripening has shortened production cycles by 30-40% for processors in the Saint-Hyacinthe corridor, locking in recurring demand for specialty protease supply contracts.
Market Restraints
- Fermentation input volatility:Microbial enzyme production depends on corn-derived dextrose and soy peptone, both subject to Prairie grain-price swings that compress margin predictability for domestic manufacturers.
- Regulatory friction:Health Canada's strain-specific Novel Food assessments create 18-24 month approval lag for new genetically modified enzyme variants, freezing product pipelines relative to European EFSA timelines.
- Technical limitation:Current lipase formulations exhibit thermal instability above 55°C, constraining their deployment in high-temperature Canadian cracker and extruded snack lines.
Strategic Opportunities
- Atlantic Canada underpenetration:Nova Scotia and New Brunswick food processors remain reliant on chemical additives, presenting first-mover openings for enzyme suppliers with technical service capabilities.
- Plant-based dairy analogs:Emerging oat and pea protein beverage categories in British Columbia require lipase-modified lipid systems to replicate mouthfeel, creating enzyme demand without legacy dairy supplier lock-in.
- Provincial carbon mandates:Quebec's cap-and-trade system incentivizes enzyme adoption as process-intensity reducers, positioning biocatalysts as compliance instruments rather than mere formulation inputs.
Industry Challenges
- Fermentation scale-up talent scarcity:Canadian universities produce fewer than 50 industrial enzymologists annually, forcing manufacturers to recruit from European and American talent pools at premium compensation.
- Legacy equipment incompatibility:Ontario's aging dairy processing infrastructure requires $2-4 million per facility to retrofit for continuous enzyme dosing, slowing adoption despite proven ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Enzymes Market |
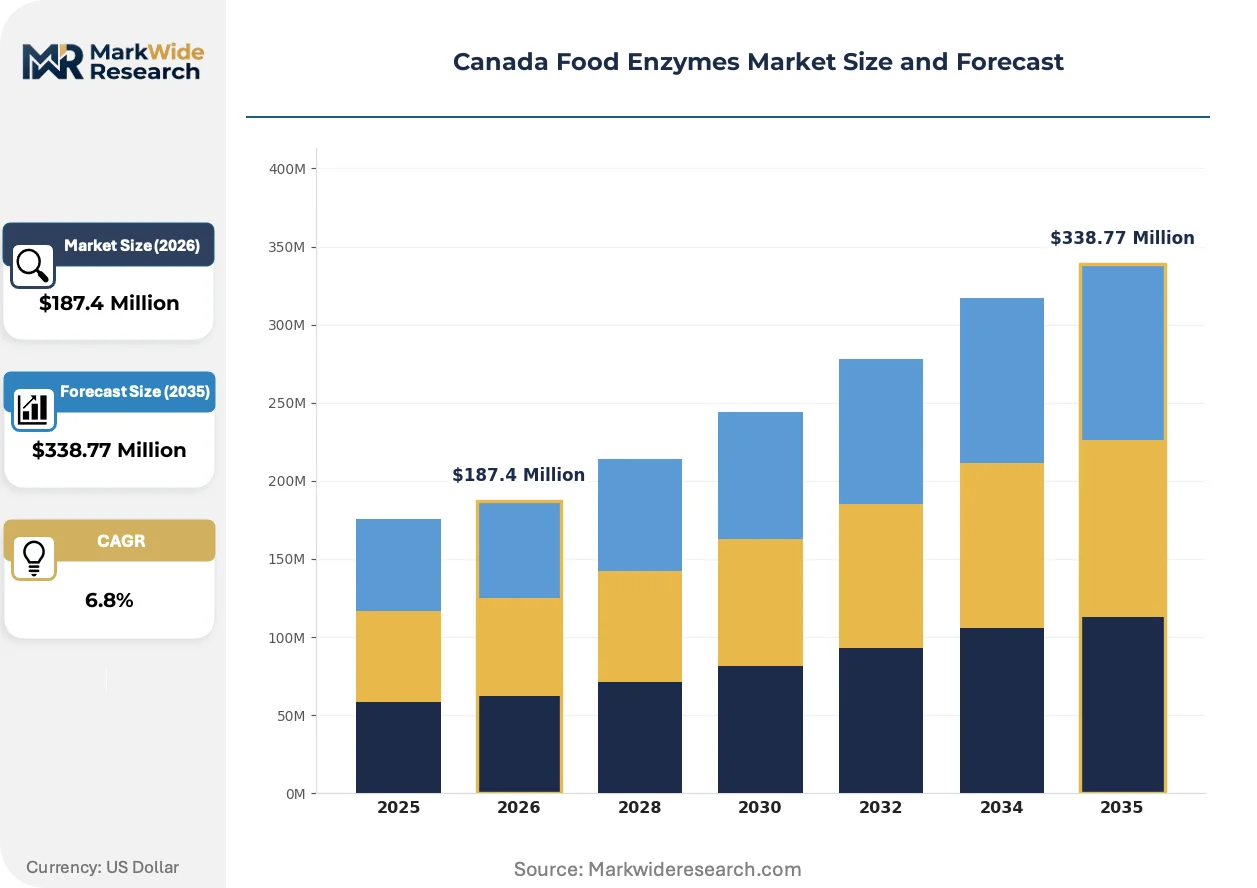
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Baking, Dairy, Meat Processing, Beverages End User: Food Manufacturers, Breweries, Restaurants, Retailers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Chr. Hansen Holding A/S, Associated British Foods Plc, DuPont de Nemours Inc., ABF Ingredients, BASF SE, Kerry Group Plc, Novozymes A/S, Puratos Group, Koninklijke DSM NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Enzymes Market Strategic Shifts
Biocatalysis platforms are fragmenting into specialized application-specific variants, while regulatory data requirements and procurement transparency mandates reshape how suppliers compete for Canadian food manufacturer contracts.
Precision fermentation-derived enzymes are bifurcating the supplier base between commodity biocatalyst traders and integrated biomanufacturers. Ontario bakery conglomerates now specify strain pedigree and carbon-intensity certificates in tenders, compressing margins for undifferentiated importers while rewarding domestic fermentation assets with multi-year supply agreements.
Health Canada's pending amendments to the Food and Drug Regulations would expand mandatory enzyme source labeling to include genetic modification status. Dairy processors in Quebec are pre-emptively reformulating with non-GMO lipase strains to avoid consumer-facing disclosure, even where performance trade-offs exist, reshaping supplier qualification criteria.
Direct supplier-manufacturer technical partnerships are displacing traditional distributor intermediaries in enzyme procurement. British Columbia plant-based protein startups now contract fermentation scientists on secondment from enzyme houses, collapsing the specification-to-application cycle from months to weeks and locking out distributors without in-house technical capacity.
Canada Food Enzymes Market Segmentation
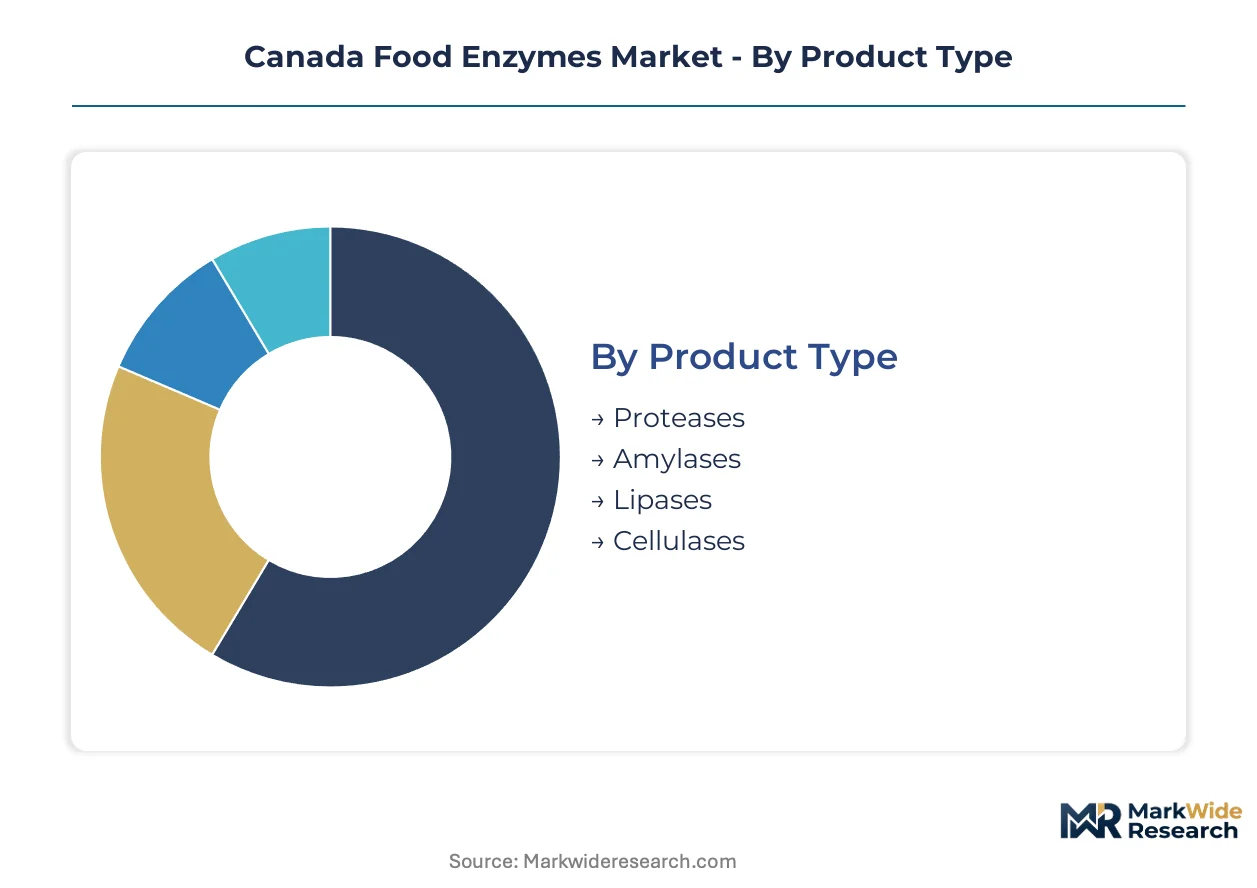
Food enzyme procurement patterns in Canada diverge sharply between domestic dairy and bakery clusters versus export-oriented meat processing corridors. Understanding these segment-specific demand profiles enables suppliers to align technical service capabilities with regional manufacturing densities.
Product Type:
Ontario and Quebec food processors drive domestic demand for high-activity enzyme concentrates, while Prairie grain processors anchor export-facing fermentation output.
- Proteases:These protein-hydrolyzing biocatalysts operate optimally at 45–60°C and pH 5.5–7.5, cleaving peptide bonds to modify texture and accelerate ripening. Saint-Hyacinthe cheese manufacturers deploy specialty protease blends to compress cheddar aging cycles by 30–40%, reducing whey disposal burdens and cold storage costs.
- Amylases:Starch-degrading enzymes hydrolyze α-1,4-glycosidic bonds to produce fermentable sugars and control crumb structure. Toronto-area bakery conglomerates specify fungal amylase systems to replace potassium bromate and azodicarbonamide in clean-label bread formulations, satisfying Loblaw and Sobeys ingredient blacklists.
- Lipases:These triglyceride-modifying catalysts enable targeted fat restructuring for reduced saturated-fat claims in crackers and pastries.
- Cellulases:Cell wall-degrading enzymes improve extraction yields in fruit juice processing and enhance fiber modification in baked goods.
Proteases hold the largest share; momentum sits with lipases as trans-fat reduction mandates intensify across Ontario bakery operations.
Application:
Margin pools concentrate in enzyme-assisted dairy processing, where shortened production cycles deliver measurable working capital advantages.
- Baking:Enzyme conditioners replace chemical oxidizers and emulsifiers in commercial bread and pastry production. Vancouver wholesale bakers deploy lipase-amylase blends to achieve consistent crumb softness without DATEM or SSL declarations on retail labels.
- Dairy:Chymosin and microbial coagulants dominate cheese manufacturing, with enzyme-assisted ripening protocols now standard across Quebec's 200+ cheese facilities. Ontario mozzarella processors leverage protease pre-treatments to accelerate stretch and melt property development.
- Meat Processing:Tenderizing enzymes face CFIA residue testing protocols that favor validated protease suppliers with established Canadian regulatory dossiers.
- Beverages:Brewing applications consume amylase and glucanase systems for wort clarification and filtration efficiency.
Dairy captures the deepest margin pools; beverages are climbing fastest as craft brewery expansion across British Columbia and Alberta drives enzyme demand.
End User:
Procurement sophistication varies dramatically between multinational food manufacturers with captive technical staff and independent operators reliant on distributor formulation support.
- Food Manufacturers:Large-scale processors in Ontario and Quebec negotiate multi-year supply agreements with fermentation houses, specifying strain pedigree and carbon-intensity certificates. Maple Leaf Foods and Olymel integrate protease dosing into standard operating procedures across abattoir operations.
- Breweries:Craft beer producers in Vancouver and Calgary purchase enzyme kits for adjunct brewing and haze stability, typically through specialty ingredient distributors.
- Restaurants:Commercial kitchens deploy pre-hydrated meat tenderizers and dough conditioners through foodservice broadliners.
- Retailers:Private-label bakery and dairy processors source enzymes through co-manufacturer specifications.
Food manufacturers dominate volume; breweries are expanding most quickly as craft segment fragmentation multiplies customer touchpoints.
Distribution Channel:
Channel selection reflects customer technical capability, with direct relationships displacing intermediaries among sophisticated enzyme users.
- Direct Sales:Fermentation houses deploy technical service teams to large dairy and bakery processors, embedding application scientists within customer R&D facilities. This model dominates Quebec cheese manufacturing and Ontario industrial baking.
- Distributors:Regional ingredient houses serve mid-tier food manufacturers without captive enzymology expertise, warehousing standard protease and amylase formulations in Mississauga and Montreal.
- Wholesalers:Broadline foodservice distributors bundle enzymes with commodity ingredients for restaurant and small processor accounts.
- Online Retail:E-commerce platforms capture hobbyist brewers and artisan bakers seeking small-quantity specialty enzymes.
Direct sales command the largest share; online retail is gaining share fastest as craft producer digitization accelerates procurement fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's food enzyme trade flows reflect concentrated import dependence for specialty fermentation inputs alongside growing domestic production capacity in Ontario and Quebec. The analysis covers five provincial markets where food manufacturing density and regulatory frameworks shape enzyme procurement patterns.
Ontario
Toronto-area bakery conglomerates drive demand for clean-label amylase and lipase systems to satisfy retailer ingredient blacklists. Health Canada's Safe Food for Canadians Regulations mandate pre-market safety assessments for genetically engineered enzyme strains used in industrial baking. The Golden Horseshoe food processing corridor anchors procurement volumes for enzyme-assisted dough conditioning and shelf-life extension.
Quebec
Saint-Hyacinthe cheese manufacturers deploy specialty protease blends to compress aging cycles by 30-40%, reducing cold storage costs. The province's cap-and-trade system positions biocatalysts as carbon compliance instruments rather than mere formulation inputs. Montreal's fermentation infrastructure supports captive enzyme supply for dairy processors seeking supply-chain security.
British Columbia
Vancouver craft breweries and plant-based protein startups generate enzyme demand for wort clarification and oat beverage mouthfeel modification. The Canadian Food Inspection Agency's commodity-specific requirements for brewing adjuncts shape supplier qualification criteria. Lower Mainland food innovators contract fermentation scientists directly from enzyme houses, collapsing specification cycles.
Alberta
Prairie grain-price volatility for corn-derived dextrose and soy peptone compresses margin predictability for domestic enzyme manufacturers. The province's meat processing sector faces CFIA residue testing protocols that favor validated protease suppliers with established regulatory dossiers. Calgary's emerging food tech cluster explores enzyme applications for pulse protein extraction.
Atlantic Canada
Nova Scotia and New Brunswick food processors remain reliant on chemical additives, presenting first-mover openings for enzyme suppliers with technical service capabilities. Federal procurement transparency mandates reshape how suppliers compete for contracts in underpenetrated markets. Halifax's seafood processing infrastructure offers retrofit opportunities for enzymatic tenderization applications.
Canada Food Enzymes Market Competitive Environment
Listed leaders compete with private specialists across regulatory dossier depth and technical service deployment. The supplier base concentrates around integrated fermentation houses with captive manufacturing assets and specialty trading operations dependent on third-party sourcing. Three archetypes dominate: multinational biocatalyst platforms with microbial strain libraries, regional ingredient houses warehousing standard formulations, and precision fermentation startups targeting clean-label segments. Competitive moves center on backward integration into fermentation capacity and direct technical partnerships displacing distributor intermediaries.
Within the multinational platform tier, Novozymes A/S and BASF SE exemplify divergent specialization strategies. Novozymes occupies a position anchored in microbial protease supply for dairy applications, while BASF SE represents lipase concentrate development for trans-fat reduction mandates. Kerry Group Plc sits within the integrated processor archetype, leveraging backward integration into enzyme fermentation to secure captive supply for flavor systems. Chr. Hansen Holding A/S and Koninklijke DSM NV represent European-origin specialists with established Health Canada regulatory dossiers.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Associated British Foods Plc |
| DuPont de Nemours Inc. |
| ABF Ingredients |
| BASF SE |
| Kerry Group Plc |
| Novozymes A/S |
| Puratos Group |
| Koninklijke DSM NV |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Quebec fermentation facilities averages above regional norms, compressing unit economics for domestic protease output while elevating price floors for imported specialty lipases. This scale asymmetry between Saint-Hyacinthe biomanufacturing clusters and Prairie grain-processing inputs concentrates bargaining power among integrated suppliers serving Ontario bakery conglomerates.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Canadian food enzyme procurement. Three-tier pricing structure across premium, standard, and economy levels separates Health Canada-validated GM strains from conventional microbial lines and commodity-grade imports. Cost compression in standard-tier amylases is intensifying because Prairie dextrose feedstock volatility feeds into fermentation cost bases. Small Atlantic Canada processors exhibit highest price sensitivity due to volume fragmentation, while Quebec dairy cooperatives prioritize strain pedigree over unit cost.
Supply Chain Analysis
Container availability constraints on the Rotterdam-Montreal lane intermittently inflate inbound logistics costs for Danish and Dutch enzyme concentrates. Geographic supply concentration centers on Denmark, the Netherlands, and domestic Quebec fermentation assets. Raw material dependencies draw from Prairie corn-derived dextrose, soy peptone from Midwest US processors, and specialized microbial strain banks in Northern Europe. Single-source vulnerability persists for GM-strain intellectual property held by two Nordic biocatalyst platforms. Distribution runs through direct technical partnerships for large processors and regional ingredient houses for mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada food enzymes market sits in early-cycle recovery as Prairie grain-price stabilization restores margin predictability to domestic fermentation operations. Clean-label reformulation mandates across Ontario and Quebec retail channels provide the cyclical impetus.
For Market Incumbents: Shield proprietary strain dossiers at Health Canada through accelerated Novel Food resubmissions ahead of pending labeling amendments. Deepen backward integration into Prairie dextrose supply through offtake agreements with grain processors, reducing exposure to spot-market volatility that erodes standard-tier pricing power.
For New Entrants and Emerging Players: Technical service gaps in Atlantic Canada seafood processing present first-mover openings for enzymatic tenderization applications. Target Nova Scotia and New Brunswick processors with on-site application scientists, displacing chemical additive incumbents through demonstration-scale trials at Halifax facilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated fermentation houses with captive Quebec dairy supply contracts. Five-to-ten-year viability favors biomanufacturers with Health Canada regulatory dossiers already validated, as Novel Food approval timelines create moats against faster European EFSA pathways. Monitor Health Canada labeling rule amendments as the inflection signal—expanded GM disclosure mandates would revalue non-GMO strain portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Prairie dextrose offtake agreements reduce margin volatility from grain-price swings. |
| Health Canada Novel Food Dossier Expansion | Pre-approved strain libraries accelerate customer reformulation cycles versus 18-24 month lags. |
| Direct Technical Partnership Deployment | Embedded application scientists at Quebec dairy facilities collapse specification-to-supply cycles. |
| Atlantic Canada Market Development | First-mover technical service presence captures chemical-additive substitution in underpenetrated seafood processing. |
| Carbon-Intensity Certification Investment | Quebec cap-and-trade compliance positioning elevates biocatalysts from inputs to regulatory instruments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with Quebec dairy processing technologists, Ontario bakery R&D directors, Health Canada regulatory affairs specialists, and Prairie grain procurement managers. Secondary validation drew from CFIA commodity-specific requirement documents, Safe Food for Canadians Regulations filings, customs trade data on enzyme concentrate imports, and provincial environmental compliance disclosures. Bottom-up volume estimates from individual facility procurement patterns were triangulated against top-down sectoral spending aggregates.
Across the analysis window, the forecasting framework modeled enzyme demand by product type, application segment, end-user sophistication tier, and provincial regulatory cluster. CAGRs were derived from segment-level growth trajectory analysis anchored to clean-label reformulation cycle timing and carbon-mandate implementation schedules. Industry-specific inputs included Quebec cheese production volume forecasts and Ontario bakery capacity expansion pipelines.
Forecasts assume regulatory continuity in Health Canada's Novel Food assessment protocols and Quebec's cap-and-trade enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Resistant Dextrin Market