
 Meat Tenderizing Agents Market | 2026-2036
Meat Tenderizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Tenderizing Agents Market Outlook
FDA food additive regulations and USDA labeling requirements is consolidating the competitive landscape for meat tenderizing agents. Enzybel Group leverages its European enzyme production footprint to sustain supply chain reliability across marinades and processing segments. AB Enzymes anchors its position through specialized protease portfolios for commercial meat processing. Amano Enzyme Inc. differentiates via fermentation-derived enzyme technologies that navigate clean-label demands.
Meat tenderizing agents comprise functional additives—primarily proteolytic enzymes such as papain, bromelain, and ficain, alongside acidic compounds and salt-based formulations—that hydrolyze collagen and elastin connective tissues to improve meat texture, reduce cooking time, and enhance flavor absorption. These agents operate optimally at specific pH ranges and temperature thresholds, with papain demonstrating activity between 60-70°C for industrial processing applications. Enzymatic formulations command the dominant share of value generation due to precision targeting of muscle proteins and shorter processing windows. Powder and liquid forms lead volume distribution, though paste formats gain traction in at-home cooking channels where convenience drives substitution from mechanical tenderization methods.
FDA GRAS determinations, USDA FSIS inspection protocols, and EFSA enzyme safety evaluations shape product registration pathways and label claims across North America and Europe. Formulators must demonstrate allergen control for papaya and pineapple-derived enzymes under FDA Food Safety Modernization Act preventive controls. Stakeholders must monitor evolving enzyme concentration thresholds in processed meat exports to Saudi Arabia and China, where national food safety regulators tighten import specifications for biological additives.
Market Dynamics
Commercial meat processors are abandoning mechanical blade tenderization for enzyme-based systems that slash processing time while meeting export-grade texture specifications. This equipment-to-biology substitution reconfigures capital allocation and supplier relationships across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic refrigerants in processing plants accelerate adoption of ambient-temperature enzymatic methods that eliminate cryogenic mechanical tenderization.
- Brazilian beef export certification:Premium enzyme demand concentrates in São Paulo and Mato Grosso processing corridors where EU and Chinese import standards mandate consistent collagen breakdown documentation.
- Papain thermal stability advances:Engineered enzyme variants now maintain activity at 60-70°C industrial processing windows, replacing slower overnight marination protocols.
Market Restraints
- Papaya crop volatility:Thai and Indian papain supply fluctuates with monsoon patterns, creating raw material cost instability for tropical-enzyme formulators.
- REACH compliance burden:ECHA registration costs for novel protease formulations exceed €100,000 per substance, blocking mid-tier entrants from European commercial markets.
- Mechanical tenderization legacy:USDA-inspected facilities retain needle-blade infrastructure investments that resist full enzyme conversion despite operational inefficiencies.
Strategic Opportunities
- Clean-label fermentation:Microbial-derived bromelain alternatives bypass allergen labeling requirements for pineapple-sensitive consumer segments in German and French retail channels.
- Saudi SFDA enzyme thresholds:Tightening import specifications for biological additives create first-mover advantage for suppliers with pre-certified halal enzyme documentation.
- Direct-to-processor e-commerce:Bulk enzyme concentrate platforms bypass traditional distribution layers, capturing margin from mid-size Brazilian and Australian abattoirs.
Industry Challenges
- Enzymologist talent scarcity:Formulation chemists with protease stability expertise command premium salaries, constraining R&D expansion at specialty ingredient houses.
- FDA FSIS preventive control documentation:Allergen control validation for papaya-derived enzymes demands 18-24 month compliance timelines before commercial deployment.
- Legacy pH monitoring infrastructure:Older processing plants lack real-time enzyme activity sensors, forcing manual sampling that degrades batch consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Tenderizing Agents Market |
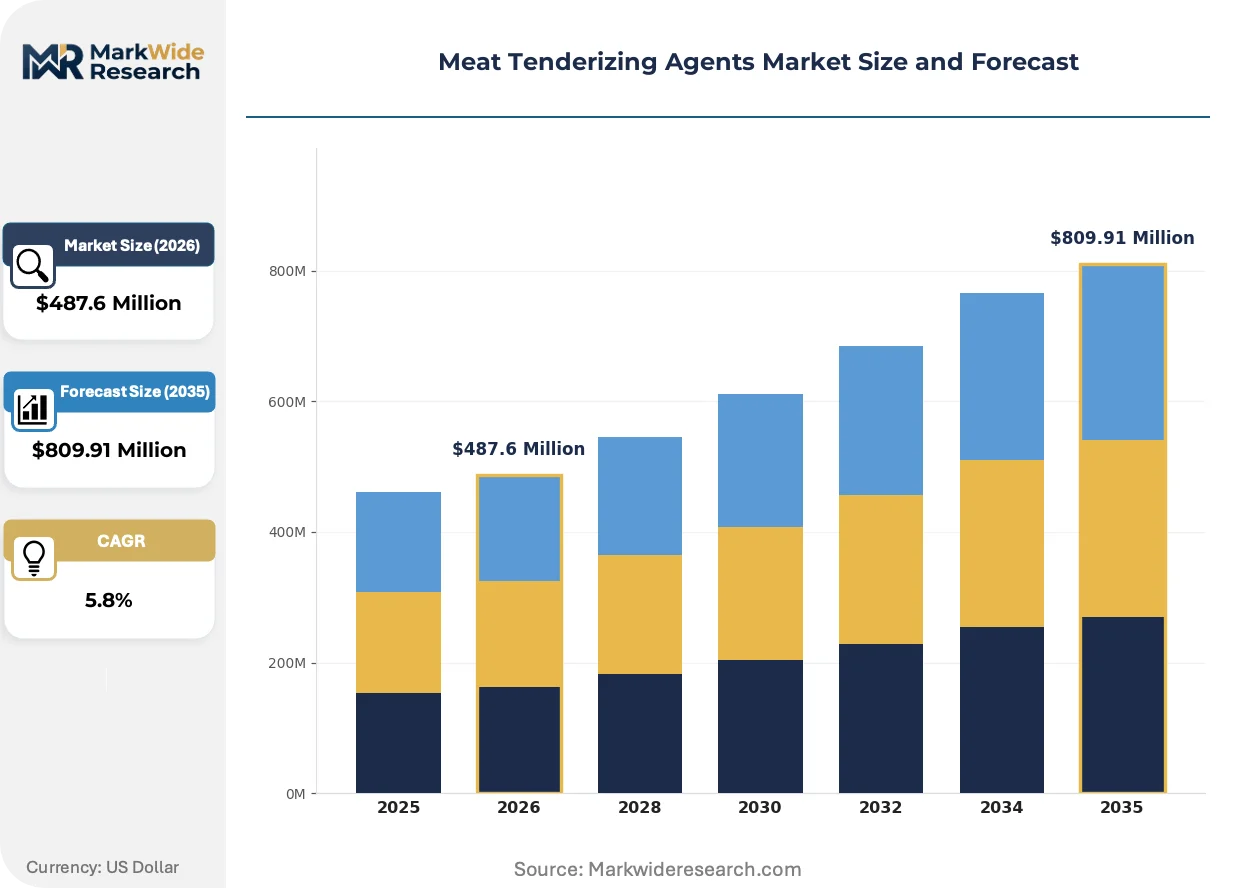
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Enzymatic, Acidic, Mechanical, Salt-based Application: Meat Processing, Marinades, At-home Cooking, Commercial Use Ingredient Source: Pineapple, Papaya, Figs, Others Form: Powder, Liquid, Granular, Paste |
| Companies Covered | Enzybel Group, AB Enzymes, Amano Enzyme Inc., Specialty Enzymes and Biotechnologies, Enzyme Bioscience Pvt Ltd, Enzyme Development Corporation, Enzyme Solutions, National Enzyme Company, Tampico Spice Co Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Tenderizing Agents Market Strategic Shifts
Biotechnology and regulatory stringency are compressing traditional processing windows while fragmenting buyer preferences across industrial, foodservice, and retail channels. Formulators now compete on enzyme specificity rather than commodity pricing.
Precision fermentation is consolidating microbial enzyme production economics. Recombinant protease strains from Aspergillus and Bacillus platforms now achieve papain-equivalent specific activity at commercial scale. Brazilian and Thai processors are adopting these systems fastest, displacing extraction-dependent tropical enzyme supply chains. The technology is consolidating supplier power among fermentation-capable biotech firms while eroding commodity papain margins.
China's SAMR biological additive notifications are tightening import documentation for enzyme concentrates entering food processing facilities. The regulation now demands batch-level activity certificates and origin traceability for all proteolytic preparations. European exporters to Chinese beef processing joint ventures are responding by embedding QR-code verification systems directly into enzyme packaging, creating compliance infrastructure that smaller competitors cannot replicate.
Foodservice distributors are unbundling tenderized meat specifications from commodity procurement contracts. Large US restaurant chains now source pre-enzyme-treated cuts through specialized protein suppliers rather than integrated packers, compressing traditional processor-distributor relationships. This disintermediation is most visible in Texas and California quick-service channels where speed-to-grill specifications override historical supplier loyalty.
Meat Tenderizing Agents Market Segmentation
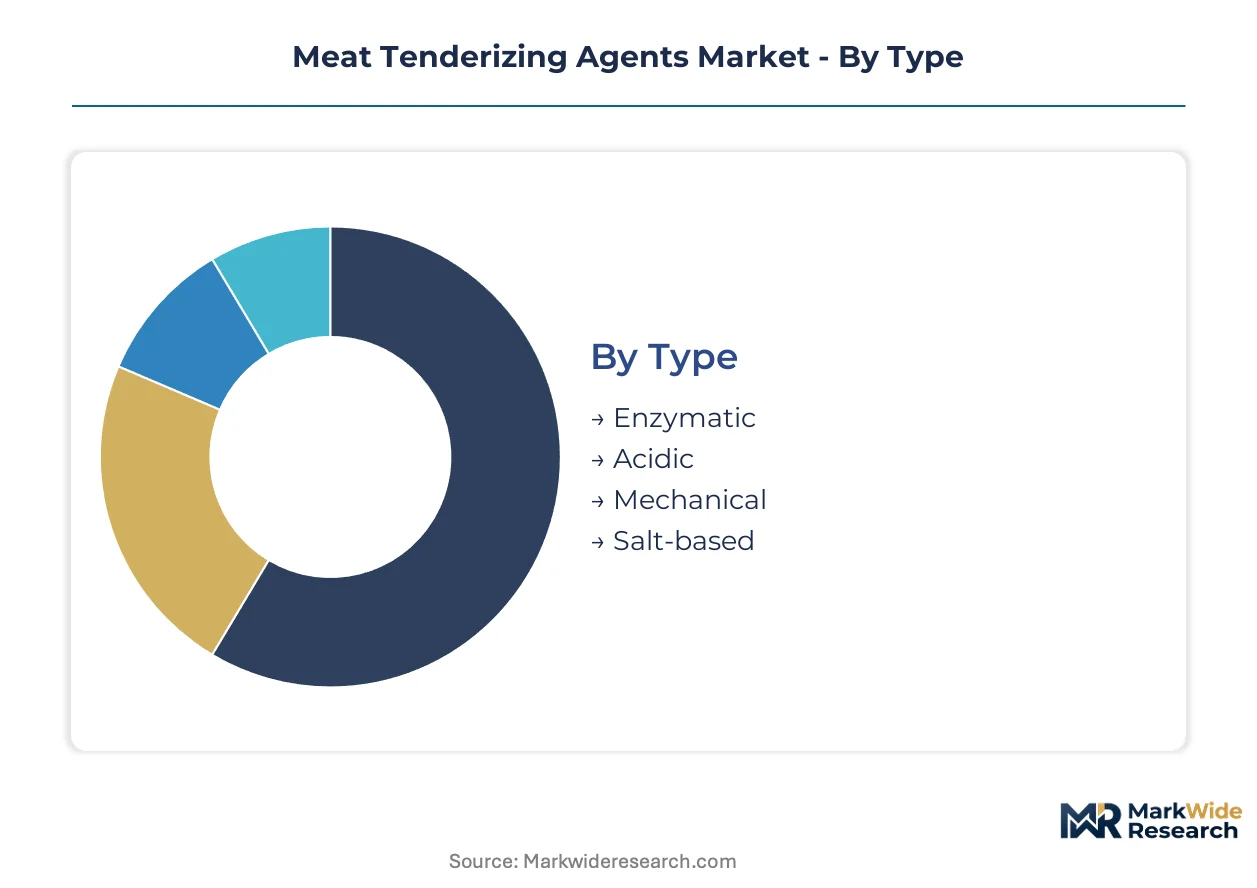
Segmentation in meat tenderizing agents separates commodity-grade formulations from precision-engineered enzyme systems. Each dimension—type, application, source, and form—carries distinct margin profiles and regulatory compliance burdens that reshape supplier strategies.
Type:
Volume concentrates in commodity enzymatic formulations, while premium pricing attaches to specialized acidic and mechanical alternatives.
- Enzymatic:Proteolytic enzymes hydrolyze collagen and elastin at specific pH and temperature thresholds. Papain from Thai and Indian papaya crops dominates commercial meat processing in São Paulo and Mato Grosso corridors where EU export certification demands consistent activity documentation. REACH registration costs exceeding €100,000 per novel protease formulation block mid-tier European entrants from this segment.
- Acidic:Citric, acetic, and phosphoric acid formulations denature proteins through pH reduction rather than enzymatic cleavage. Brazilian processors favor these systems for halal-certified beef exports to Saudi Arabia where SFDA documentation requirements favor simpler chemical traceability over complex enzyme batch certificates.
- Mechanical:Blade and needle tenderization equipment persists in USDA-inspected facilities with sunk capital in needle-blade infrastructure. Legacy plants in Texas and California resist full enzyme conversion despite operational inefficiencies.
- Salt-based:Sodium chloride and phosphate blends draw moisture into muscle fibers through osmotic pressure. These formulations dominate at-home cooking channels in Germany and France where clean-label demands are less stringent than in foodservice procurement.
Mature deployment sits with enzymatic systems in large-scale commercial processing. Newer deployment is concentrated in acidic formulations for export-certified halal segments.
Application:
Customer type separates industrial procurement from fragmented retail and foodservice buying patterns.
- Meat Processing:Industrial abattoirs and further-processing facilities deploy enzyme systems for collagen breakdown in high-volume beef and pork operations. Brazilian processors in São Paulo state adopt precision fermentation-derived proteases fastest, displacing extraction-dependent tropical enzyme supply chains.
- Marinades:Pre-formulated liquid and dry marinade blends integrate tenderizing enzymes with flavor compounds for foodservice distributors. Large US restaurant chains in Texas and California now source pre-enzyme-treated cuts through specialized protein suppliers rather than integrated packers.
- At-home Cooking:Retail consumers purchase powder and paste formats for domestic meal preparation. Paste formats gain traction in German and French retail channels where convenience drives substitution from mechanical tenderization methods.
- Commercial Use:Foodservice operations including hotels, catering, and institutional kitchens apply tenderizing agents to manage protein texture consistency. Quick-service specifications in California override historical supplier loyalty as speed-to-grill requirements intensify.
Procurement consolidation characterizes meat processing applications. Fragmented purchasing patterns dominate at-home cooking channels.
Ingredient Source:
Supply geography determines cost volatility and allergen labeling obligations across regulatory jurisdictions.
- Pineapple:Bromelain extraction from pineapple stems and fruit delivers proteolytic activity with distinct temperature stability profiles. Microbial-derived alternatives from Aspergillus and Bacillus fermentation platforms now achieve equivalent specific activity, bypassing allergen labeling for pineapple-sensitive consumer segments in European retail.
- Papaya:Papain dominates industrial processing due to thermal stability advances maintaining activity at 60-70°C windows. Thai and Indian monsoon patterns create raw material cost instability that precision fermentation is gradually displacing.
- Figs:Ficain from fig latex provides alternative proteolytic activity with distinct substrate specificity. Niche applications in specialty meat products and traditional processing methods in Mediterranean markets sustain limited commercial volume.
- Others:Kiwifruit actinidin and microbial fermentation products expand source diversity. Recombinant strains consolidate supplier power among fermentation-capable biotech firms while eroding commodity tropical enzyme margins.
Established supply chains anchor papaya and pineapple extraction. Fermentation-derived alternatives represent the steepest expansion trajectory.
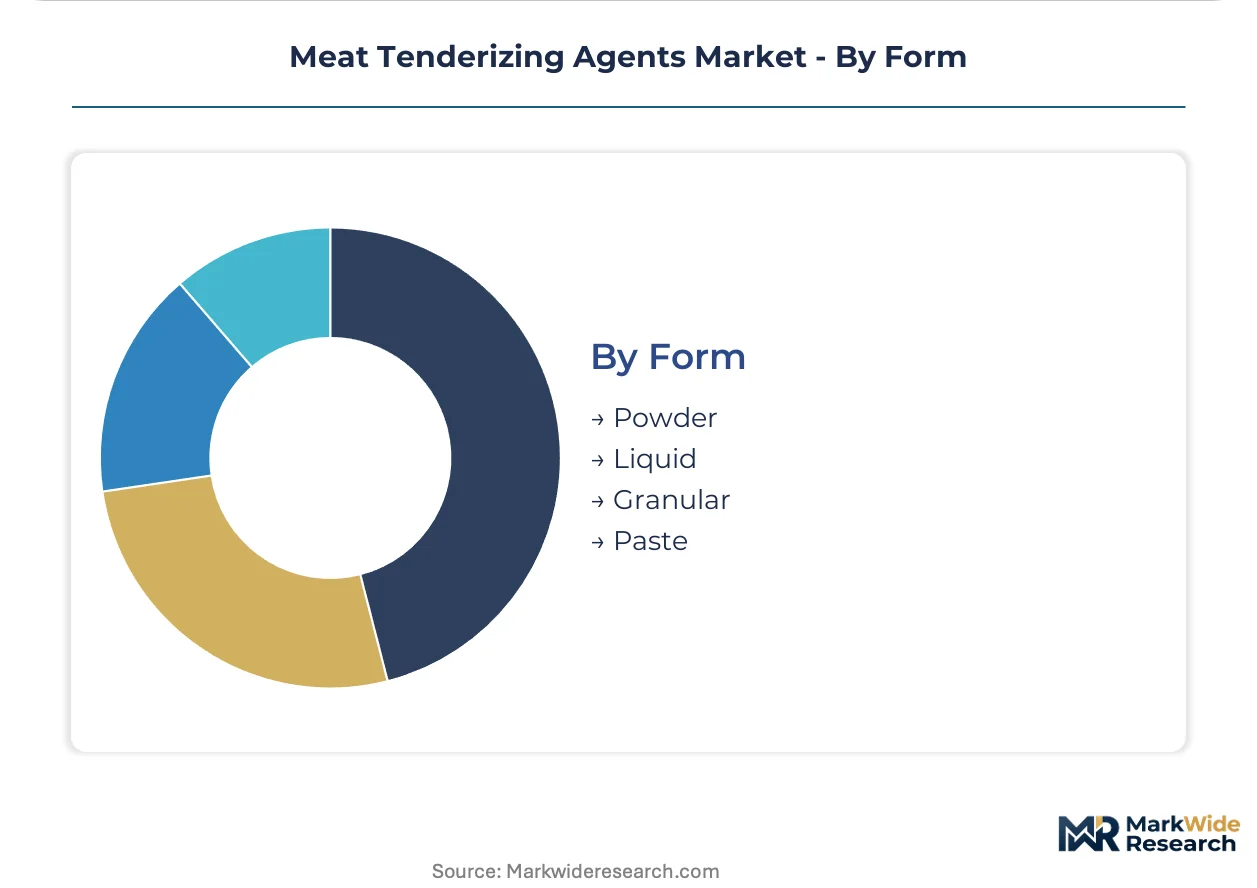
Form:
Physical format dictates dosing precision, shelf stability, and distribution economics through processing and retail channels.
- Powder:Dry enzyme concentrates and salt-based blends dominate bulk commercial procurement for meat processing facilities. Brazilian and Australian abattoirs increasingly source through direct-to-processor e-commerce platforms that bypass traditional distribution layers.
- Liquid:Ready-to-use enzyme solutions and acidic formulations enable precise dosing in continuous processing lines. China's SAMR now demands batch-level activity certificates and origin traceability, prompting European exporters to embed QR-code verification systems directly into liquid enzyme packaging.
- Granular:Free-flowing dry particles suit automated dispensing equipment in large-scale operations. This format bridges powder economy with liquid handling convenience for mid-tier processors.
- Paste:High-viscosity formulations target at-home cooking and small commercial kitchens where measurement simplicity outweighs unit cost premiums. German and French retail channels show fastest paste format adoption among convenience-seeking consumers.
Industrial scale favors powder and liquid systems. Paste formats penetrate consumer markets most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in São Paulo state concentrate Brazilian enzyme demand, while EU REACH compliance zones in Germany and Netherlands reshape supplier economics across the Atlantic corridor.
Brazil
Beef processing volumes in São Paulo and Mato Grosso corridors drive premium enzyme consumption for EU and Chinese export certification. ANVISA documentation requirements for biological additives tighten batch-level traceability standards. São Paulo state processors adopt precision fermentation-derived proteases fastest, displacing traditional tropical extraction supply chains.
United States
USDA-inspected facilities in Texas and California retain mechanical tenderization infrastructure while adopting enzymatic systems for speed-to-grill specifications. FDA FSIS preventive controls demand 18-24 month allergen validation timelines for papaya-derived enzymes. Texas quick-service restaurant chains now source pre-enzyme-treated cuts through specialized protein suppliers rather than integrated packers.
Germany
Clean-label fermentation demand in German retail channels accelerates microbial-derived bromelain alternatives bypassing pineapple allergen labeling. ECHA registration costs exceeding €100,000 per novel protease formulation block mid-tier entrants. Bavarian and North Rhine-Westphalia processing corridors concentrate enzyme formulation R&D for halal-certified export markets.
China
SAMR biological additive notifications tighten import documentation for enzyme concentrates entering beef processing joint ventures. Batch-level activity certificates and origin traceability requirements now apply to all proteolytic preparations. Yangtze River Delta processing hubs embed QR-code verification systems into enzyme packaging to satisfy compliance infrastructure demands.
Saudi Arabia
SFDA enzyme threshold tightening for biological additives creates first-mover advantage for suppliers with pre-certified halal documentation. Acidic formulations gain preference over enzymatic systems for simpler chemical traceability in export-certified beef. Riyadh and Eastern Province processing corridors concentrate demand for documented collagen breakdown specifications.
Meat Tenderizing Agents Market Competitive Environment
European producers anchor one tier; Asian specialists hold fermentation scale advantages. The vendor base separates into consolidated biotechnology platforms and fragmented regional formulators. Three archetypes dominate: precision fermentation operators, tropical extraction-dependent suppliers, and hybrid chemical-enzyme blenders. Competitive moves concentrate on REACH pre-registration strategies and halal certification pre-qualification for Middle East access.
Within the fermentation-technology tier, Amano Enzyme Inc. and AB Enzymes exemplify microbial-derived production scale, while Enzybel Group occupies a position bridging European enzyme manufacturing with supply chain reliability across marinades and processing segments. These anchors represent the shift from commodity papain extraction toward recombinant protease platforms.
| Leading Market Players |
|---|
| Enzybel Group |
| AB Enzymes |
| Amano Enzyme Inc. |
| Specialty Enzymes and Biotechnologies |
| Enzyme Bioscience Pvt Ltd |
| Enzyme Development Corporation |
| Enzyme Solutions |
| National Enzyme Company |
| Tampico Spice Co Inc |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation scale-up is compressing production economics while redrawing supplier power maps across enzymatic and extraction-dependent tenderizer categories. Thai and Indian papain extraction operations now face margin pressure from recombinant protease platforms that bypass tropical crop volatility entirely.
Pricing Analysis
Short lead-time premiums attach to precision fermentation-derived enzymes with documented batch activity certificates, while spot inventory of commodity papain trades at discounts. Three-tier pricing structure separates pharmaceutical-grade proteases with REACH dossiers from standard industrial formulations and economy-grade salt-based blends. Cost compression in commodity enzymatic tiers is intensifying because Brazilian processors are consolidating procurement volumes around pre-certified suppliers. Mid-size Australian abattoirs exhibit highest price sensitivity due to working capital constraints, while EU export-certified São Paulo facilities prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-processor e-commerce platforms now handle hyperscale demand from Brazilian and Australian abattoirs, bypassing traditional distribution layers. Raw material supply anchors in Thailand, India, and Brazil for papain extraction, while microbial fermentation capacity concentrates in Germany, Japan, and the United States. Recombinant strain development rests on Aspergillus and Bacillus platform mastery, with growth media and bioreactor equipment as critical inputs. Single-source vulnerability runs through Thai papaya crop concentration exposed to monsoon pattern disruption. Distribution runs through specialized ingredient distributors for smaller processors and direct contracts for large-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration exceeding €100,000 per novel protease erects a barrier-to-entry moat protecting established European fermentation operators.
For Market Incumbents: Hedge against tropical enzyme supply disruption by accelerating backward integration into precision fermentation capacity in Bavarian and North Rhine-Westphalia corridors. Secure pre-qualified halal documentation for Saudi SFDA thresholds before competitor certification windows close. Anchor position through captive supply of recombinant protease strains that displace commodity papain dependence.
For New Entrants and Emerging Players: Enter via direct-to-processor e-commerce platforms serving mid-size Brazilian and Australian abattoirs underserved by traditional distribution layers. Target acidic formulation segments for halal-certified beef exports to Saudi Arabia where documentation requirements favor simpler chemical traceability. Pursue white-label manufacturing partnerships with established fermentation houses to bypass REACH registration capital requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by consolidated biotechnology platforms seeking fermentation scale and geographic certification coverage. Long-term viability favors operators with dual capabilities across precision fermentation and established tropical extraction relationships. Monitor Chinese SAMR notification timelines as inflection indicator for import documentation intensity and compliance infrastructure investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Recombinant protease platforms displace Thai and Indian papain extraction economics. |
| Halal Certification Pre-Qualification | SFDA documentation requirements create first-mover advantage in Saudi beef processing corridors. |
| Direct-to-Processor E-Commerce | Bypass traditional distribution layers to capture margin from mid-size Brazilian abattoirs. |
| REACH Dossier Completion | €100,000+ registration costs block mid-tier entrants from European commercial markets. |
| QR-Code Compliance Infrastructure | Chinese SAMR batch-level traceability demands embed verification into enzyme packaging. |
Study Parameters
Multi-period observation of enzyme concentration thresholds, export certification standards, and fermentation capacity buildouts anchored the trend analysis, supplemented by interviews with commercial meat processing facility managers, enzyme formulation chemists, regulatory affairs specialists at ANVISA and SAMR, and procurement leads at Brazilian beef export operations. Secondary validation drew from ECHA registration databases, FDA GRAS notifications, customs trade data for protease concentrates, and SEC filings of publicly traded biotechnology platforms. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped protease activity units to processed meat volumes across enzymatic, acidic, mechanical, and salt-based type segments, with application splits across meat processing, marinades, at-home cooking, and commercial use channels. Source differentiation tracked pineapple extraction, papaya cultivation, fig latex harvesting, and microbial fermentation platforms. Form factors modeled powder, liquid, granular, and paste distribution economics. CAGRs derived from regression analysis of historical capacity utilization, regulatory implementation timelines, and substitution elasticity between mechanical and enzymatic tenderization methods.
Revisions become necessary when Brazilian export certification standards tighten, Chinese SAMR notification requirements expand, or precision fermentation yield improvements accelerate beyond baseline assumptions. Forecasts reflect documented enzyme activity specifications, crop yield projections for tropical source materials, and regulatory implementation schedules. Periodic stress-testing of base assumptions against actual REACH registration completion rates and halal certification pre-qualification timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Pet Food Emulsifier Market