
 Canada Food Emulsifiers Market | 2026-2036
Canada Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Emulsifiers Market Outlook
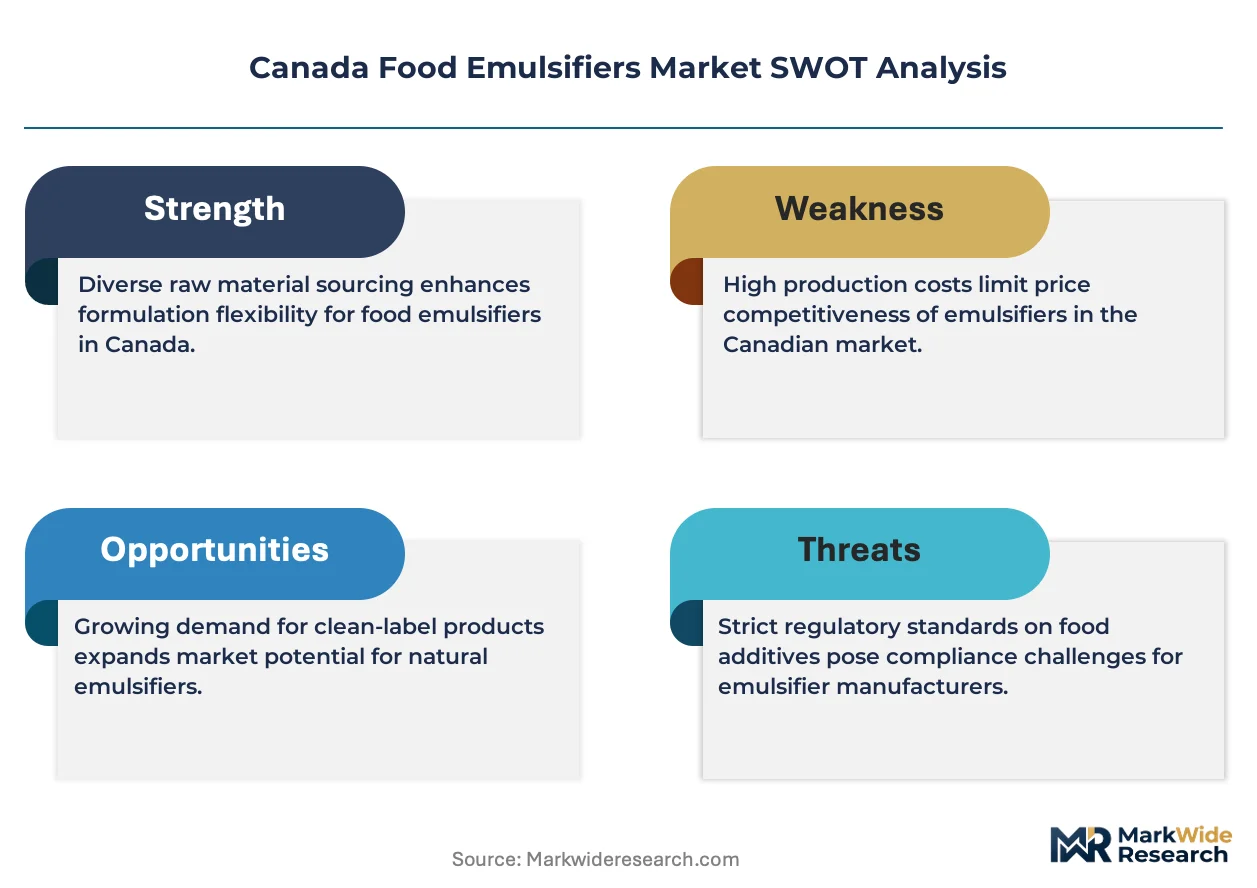
The gap between premium clean-label emulsifiers and commodity-grade alternatives is realigning procurement strategies across Canadian food manufacturing. Kerry Group plc leverages its North American ingredient technology platform to sustain leadership in plant-derived lecithin applications. Cargill, Incorporated anchors its position through backward integration into oilseed processing, while BASF SE differentiates via synthetic emulsifier specialization for industrial bakery scale.
Food emulsifiers are surface-active agents that reduce interfacial tension between immiscible phases such as oil and water, typically comprising molecules with both hydrophilic and lipophilic moieties; mono- and diglycerides function through partial esterification of glycerol with fatty acids to achieve HLB values between 3 and 6 for water-in-oil systems. Lecithin dominates volume consumption in Canadian dairy alternatives and baked goods due to its label-friendly phospholipid composition, while sorbitan esters occupy higher-margin niches in confectionery fat bloom control where thermal stability requirements exceed standard monoglyceride performance.
Health Canada and the Canadian Food Inspection Agency enforce the Safe Food for Canadians Regulations and Food and Drug Regulations, which govern emulsifier additive approvals, maximum usage levels, and labeling disclosures that directly constrain formulation flexibility. The CFIA's preventive control plan requirements for food manufacturers further elevate documentation burdens for imported emulsifier sourcing. Stakeholders must monitor regulatory divergence between Canadian and U.S. FDA GRAS designations, as asynchronous approval timelines for novel emulsifier technologies could fragment cross-border supply strategies.
Market Dynamics
Clean-label migration is compressing formulation cycles across Canadian food manufacturing as processors reformulate around Health Canada's evolving additive disclosure requirements and plant-based stabilizer specifications.
Growth Catalysts
- Safe Food for Canadians Regulations:Health Canada's preventive control plan mandates are accelerating documentation standardization among domestic emulsifier users, creating procurement preference for pre-qualified suppliers with established compliance infrastructure.
- Dairy alternative expansion:Oat and pea protein beverage processors in Ontario and Quebec are specifying phospholipid-based lecithin systems to achieve clean-label positioning without synthetic mono-glyceride alternatives.
- Industrial bakery clustering:Greater Toronto Area and Montreal corridor concentration of large-scale commercial bakeries generates concentrated demand for emulsifier blends optimized for extended shelf-life and freeze-thaw stability.
Market Restraints
- Canola and soybean input volatility:Lecithin production costs track prairie oilseed commodity swings, compressing margin predictability for domestic processors without backward integration into crushing operations.
- Import dependency concentration:Specialty sorbitan esters and distilled monoglycerides flow predominantly through U.S. and European suppliers, exposing Canadian formulators to cross-border logistics friction and currency fluctuation.
- GRAS-Food and Drug Regulations divergence:Novel emulsifier technologies approved under U.S. FDA pathways face asynchronous Health Canada review timelines, fragmenting product launch synchronization for multinational food manufacturers.
Strategic Opportunities
- Prairie oilseed processing integration:Saskatchewan and Manitoba crushing capacity expansion offers domestic lecithin producers captive supply chain control over phospholipid raw material flows.
- Cell-cultured meat adjunct positioning:Emerging Canadian precision fermentation startups require customized emulsifier systems for fat structuring in hybrid meat analogues, opening formulation partnership channels.
- CFIA export certification leverage:Canadian Food Inspection Agency equivalence agreements with select Asian markets create regulatory pathway advantages for domestic emulsifier suppliers qualifying under integrated food safety frameworks.
Industry Challenges
- Food additive toxicology expertise scarcity:Health Canada submission preparation requires specialized regulatory science capabilities concentrated in Toronto and Vancouver consultancies, creating talent bottlenecks for mid-sized ingredient firms.
- Clean-label reformulation capex intensity:Transitioning from synthetic to plant-derived emulsifier systems demands pilot-scale extrusion and spray-drying equipment investments that strain processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Emulsifiers Market |
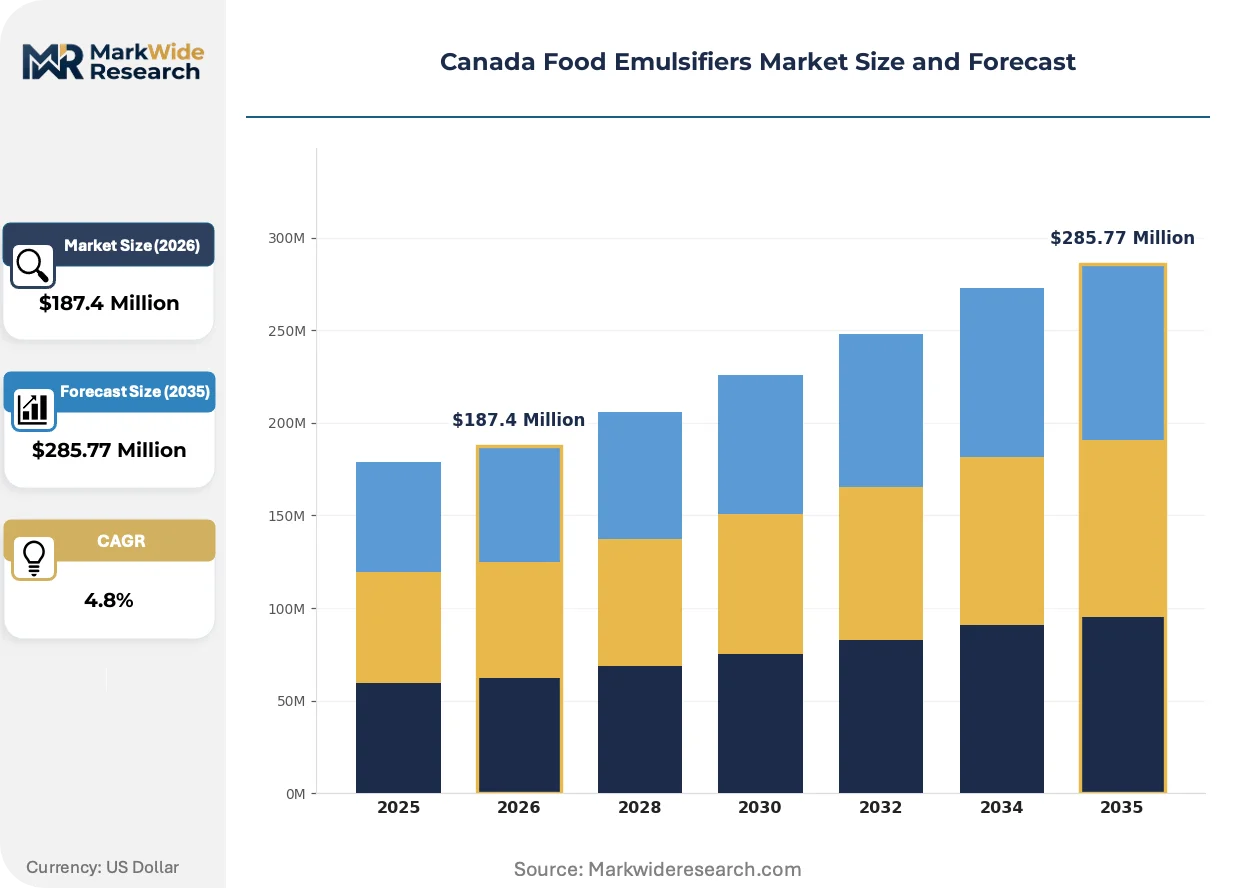
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono- and Diglycerides, Lecithin, Sorbitan Esters, Polyglycerol Esters Application: Dairy Products, Baked Goods, Sauces, Dressings Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade End User: Food Manufacturers, Beverage Companies, Confectionery Producers, Bakery Establishments |
| Companies Covered | Corbion NV, BASF SE, Kerry Group plc, Caldic B.V., Archer Daniels Midland Company, Bulk Barn Foods Limited, Botanic Planet, ADM, Cargill, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Emulsifiers Market Strategic Shifts
Enzymatic modification processes and precision fermentation are displacing solvent-based extraction in Canadian emulsifier production, while regulatory disclosure tightening and procurement centralization reshape competitive access.
Enzyme-catalyzed interesterification is automating the production of tailored mono- and diglyceride structures with specific HLB values for water-in-oil bakery applications. Large Ontario commercial bakeries are adopting these enzymatically processed emulsifiers at accelerating rates to achieve clean-label compliance without sacrificing dough conditioning performance. This biotechnology transition is compressing demand for conventional chemical glycerolysis routes while elevating premium positioning for enzymatic product lines.
Health Canada's Food and Drug Regulations amendment proposals on enhanced additive labeling are forcing reformulation disclosures for mono- and diglyceride sources. Industrial consequence includes accelerated substitution toward lecithin and plant-derived alternatives that require less explanatory packaging text. Quebec dairy alternative processors are responding most aggressively, specifying certified organic sunflower lecithin to preempt consumer scrutiny on ingredient panels.
Consolidated procurement through national food manufacturing headquarters is displacing regional ingredient sourcing autonomy across Canadian bakery and dairy sectors. Category managers at Toronto and Montreal corporate centers now mandate single-supplier emulsifier contracts with integrated technical service support, marginalizing smaller regional distributors. This concentration pattern is most visible in Ontario's Golden Horseshoe manufacturing belt where plant closures have compressed buyer geography.
Canada Food Emulsifiers Market Segmentation
Emulsifier procurement patterns in Canadian food manufacturing diverge sharply between commodity-grade bulk applications and precision-formulated specialty systems. Understanding these segment boundaries clarifies where formulation investments concentrate versus where price competition dominates supplier relationships.
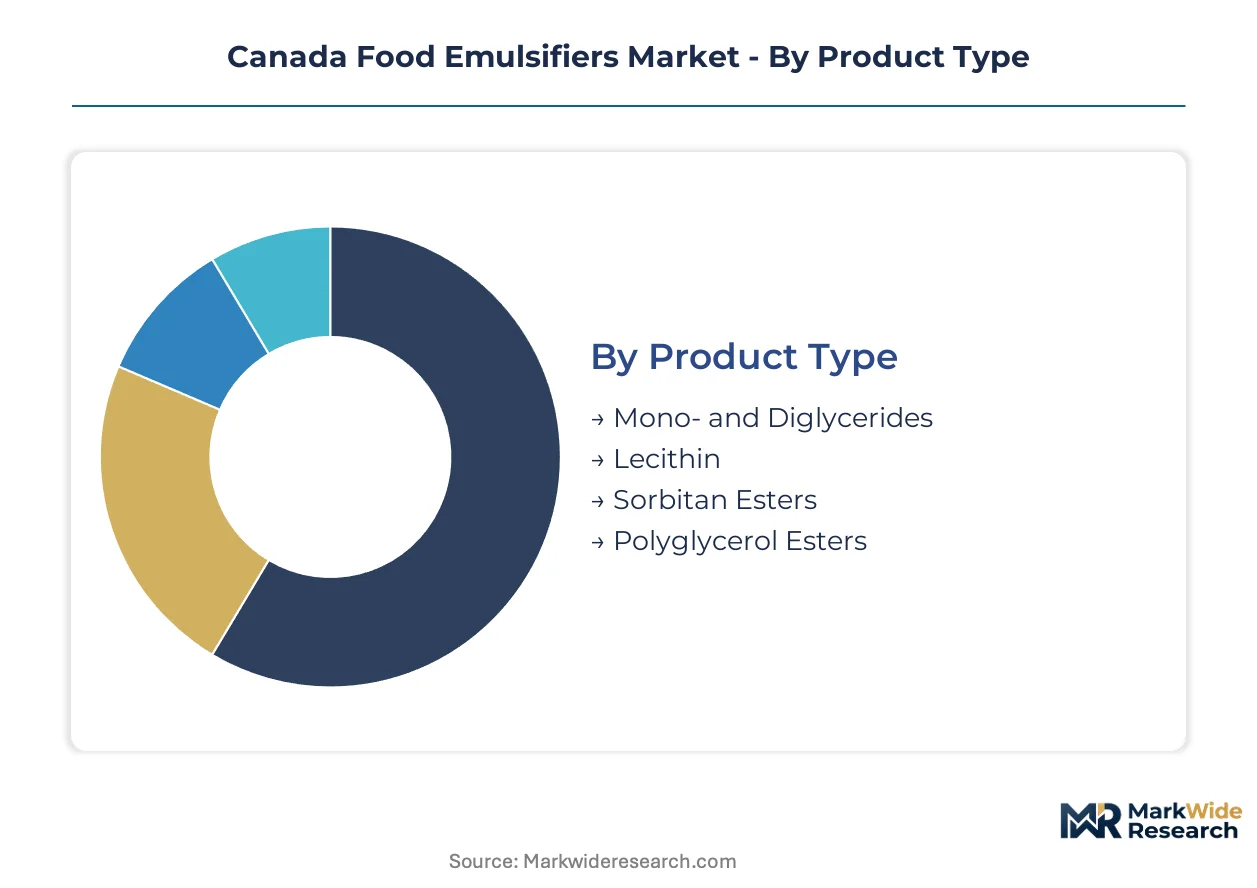
Product Type:
Integration depth varies substantially across emulsifier chemistries, with some functioning as standalone stabilizers while others require co-emulsifier pairing for full performance.
- Lecithin:Phospholipid mixtures extracted from soybean or sunflower oilseeds deliver label-friendly emulsification without synthetic additive classification. Ontario oat milk processors specify non-GMO sunflower lecithin to meet clean-label positioning requirements while avoiding allergen disclosure burdens associated with soy-derived alternatives.
- Mono- and Diglycerides:Partial fatty acid esters of glycerol achieve HLB values of 3-6 for water-in-oil systems through controlled esterification. Quebec industrial bakeries procure enzymatically processed variants to satisfy Health Canada's evolving additive disclosure mandates without sacrificing dough conditioning performance in frozen par-baked applications.
- Sorbitan Esters:Lipophilic surfactants derived from sorbitol dehydration provide thermal stability exceeding standard monoglyceride performance.
- Polyglycerol Esters:Multi-functional emulsifiers synthesized through glycerol polymerization offer broad HLB range coverage.
Volume placements concentrate in Lecithin; the faster expansion belongs to Mono- and Diglycerides.
Application:
Cost tier stratification separates commodity-scale industrial users from premium-positioned specialty formulators across Canadian food processing.
- Baked Goods:Commercial bakeries in the Greater Toronto Area and Montreal corridor deploy emulsifier blends optimized for extended shelf-life and freeze-thaw stability in par-baked distribution systems. Large-scale operations specify integrated technical service contracts, marginalizing smaller regional distributors.
- Dairy Products:Conventional dairy and plant-based alternative processors specify phospholipid-based systems for clean-label compliance. Butter and cream applications maintain steady demand for distilled monoglycerides in texture stabilization.
- Confectionery:Fat bloom control requirements drive sorbitan ester specification in chocolate manufacturing.
- Sauces, Dressings:Mayonnaise and vinaigrette emulsions utilize lecithin and polyglycerol ester combinations.
Procurement scale peaks in Baked Goods; margin capture concentrates in Dairy Products.
Grade:
Application maturity determines grade specification rigor, with established food categories maintaining food-grade dominance while adjacent industries drive pharmaceutical and cosmetic tier demand.
- Food Grade:Compliant with Health Canada's Food and Drug Regulations and Safe Food for Canadians Regulations, this grade dominates Canadian procurement volume. CFIA preventive control plan documentation requirements elevate preference for pre-qualified suppliers with established compliance infrastructure.
- Industrial Grade:Non-food applications in animal feed and technical manufacturing absorb lower-purity emulsifier streams.
- Pharmaceutical Grade:USP/NF compliance enables excipient applications in drug delivery systems.
- Cosmetic Grade:Personal care emulsion stability requirements drive specialized specification.
Volume concentration sits with Food Grade; specification complexity climbs fastest in Pharmaceutical Grade.
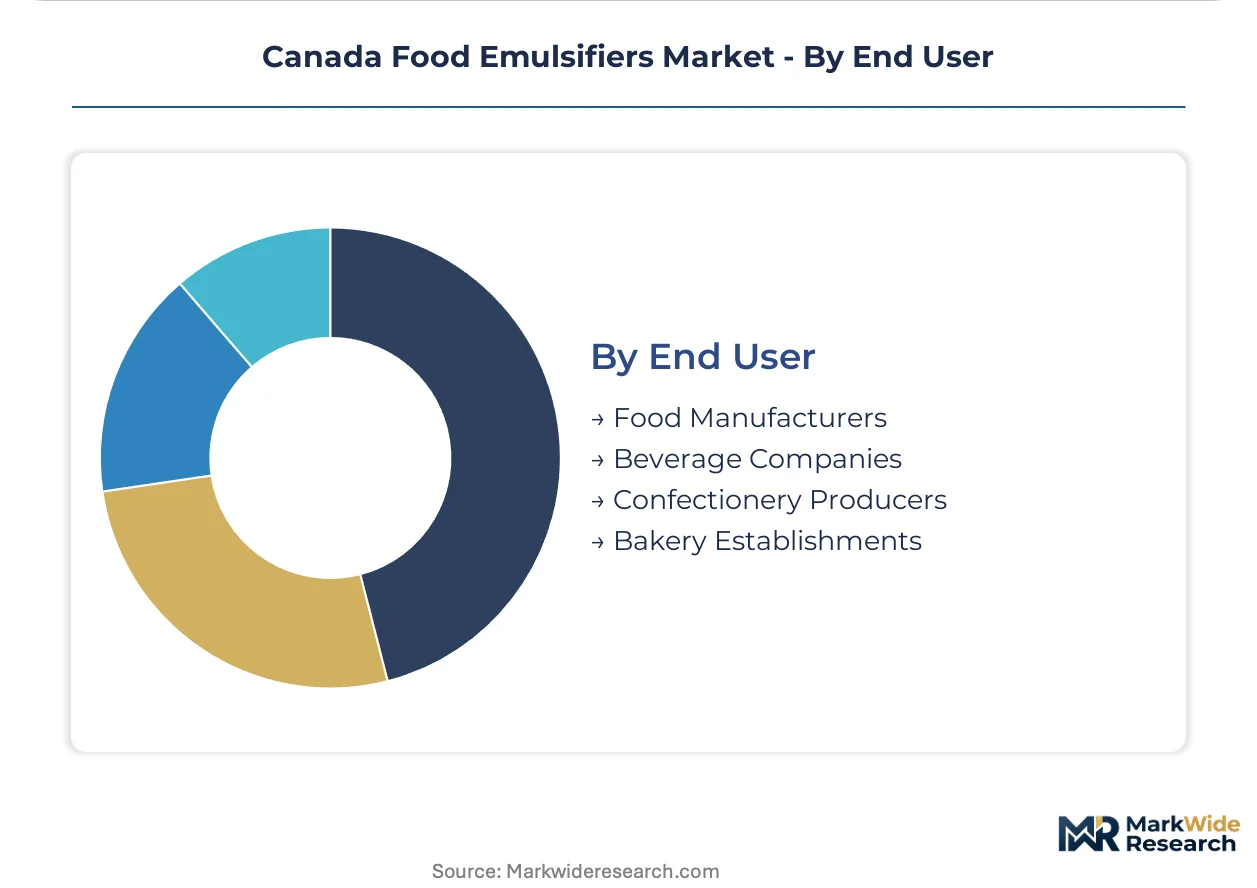
End User:
Customer type fragmentation separates national procurement headquarters from regional manufacturing autonomy across Canadian food production.
- Food Manufacturers:National headquarters in Toronto and Montreal mandate single-supplier emulsifier contracts with integrated technical service support. Category managers centralize specification authority, compressing regional distributor relevance.
- Beverage Companies:Oat and pea protein beverage processors in Ontario and Quebec specify certified organic lecithin systems to preempt consumer scrutiny on ingredient panels.
- Confectionery Producers:Fat bloom control and tempering stability requirements drive specialty ester procurement.
- Bakery Establishments:Smaller artisan operations retain limited regional sourcing flexibility outside consolidated procurement frameworks.
Procurement concentration centers on Food Manufacturers; reformulation velocity runs highest among Beverage Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Toronto Area anchors Canadian emulsifier procurement volume through its concentration of industrial bakeries and dairy alternative processors. Quebec's Montreal corridor generates parallel demand for plant-derived stabilizers in oat and pea protein beverage manufacturing. Provincial regulatory alignment with Health Canada's Safe Food for Canadians Regulations creates differentiated compliance burdens across sub-regional manufacturing clusters.
Ontario
Commercial bakeries in the Golden Horseshoe manufacturing belt specify emulsifier blends for par-baked distribution systems requiring extended shelf-life stability. Health Canada's preventive control plan mandates elevate documentation requirements for ingredient suppliers serving Toronto-headquartered food manufacturers. Category managers at national headquarters consolidate procurement authority, compressing regional distributor relevance across the province.
Quebec
Dairy alternative processors in Montreal and surrounding regions drive specification of certified organic sunflower lecithin for clean-label oat milk positioning. The CFIA's bilingual labeling requirements add compliance complexity for imported emulsifier sourcing from U.S. suppliers. Laval and Longueuil industrial zones concentrate precision fermentation startups requiring customized fat structuring systems for hybrid meat analogues.
Alberta
Canola crushing operations in the Edmonton-Calgary corridor supply phospholipid feedstock for domestic lecithin production serving western Canadian food processors. Prairie oilseed commodity price volatility compresses margin predictability for processors without backward integration into crushing infrastructure. Red Deer manufacturing clusters absorb lower-grade emulsifier streams for animal feed and technical applications.
British Columbia
Vancouver-based regulatory consultancies concentrate Health Canada submission preparation expertise for novel emulsifier technologies facing asynchronous approval timelines. Lower Mainland beverage processors import specialty sorbitan esters through Port Metro Vancouver, exposing operations to cross-border logistics friction and currency fluctuation. Victoria-area natural foods manufacturers specify premium plant-derived stabilizers for export-oriented organic product lines.
Prairie Provinces
Saskatchewan and Manitoba crushing capacity expansion offers domestic lecithin producers captive supply chain control over phospholipid raw material flows. Winnipeg and Regina food ingredient distributors serve as procurement intermediaries for mid-sized processors lacking direct supplier relationships. Regional regulatory science capabilities remain concentrated in Toronto and Vancouver consultancies, creating talent access bottlenecks for local ingredient firms.
Canada Food Emulsifiers Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and technical service integration depth. The Canadian food emulsifier market structures around three tiers: multinational ingredient technology platforms with North American manufacturing footprints, oilseed processors with backward-integrated phospholipid extraction capabilities, and regional distributors serving artisan-scale bakery and dairy operations. Strategic archetypes include clean-label specialists leveraging enzymatic modification processes, commodity lecithin suppliers anchored in prairie oilseed crushing infrastructure, and synthetic emulsifier developers targeting industrial bakery scale requirements. Dominant competitive moves encompass capacity expansion in Saskatchewan and Manitoba crushing operations and strategic partnerships between precision fermentation startups and customized emulsifier formulators.
Within the multinational platform tier, Kerry Group plc and BASF SE occupy positions differentiated by technical service integration depth and synthetic specialization respectively. Kerry Group plc represents the plant-derived lecithin application archetype through its North American ingredient technology infrastructure. BASF SE exemplifies synthetic emulsifier specialization for industrial-scale bakery applications requiring precise HLB value control. Cargill, Incorporated anchors the backward-integrated archetype through its oilseed processing footprint, though its specific Canadian manufacturing presence remains concentrated in commodity grain handling rather than emulsifier-specific production. These three entities collectively illustrate the competitive tension between label-friendly positioning and performance-optimized formulation across Canadian food manufacturing procurement.
| Leading Market Players |
|---|
| Corbion NV |
| BASF SE |
| Kerry Group plc |
| Caldic B.V. |
| Archer Daniels Midland Company |
| Bulk Barn Foods Limited |
| Botanic Planet |
| ADM |
| Cargill, Incorporated |
| Others |
Value Chain & Pricing Dynamics
National food manufacturing headquarters in Toronto and Montreal concentrate procurement authority into single-supplier contracts, compressing regional distributors and anchoring a contract-based long-term offtake model with integrated technical service premiums.
Pricing Analysis
Yield-optimized formulation performance anchors value-based pricing for enzymatically processed mono- and diglycerides in Ontario industrial bakeries. Three-tier pricing structure across premium enzymatic, standard chemical-grade, and economy bulk lecithin levels segments buyer tiers. Cost compression in commodity lecithin is intensifying because prairie oilseed commodity swings transmit directly into phospholipid feedstock costs. Small artisan bakery establishments exhibit highest price sensitivity, while national food manufacturers with consolidated procurement budgets absorb premium positioning for clean-label compliance.
Supply Chain Analysis
Cross-border freight exposure from U.S. and European specialty sorbitan ester suppliers elevates landed cost unpredictability for Canadian formulators. Domestic supply draws from prairie oilseed crushing in Saskatchewan and Manitoba, U.S. Midwest soy processing, and European specialty ester manufacturing. Raw material flows hinge on canola and soybean phospholipid streams, distilled glycerol feedstock, and sorbitol dehydration precursors. Single-source vulnerability concentrates in imported sorbitan esters and distilled monoglycerides flowing through Port Metro Vancouver. Distribution runs through national ingredient distributors with CFIA pre-qualification status serving Toronto and Montreal manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty emulsifier capacity constraints in enzymatic modification and Health Canada regulatory submission expertise prop pricing power for qualified suppliers across the analysis window.
For Market Incumbents: Extend backward integration into Saskatchewan and Manitoba oilseed crushing to secure captive phospholipid supply against prairie commodity volatility. Deepen technical service teams in Toronto and Montreal to defend contract renewals against emerging precision fermentation startups offering customized fat structuring systems for hybrid meat analogues. For New Entrants and Emerging Players: Enzymatic modification technology offers entry leverage into Quebec dairy alternative processors specifying certified organic sunflower lecithin. White-space concentrates in cell-cultured meat adjunct formulation partnerships with Laval and Longueuil precision fermentation startups. Go-to-market through CFIA export certification pathways targeting Asian equivalence agreements sidesteps incumbent procurement lock-in. For Investors and Strategic Acquirers: The window for entry favors mid-sized enzymatic processing specialists with Health Canada submission capabilities and established organic certification. Long-term viability centers on clean-label transition permanence and regulatory disclosure tightening. Watch Health Canada Food and Drug Regulations amendment timing on enhanced additive labeling as inflection signal for substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Prairie capacity expansion secures phospholipid supply chain control against commodity swings. |
| Enzymatic Processing Technology Investment | Health Canada disclosure mandates accelerate substitution from chemical glycerolysis routes. |
| CFIA Export Certification Qualification | Asian equivalence agreements unlock regulatory pathway advantages for domestic suppliers. |
| Precision Fermentation Partnership Formation | Hybrid meat analogue startups require customized fat structuring emulsifier systems. |
| Technical Service Team Expansion | Toronto and Montreal procurement centralization demands integrated formulation support. |
Study Parameters
Health Canada regulatory filings, CFIA enforcement guidance documents, and prairie oilseed trade statistics formed the secondary backbone for this study. Primary interviews with ingredient procurement managers at national food manufacturers, regulatory affairs consultants in Toronto and Vancouver, crushing facility operations directors, and precision fermentation startup technical leads validated supply-side constraints. Bottom-up volume estimates from application-level consumption patterns and top-down value reconciliation through producer revenue analysis enabled triangulation.
Bottom-up modeling segmented consumption by product type chemistry, application end-use, grade certification tier, and provincial manufacturing cluster. CAGRs derived from weighted average of historical trajectory elasticity and projected clean-label substitution rates across the projection horizon. Forecast inputs incorporated Health Canada regulatory amendment probability, prairie crushing capacity expansion timelines, and precision fermentation commercialization pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under asynchronous Health Canada approval timelines for novel emulsifier technologies and severe prairie drought impacting oilseed yields. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
India Food Enzymes Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market