
 Food Grade Potassium Sorbate Market | 2026-2036
Food Grade Potassium Sorbate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Potassium Sorbate Market Insights
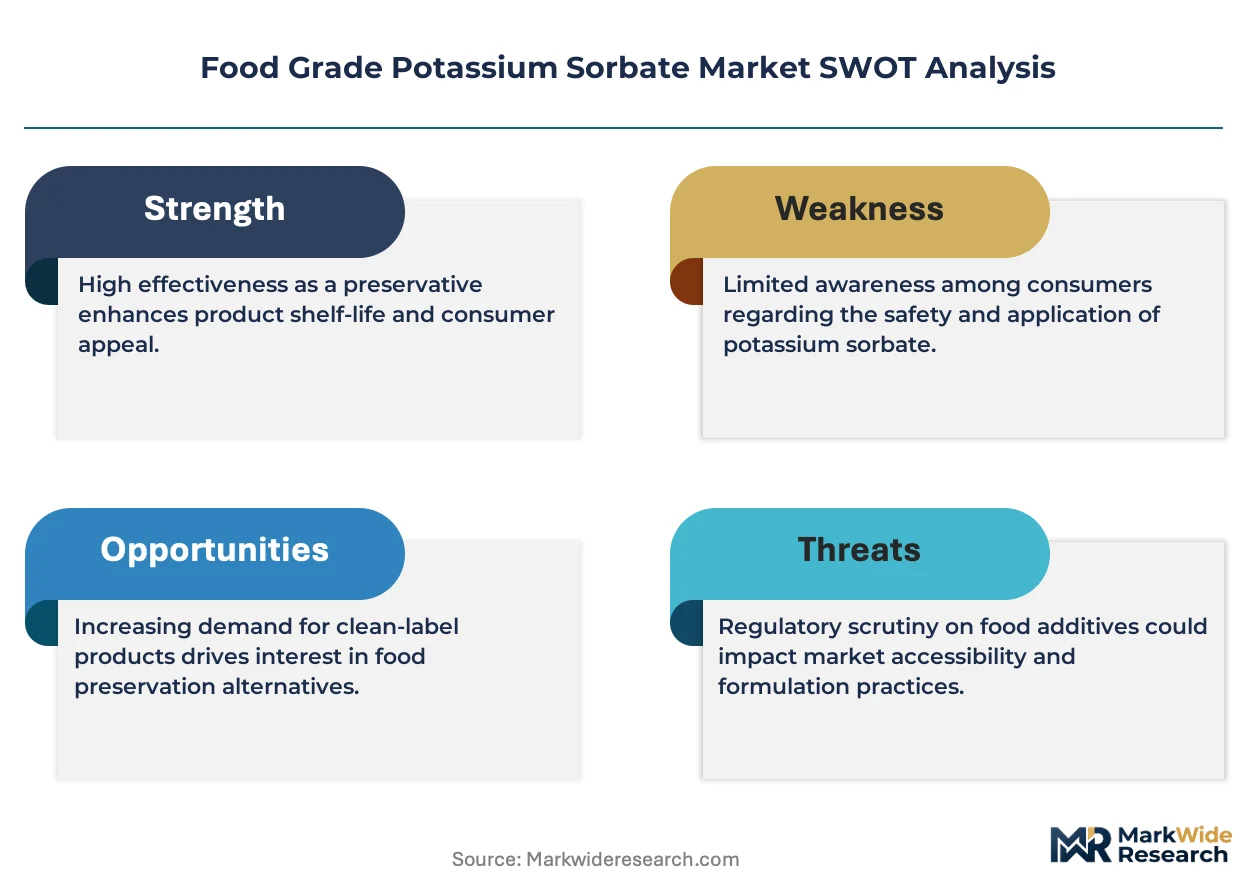
REACH compliance in Europe is repositioning the cost-of-entry calculus for potassium sorbate suppliers seeking EU market access. Nantong Alchemy Biotech Development Co., Ltd. leverages its integrated acetic acid supply chain to control input costs across powder and granule grades. Celanese Corporation sustains a technology leadership position in high-purity liquid formulations for beverage applications. Hawkins, Inc. anchors North American distribution through direct sales channels to mid-sized dairy processors.
Food grade potassium sorbate (C6H7KO2) is the potassium salt of sorbic acid, manufactured industrially through neutralization of sorbic acid with potassium hydroxide to yield a white crystalline powder with minimum assay of 98% and maximum moisture content of 1%. It functions primarily as a mold and yeast inhibitor in acidic food systems with effective pH range of 2.5–6.5, extending shelf life without altering sensory profiles. Powder formulations dominate current volume owing to handling efficiency and lower shipping costs, while liquid concentrates represent the fastest-expanding category as beverage manufacturers automate dosing systems. Dairy applications command premium positioning due to stringent microbiological standards, whereas bakery segment margins compress amid commodity pricing pressure.
The FDA's GRAS notification program and the EPA's chemical substance inventory requirements govern US market access, while REACH registration and EFSA purity specifications dictate European commercialization pathways. China's GB 1886.39 food additive standard and SAMR production licensing enforce domestic quality floors that increasingly influence export benchmarks. Stakeholders must monitor evolving clean-label certification schemes and regional maximum-permitted-level adjustments as primary determinants of formulation strategy and geographic prioritization.
Market Dynamics
Clean-label reformulation pressure from beverage and dairy processors is restructuring potassium sorbate demand toward high-purity liquid concentrates and certified-organic-compatible grades.
Growth Catalysts
- REACH registration tiering:ECHA's updated substance evaluation protocols are accelerating compliance investment among Asian exporters seeking EU market stability.
- Acetic acid supply chain control:Integrated producers with captive ketene-based sorbic acid capacity capture margin expansion as feedstock volatility compresses merchant suppliers.
- RTD beverage automation:Inline dosing systems at Coca-Cola and PepsiCo bottling facilities favor liquid potassium sorbate over powder handling.
Market Restraints
- Crotonaldehyde cost volatility:Crude oil-linked feedstock pricing for sorbic acid precursors squeezes toll manufacturers without long-term ketene supply agreements.
- Jiangsu production concentration:Nantong chemical parks account for disproportionate global powder capacity, creating single-point disruption exposure.
- Benzoate substitution in high-pH applications:Sodium benzoate retains cost advantage above pH 5.5, limiting potassium sorbate penetration in neutral sauces and dressings.
Strategic Opportunities
- Southeast Asian dairy expansion:Vietnam and Indonesia's chilled yogurt segments lack mature preservation supply chains, opening first-mover positioning for compliant exporters.
- Plant-based meat shelf-life extension:Mycoprotein and pea-protein analogs require mold inhibition in high-moisture matrices where potassium sorbate outperforms chemical alternatives.
- EU Green Deal chemical sustainability certification:Mass-balance audited production lines command premium placement in Nordic retail private-label programs.
Industry Challenges
- Food safety auditor specialization:BRCGS and FSSC 22000 certification for preservative additives requires scarce toxicology and regulatory affairs talent.
- Legacy powder-to-liquid line conversion:Midwest US dairy processors face eight-figure capex thresholds to retrofit spray-dry handling for automated liquid dosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Potassium Sorbate Market |
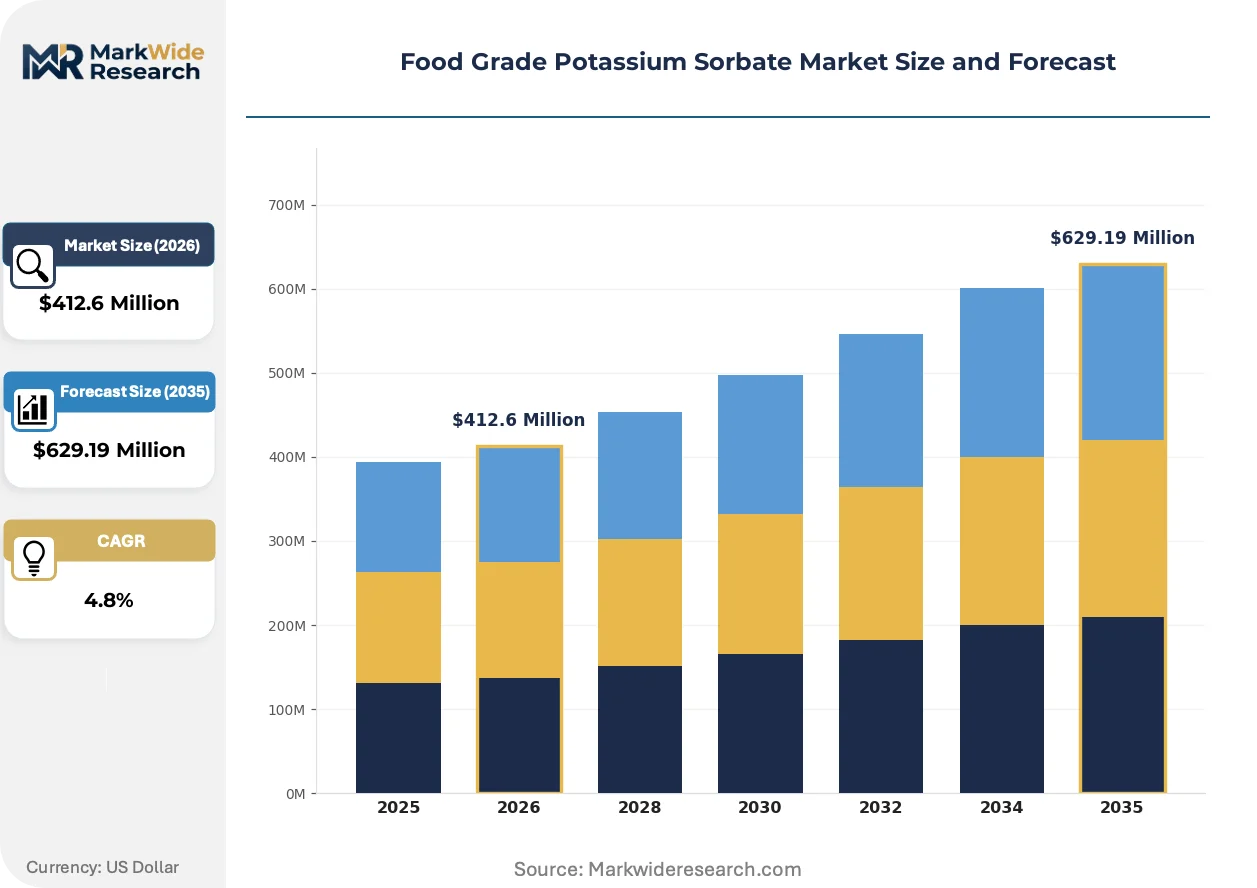
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Crystals Application: Beverages, Dairy, Bakery, Sauces End User: Food Industry, Beverage Manufacturers, Pharmaceuticals, Personal Care Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Hawkins, Inc., Nantong Alchemy Biotech Development Co., Ltd., Celanese Corporation, McCormick & Company, Inc., The Lubrizol Corporation, Archer Daniels Midland Company, Nantong Acetic Acid Chemical Co., Ltd., Shanghai Tianjia Biochemical Co., Ltd., FBC Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Potassium Sorbate Market Trends and Innovations
Encapsulation and controlled-release technologies are redrawing competitive boundaries between commodity suppliers and specialty formulation houses.
Microencapsulated potassium sorbate using modified starch or lipid matrices is unifying extended-release functionality with clean-label positioning. Bakery manufacturers in France and Germany adopt these grades to delay mold onset without surface residue. The technology is unifying what were separate preservation and sensory-performance purchasing decisions into single-source contracts.
EFSA's 2023 re-evaluation of sorbic acid ADI levels triggered reformulation audits across EU confectionery and soft drink categories. Manufacturers operating near previous maximum permitted levels face label adjustments or dose reductions. German and Dutch processors are responding by blending potassium sorbate with cultured dextrose or fermentation-derived alternatives to maintain efficacy within tightened regulatory ceilings.
Direct procurement from Nantong and Shanghai producers is displacing traditional distributor intermediaries among North American mid-sized sauce manufacturers. Buyers with in-house regulatory affairs capabilities now manage SAMR export documentation and FDA FSVP compliance internally, compressing landed costs. This pattern is most visible in California and Texas specialty food clusters where technical purchasing teams have expanded to handle Asian supplier qualification directly.
Food Grade Potassium Sorbate Market Segmentation
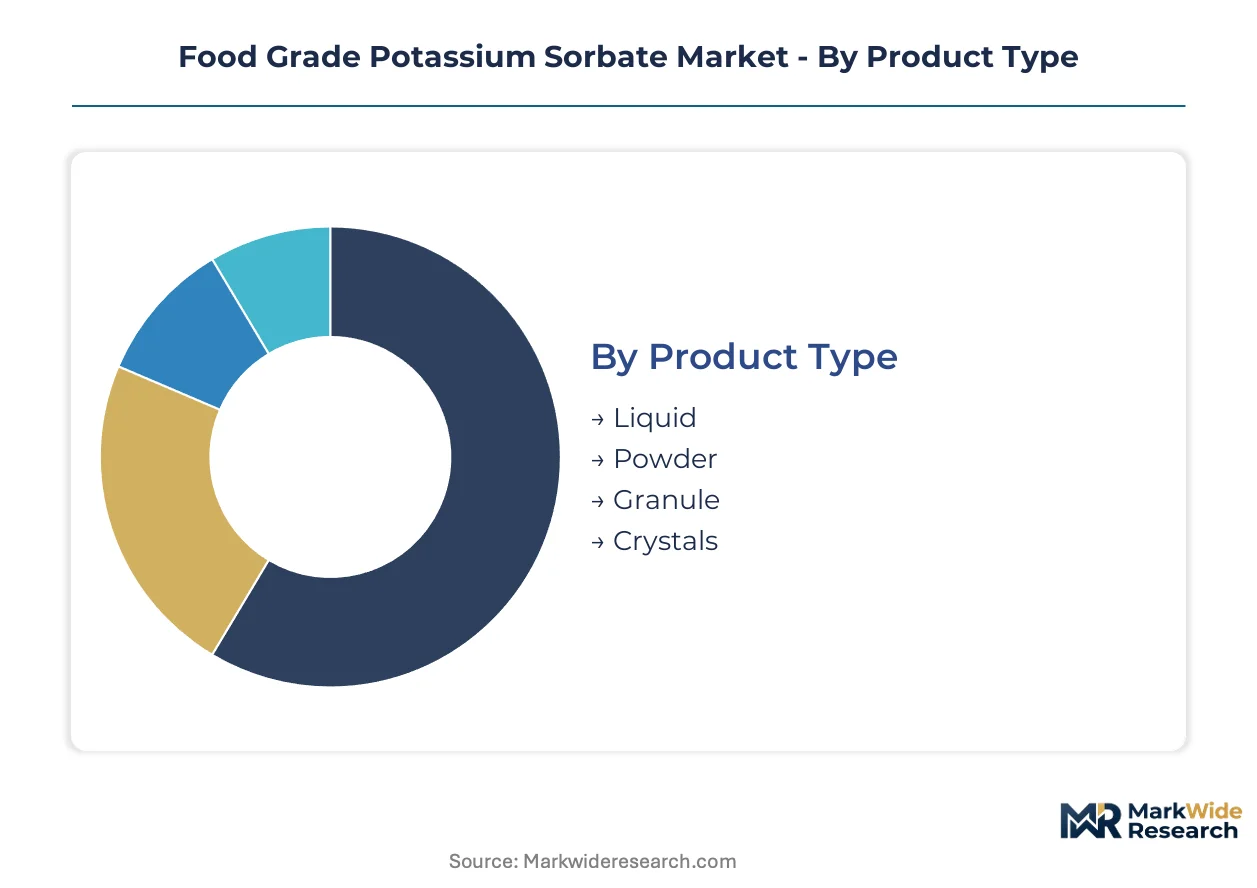
Potassium sorbate segmentation reflects divergent handling economics, automation readiness, and regulatory compliance burdens across food manufacturing verticals. Form factor selection directly determines dosing precision, shipping costs, and clean-label positioning in reformulation strategies.
Product Type:
Specification tiers differentiate across solubility profiles, bulk density, and automated system compatibility.
- Liquid:Pre-dissolved aqueous concentrates with standardized assay of 50% enable inline metering at Coca-Cola and PepsiCo bottling facilities. RTD beverage automation in Texas and California drives procurement volume as manufacturers eliminate powder handling infrastructure.
- Powder:White crystalline material with 98% minimum assay dominates current volume through lower shipping costs and extended ambient stability. Nantong and Shanghai producers anchor global export supply, though Jiangsu concentration creates single-point disruption exposure.
- Granule:Free-flowing agglomerated particles reduce dust generation during bulk transfer operations. Midwest US dairy processors favor this grade for silo-fed spray-dry systems.
- Crystals:Large-particle morphologies suit laboratory-scale compounding and pharmaceutical-grade applications where dissolution kinetics require controlled release.
Powder leads on scale; liquid leads on momentum.
Application:
End-use differentiation tracks pH tolerance, microbiological standards, and margin compression exposure.
- Beverages:Acidic soft drinks and functional waters with pH 2.5–4.5 maximize potassium sorbate efficacy against yeast and mold. German and Dutch processors blend with cultured dextrose to maintain efficacy within EFSA's tightened ADI ceilings.
- Dairy:Chilled yogurt and cheese applications command premium positioning due to stringent microbiological standards. Vietnam and Indonesia's expanding chilled segments lack mature preservation supply chains.
- Bakery:High-moisture cakes and breads face commodity pricing pressure. French and German manufacturers adopt microencapsulated grades to delay mold onset without surface residue.
- Sauces:Neutral pH dressings above 5.5 limit penetration where sodium benzoate retains cost advantage. California and Texas specialty sauce clusters increasingly procure direct from Asian producers.
Beverages lead on volume velocity; dairy leads on margin retention.
End User:
Customer archetypes separate across technical capability, regulatory sophistication, and volume scale.
- Food Industry:Broad-category processors spanning bakery, confectionery, and prepared meals represent the deepest volume base. BRCGS and FSSC 22000 certification requirements concentrate procurement among qualified additive suppliers.
- Beverage Manufacturers:Consolidated bottlers with automated dosing infrastructure drive liquid concentrate specification. Technical purchasing teams manage FDA FSVP compliance internally.
- Pharmaceuticals:USP-grade requirements for oral dosage forms command purity premiums and dedicated batch documentation.
- Personal Care:Cosmetic preservation applications in creams and lotions utilize lower-assay grades with less stringent heavy metal specifications.
Food industry leads on aggregate tonnage; beverage manufacturers lead on formulation innovation.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and landed cost optimization.
- Direct Sales:Hawkins, Inc. anchors North American supply through technical field service to mid-sized dairy processors. SAMR export documentation and FDA compliance support justify relationship premiums.
- Wholesale:Regional chemical distributors aggregate fragmented demand from small bakeries and sauce manufacturers. Inventory pooling reduces working capital burdens.
- Online:Alibaba and specialty chemical marketplaces enable sample procurement and spot purchasing for R&D formulations. Quality verification remains buyer-managed.
- Retail:Packaged consumer quantities through industrial supply stores serve artisan food producers and institutional kitchens with minimal volume requirements.
Direct sales leads on value capture; wholesale leads on reach density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Potassium sorbate manufacturing first achieved industrial scale in Germany during the 1950s as sorbic acid synthesis matured. Production subsequently migrated to Asia-Pacific feedstock centers. Today, regulatory divergence and automation readiness separate regional demand patterns.
United States
RTD beverage automation at Coca-Cola and PepsiCo bottling facilities drives liquid concentrate procurement. FDA GRAS notification protocols govern market access with updated review timelines affecting compliance costs. Midwest dairy processors in Wisconsin and Minnesota anchor powder demand for yogurt and cheese applications.
China
Nantong and Shanghai chemical parks control disproportionate global powder capacity through integrated acetic acid supply chains. SAMR production licensing and GB 1886.39 standards enforce quality floors that increasingly shape export benchmarks. Jiangsu province concentration creates single-point disruption exposure for international buyers.
Germany
Bakery manufacturers adopt microencapsulated grades to delay mold onset without surface residue. EFSA's 2023 ADI re-evaluation triggered reformulation audits across confectionery and soft drink categories. The Rhine-Ruhr industrial corridor hosts specialized distributors serving EU-wide preservative demand.
Vietnam
Expanding chilled yogurt segments lack mature preservation supply chains, opening first-mover positioning for compliant exporters. The country's national food safety regulator enforces evolving additive maximum permitted levels. Ho Chi Minh City-based dairy processors represent the fastest-growing import demand node in Southeast Asia.
Indonesia
Mycoprotein and pea-protein analogs require mold inhibition in high-moisture matrices where potassium sorbate outperforms alternatives. The national food and drug agency monitors preservative imports with tightening documentation requirements. Jakarta-Bandung manufacturing clusters concentrate plant-based meat formulation activity.
Food Grade Potassium Sorbate Market Competitive Landscape
The competitive structure tilts toward integrated chemical producers with captive feedstock positions. Merchant suppliers without long-term ketene supply agreements face margin compression from crude oil-linked crotonaldehyde volatility. Three archetypes dominate: integrated acetic acid-sorbic acid producers, high-purity liquid formulation specialists, and North American distribution anchors with technical field service capabilities. Capacity expansion and direct procurement channel development represent the dominant competitive moves.
Among integrated Chinese producers, Nantong Alchemy Biotech Development Co., Ltd. and Nantong Acetic Acid Chemical Co., Ltd. exemplify the feedstock-control archetype through their Jiangsu basin positioning. Celanese Corporation occupies a position on the high-purity liquid formulation vector. Hawkins, Inc. anchors North American distribution reach through direct technical sales to mid-sized dairy processors. Shanghai Tianjia Biochemical Co., Ltd. sits within the export-oriented powder specialist tier.
| Leading Market Players |
|---|
| Hawkins, Inc. |
| Nantong Alchemy Biotech Development Co., Ltd. |
| Celanese Corporation |
| McCormick & Company, Inc. |
| The Lubrizol Corporation |
| Archer Daniels Midland Company |
| Nantong Acetic Acid Chemical Co., Ltd. |
| Shanghai Tianjia Biochemical Co., Ltd. |
| FBC Industries, Inc. |
| Others |
Pricing and Supply Chain Analysis
Mid-sized dairy processors in Wisconsin and Minnesota anchor North American powder demand through contract-based procurement that favors volume-scaled pricing over spot-market flexibility. Their silo-fed spray-dry infrastructure locks in multi-year supply agreements with distributors like Hawkins, Inc., compressing price discovery for smaller sauce manufacturers competing for residual powder tonnage.
Pricing Analysis
Three-tier pricing structure across high-purity liquid, standard powder, and economy granule grades separates beverage automation leaders from commodity bakery buyers. Price differentiation hinges on certification tier—BRCGS and FSSC 22000 compliance commands premium placement—and captive ketene supply integration that buffers integrated producers from crotonaldehyde volatility. Cost compression in standard powder grades is intensifying as Nantong exporters absorb REACH registration burdens. Beverage manufacturers with automated dosing systems show least price sensitivity; artisan bakeries face acute margin pressure from minimum order thresholds.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu province chemical parks, where Nantong and Shanghai producers control disproportionate global powder capacity. Raw material flows draw from acetic acid feedstocks, potassium hydroxide neutralization agents, and ketene-based sorbic acid precursors. Tariff exposure runs through US-China customs classifications for food additive imports. Distribution runs through direct technical sales to large dairy processors, regional chemical distributors for fragmented bakery demand, and Alibaba-enabled spot purchasing for R&D sampling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU REACH compliance costs in Nantong diverge sharply from domestic Chinese production economics, creating margin capture opportunities for exporters with in-house regulatory affairs capabilities.
For Market Incumbents: Deepen captive ketene supply integration to defend against crotonaldehyde cost volatility that squeezes toll manufacturers without long-term feedstock agreements. Expand high-purity liquid formulation capacity in Texas and California to capture RTD beverage automation demand from Coca-Cola and PepsiCo bottling facilities. Prioritize BRCGS certification maintenance as auditor scarcity concentrates procurement power among qualified suppliers. For New Entrants and Emerging Players: E-commerce marketplaces like Alibaba and specialty chemical platforms enable direct qualification with California and Texas sauce manufacturers bypassing traditional distributor markups. Target Vietnam's chilled yogurt segment, where import demand outpaces mature preservation supply chain development. Lead with SAMR export documentation expertise and FDA FSVP compliance support to differentiate from commodity Nantong exporters. For Investors and Strategic Acquirers: Food-grade chemical distributors with technical field service capabilities are the most active acquirer in this space, seeking additive specialists to deepen dairy and beverage vertical penetration. The viable acquisition window spans integrated acetic acid-sorbic acid producers and microencapsulation technology holders. Watch EFSA maximum-permitted-level adjustments as the signal for reformulation-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ketene Supply | Captive crotonaldehyde sourcing insulates margins from oil-linked feedstock volatility. |
| Liquid Concentrate Capacity Expansion | Automated dosing adoption at Coca-Cola and PepsiCo bottlers favors pre-dissolved aqueous formulations. |
| Microencapsulation Technology Acquisition | French and German bakery demand for modified starch matrices unifies preservation with clean-label positioning. |
| REACH Registration Tiering Investment | ECHA substance evaluation protocols reposition EU market access costs for Asian exporters. |
| Southeast Asian Distribution Partnership | Vietnam and Indonesia dairy expansion lacks mature preservation supply chains. |
Research Methodology
Direct dialogue with plant managers at Nantong chemical parks, procurement leads at Midwest dairy processors, distribution channel partners, and technical R&D directors at encapsulation specialists grounded the qualitative foundation. Secondary validation drew from Chinese customs export data, FDA GRAS notification filings, EFSA re-evaluation documentation, and SEC 10-K disclosures from listed chemical producers. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across Jiangsu province facilities.
Segment-level outputs across powder, liquid, granule, and crystal formulations tracked application-specific demand from beverages, dairy, bakery, and sauces through the projection horizon. Modeled dimensions included grade tier, end-use industry vertical, packaging format, and regional production hub clustering. CAGRs were derived from regression analysis of historical price-volume relationships and forward assumptions about automation adoption rates and regulatory compliance cost trajectories. Forecast inputs incorporated EFSA ADI ceiling adjustments and SAMR licensing enforcement trends as demand-modifying variables.
The model assumes a particular technology adoption path; alternative pathways for microencapsulated delivery systems would alter the outlook if bakery manufacturers accelerate surface-residue-free formulation transitions. Forecasts reflect assumptions about REACH registration completion rates and crude oil-crotonaldehyde price linkage persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Oxygen Absorbers Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Global Organic Food Preservatives Market