
 France Food Additives Market | 2026-2036
France Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Additives Market Foresight
Clean-label certification services is rebalancing what processors pay for, shifting value from commodity ingredients toward compliance-backed ingredient systems. Kerry Group plc leverages its European formulation centers to anchor premium positioning in enzymatic solutions. Tate & Lyle PLC specializes in plant-derived sweetener portfolios that navigate France's sugar reduction mandates. Corbion NV dominates natural preservation through its lactic acid bacteria platforms, extending shelf-life claims without synthetic labeling.
France food additives encompass substances added to food during processing to preserve quality, enhance sensory attributes, or improve nutritional profiles, including emulsifiers with specific hydrophilic-lipophilic balance values and preservatives with defined maximum permitted concentrations under EU 1333/2008. Their primary commercial purpose centers on enabling industrial-scale food production while meeting shelf stability and consumer acceptability thresholds. Sweeteners and emulsifiers command concentrated margin pools as beverage and dairy reformulations accelerate. Colorants face structural pressure from botanical extract substitution, while flavor enhancers occupy stable demand in savory processing applications.
ANSES conducts risk assessments that determine additive authorization timelines, while EFSA establishes acceptable daily intake thresholds that directly constrain formulation ceilings for French manufacturers. The EU Green Deal's chemical sustainability targets are forcing ingredient suppliers to demonstrate biodegradability and reduced environmental impact across additive life cycles. REACH compliance costs are filtering smaller importers from the French supply base, consolidating procurement relationships around established multinationals. Stakeholders must monitor the EU's pending revision of food improvement agent categories, as reclassification would reshape labeling obligations and consumer perception thresholds across retail channels.
Market Dynamics
Clean-label mandates from ANSES and the EU Green Deal are compressing formulation timelines while forcing ingredient suppliers to rebuild portfolios around botanical and fermentation-derived alternatives. This regulatory pressure is restructuring procurement relationships and accelerating consolidation among French food processors.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Biodegradability requirements are pulling investment into enzymatic and fermentation-based additive platforms. French dairy and beverage manufacturers are prioritizing suppliers with verified life-cycle assessments.
- Paris-Lyon manufacturing corridor concentration:Proximity to formulation R&D centers reduces logistics costs and enables just-in-time additive delivery for industrial bakeries. Regional clustering accelerates technical service response times.
- Sugar reduction mandates:Reformulation pressures in beverages and confectionery are expanding volume demand for plant-derived sweeteners and taste-modulating solutions that mask off-notes from reduced sugar content.
Market Restraints
- ANSES authorization timelines:Novel additive approvals face extended toxicological review periods that delay commercialization by 18-36 months. Uncertainty around EFSA acceptable daily intake revisions constrains long-term formulation planning.
- Raw material volatility:Botanical extract supply depends on agricultural harvest cycles and climate variability in Mediterranean sourcing regions. Price swings in natural colorant feedstocks compress margins for clean-label product lines.
- REACH compliance cost concentration:Registration and data-sharing requirements filter smaller importers from the French market. Procurement relationships consolidate around established multinationals with dedicated regulatory affairs capabilities.
Strategic Opportunities
- Auvergne-Rhône-Alpes specialty ingredient cluster:Underpenetrated natural preservation demand from regional cheese and charcuterie processors offers white space for lactic acid bacteria platforms with proven shelf-life extension claims.
- Clean-label certification services:Third-party verification of additive-free or minimal-processing claims creates recurring revenue streams. French retailers are mandating independent certification for private-label positioning.
- Fermentation technology convergence:Precision fermentation for high-value flavor precursors and alternative proteins is opening adjacent additive applications. Bioprocess expertise from pharmaceutical manufacturing transfers to food-grade production.
Industry Challenges
- Formulation chemist scarcity:Talent pipelines for clean-label reformulation expertise lag behind demand. French technical universities produce fewer graduates with combined food science and regulatory knowledge.
- Legacy equipment retrofit costs:Switching from synthetic to natural preservatives often requires modified processing temperatures and pH controls. Capital expenditure for line adjustments strains mid-tier processors.
- Consumer perception management:E-number labeling stigma persists despite natural additive functional equivalence. Communication strategies must navigate ANSES transparency requirements without triggering rejection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Additives Market |
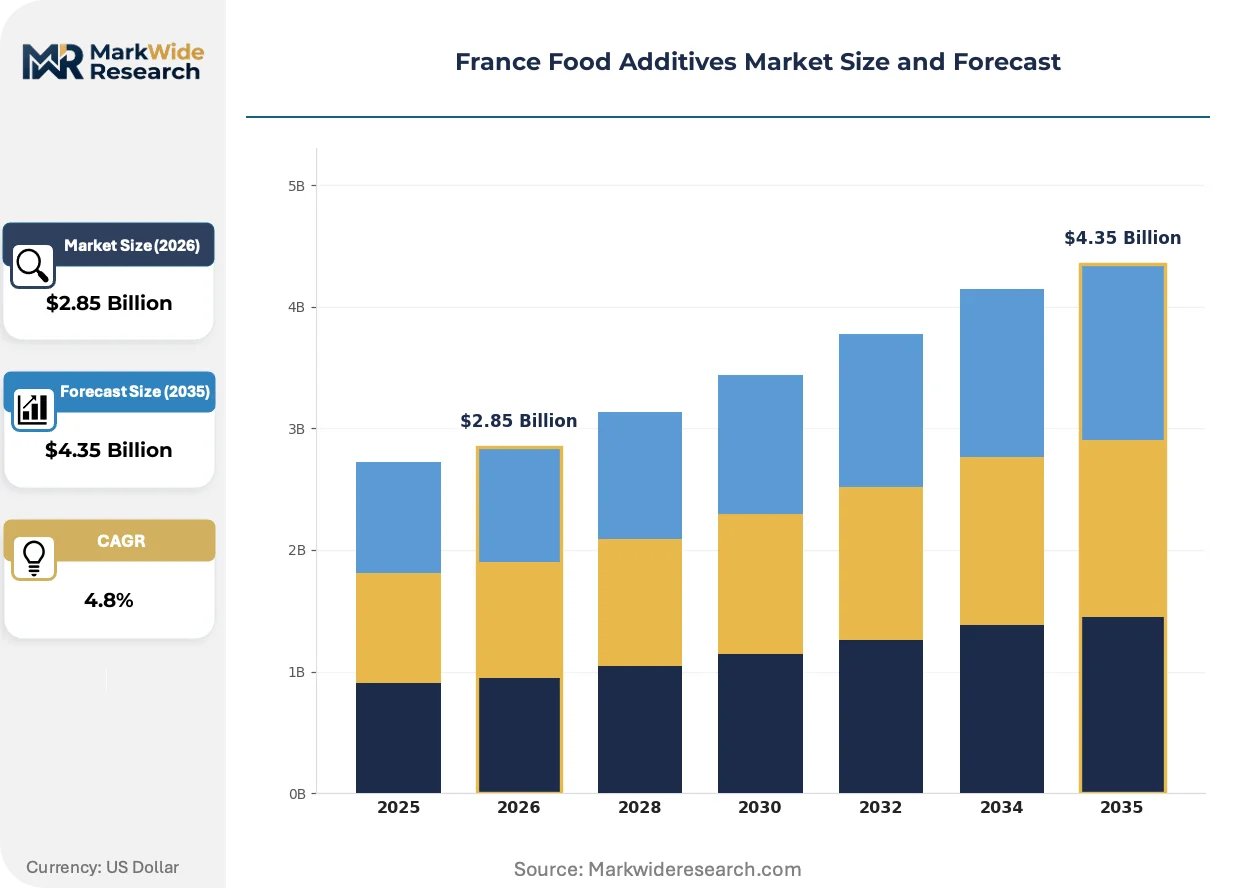
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.35 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Sweeteners, Emulsifiers, Colorants, Flavor Enhancers Application: Baked Goods, Dairy Products, Beverages, Confectionery, Meat Processing, Snacks Form: Powder, Liquid, Granules, Crystals, Gel End User: Food Manufacturers, Beverage Producers, Catering Services, Food Packaging Companies |
| Companies Covered | Kerry Group plc, Archer Daniels Midland Company, BASF SE, Corbion NV, Tate & Lyle PLC, Cargill, Incorporated, Ingredion Incorporated, DSM, DuPont de Nemours, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Additives Market Shifts & Advancements
Enzymatic processing platforms and precision fermentation are displacing conventional chemical synthesis across multiple additive categories. These biotechnologies enable label-friendly claims while maintaining industrial performance thresholds that French manufacturers require.
Enzymatic solutions for texture modification and shelf-life extension are decentralizing additive production from centralized chemical plants toward distributed bioreactor facilities. Artisan and mid-scale French bakeries are adopting on-site enzyme activation systems that reduce dependency on pre-blended ingredient supplies. This distributed model compresses logistics costs and enables real-time formulation adjustments based on flour batch variability.
ANSES is tightening maximum permitted concentration thresholds for synthetic preservatives under revised EU 1333/2008 implementation guidelines. French sauce and ready-meal manufacturers face reformulation deadlines that accelerate substitution toward cultured dextrose and fermented wheat flour derivatives. Smaller processors in the Nord-Pas-de-Calais region report compliance timeline pressure due to limited technical service access.
Direct procurement relationships between food manufacturers and biotechnology suppliers are bypassing traditional ingredient distributors. Large French dairy cooperatives now contract directly with fermentation technology providers for customized starter culture development. This disintermediation concentrates in the Brittany dairy processing corridor where volume scale justifies dedicated supply arrangements and technical collaboration agreements.
France Food Additives Market Segmentation
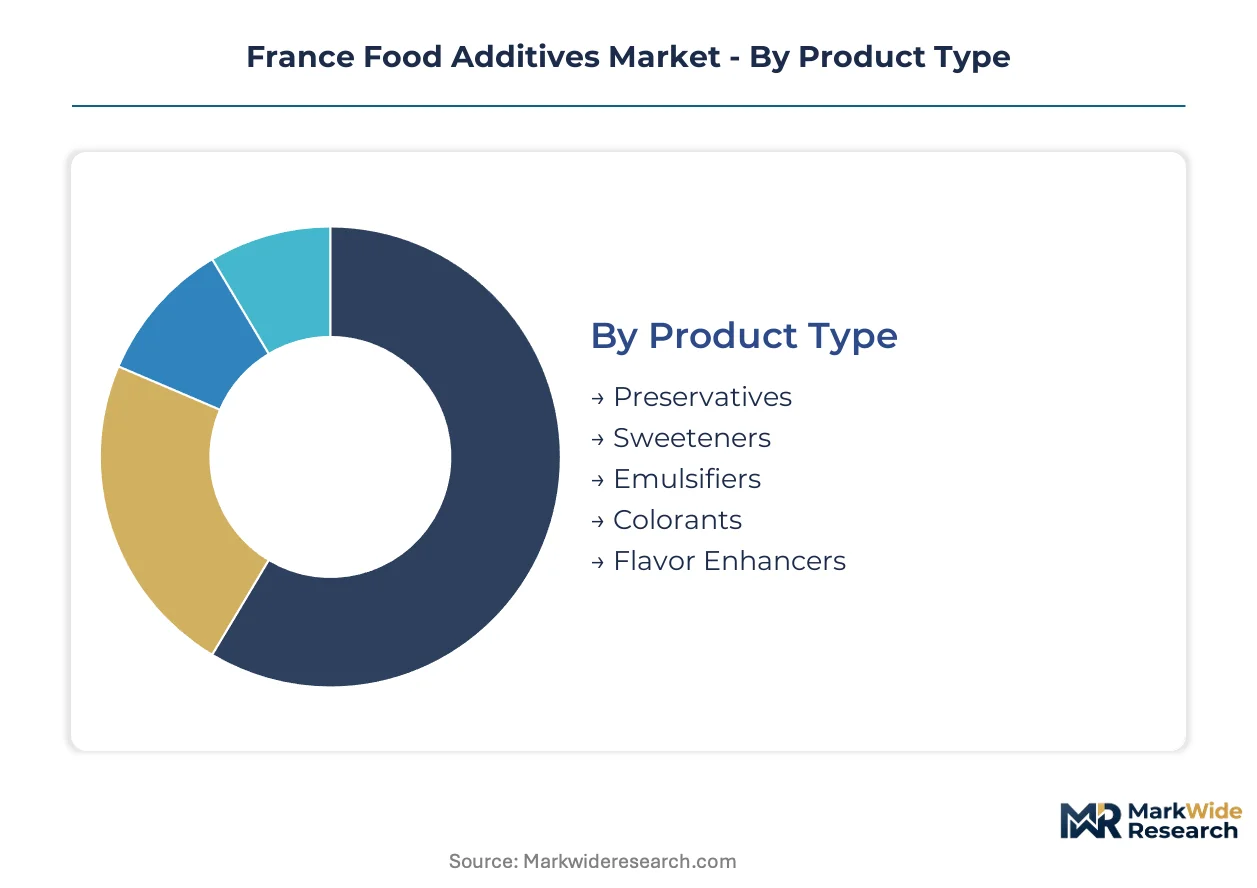
Segmentation in the France food additives market reveals how procurement priorities diverge between industrial-scale processors and specialty food producers. Clean-label mandates from ANSES and the EU Green Deal are compressing traditional category boundaries as reformulation requirements reshape ingredient specifications across every segment.
Product Type:
Buyers prioritize functional equivalence under tightened maximum permitted concentration thresholds, forcing suppliers to demonstrate performance parity between synthetic and natural alternatives.
- Preservatives:Synthetic variants face downward pressure from ANSES maximum permitted concentration revisions under EU 1333/2008. Natural alternatives derived from cultured dextrose and fermented wheat flour gain traction among sauce and ready-meal manufacturers facing reformulation deadlines.
- Sweeteners:Plant-derived portfolios navigate France's sugar reduction mandates through taste-modulating solutions that mask off-notes. Beverage and confectionery reformulations are expanding procurement volumes for stevia and monk fruit extracts with verified glycemic impact profiles.
- Emulsifiers:Specific hydrophilic-lipophilic balance values enable texture stability in dairy and bakery applications. Hydrophilic-lipophilic balance precision determines supplier selection for industrial-scale margarine and ice cream production.
- Colorants:Botanical extract substitution is displacing synthetic alternatives as E-number labeling stigma persists. Mediterranean agricultural harvest variability creates feedstock price instability for carotenoid and anthocyanin sourcing.
- Flavor Enhancers:Stable demand occupies savory processing applications where umami intensity requirements resist clean-label substitution. Yeast extract and hydrolyzed vegetable protein maintain formulation presence despite sodium reduction pressures.
Volume sits with emulsifiers and preservatives; growth tilts toward plant-derived sweeteners.
Application:
End-use concentration in the Paris-Lyon manufacturing corridor determines logistics cost structures and technical service accessibility for additive suppliers.
- Baked Goods:Enzymatic texture modification platforms enable clean-label claims while maintaining industrial performance. Artisan and mid-scale bakeries adopt on-site enzyme activation systems reducing dependency on pre-blended supplies.
- Dairy Products:Brittany processing cooperatives contract directly with fermentation technology providers for customized starter cultures. Direct procurement bypasses traditional distributors and concentrates supply relationships around dedicated technical collaboration agreements.
- Beverages:Sugar reduction mandates accelerate reformulation timelines for carbonated and functional drink categories. Plant-derived sweetener integration requires pH stability testing under accelerated shelf-life protocols.
- Confectionery:Colorant substitution pressure is most acute in children's product lines where parental purchasing decisions reject E-number labeling. Natural colorant light stability challenges constrain packaging transparency specifications.
- Meat Processing:Auvergne-Rhône-Alpes charcuterie processors represent underpenetrated demand for lactic acid bacteria preservation platforms. Regional specialty production scales justify customized shelf-life extension formulations.
- Snacks:Fried and extruded categories balance acrylamide mitigation requirements with clean-label antioxidant sourcing. Rosemary extract and tocopherol blends compete on cost-performance metrics against synthetic alternatives.
Dairy and baked goods anchor current procurement volumes; beverage reformulation climbs the fastest.
Form:
Processing equipment compatibility and dissolution kinetics drive form selection, with legacy line configurations constraining rapid format switching.
- Powder:Dominates high-volume emulsifier and preservative distribution with extended stability under ambient storage. Dust containment requirements influence handling infrastructure investment for industrial bakeries.
- Liquid:Preferred for beverage and sauce applications where homogeneous dispersion eliminates hydration time. Concentrated liquid enzymes enable precise dosing control in continuous processing lines.
- Granules:Intermediate dissolution characteristics suit dry mix applications where controlled release improves manufacturing flexibility. Flowability specifications determine packaging and conveying system compatibility.
- Crystals:High-purity sweetener formats meet exacting dissolution clarity standards for premium beverage positioning. Crystal size distribution affects mouthfeel perception in reduced-sugar formulations.
- Gel:Specialized hydrocolloid matrices enable water-binding and texture modification in meat and dairy analogs. Gel strength specifications differentiate supplier offerings for plant-based product development.
Powder and liquid formats capture established volume; gel applications gain share fastest in alternative protein development.
End User:
Scale determines regulatory affairs capability, with REACH compliance costs filtering smaller participants toward distributor-dependent procurement models.
- Food Manufacturers:Large processors maintain dedicated formulation teams capable of navigating ANSES authorization timelines. Direct supplier relationships enable customized additive development for proprietary product lines.
- Beverage Producers:Sugar reduction mandates concentrate reformulation investment in this segment. Technical service demands for taste modulation solutions exceed commodity ingredient support requirements.
- Catering Services:Smaller scale limits in-house regulatory expertise, driving preference for pre-certified clean-label ingredient systems. Third-party certification requirements from French retailers shape procurement specifications.
- Food Packaging Companies:Active packaging additive integration represents emerging demand for shelf-life extension without direct food contact. Oxygen scavenger and moisture control technologies blur traditional additive category boundaries.
Food manufacturers dominate procurement scale; beverage producers show steepest expansion trajectory for reformulation-driven additive demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France produces specialty additives for export while consuming bulk formulations from neighboring EU states. Domestic manufacturing concentrates in enzyme and fermentation platforms rather than commodity chemical synthesis. Regional clusters align with agricultural processing corridors and pharmaceutical biotechnology spillover.
Île-de-France
Paris anchors formulation R&D and regulatory affairs operations for pan-European food manufacturers. ANSES headquarters proximity accelerates pre-submission consultations for novel additive approvals. The Genopole biocluster at Évry transfers pharmaceutical fermentation expertise to food-grade enzyme production.
Auvergne-Rhône-Alpes
Lyon's chemical engineering heritage supports precision fermentation scale-up for natural preservative platforms. The EU Green Deal chemical sustainability targets drive investment in biodegradable additive alternatives at the Lyonbiopôle campus. Regional charcuterie and cheese processors generate concentrated demand for lactic acid bacteria shelf-life solutions.
Brittany
Dairy cooperative processing scale justifies direct procurement relationships with fermentation technology providers. Saint-Brieuc and Lorient harbors enable seaweed-derived hydrocolloid extraction for clean-label gelling applications. Local processors bypass traditional distributors through dedicated technical collaboration agreements.
Hauts-de-France
Nord-Pas-de-Calais industrial bakeries face compressed compliance timelines under revised EU 1333/2008 implementation. Lille's logistics hub position reduces inbound additive delivery costs for mid-scale processors. Limited technical service access constrains reformulation speed compared to Paris-Lyon corridor competitors.
Provence-Alpes-Côte d'Azur
Mediterranean botanical extract supply chains face climate variability pressure on carotenoid and anthocyanin feedstocks. Grasse fragrance expertise transfers to natural flavor precursor development for beverage applications. Regional agricultural cooperatives pilot drought-resistant plant varieties for stable colorant sourcing.
France Food Additives Market Competitive Landscape
Top-tier vendors anchor premium enzymatic and fermentation platforms, while mid-tier commodity suppliers compete on REACH compliance efficiency and logistics proximity. The French market exhibits tiered consolidation around multinationals with dedicated regulatory affairs capabilities. Three archetypes dominate: biotechnology specialists with precision fermentation assets, diversified ingredient conglomerates with broad portfolios, and regional distributors with formulation technical service. Competitive moves concentrate on direct procurement relationship cultivation and clean-label certification service bundling.
Within the biotechnology specialist tier, Kerry Group plc and Corbion NV exemplify platform-focused positioning, while Tate & Lyle PLC occupies the plant-derived sweetener specialization vector. These entities represent the transition from commodity chemical supply toward compliance-backed ingredient systems. Irish-registered Kerry Group plc anchors enzymatic solution development through European formulation centers. Dutch-registered Corbion NV exemplifies natural preservation dominance via lactic acid bacteria platforms. UK-registered Tate & Lyle PLC navigates sugar reduction mandates through stevia and monk fruit portfolios.
| Leading Market Players |
|---|
| Kerry Group plc |
| Archer Daniels Midland Company |
| BASF SE |
| Corbion NV |
| Tate & Lyle PLC |
| Cargill, Incorporated |
| Ingredion Incorporated |
| DSM |
| DuPont de Nemours, Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal chemical sustainability targets gate qualified supply and premium-tier pricing access, filtering smaller importers from France's additive market while concentrating procurement relationships around multinationals with verified life-cycle assessments. REACH compliance costs and ANSES authorization timelines compound this bifurcation, forcing mid-tier processors toward distributor-dependent models as larger buyers secure direct fermentation technology contracts.
Pricing Analysis
Margin tightening in natural preservative tiers reflects botanical extract feedstock volatility and extended ANSES toxicological review timelines. Three-tier pricing structure across premium enzymatic platforms, standard chemical alternatives, and economy synthetic grades differentiates suppliers. Cost-down pressure on mid-tier processors accelerates because legacy equipment retrofit requirements strain capital expenditure budgets. Beverage manufacturers show least price sensitivity for taste-modulating solutions, while industrial bakeries prioritize volume-scale emulsifier contracts.
Supply Chain Analysis
Regional distribution centers in Lille and Lyon operate hub-and-spoke patterns serving the Paris manufacturing corridor with just-in-time additive delivery. Supply concentrates in the Netherlands for fermentation-derived preservation platforms, Ireland for enzymatic texture solutions, and Mediterranean France for botanical colorant feedstocks. Raw material dependencies include lactic acid bacteria cultures, stevia leaf extracts, and wheat flour derivatives for cultured dextrose production. Single-source vulnerability in Mediterranean agricultural harvests creates structural risk for natural colorant supply chains. Distribution runs through specialized ingredient distributors with formulation technical service capabilities, though direct procurement relationships are displacing this layer among large dairy cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's food additive market is becoming a vertical-integration race, with fermentation technology capabilities and clean-label certification assets serving as the decisive upstream and downstream levers that separate consolidators from filtered participants.
For Market Incumbents: Deploy precision fermentation capacity additions in the Auvergne-Rhône-Alpes corridor to capture unmet demand from regional charcuterie processors. Anchor defensive positioning through exclusive starter culture development agreements with Brittany dairy cooperatives, neutralizing emerging biotechnology specialists before they achieve scale. Certification investment in third-party clean-label verification creates switching costs against commodity distributors. For New Entrants and Emerging Players: Precision fermentation platforms for high-value flavor precursors offer the most penetrable wedge into established supply relationships. Target the Nord-Pas-de-Calais bakery segment where limited technical service access constrains reformulation speed and creates white space for on-site enzyme activation systems. Go-to-market through direct technical collaboration agreements rather than distributor channels to bypass REACH compliance cost barriers. For Investors and Strategic Acquirers: ANSES authorization timeline compression for novel additives is the leading indicator that fermentation technology assets will command scarcity premiums. Five-to-ten year viability favors precision fermentation specialists with pharmaceutical bioprocess transfer capabilities over commodity chemical synthesis operations. Acquisition target archetype: regional biotechnology platforms with established lactic acid bacteria strain libraries and existing relationships with French dairy cooperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables label-friendly claims under tightened EU 1333/2008 maximum permitted concentration thresholds. |
| Direct Procurement Relationship Cultivation | Bypasses distributor layer in Brittany dairy corridor where volume justifies dedicated technical collaboration. |
| Clean-Label Certification Service Bundling | Creates recurring revenue as French retailers mandate independent verification for private-label positioning. |
| Backward Integration into Botanical Feedstocks | Reduces Mediterranean agricultural harvest variability exposure for natural colorant supply chains. |
| Enzymatic Platform Geographic Expansion | Compresses logistics costs and technical service response times in the Paris-Lyon manufacturing corridor. |
Research Methodology
Multi-period observation of ANSES authorization timelines, EFSA acceptable daily intake revisions, and EU Green Deal implementation progress anchored the trend analysis, supplemented by interviews with formulation chemists at industrial bakeries, procurement leads at dairy cooperatives, regulatory affairs directors at additive suppliers, and technical service managers at ingredient distributors. Secondary validation drew from EU 1333/2008 regulatory filings, REACH registration databases, customs trade records for botanical extract imports, and SEC disclosures from listed ingredient conglomerates. Bottom-up volume modeling across product type and application segments triangulated against top-down market sizing from macro consumption indicators.
Segment-weighting approaches applied differential growth assumptions across enzymatic, fermentation-derived, and synthetic additive categories, with cross-validation against reformulation pipeline visibility from beverage and dairy manufacturers. Segmentation dimensions modeled include product type, application, form, and end-user scale tier. CAGRs were derived from slope analysis of historical authorization-to-commercialization intervals and projected substitution elasticities under sugar reduction mandates. Industry-specific forecast inputs incorporated ANSES pre-submission consultation queues and EU Green Deal chemical sustainability target compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANSES maximum permitted concentration threshold revisions or Mediterranean climate disruption affecting botanical feedstock yields. Outputs reflect documented assumptions around regulatory implementation speed and clean-label consumer preference stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market