
 North America Food Enzymes Market | 2026-2036
North America Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Enzymes Market Analytics
Modular enzyme blends is recalibrating how food manufacturers configure their ingredient portfolios, letting buyers mix amylase, protease, and lipase ratios rather than accepting one-size formulations. DuPont de Nemours Inc. leverages its integrated biotechnology pipeline to supply customized enzyme systems for industrial bakeries. Kerry Group PLC anchors its position through deep relationships with North American dairy processors seeking lipase solutions for flavor development. Novozymes A/S differentiates via sustained R&D investment in cold-active enzymes that reduce energy costs in beverage filtration.
Food enzymes comprise protein-based biocatalysts—typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0—that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. These catalysts derive from microbial fermentation, plant extraction, or recombinant DNA techniques, and serve primarily to improve processing efficiency, extend shelf stability, or enhance sensory attributes in finished goods. The amylase category leads volume throughput due to its indispensability in starch hydrolysis for baking and brewing applications, while lipase commands premium positioning as dairy processors pursue clean-label flavor modulation without synthetic additives. Encapsulated formats represent the fastest-growing form segment, as protection technologies expand enzyme viability through harsh processing conditions and extended distribution cycles.
The FDA's GRAS notification framework and the USDA's organic certification standards jointly determine which enzyme preparations gain commercial traction in U.S. food manufacturing, with Canadian regulators under Health Canada and PMMA applying parallel but non-identical safety assessments that complicate cross-border product registration. The EPA's oversight of industrial biotechnology facilities adds compliance layers for microbial-derived enzyme production, particularly for genetically modified strains. Stakeholders must monitor evolving definitions of "natural" and "clean label" across U.S. and Canadian jurisdictions, as these consumer-driven classifications increasingly override purely technical performance metrics in procurement decisions.
Market Dynamics
Modular enzyme blending systems are restructuring procurement relationships between North American food manufacturers and their biocatalyst suppliers, replacing fixed-formulation contracts with ratio-adjustable supply agreements that let industrial bakeries and dairy processors tune amylase, protease, and lipase concentrations to specific production runs.
Growth Catalysts
- Clean-label bakery demand:U.S. consumers are rejecting chemical conditioners in bread and pastry applications, pulling food enzymes into formulations that replace azodicarbonamide and DATEM emulsifiers.
- GRAS notification modernization:The FDA's updated self-affirmation pathway is compressing time-to-market for novel enzyme preparations derived from recombinant microbial strains.
- Midwest processing concentration:Large-scale milling clusters in Minnesota and Wisconsin, combined with Wisconsin and California dairy processing density, create localized demand pools that justify dedicated enzyme distribution infrastructure.
Market Restraints
- Fermentation feedstock volatility:Corn syrup and molasses price swings directly compress margins for microbial-derived enzyme manufacturers operating at industrial scale.
- Cross-border registration friction:Health Canada's PMRA applies non-identical safety assessments to enzyme preparations already validated under FDA GRAS, forcing redundant toxicology packages for U.S.-based suppliers.
- Plant-extracted enzyme scarcity:Papain and bromelain supply from tropical sources faces climate-driven harvest inconsistency that limits formulation flexibility for allergen-sensitive applications.
Strategic Opportunities
- Canadian organic dairy expansion:The USDA's organic certification standards for enzyme processing aids create a compliance moat that favors suppliers with established organic-handling infrastructure.
- Cold-active enzyme deployment:Energy-intensive beverage filtration operations in California and Washington are piloting low-temperature biocatalysts that cut refrigeration loads.
- Encapsulation technology convergence:Spray-drying and fluidized-bed coating advances are extending enzyme viability through retort processing and frozen distribution cycles.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology and downstream processing expertise concentrates at a handful of Midwest universities, constraining workforce expansion for production facilities.
- Legacy formulation integration:Retrofitting enzyme-based dough conditioners into existing high-speed bakery lines requires revalidation of mixing profiles and proofing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Enzymes Market |
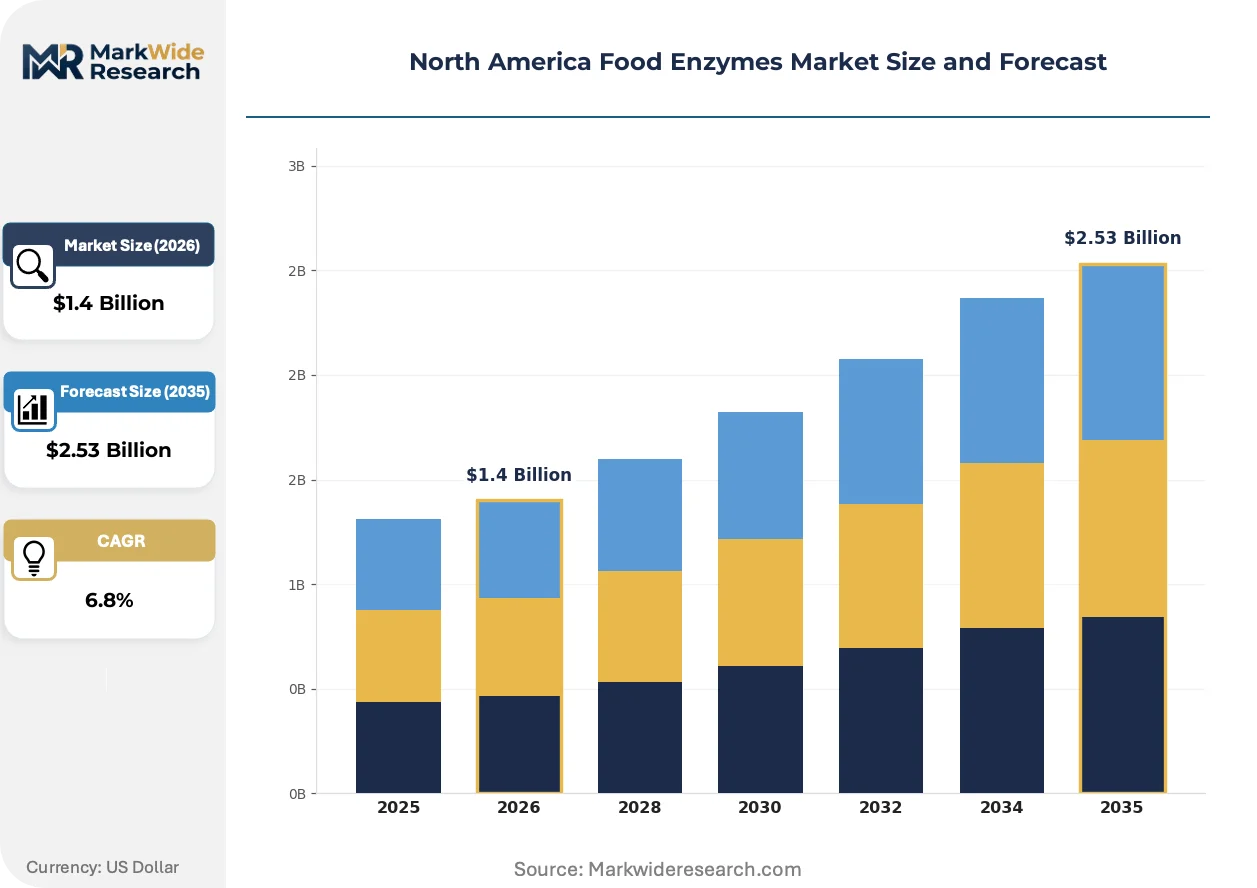
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Lipase, Cellulase Application: Baking, Dairy Processing, Beverages, Confectionery End User: Food Manufacturers, Beverage Producers, Retailers, Restaurants Form: Liquid, Powder, Granular, Encapsulated |
| Companies Covered | Kerry Group PLC, DuPont de Nemours Inc., Koninklijke DSM NV, AB Enzymes, Amano Enzyme Inc., Novozymes A/S, BASF SE, International Flavors & Fragrances Inc., Enmex, S.A. de C.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Enzymes Market Evolving Landscape
Enzyme engineering platforms and delivery-format innovations are compressing the traditional trade-off between processing performance and label simplicity that has constrained biocatalyst adoption in premium food categories.
Precision genome editing of production strains is unifying yield optimization with substrate specificity improvements that previously required separate development tracks. Large-scale malt houses and starch processors are adopting these second-generation amylases at replacement cycle pace. The technology is unifying cost parity with synthetic chemical alternatives in applications where enzymes previously carried a formulation premium.
The EPA's oversight of industrial biotechnology facilities is tightening containment and waste-treatment requirements for genetically modified microbial production. Enzyme manufacturers operating fermentation plants in the U.S. Midwest are retrofitting bioreactor suites and downstream recovery systems to meet revised discharge standards. Dairy enzyme suppliers with Wisconsin and Minnesota production assets face the steepest compliance timelines given their concentration of recombinant lipase capacity.
Specification-driven procurement is consolidating buyer power among North American industrial bakeries, with procurement teams demanding enzyme suppliers provide validated performance data across variable flour protein profiles rather than accepting generic application guidance. Direct supplier relationships are displacing distributor intermediaries for high-volume accounts. The shift is most visible in the U.S. Southeast, where regional bakery chains are building in-house technical service capabilities to evaluate enzyme performance in real-time production trials.
North America Food Enzymes Market Segmentation
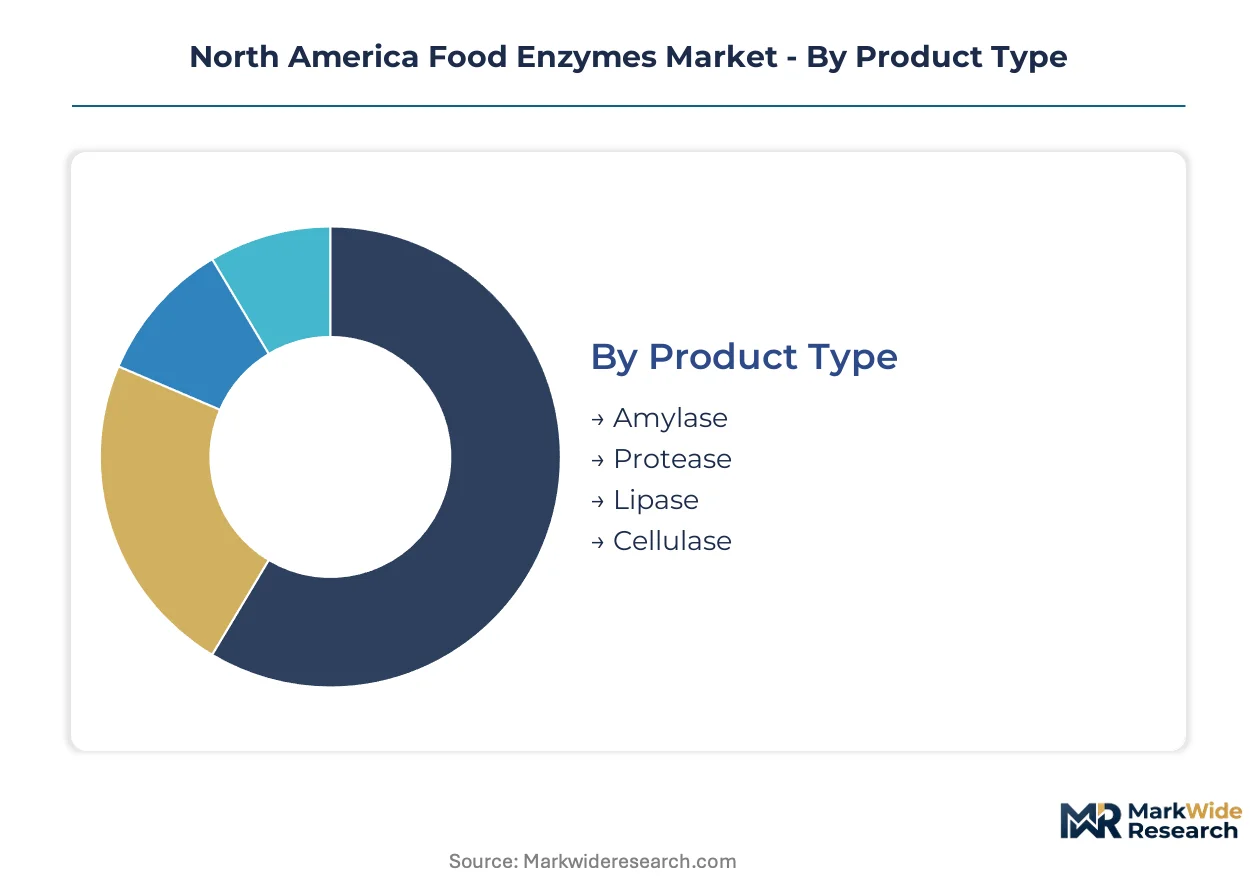
Food enzyme procurement in North America hinges on matching biocatalyst specificity to processing conditions rather than commodity purchasing. Manufacturers configure their ingredient portfolios across multiple segmentation axes simultaneously—selecting amylase concentrations for flour protein profiles, lipase formats for organic dairy compliance, and delivery systems for retort survivability.
Product Type:
Cost tier determines supplier selection, with premium lipase formulations commanding multiples of standard amylase pricing and driving portfolio margin strategy.
- Amylase:Starch-hydrolyzing enzymes operating optimally between 50°C and 70°C catalyze dextrinization in bread dough and wort preparation. Demand concentrates in Minnesota and Wisconsin milling corridors where large-scale bakeries and malt houses require consistent α-amylase activity across variable wheat harvests. The GRAS self-affirmation pathway accelerates novel thermostable variant introductions.
- Lipase:Triacylglycerol hydrolases generate free fatty acids for flavor development in aged cheeses and butterfat modification. Wisconsin and California organic dairy processors absorb capacity for clean-label lipolysis, though fermentation feedstock volatility compresses supplier margins during corn syrup price spikes.
- Protease:Peptide-bond cleavage enzymes reduce gluten strength in cracker dough and accelerate cheese ripening. Midwest universities supply constrained fermentation scale-up talent for production strain optimization.
- Cellulase:β-1,4-glucanases break down cell wall polysaccharides in fruit processing and vegetable fiber modification. Beverage filtration operations in Washington pilot cold-active variants to cut energy loads.
Volume sits with amylase; growth tilts toward lipase.
Application:
Application selection follows end-product label requirements, with clean-label bakery and organic dairy creating specification moats that exclude commodity chemical alternatives.
- Baking:Dough conditioning and crumb softening applications replace azodicarbonamide and DATEM emulsifiers as U.S. consumers reject chemical additives. Regional bakery chains in the U.S. Southeast build in-house technical service capabilities to evaluate enzyme performance in real-time production trials, displacing distributor intermediaries.
- Dairy Processing:Flavor modulation, texture modification, and lactose hydrolysis serve organic certification requirements under USDA standards. Canadian organic dairy expansion creates cross-border registration friction as Health Canada's PMRA applies non-identical safety assessments to FDA-validated preparations.
- Beverages:Filtration efficiency and haze stability in brewing and juice processing. California operations pilot energy-reducing cold-active enzyme deployments.
- Confectionery:Viscosity control and sugar inversion in chocolate and candy manufacturing. Encapsulation technologies extend viability through retort processing cycles.
Procurement concentrates in baking; specification complexity peaks in dairy processing.
End User:
Customer type dictates technical service intensity, with food manufacturers demanding validated performance data across variable input profiles.
- Food Manufacturers:Industrial bakeries and dairy processors with high-throughput lines require ratio-adjustable enzyme blends rather than fixed formulations. Direct supplier relationships consolidate buyer power among large accounts.
- Beverage Producers:Malt houses and breweries adopt second-generation amylases at replacement cycle pace. Specification-driven procurement demands substrate-specificity documentation.
- Retailers:Private-label food brands specify enzyme-treated ingredients for clean-label positioning. Organic certification compliance filters supplier pools.
- Restaurants:Limited penetration due to batch-scale operations lacking fermentation expertise or capital for enzyme dosing systems.
Revenue concentrates with food manufacturers; service intensity differentiates beverage accounts.
Form:
Supply concentration in Midwest fermentation clusters shapes delivery format availability, with encapsulated variants requiring specialized coating infrastructure.
- Liquid:Standard enzymatic solutions for continuous dosing in high-speed bakery lines. Retrofitting requires revalidation of mixing profiles and proofing protocols.
- Powder:Spray-dried preparations for dry blending in flour milling and premix manufacturing. Shelf stability depends on moisture control through distribution cycles.
- Granular:Free-flowing particulates for uniform dispersion in dough systems. Wisconsin and Minnesota production assets face EPA compliance timelines for recombinant strain containment.
- Encapsulated:Fluidized-bed and spray-coating technologies protect enzyme activity through retort processing and frozen distribution. Advances in protection technologies expand viability through harsh processing conditions.
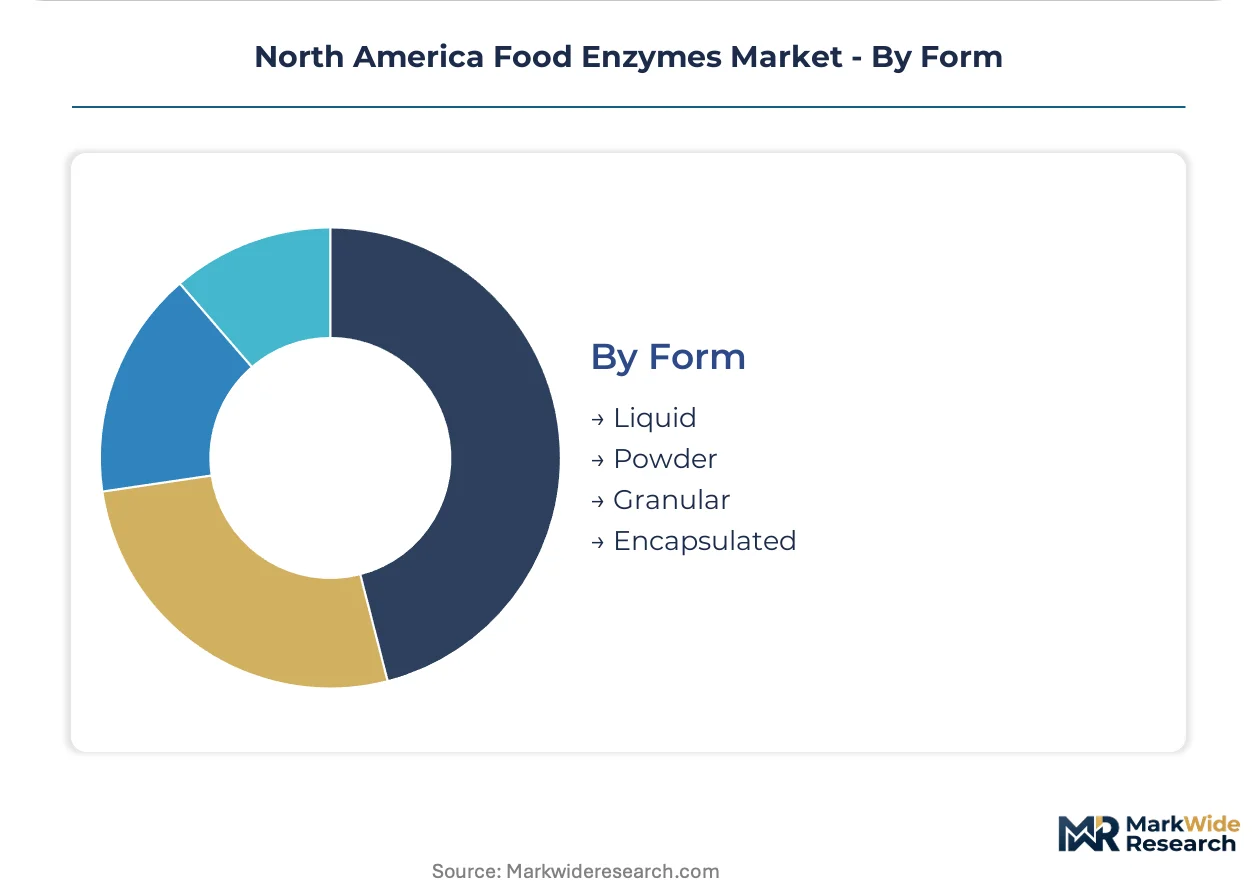
Volume flows through liquid and powder; encapsulated formats expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme production concentrates in Midwest fermentation clusters while consumption spreads across coastal dairy and bakery processing belts. This geographic split shapes distribution infrastructure and regulatory compliance strategies for suppliers.
United States
Industrial bakeries in Minnesota and Wisconsin drive amylase demand for starch hydrolysis in high-speed dough conditioning. FDA GRAS notification updates compress time-to-market for novel recombinant enzyme preparations. The EPA enforces tightened containment standards for genetically modified microbial production at fermentation facilities across the Upper Midwest.
Canada
Organic dairy processors in Quebec and Ontario absorb lipase capacity for clean-label flavor development in aged cheeses. Health Canada's PMRA applies non-identical safety assessments to FDA-validated preparations, forcing redundant toxicology packages. Cross-border registration friction complicates supply agreements for U.S.-based enzyme manufacturers serving Canadian accounts.
Mexico
Beverage filtration operations in Jalisco and Nuevo León pilot cold-active cellulase variants to reduce refrigeration energy loads. The national food safety regulator applies parallel but distinct approval pathways for microbial-derived processing aids. Guadalajara's brewing cluster generates localized demand for second-generation amylases at replacement cycle pace.
North America Food Enzymes Market Competitive Landscape
The competitive structure tilts toward integrated biotechnology conglomerates with captive fermentation infrastructure. Three to five multinational suppliers control premium lipase and customized enzyme blend segments through proprietary strain libraries and direct technical service relationships. Mid-tier regional specialists compete on price for commodity amylase formulations. Dominant competitive moves include backward integration into fermentation feedstock sourcing and geographic expansion of application laboratories near Midwest milling and dairy clusters.
Among European-anchored biotechnology groups, Novozymes A/S and Koninklijke DSM NV occupy positions emphasizing sustained R&D investment in cold-active and thermostable enzyme variants. DuPont de Nemours Inc. represents the integrated industrial conglomerate archetype with biotechnology pipelines serving industrial bakery accounts. Kerry Group PLC exemplifies the ingredients-platform strategy, anchoring its position through service relationships with North American dairy processors seeking lipase solutions.
| Leading Market Players |
|---|
| Kerry Group PLC |
| DuPont de Nemours Inc. |
| Koninklijke DSM NV |
| AB Enzymes |
| Amano Enzyme Inc. |
| Novozymes A/S |
| BASF SE |
| International Flavors & Fragrances Inc. |
| Enmex, S.A. de C.V. |
| Others |
Value Network & Pricing Analysis
Captive fermentation infrastructure in the U.S. Midwest anchors supply positions and pricing power for enzyme suppliers serving North American food manufacturers. DuPont de Nemours Inc. and Novozymes A/S leverage in-house bioreactor capacity to offset feedstock volatility while commanding premium positioning for customized lipase blends.
Pricing Analysis
Margin tightening in standard amylase formulations reflects corn syrup price volatility and commodity-grade competition from regional specialists. Three-tier pricing structure across premium, standard, and economy levels separates recombinant lipase for organic dairy from generic protease and economy-grade cellulase. Certification under FDA GRAS and USDA organic standards commands tier premiums. Industrial bakeries in Minnesota and Wisconsin exhibit highest price sensitivity due to volume procurement and ratio-adjustable blend flexibility, while California organic dairy processors accept premium positioning for clean-label compliance.
Supply Chain Analysis
Fermentation feedstock supply rests on U.S. corn belt harvests, Brazilian sugarcane molasses, and Canadian wheat starch derivatives. Corn syrup and molasses constitute primary carbon sources for microbial strain cultivation, while specialized coating polymers for encapsulation formats draw from German and Japanese chemical producers. Single-source vulnerability concentrates in tropical papain and bromelain extraction from India and Thailand. Distribution runs through dedicated cold-chain logistics from Midwest production clusters to coastal dairy and bakery processing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision genome editing platforms are displacing traditional strain development timelines, compressing competitive moats for incumbent suppliers while opening white-space for specialized entrants with CRISPR-optimized production strains.
For Market Incumbents: Extend proprietary strain libraries into cold-active and thermostable variants to defend against precision-edited challengers. Backward integration into fermentation feedstock sourcing mitigates corn syrup margin compression. Wisconsin and Minnesota capacity expansion captures Midwest dairy cluster growth.
For New Entrants and Emerging Players: Direct-to-bakery technical service platforms bypass established distributor networks for specification-driven procurement accounts. Canadian organic dairy expansion offers the most penetrable geography given cross-border registration friction disadvantaging U.S. incumbents. Real-time dough performance validation tools differentiate against generic application guidance.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated ingredients platforms seeking fermentation scale. Mid-term viability favors suppliers with captive organic-handling infrastructure and EPA-compliant recombinant containment systems. Watch FDA GRAS notification volume for novel enzyme submissions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Strain Engineering Investment | CRISPR-edited production strains unify yield optimization with substrate specificity improvements. |
| Encapsulation Technology Scale-Up | Fluidized-bed coating infrastructure extends enzyme viability through retort processing cycles. |
| Cross-Border Registration Infrastructure | Parallel Health Canada PMRA and FDA GRAS validation accelerates Canadian market access. |
| Cold-Active Enzyme Commercialization | Low-temperature biocatalysts cut refrigeration loads in California and Washington beverage filtration. |
| Organic Certification Compliance Buildout | USDA organic-handling infrastructure creates procurement moats for dairy enzyme suppliers. |
Research Methodology
Independent corroboration across fermentation plant managers, dairy processor procurement leads, bakery technical directors, and enzyme R&D specialists underwrites the qualitative findings. Primary interviews with distribution channel partners and EPA compliance officers supplemented secondary validation through FDA GRAS notification databases, USDA organic certification records, SEC 10-K filings of listed biotechnology conglomerates, and customs trade data on fermentation feedstock imports. Bottom-up enzyme volume estimates triangulated against top-down food processing capacity assessments across the analysis window.
Comparable-period anchoring to historical production volumes and replacement cycle timing established the forecast baseline. The analytical framework models enzyme demand across product type, application, end user, and delivery form dimensions throughout the projection horizon. CAGRs derive from segmented growth rate reconciliation against macro food processing output trends. Fermentation feedstock price indices and clean-label bakery penetration rates constitute industry-specific forecast inputs.
The model holds under stable FDA GRAS notification timelines and EPA containment standard continuity; deviation in regulatory approval velocity or recombinant strain discharge restrictions would shift supply availability assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Pyranose Oxidase Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Coconut Fatty Acids Market