
 Canada Electric Vehicle Battery Manufacturing Market | 2026-2036
Canada Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Electric Vehicle Battery Manufacturing Market Insights
Light-duty passenger vehicle electrification is consolidating as the dominant demand channel across Canadian automotive supply chains. LG Energy Solution anchors its North American position through the NextStar Energy joint venture in Windsor, leveraging integrated cathode active material sourcing. Stellantis sustains its battery manufacturing footprint through partnerships that secure Ontario-based cell supply for its electrified vehicle platforms.
Canada electric vehicle battery manufacturing encompasses the domestic production of electrochemical energy storage cells, modules, and packs, primarily utilizing lithium-ion chemistries with nickel-manganese-cobalt or lithium-iron-phosphate cathode compositions fabricated through electrode coating, cell formation, and module assembly processes. This industrial activity supplies propulsion systems for battery electric and plug-in hybrid vehicles while supporting grid-connected energy storage applications. Lithium-ion battery types dominate current production scale due to established supply chains and energy density requirements, though solid-state architectures represent the fastest-growing technology segment as manufacturers pursue higher safety margins and extended cycle life. Passenger vehicle applications command the largest addressable volume, while commercial vehicle electrification is emerging as a concentrated margin pool for heavy-duty cell formats.
Health Canada and Transport Canada jointly administer vehicle safety and emissions standards that mandate zero-emission vehicle sales thresholds, directly conditioning market access for domestic battery production. Environment and Climate Change Canada enforces federal clean fuel regulations that credit low-carbon intensity electricity used in cell manufacturing, while Ontario's Ministry of Mines advances critical minerals processing permits that determine feedstock availability for cathode precursor production. Stakeholders must monitor how provincial permitting timelines for lithium hydroxide refining align with offtake commitments from Windsor-area gigafactories.
Market Dynamics
Cell chemistry standardization around nickel-manganese-cobalt and lithium-iron-phosphate formats is compressing equipment vendor margins while concentrating procurement power among Windsor-Oshawa gigafactory operators demanding process guarantees.
Growth Catalysts
- Clean Fuel Regulations:Environment and Climate Change Canada's crediting mechanism for low-carbon electricity in cell manufacturing is accelerating cathode precursor facility siting in Ontario's industrial heartland.
- Passenger vehicle electrification:Light-duty platform commitments from Stellantis and Detroit Three affiliates are pulling gigawatt-hour-scale capacity commitments into the Windsor corridor.
- Critical minerals processing:Ontario's Ministry of Mines permitting framework for lithium hydroxide refining is aligning feedstock availability with cathode active material demand.
Market Restraints
- Lithium hydroxide supply concentration:Spodumene concentrate dependency on Australian and African hard-rock mining creates input cost volatility for Ontario-based cathode plants.
- Technical limitation:Dry electrode coating equipment for silicon-anode cells remains captive to German and Japanese machinery vendors, constraining domestic process innovation.
- Regulatory friction:Health Canada's evolving battery safety testing protocols for thermal runaway propagation are extending certification timelines for new cell formats.
Strategic Opportunities
- Quebec lithium refining:Underpenetrated hydroelectric-powered processing capacity in Abitibi-Témiscamingue offers feedstock security for cathode precursor expansion.
- Commercial vehicle electrification:Heavy-duty cell formats for regional haul trucking represent concentrated margin pools with less price-sensitive procurement.
- Integrated material recovery:Black mass hydrometallurgical refining convergence with direct recycling technologies is creating closed-loop supply economics.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell formation and aging protocol optimization expertise concentrates among former Panasonic and LG Chem specialists, constraining domestic workforce scaling.
- Capex intensity for dry room infrastructure:Dew point-controlled cleanroom construction for electrode coating lines demands specialized HVAC contractors with 18-month lead times.
- UN 38.3 certification complexity:Lithium cell transportation testing requirements for cross-border module shipment are creating compliance bottlenecks at the Detroit River crossing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Electric Vehicle Battery Manufacturing Market |
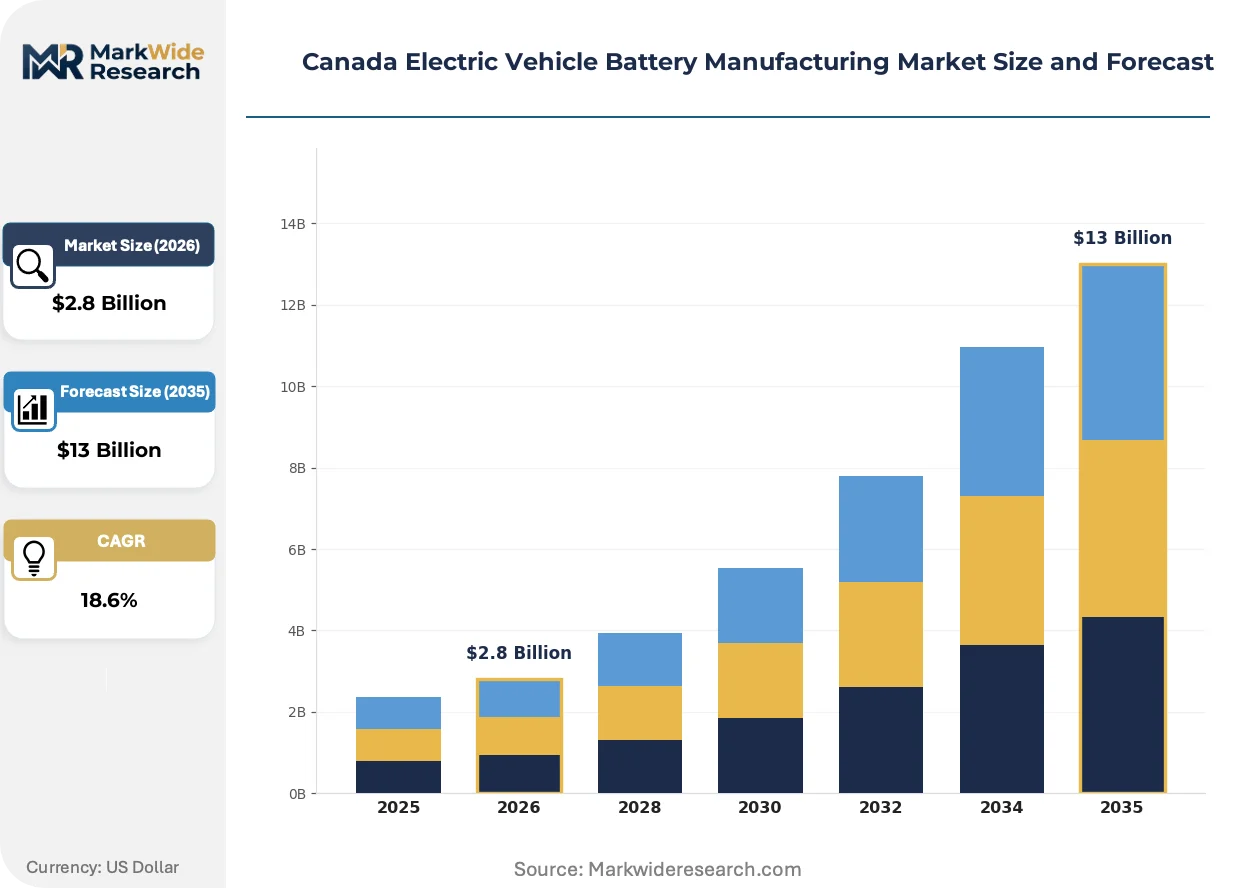
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Lead-Acid End User: Automakers, OEMs, Charging Infrastructure Providers, Fleet Operators Technology: Battery Management Systems, Manufacturing Automation, Recycling Technology, Cell Production Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Volkswagen, Stellantis, LG Energy Solution, Northvolt, NextStar Energy, Panasonic, General Motors, SK On, Targray, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Electric Vehicle Battery Manufacturing Market Trends and Innovations
Solid-state electrolyte development and silicon-anode integration are compressing conventional liquid-electrolyte cell economics while reshaping equipment vendor competitive hierarchies across Canadian manufacturing corridors.
Sulfide-based solid-state architectures are electrifying next-generation safety margins through ceramic electrolyte layers that eliminate flammable organic solvents. Automotive OEMs are qualifying these cells for premium passenger platforms with extended cycle life requirements. This technology is electrifying incumbent wet-coating equipment valuations as dry electrode processes displace solvent-based slurry lines.
Health Canada's advancing battery safety standards for thermal propagation resistance are mandating multi-layer ceramic separators and cell-level fuse integration. Manufacturers are retrofitting formation lines with enhanced abuse testing protocols to secure type approval. The passenger vehicle segment bears the heaviest compliance burden, with Windsor-area facilities accelerating pilot production for 2026 platform deadlines.
Fleet operators are consolidating procurement around total-cost-of-ownership contracts that bundle cell performance guarantees with residual value recovery. Direct OEM-to-fleet agreements are displacing traditional tiered distribution through aftermarket parts networks. This concentration is most visible in Ontario's Golden Horseshoe municipal transit electrification programs, where battery-as-a-service models dominate tender specifications.
Canada Electric Vehicle Battery Manufacturing Market Segmentation
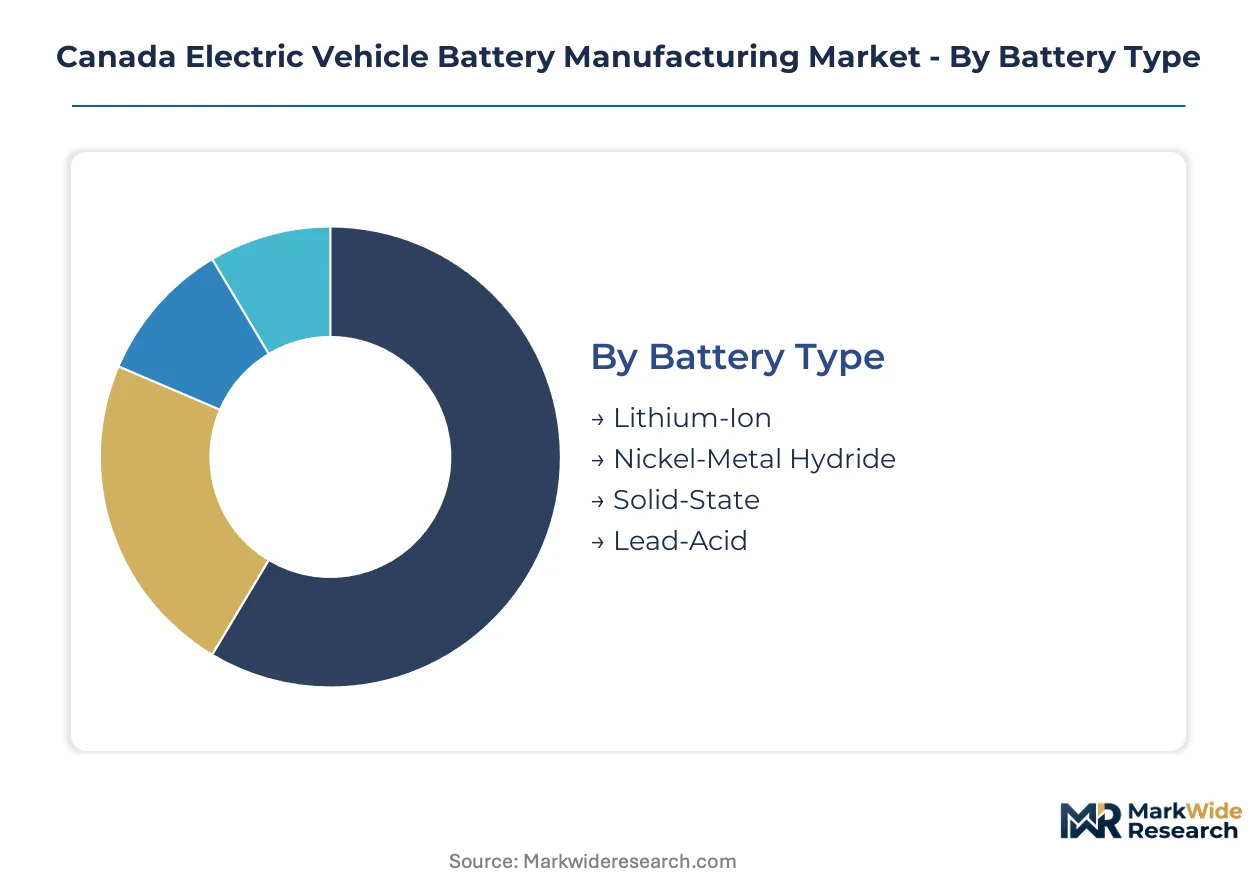
Segmentation reveals how Windsor-to-Toronto corridor capacity allocates across competing demand channels. Chemistry choices, end-user procurement patterns, and application specifications determine equipment vendor selection and facility siting decisions.
Battery Type:
Supply concentration among cathode active material processors in Ontario favors specific electrochemical architectures.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants dominate current gigafactory output. Stellantis and NextStar Energy offtake agreements concentrate demand in Windsor for these liquid-electrolyte formats.
- Solid-State:Sulfide-based ceramic electrolyte architectures eliminate thermal runaway risks through non-flammable designs. Pilot lines in Ontario are qualifying these cells for premium passenger platforms with extended cycle life requirements.
- Nickel-Metal Hydride:Legacy hybrid vehicle applications sustain limited production for Toyota-affiliated supply chains.
- Lead-Acid:Starter battery and auxiliary power applications persist in commercial vehicle aftermarket channels.
Lithium-Ion absorbs the bulk of installed capacity; Solid-State is expanding most quickly.
End User:
Procurement scale and contract duration vary sharply across buyer categories.
- Automakers:Stellantis and Detroit Three affiliates negotiate multi-gigawatt-hour offtake agreements with decade-long supply commitments. These contracts dictate cathode chemistry standardization across Ontario cell plants.
- OEMs:Tier-1 system integrators procure modules for platform-agnostic integration, demanding UN 38.3 certification compliance for cross-border Detroit River shipments.
- Charging Infrastructure Providers:Stationary storage procurement for grid-buffering applications favors second-life automotive cells with degraded but serviceable capacity.
- Fleet Operators:Municipal transit electrification programs in Ontario's Golden Horseshoe specify battery-as-a-service models with performance guarantees and residual value recovery clauses.
Automakers command the largest procurement volumes; Fleet Operators are adopting performance-based contracting fastest.
Technology:
Process capability gaps determine domestic value capture versus imported equipment dependency.
- Cell Production:Electrode coating, winding, and formation lines constitute the core manufacturing asset base. Windsor-area facilities source dry room infrastructure from specialized HVAC contractors with 18-month lead times.
- Battery Management Systems:Firmware and thermal control electronics represent high-margin embedded software layers. Ontario engineering talent concentrates in this segment versus electrochemical hardware.
- Manufacturing Automation:Vision-guided assembly and in-line quality inspection equipment reduces labor content per kilowatt-hour.
- Recycling Technology:Black mass hydrometallurgical refining and direct recycling methods are converging toward closed-loop feedstock economics for cathode precursor recovery.
Cell Production absorbs the bulk of capital deployment; Recycling Technology is climbing the fastest as feedstock security concerns intensify.
Application:
Energy density requirements and duty cycle profiles segment addressable markets.
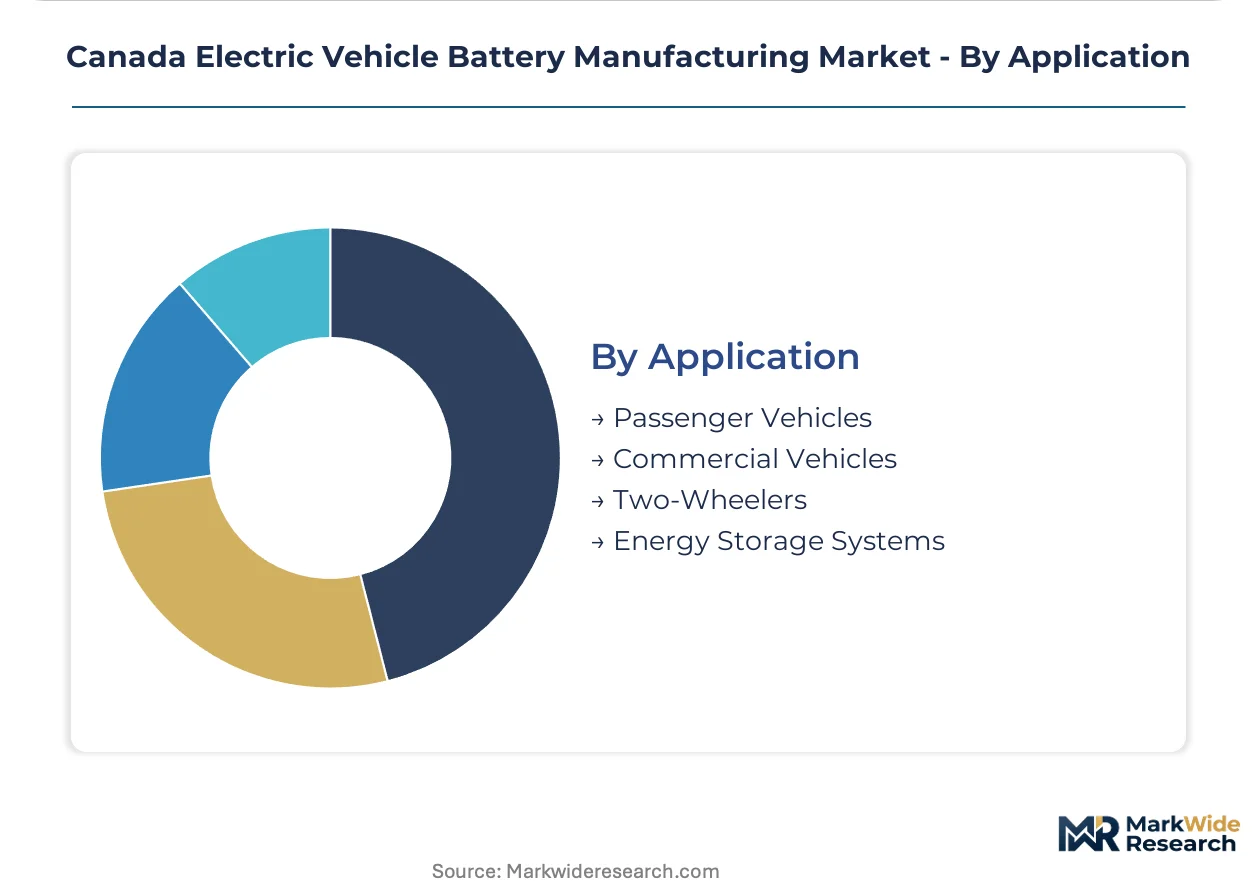
- Passenger Vehicles:Light-duty platform specifications from Stellantis pull the majority of Ontario cell capacity. Health Canada thermal propagation standards mandate multi-layer ceramic separators for this segment.
- Commercial Vehicles:Heavy-duty regional haul trucking applications favor larger cell formats with less price-sensitive procurement. Fleet operators consolidate around total-cost-of-ownership contracts bundling performance guarantees.
- Energy Storage Systems:Grid-connected stationary applications tolerate lower energy density in exchange for extended cycle life and degraded automotive cell reuse.
- Two-Wheelers:Low-power urban mobility applications represent marginal volume for Canadian production, with supply dominated by Asian cell imports.
Passenger Vehicles absorb the bulk of production volume; Commercial Vehicles are gaining share fastest on margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Investment Tax Credit for clean technology manufacturing is concentrating gigafactory development in the Windsor-to-Toronto corridor. Health Canada's clean transportation mandates and provincial critical minerals strategies are reshaping where cell production capacity locates.
Ontario
Stellantis and NextStar Energy anchor multi-gigawatt-hour commitments in Windsor, pulling cathode active material demand into the region. Ontario's Ministry of Mines advances lithium hydroxide refining permits that determine feedstock availability for precursor production. The Windsor-Oshawa manufacturing belt now hosts electrode coating, cell formation, and module assembly lines serving Detroit Three electrification platforms.
Quebec
Hydroelectric-powered lithium refining in Abitibi-Témiscamingue offers feedstock security for cathode precursor expansion. The province's critical minerals processing framework supports spodumene concentrate conversion for Ontario-based gigafactories. Bécancour and surrounding industrial zones are attracting hydrometallurgical refining investments that reduce Australian hard-rock dependency.
British Columbia
Port infrastructure for spodumene concentrate imports from Australia creates a western logistics node for Canadian cell manufacturing. The province's clean electricity grid supports carbon-intensity calculations under federal clean fuel regulations. Vancouver-area engineering consultancies specialize in battery management system firmware development for Ontario-based pack integrators.
Alberta
Petrochemical complex repurposing is creating pathways for electrolyte solvent and binder chemical production. The province's industrial heartland offers existing process engineering talent pools for cell manufacturing equipment maintenance. Calgary-based energy service companies are pivoting technical capabilities toward battery recycling and black mass refining economics.
Canada Electric Vehicle Battery Manufacturing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automaker-affiliated joint ventures commanding the largest procurement volumes. The market structure concentrates around three strategic archetypes: integrated OEM-battery partnerships, standalone cell producers, and materials-specialist suppliers. Capacity expansion and strategic partnerships dominate competitive moves as players secure cathode precursor feedstock and offtake agreements.
Within the automaker-anchored tier, Stellantis, Volkswagen, and General Motors exemplify the joint-venture model for securing Ontario-based cell supply. These companies occupy positions that bind vehicle platform electrification timelines to Windsor-area gigafactory output. LG Energy Solution and NextStar Energy represent the contract-manufacturing archetype, sitting within the supply chain as dedicated production entities rather than brand-forward marketers. Panasonic occupies a position bridging both models, with historical cell supply relationships informing current North American siting decisions.
| Leading Market Players |
|---|
| Volkswagen |
| Stellantis |
| LG Energy Solution |
| Northvolt |
| NextStar Energy |
| Panasonic |
| General Motors |
| SK On |
| Targray |
| Others |
Pricing and Supply Chain Analysis
Automaker multi-gigawatt-hour offtake agreements with decade-long supply commitments are compressing cell pricing through volume guarantees while forcing cathode precursor suppliers to absorb feedstock volatility. Health Canada's thermal propagation standards and Ontario's clean fuel regulations add compliance layers that segment pricing across certified and non-certified production tiers.
Pricing Analysis
Premium pricing for dry room infrastructure with 18-month contractor lead times separates urgent capacity expansions from planned brownfield deployments. Three-tier pricing structure across premium certified, standard qualified, and economy spot-market tiers reflects Health Canada safety protocol adherence and UN 38.3 transportation certification status. Cost compression in liquid-electrolyte cell formats is intensifying because equipment vendor margins compress around standardized nickel-manganese-cobalt and lithium-iron-phosphate chemistries. Fleet operators with battery-as-a-service contracts demonstrate lowest price sensitivity due to total-cost-of-ownership bundling, while aftermarket distributors face highest margin pressure from Asian cell import competition.
Supply Chain Analysis
UN 38.3 lithium cell transportation certification and Health Canada thermal runaway propagation testing create gating delays that concentrate qualified supplier power among established Ontario gigafactory operators. Spodumene concentrate feeds from Australia, Chile, and hard-rock African mining operations anchor cathode precursor input costs. Lithium hydroxide refining, cathode active material processing, and electrode coating equipment draw from Chinese, South Korean, and Japanese manufacturing bases. Single-source vulnerability in dry electrode coating machinery from German and Japanese vendors threatens Windsor corridor expansion timelines. Distribution runs through Detroit River cross-border module shipments to Stellantis and Detroit Three assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's evolving battery safety testing protocols function as a cost-of-compliance moat, elevating capital requirements for thermal propagation certification and compressing returns for undercapitalized entrants unable to secure extended formation line investments.
For Market Incumbents: Anticipate silicon-anode dry electrode process transitions by securing formation line retrofit partnerships before German and Japanese equipment vendors extend lead times beyond 24 months. Defensive consolidation around Quebec lithium hydroxide refining capacity in Abitibi-Témiscamingue reduces Australian spodumene dependency. Backward integration into black mass hydrometallurgical recovery creates captive cathode precursor feedstock security against volatile lithium compound spot markets. For New Entrants and Emerging Players: Municipal transit electrification programs in Ontario's Golden Horseshoe represent the most penetrable buyer archetype, with battery-as-a-service procurement models favoring performance-guarantee newcomers over established automaker supply relationships. Heavy-duty regional haul trucking cell formats offer concentrated margin pools with less price-sensitive fleet operator procurement. Direct OEM-to-fleet agreements displace tiered aftermarket distribution, enabling bypass of incumbent channel control through residual value recovery clauses. For Investors and Strategic Acquirers: The window for entry favors integrated material recovery specialists with hydrometallurgical refining capabilities and direct recycling technology convergence. Long-term viability centers on closed-loop cathode precursor economics as feedstock security concerns intensify across the projection horizon. Watch for Ontario Ministry of Mines permitting timeline acceleration for lithium hydroxide refining as the inflection signal for cathode active material capacity expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Quebec hydroelectric-powered lithium refining reduces Australian hard-rock dependency for Windsor gigafactories. |
| Solid-State Pilot Line Qualification | Health Canada thermal propagation standards favor sulfide-based ceramic electrolyte architectures for premium platforms. |
| Battery-as-a-Service Fleet Contracts | Ontario Golden Horseshoe municipal transit programs bundle performance guarantees with residual value recovery. |
| Black Mass Hydrometallurgical Recovery | Closed-loop cathode precursor economics align with Ontario's critical minerals processing framework. |
| Dry Room Infrastructure Expansion | Dew point-controlled cleanroom construction demands specialized HVAC contractors with extended lead times. |
Research Methodology
Trade flow databases, vehicle production registries, and provincial mining permit filings formed the secondary backbone, cross-referenced with primary interviews across cell formation engineers, cathode precursor procurement leads, gigafactory operations directors, and Health Canada regulatory compliance officers. Bottom-up installed capacity estimates from Windsor-to-Toronto corridor facilities were triangulated against top-down demand projections from Stellantis and Detroit Three electrification platform commitments.
Historical trendline analysis of lithium-ion cell manufacturing capex intensity and electrode coating equipment deployment patterns informed the analytical framework across the analysis window. Segmentation dimensions modeled include battery chemistry architecture, end-user procurement category, application energy density requirements, and technology process capability tiers. CAGRs were derived from capacity expansion announcements, offtake agreement volumes, and feedstock availability timelines. Forecast inputs incorporated Ontario Investment Tax Credit utilization rates and Quebec hydroelectric grid carbon intensity calculations under federal clean fuel regulations.
Revisions become necessary when Health Canada battery safety protocol amendments extend certification timelines, Ontario Ministry of Mines permitting delays disrupt lithium hydroxide refining alignment, or solid-state electrolyte pilot production achieves commercial scale faster than modeled. A model refresh is warranted upon material change in Windsor corridor gigafactory utilization rates or Detroit Three electrification platform volume commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
Traction Battery Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market