
 Thermal Interface Material for EV Battery Market | 2026-2036
Thermal Interface Material for EV Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Interface Material for EV Battery Market Insights
The EU Green Deal is restructuring procurement priorities across European EV supply chains, forcing battery manufacturers to prioritize low-thermal-impedance materials that extend cycle life and reduce fire risk. Henkel leverages its adhesive chemistry heritage to dominate conductive polymer formulations for pouch-cell modules. Saint-Gobain Tape Solutions anchors high-volume pad production for prismatic battery architectures across multiple continents. Shin-Etsu Chemicals specializes in silicone-based thermal gels that sustain performance across extreme temperature cycling.
Thermal interface material for EV battery denotes engineered substances—typically silicone, acrylic, or epoxy formulations loaded with boron nitride, alumina, or metal oxide fillers—that facilitate heat transfer between battery cells, modules, and cooling plates while maintaining electrical isolation. These materials operate within thermal conductivity ranges of 1–15 W/m·K and must retain dielectric strength above 5 kV/mm under sustained compression. Phase change materials and conductive polymers command premium positioning as OEMs adopt cell-to-pack designs that eliminate module housings and demand thinner, higher-performance thermal layers. Grease and gel formulations compete for share in service-accessible battery architectures where reworkability matters, while film and pad segments occupy established positions in cost-optimized mass-market platforms where manufacturing simplicity drives specification.
EMA, REACH, and the EU Battery Regulation collectively shape material compliance burdens, restricting certain flame-retardant chemistries and mandating recycled content disclosures that filter down to formulation choices. EPA and NHTSA influence parallel requirements in the United States through vehicle safety standards and emerging battery passport frameworks. OEMs and tier-1 suppliers must monitor how these regulatory trajectories diverge, as compliance investments in one jurisdiction rarely transfer cleanly to another, fragmenting R&D budgets and supplier qualification timelines across overlapping but incompatible standards regimes.
Market Dynamics
Cell-to-pack architectures are compressing thermal management layers into sub-millimeter gaps, forcing material suppliers to engineer higher-conductivity formulations without sacrificing dielectric integrity.
Growth Catalysts
- EU Battery Regulation:Mandates stricter thermal runaway containment standards across cell-to-pack designs, accelerating qualification of advanced phase-change materials.
- Solid-state battery development:Next-generation cell chemistries generate localized heat spikes that conventional greases cannot manage, opening demand for boron nitride-loaded silicone gels.
- Germany:Volkswagen, BMW, and Mercedes-Benz operate large-format battery assembly plants that concentrate procurement of high-performance thermal pads.
Market Restraints
- Alumina price volatility:Ceramic filler costs swing with energy-intensive smelting operations in China, squeezing formulation margins.
- Single-source silicone dependence:Shin-Etsu and Wacker dominate medical-grade polymer supply, creating concentration risk for gel-based TIM producers.
- REACH authorization delays:Flame-retardant chemistries face extended substance evaluation timelines, freezing product reformulation cycles.
Strategic Opportunities
- India:PLI scheme subsidies for domestic cell manufacturing create first-mover advantage for TIM suppliers establishing local compounding facilities.
- Second-life battery thermal management:Repurposed EV packs in stationary storage need reworkable gel interfaces rather than permanent pads.
- AI-enabled thermal modeling:Convergence of predictive simulation tools with material databases allows customized filler loading optimization per battery design.
Industry Challenges
- Dielectric spectroscopy expertise:Few technicians can validate AC breakdown performance under compression cycling, extending supplier qualification timelines.
- Cleanroom capex requirements:Sub-100-micron film production demands ISO Class 7 environments that mid-size compounders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Interface Material for EV Battery Market |
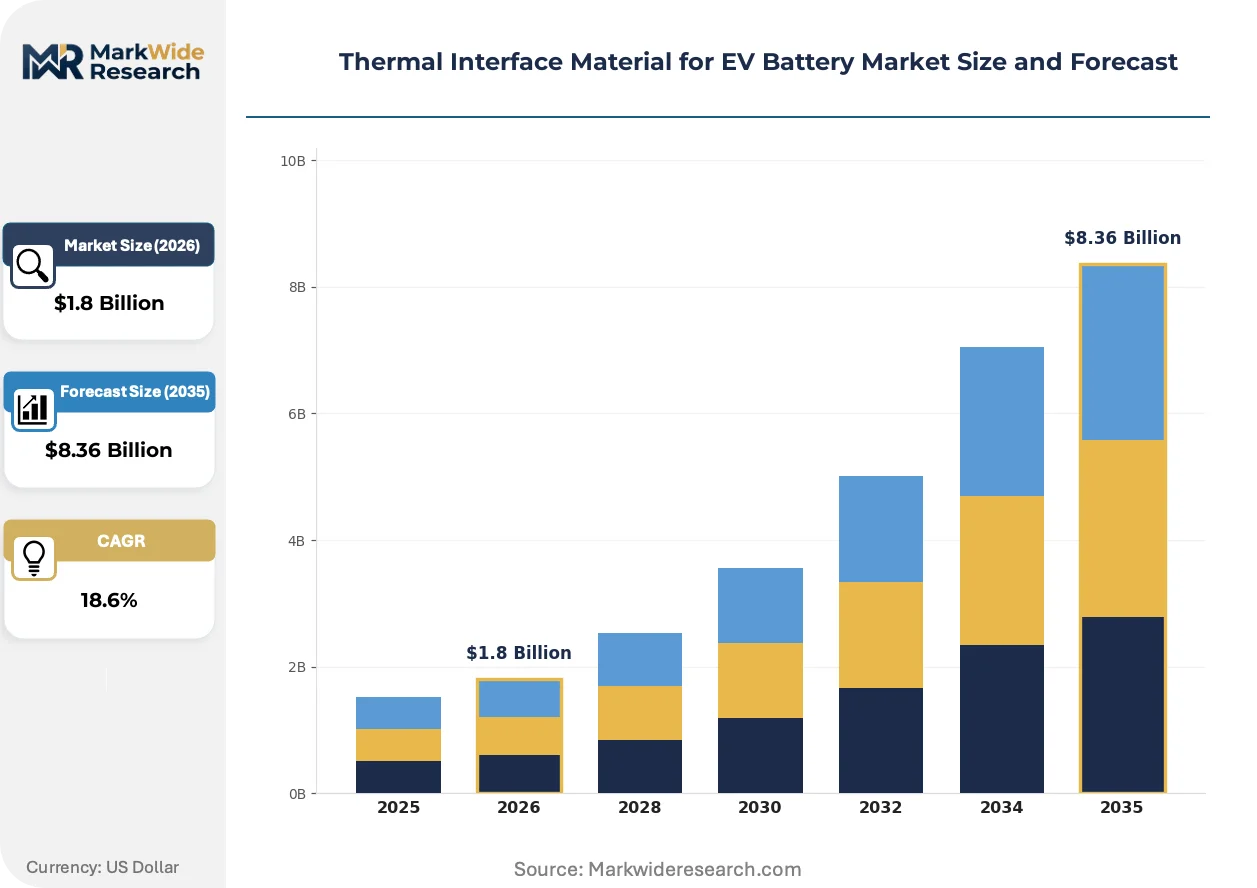
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grease, Gel, Film, Pad Application: Power Electronics, Thermal Management, Battery Pack, Heat Sink End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Phase Change Material, Conductive Polymer, Metal-based, Non-metallic |
| Companies Covered | Saint-Gobain Tape Solutions, JBC Technologies, Henkel, Parker Hannifin, Avery Dennison, DuPont, 3M, Jones Tech, Shin-Etsu Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Interface Material for EV Battery Market Trends and Innovations
Material science advances are collapsing the trade-off between thermal conductivity and electrical isolation, enabling thinner interface layers that free pack volume for active cell material.
Graphite-boron nitride hybrid fillers are unifying anisotropic heat spreading with through-plane conductivity in single-layer structures. Korean battery makers are qualifying these composites for 4680 cylindrical cell architectures. The technology is unifying what previously required separate spreader and gap-filler materials into one deposition step.
REACH restrictions on halogenated flame retardants are forcing reformulation of acrylic-based phase-change materials toward phosphorus-nitrogen synergists. Compounders must revalidate dielectric aging performance under these alternative chemistries. European pouch-cell producers are most exposed, as their thin aluminum housings offer less thermal mass than prismatic steel cases.
Fleet operators are consolidating thermal interface specifications across multiple OEM platforms to simplify aftermarket service inventory. Independent service networks are displacing captive dealer channels for battery refurbishment. This pattern is most visible in Germany, where commercial vehicle leasing companies operate mixed-brand electric fleets.
Thermal Interface Material for EV Battery Market Segmentation
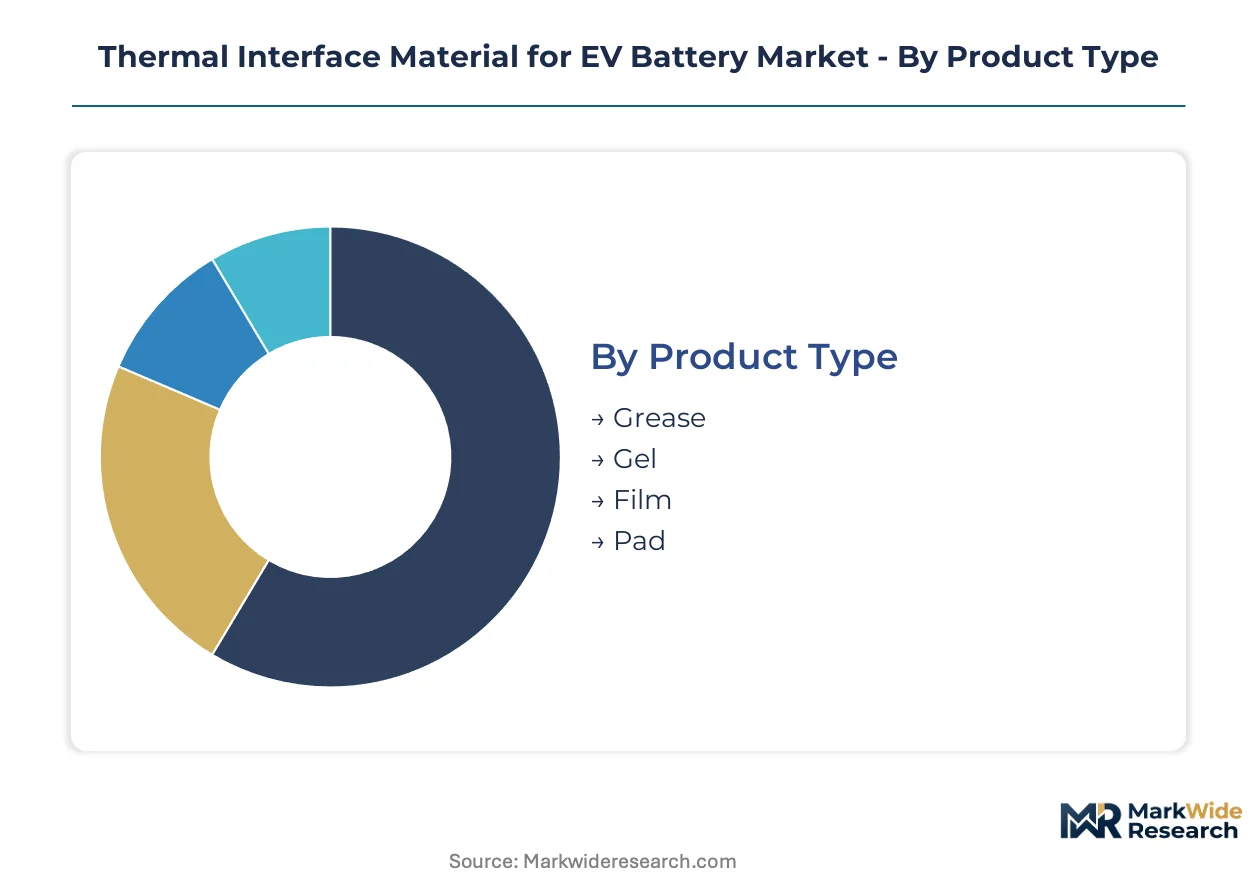
Thermal interface material specifications diverge sharply across battery architectures, forcing suppliers to maintain parallel formulation portfolios. Cell-to-pack designs compress layer thickness below 500 microns while prismatic platforms sustain thicker, more cost-tolerant pad specifications.
Product Type:
Buyers in this category differentiate primarily by reworkability needs versus manufacturing throughput priorities.
- Grease:Silicone or hydrocarbon-based compounds loaded with alumina or zinc oxide fillers that permit field disassembly for warranty repairs. Fleet operators in Germany specify grease formulations for commercial vehicle battery refurbishment contracts where module access remains economically critical.
- Gel:Cross-linked silicone matrices suspending boron nitride particles that sustain compression set resistance across -40°C to 150°C cycling. Korean battery makers are qualifying gel interfaces for 4680 cylindrical cell architectures where thermal uniformity across cell bottoms determines pack longevity.
- Film:Die-cut acrylic or silicone sheets with controlled thickness tolerance for high-speed automated assembly lines.
- Pad:Pre-cured silicone or fiberglass-reinforced composites that eliminate curing time in mass-market prismatic battery production.
Volume sits with Pad; growth tilts toward Gel.
Application:
Application selection tracks directly to heat flux density and electrical isolation requirements within the thermal path.
- Battery Pack:Multi-layer interfaces spanning cell-to-cell, cell-to-module, and module-to-cooling plate junctions in cell-to-pack architectures. Volkswagen's Zwickau plant sources phase-change materials for ID series battery packs where thermal runaway containment timelines now exceed 15 minutes under EU Battery Regulation mandates.
- Thermal Management:System-level heat rejection interfaces connecting cooling plates to chillers or ambient heat exchangers. BMW's Leipzig facility specifies conductive polymer sheets for iX thermal management circuits operating at sustained 3 kW/m² heat flux densities.
- Power Electronics:IGBT and SiC inverter interfaces demanding simultaneous thermal conductivity above 8 W/m·K and dielectric strength exceeding 6 kV/mm.
- Heat Sink:Discrete component cooling for onboard chargers and DC-DC converters in service-accessible locations.
Procurement weight centers on Battery Pack; specification complexity expands fastest in Thermal Management.
End User:
End user type determines qualification timeline tolerance and volume commitment scale.
- OEMs:Captive battery divisions at Volkswagen, BMW, and Mercedes-Benz that specify materials 24-36 months ahead of platform launch and demand dedicated production lines with locked formulations.
- Tier-1 Suppliers:Cell manufacturers and battery integrators such as CATL and LG Energy Solution operations in Germany that aggregate multi-OEM demand and negotiate filler loading customization.
- Vehicle Assemblers:Contract manufacturers and specialty EV producers purchasing qualified materials through distributor channels.
- Aftermarket Providers:Independent service networks and second-life battery repurposers prioritizing reworkable gel interfaces over permanent bonded solutions.
Contract value concentrates with OEMs; account expansion accelerates among Aftermarket Providers.
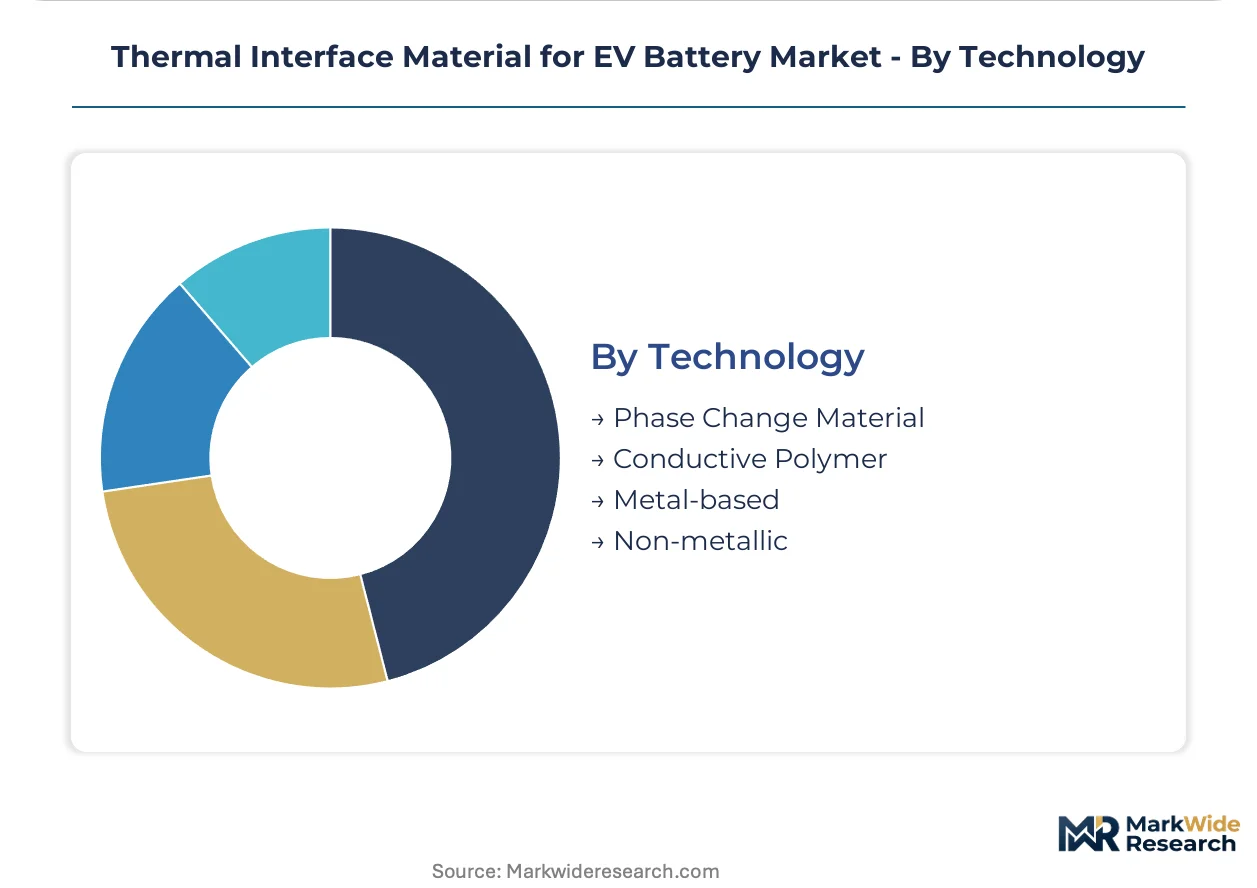
Technology:
Technology choice reflects the conductivity-isolation trade-off and operating temperature envelope.
- Phase Change Material:Paraffin or salt hydrate formulations that absorb latent heat at 45-60°C transition temperatures to dampen thermal spikes during fast charging. European pouch-cell producers are most exposed to REACH-driven reformulation of halogenated flame retardants in these materials.
- Conductive Polymer:Epoxy or acrylic matrices with aligned graphite fillers achieving anisotropic conductivity ratios exceeding 10:1. Henkel's Bergisch Gladbach facility supplies conductive polymer films to Mercedes-Benz EQ platform battery packs.
- Metal-based:Indium, gallium, or liquid metal alloys for extreme heat flux applications in performance EV inverters.
- Non-metallic:Ceramic-filled silicone and boron nitride composites that dominate cost-optimized mass-market specifications.
Shipments run heaviest through Non-metallic; technology investment flows toward Phase Change Material.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zwickau anchors European thermal interface material procurement through Volkswagen's dedicated EV battery assembly complex, where phase-change material specifications now exceed 15-minute thermal runaway containment timelines under EU Battery Regulation mandates. Procurement concentration across Germany, South Korea, China, and the United States shapes supplier qualification priorities and regional formulation requirements.
Germany
Volkswagen's Zwickau plant and BMW's Leipzig facility drive specification intensity for conductive polymer sheets and phase-change materials. ECHA REACH restrictions on halogenated flame retardants force reformulation of acrylic-based thermal layers. Stuttgart anchors Mercedes-Benz EQ platform battery pack assembly, sourcing customized filler loading from Henkel's Bergisch Gladbach facility.
South Korea
LG Energy Solution and Samsung SDI operations concentrate demand for boron nitride-loaded silicone gels in 4680 cylindrical cell architectures. MFDS chemical substance notifications intersect with automotive thermal management standards. Gyeonggi Province battery cell clusters qualify gel interfaces where thermal uniformity across cell bottoms determines pack longevity.
China
CATL and BYD scale procurement of ceramic-filled silicone composites for prismatic and blade-cell platforms. MIIT new energy vehicle safety standards mandate thermal runaway propagation testing exceeding five minutes. Ningbo and Shenzhen industrial corridors concentrate domestic compounding capacity for alumina and boron nitride filler supply.
United States
Tesla's Nevada Gigafactory and Ford's BlueOval SK joint venture in Kentucky drive qualification timelines for non-metallic thermal pads. NHTSA vehicle safety standards and emerging battery passport frameworks shape compliance investments. Michigan automotive clusters source reworkable grease formulations for commercial vehicle battery refurbishment networks.
India
Reliance Industries and Ola Electric expand domestic cell manufacturing under PLI scheme subsidies, creating first-mover positioning for TIM suppliers establishing local compounding. BIS certification requirements for automotive components extend to thermal management materials. Gujarat and Tamil Nadu industrial corridors concentrate emerging battery assembly investments.
Thermal Interface Material for EV Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across dielectric performance and filler customization capabilities, with formulation IP separating tier-1 qualification from mass-market supply. The vendor base spans adhesive chemistry specialists, diversified materials conglomerates, and regional compounders serving single OEM platforms. Three archetypes dominate: integrated chemical companies controlling polymer supply, precision film converters with cleanroom assets, and filler technology specialists licensing boron nitride loading protocols. Capacity expansion and strategic partnerships represent the dominant competitive moves, as qualification timelines extend beyond 24 months and locked formulations create switching costs.
Within the integrated chemical tier, Henkel and Shin-Etsu Chemicals occupy positions reflecting adhesive chemistry heritage and medical-grade silicone polymer supply respectively. Among diversified materials conglomerates, Saint-Gobain Tape Solutions and DuPont exemplify multi-continent production footprints spanning automotive and industrial thermal management applications. 3M represents the precision film conversion archetype with dielectric sheet capabilities.
| Leading Market Players |
|---|
| Saint-Gobain Tape Solutions |
| JBC Technologies |
| Henkel |
| Parker Hannifin |
| Avery Dennison |
| DuPont |
| 3M |
| Jones Tech |
| Shin-Etsu Chemicals |
| Others |
Pricing and Supply Chain Analysis
Alumina filler costs cascade from energy-intensive Chinese smelting operations through three pricing tiers: premium phase-change materials for cell-to-pack architectures, mid-grade silicone gels for cylindrical cell platforms, and economy ceramic-filled pads for prismatic mass-market batteries. Boron nitride powder prices hinge on Shin-Etsu and Wacker polymer supply allocations, concentrating margin pressure on gel formulators serving Korean battery makers.
Pricing Analysis
Yield-per-watt thermal performance anchors value-based pricing, with dielectric strength certification separating premium formulations from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects filler loading density and REACH compliance status. Cost compression in the pad segment is intensifying because Chinese compounders scale alumina-filled silicone output for domestic EV producers. Tier-1 suppliers exhibit lowest price sensitivity due to locked 24-36 month formulation commitments, while aftermarket providers negotiate spot purchases on reworkable grease specifications.
Supply Chain Analysis
Medical-grade silicone polymer supply rests on Shin-Etsu and Wacker production footprints in Japan and Germany, tethering gel-based TIM output to pharmaceutical-sector polymer allocation priorities. Ceramic filler feedstock draws from Chinese alumina refineries and Turkish boron operations, with logistics chokepoints at Rotterdam and Singapore container hubs. Single-source polymer dependence creates vulnerability for European compounders qualifying materials under ECHA REACH timelines. Distribution runs through qualified tier-1 battery integrators rather than open distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom compounding capacity scarcity props pricing for sub-100-micron film specifications, constraining supply expansion faster than cell-to-pack adoption accelerates demand.
For Market Incumbents: Anticipate REACH-driven flame-retardant reformulation cycles by securing phosphorus-nitrogen synergist supply agreements ahead of authorization delays. Defensive consolidation through backward integration into boron nitride filler processing mitigates raw material volatility exposure. Capacity addition in Gujarat and Tamil Nadu industrial corridors captures PLI-subsidized Indian cell manufacturing demand before qualification timelines extend. For New Entrants and Emerging Players: The mid-tier price-point gap between Henkel conductive polymers and Chinese ceramic-filled pads offers white-space positioning for customized gel formulations serving second-life battery repurposers. India's emerging domestic cell manufacturing under PLI subsidies represents the most penetrable geography, with BIS certification requirements creating qualification barriers favoring early facility investment. Go-to-market leverage rests on AI-enabled thermal modeling partnerships that reduce OEM validation cycles. For Investors and Strategic Acquirers: OEM announcement of dedicated cell-to-pack platform commitments is the leading indicator that phase-change material demand inflection is materializing. Long-term viability across the analysis window favors precision film converters with ISO Class 7 assets and locked tier-1 supplier qualifications. Acquisition target archetype: regional compounders with boron nitride loading IP and existing automotive thermal management certifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filler Processing | Captive alumina and boron nitride supply secures margin stability against Chinese smelting volatility. |
| Cleanroom Capacity Expansion | ISO Class 7 film production assets qualify sub-100-micron specifications for Volkswagen and BMW platforms. |
| REACH-Compliant Flame Retardant Reformulation | Phosphorus-nitrogen synergist validation maintains EU market access for pouch-cell thermal materials. |
| India Compounding Facility Establishment | Local production meets BIS certification requirements for Reliance Industries and Ola Electric supply. |
| AI-Enabled Thermal Modeling Partnership | Predictive simulation tools reduce OEM qualification timelines through customized filler loading optimization. |
Research Methodology
Independent corroboration across OEM platform engineers, tier-1 battery integrator procurement leads, thermal materials R&D directors, and aftermarket service network operators underwrites the qualitative findings in this study. Primary interview inputs combined with MIIT safety standard filings, ECHA REACH substance databases, customs trade data for alumina and boron nitride flows, and SEC disclosures from diversified materials conglomerates enable bottom-up and top-down triangulation.
Rate-of-change decomposition across product type, application heat flux density, end-user qualification timeline, and technology conductivity-isolation trade-off dimensions structures the analytical framework. CAGRs derive from segment-level volume build-ups calibrated to battery production capacity announcements and content-per-pack assumptions. Forecast inputs incorporate cell-to-pack adoption curves, solid-state battery thermal management requirements, and second-life repurposing demand patterns.
Inputs from OEM platform roadmaps and tier-1 supplier qualification timelines were available through the study window; gaps in aftermarket provider procurement data introduce uncertainty bands around second-life battery segment sizing. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and polymer supply allocation priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Materials Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Auto Storage Battery Market
EV Batteries
US EV Battery Pack Market