
 Italy Electric Vehicle Battery Manufacturing Market | 2026-2036
Italy Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electric Vehicle Battery Manufacturing Market Insights
Project finance tied to EU Innovation Fund grants and green bond issuance is reconfiguring capital requirements for Italian battery producers. Flash Battery leverages its specialization in lithium-iron-phosphate systems for industrial vehicles to anchor a defensible niche against multinational competitors. Midac Batteries sustains decades of lead-acid expertise while navigating the transition toward lithium-ion architectures for automotive contracts. FIAMM SpA competes through its established relationships with European OEMs and energy storage applications.
Italy electric vehicle battery manufacturing encompasses the industrial production of electrochemical energy storage devices, specifically cells and packs with nominal voltages ranging from 48V to 800V and energy densities exceeding 250 Wh/kg for premium automotive applications. These systems store and discharge electrical energy through reversible redox reactions, enabling propulsion in battery electric vehicles and plug-in hybrids while supporting vehicle-to-grid integration. Lithium-ion chemistries dominate current output, though solid-state architectures promise higher energy density and improved thermal stability as manufacturing scales mature. Among end users, automakers command the largest procurement volumes, while fleet operators represent the fastest-expanding segment as logistics electrification accelerates across Italian commercial corridors.
Italy's battery sector operates under the EU Battery Regulation, which imposes due diligence obligations and recycled content mandates enforced by national market surveillance authorities. CE marking requirements under the MDR framework and alignment with REACH chemical restrictions further constrain material sourcing and cell design choices. Stakeholders must monitor how delegated acts under the EU Battery Regulation define performance classes and carbon intensity thresholds, as these will determine which Italian manufacturers qualify for preferred supplier status with domestic and European OEMs.
Market Dynamics
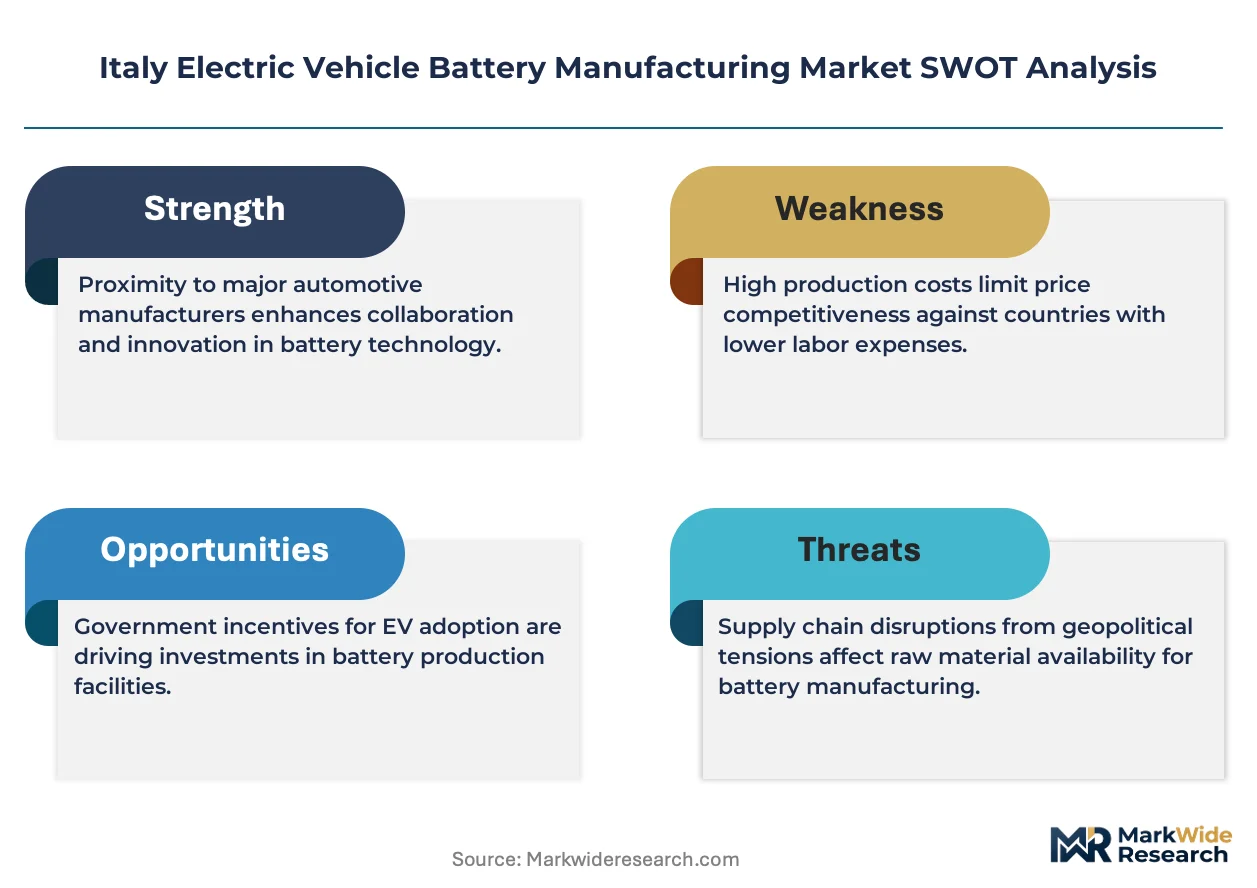
EU Battery Regulation mandates on recycled content and carbon footprint declarations are compressing the competitive set, forcing Italian producers to reconfigure cathode sourcing and cell assembly lines ahead of delegated acts defining performance classes.
Growth Catalysts
- EU Innovation Fund:Project finance through green bonds and grants lowers capital barriers for Piedmont-based gigafactory investments. Battery producers secure non-dilutive funding streams that multinational competitors cannot replicate.
- Stellantis electrification roadmap:The automaker's accelerated EV platform rollout generates anchored offtake agreements for domestic cell suppliers. Turin manufacturing clusters benefit from co-located testing and pack assembly.
- Lithium-iron-phosphate chemistries:Industrial vehicle electrification demands thermal-stable, cycle-durable cells for logistics corridors. Italian specialists capture fleet operator procurement with chemistry-optimized solutions.
Market Restraints
- Cathode precursor concentration:Nickel and cobalt refining capacity concentrates in Southeast Asian and African supply chains. Italian manufacturers face input cost volatility and geopolitical transit risks for critical raw materials.
- REACH chemical restrictions:ECHA substance authorization processes constrain electrolyte additive selection and binder chemistry. Reformulation timelines extend product qualification cycles by 12-18 months.
- Lead-acid substitution ceiling:Industrial starter battery applications retain cost advantages for conventional chemistries in price-sensitive aftermarket channels. Lithium-ion penetration stalls in certain commercial vehicle segments.
Strategic Opportunities
- Southern Italy manufacturing zones:Underutilized industrial land in Sicily and Apulia offers labor cost arbitrage and port access for North African raw material imports. Regional development incentives attract secondary supply chain nodes.
- Vehicle-to-grid integration:Bidirectional charging hardware converges with stationary storage applications. Italian producers can dual-purpose automotive cell designs for residential and commercial energy systems.
- EU Battery Regulation delegated acts:Pending carbon intensity thresholds will create preferred supplier tiers. Early compliance investments position domestic manufacturers for OEM qualification advantages.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management expertise concentrates in Asian and German labor markets. Italian technical universities must expand specialized curricula to feed domestic pipeline needs.
- Gigafactory capex intensity:Dry electrode coating and formation equipment require billion-euro facility commitments. Capital deployment timing misalignment with offtake contract finalization creates financing gaps.
- CE marking timeline compression:MDR framework documentation and notified body review queues extend market entry schedules. Parallel EU Battery Regulation conformity assessments compound certification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electric Vehicle Battery Manufacturing Market |
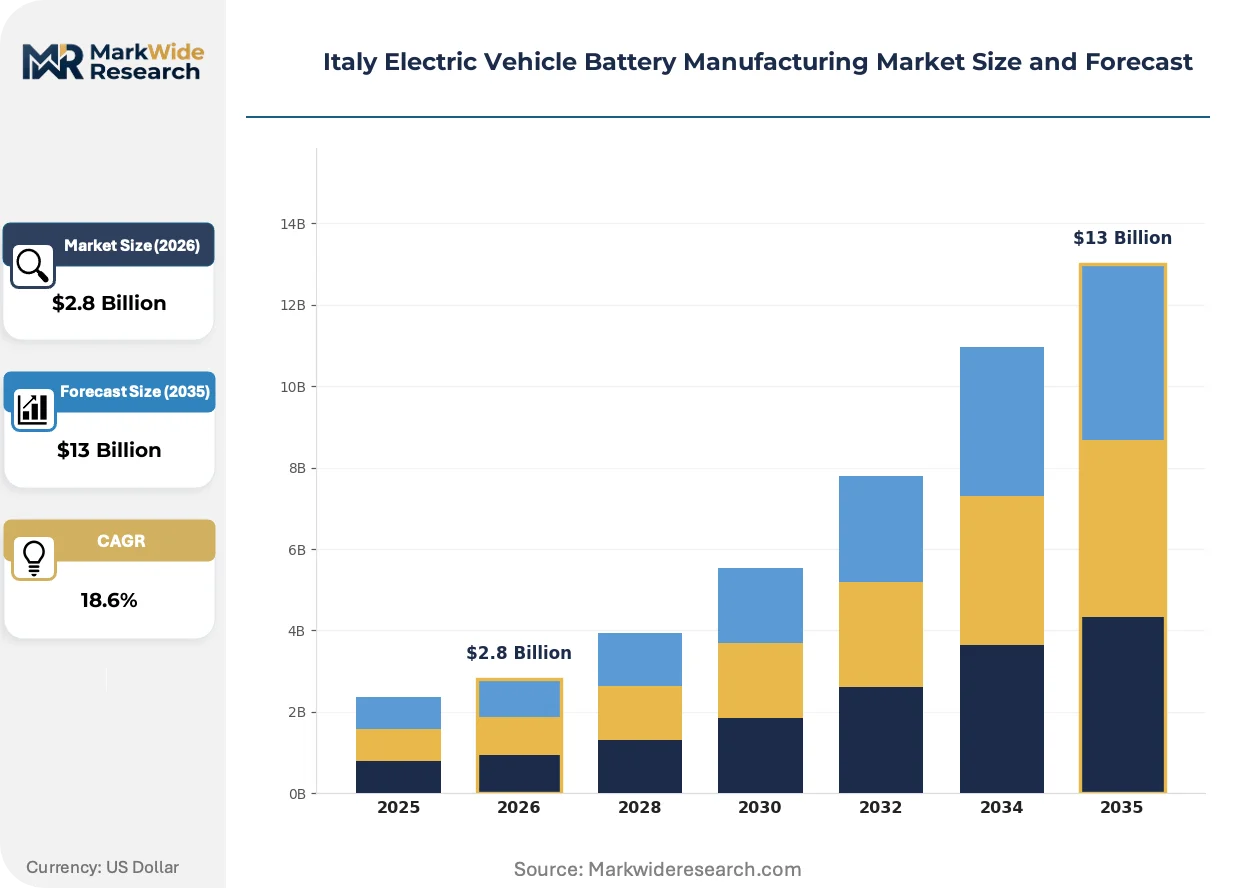
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state End User: Automakers, Aftermarket Providers, Fleet Operators, Public Transportation Technology: Manufacturing Process, Recycling Technology, Energy Management, Battery Management Systems Distribution Channel: Direct Sales, Online Retail, Distributors, Exporters |
| Companies Covered | Flash Battery, Midac Batteries, Itavolt, FIAMM SpA, Saft Groupe SA, FAAM, Voltmec, Aliant Battery, Sovema Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electric Vehicle Battery Manufacturing Market Trends and Innovations
Solid-state cell architectures and dry electrode manufacturing are compressing incumbent process advantages, while regulatory carbon accounting and procurement model evolution reshape how Italian producers compete for OEM qualification.
Dry electrode coating eliminates solvent-based slurry processing and reduces formation energy consumption by half. Stellantis and Ferrari supplier development teams are qualifying electrode stacks from Italian pilot lines for 2026 platform integration. This manufacturing shift is rendering obsolete wet-casting equipment investments that anchored previous generation capacity decisions.
EU Battery Regulation carbon footprint declarations require granular Scope 3 accounting from mine to module. ECHA enforcement mechanisms and national market surveillance authorities in Italy are developing audit protocols for cell passport documentation. Premium automotive OEMs now mandate supplier disclosure thresholds that disqualify uncertified producers from RFQ participation.
Fleet operators in Milan and Rome logistics corridors are consolidating procurement through battery-as-a-service contracts. Third-party asset ownership replaces capital expenditure models for electric van and truck deployments. This financing structure concentrates buyer power with leasing platforms and energy service companies, compressing direct manufacturer margins while expanding volume commitments.
Italy Electric Vehicle Battery Manufacturing Market Segmentation
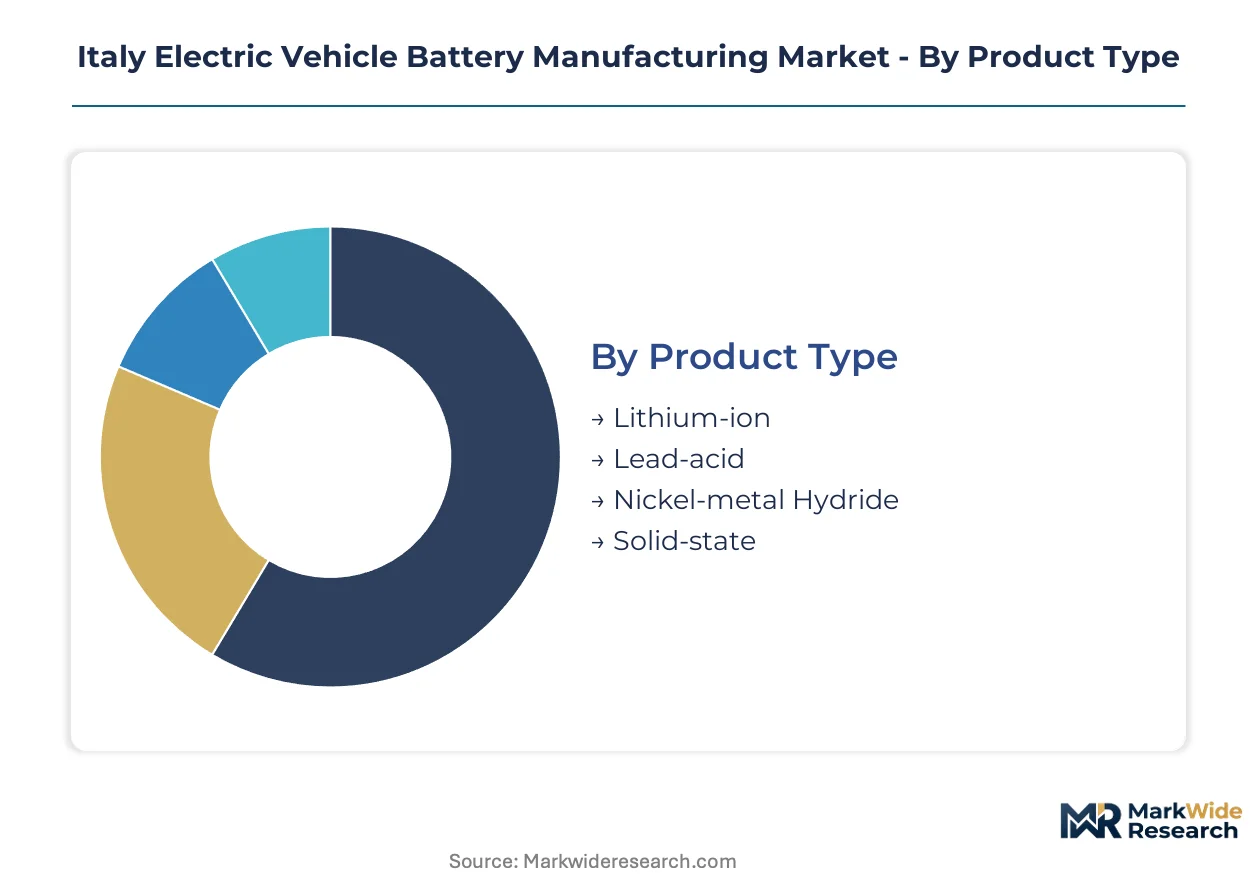
Segmentation reveals how Italian battery manufacturers allocate engineering resources across divergent technical requirements and procurement models. Each dimension exposes distinct margin structures and qualification barriers that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across chemistries, with solid-state architectures demanding specialized diagnostic capabilities and lithium-ion requiring thermal management field support.
- Lithium-ion:Dominant cell chemistry utilizing layered oxide cathodes and graphite anodes with energy densities above 250 Wh/kg. Stellantis platform integration in Turin-Piedmont clusters drives procurement concentration, though ECHA REACH compliance for electrolyte additives extends qualification cycles.
- Solid-state:Emerging architecture replacing liquid electrolytes with ceramic or polymer conductors for improved thermal stability. Ferrari supplier development programs anchor pilot demand, with dry electrode coating investments compressing formation energy requirements.
- Lead-acid:Mature flooded and absorbed glass mat designs for starter and industrial applications. Midac Batteries sustains aftermarket channel presence despite lithium-ion substitution pressure in commercial vehicle segments.
- Nickel-metal Hydride:Legacy chemistry retaining niche applications in hybrid powertrains and stationary buffering. Limited Italian production capacity concentrates import dependence on Japanese and Korean suppliers.
Lithium-ion holds the largest share; momentum sits with solid-state.
End User:
Cost tier stratification separates capital-intensive automaker contracts from working-capital-light aftermarket replenishment cycles.
- Automakers:OEM qualification mandates cells and packs with 48V to 800V nominal ranges and 10-year cycle warranties. Stellantis electrification roadmaps generate anchored offtake agreements for Piedmont-based suppliers.
- Fleet Operators:Logistics electrification across Milan and Rome corridors drives battery-as-a-service procurement consolidation. Third-party asset ownership models compress direct manufacturer margins while expanding volume commitments.
- Aftermarket Providers:Replacement battery distribution for existing vehicle parc through service center networks. Price-sensitive channels retain lead-acid preference for starter applications in commercial segments.
- Public Transportation:Municipal bus and rail electrification tenders with extended payment terms and localization requirements. Regional development incentives in Southern Italy attract secondary supply chain nodes for fleet deployments.
Automakers command the largest procurement volumes; fleet operators are expanding most quickly.
Technology:
Application focus distinguishes process equipment investments from software-defined energy optimization layers.
- Manufacturing Process:Dry electrode coating and formation equipment eliminating solvent-based slurry processing. Stellantis supplier qualification programs validate Italian pilot lines for platform integration.
- Battery Management Systems:Cell balancing algorithms and thermal runaway protection firmware. CE marking under MDR framework and parallel EU Battery Regulation assessments compound certification burdens for domestic producers.
- Recycling Technology:Hydrometallurgical and pyrometallurgical recovery of lithium, cobalt, and nickel from end-of-life cells. EU Battery Regulation recycled content mandates force cathode sourcing reconfiguration ahead of delegated acts.
- Energy Management:Vehicle-to-grid integration hardware enabling bidirectional charging for residential and commercial stationary storage. Dual-purpose automotive cell designs expand addressable market beyond propulsion applications.
Manufacturing Process holds the largest share; momentum sits with Battery Management Systems.
Distribution Channel:
Customer type determines contract structure, with direct sales requiring embedded engineering support and distributor networks demanding price protection mechanisms.
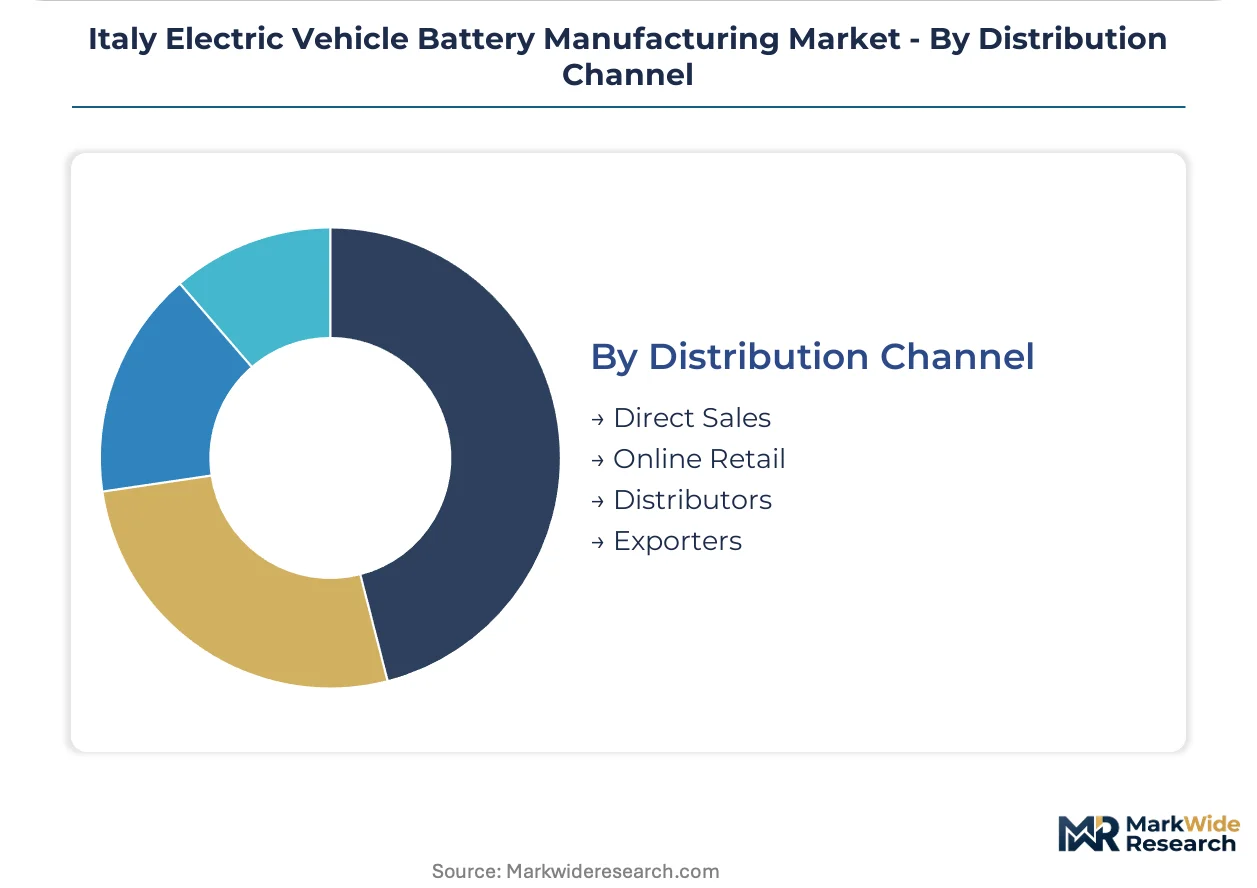
- Direct Sales:Long-term supply agreements with OEMs and fleet operators specifying volume commitments and technical collaboration clauses. Flash Battery leverages direct relationships for lithium-iron-phosphate industrial vehicle specialization.
- Distributors:Inventory carrying intermediaries serving aftermarket providers and smaller fleet operators. Regional coverage requirements fragment order concentration across multiple wholesaler relationships.
- Online Retail:E-commerce platforms for replacement batteries in consumer and light commercial segments. Limited penetration for high-voltage automotive applications due to installation complexity and safety certification requirements.
- Exporters:Cross-border shipments to European OEMs and energy storage integrators. Port access in Sicily and Apulia supports North African raw material import logistics for export-oriented production.
Direct Sales holds the largest share; momentum sits with Exporters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Innovation Fund grants and green bond issuance are reconfiguring capital flows across Italian sub-regions, with Piedmont anchoring gigafactory investments and Southern zones attracting secondary supply chain nodes through development incentives.
Piedmont
Stellantis electrification roadmaps generate anchored offtake agreements for Turin-based cell suppliers. ECHA REACH compliance requirements extend qualification cycles for electrolyte additive formulations. The Turin manufacturing cluster draws co-located testing facilities and cathode material suppliers seeking proximity to OEM development centers.
Lombardy
Milan and Rome logistics corridors drive fleet operator procurement consolidation for battery-as-a-service contracts. CE marking under the MDR framework compounds certification burdens for domestic producers seeking automotive qualification. The Milan metro zone hosts energy service companies consolidating buyer power through third-party asset ownership models.
Sicily
Underutilized industrial land offers labor cost arbitrage and port access for North African raw material imports. Regional development incentives attract secondary supply chain nodes seeking export-oriented production bases. The Port of Catania supports logistics for cross-border shipments to European OEMs and energy storage integrators.
Apulia
Port infrastructure in Taranto and Bari enables cathode precursor import routes bypassing congested Northern European gateways. The national market surveillance authority coordinates with ECHA on audit protocols for cell passport documentation. Brindisi industrial zones target formation equipment deployment for dry electrode coating pilot lines.
Emilia-Romagna
Automotive supplier networks in Modena and Bologna extend into pack assembly and battery management system integration. EU Battery Regulation delegated acts on carbon intensity thresholds drive early compliance investments among component specialists. The region's technical universities feed electrochemical engineering pipelines for thermal management and cell design roles.
Italy Electric Vehicle Battery Manufacturing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across direct OEM supply agreements and distributor-served aftermarket channels. The structure concentrates around anchored offtake relationships with Stellantis and Ferrari supplier development programs, while fragmented industrial vehicle and stationary storage segments sustain niche specialists. Three archetypes dominate: chemistry-specialized cell producers, legacy lead-acid incumbents navigating lithium transitions, and system integrators bundling hardware with energy management software. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with dry electrode coating investments compressing formation energy requirements and platform integration timelines.
Among Italy-based producers, Flash Battery and Midac Batteries exemplify divergent transition strategies within the domestic competitive set. Flash Battery occupies a position anchoring the lithium-iron-phosphate specialization archetype for industrial vehicle applications. Midac Batteries represents the legacy incumbent archetype, sustaining decades of lead-acid expertise while navigating architectural shifts toward lithium-ion automotive contracts. FIAMM SpA sits within the established European supplier tier, competing through OEM relationship depth and cross-application energy storage positioning. These three producers collectively illustrate how Italian manufacturers segment across chemistry focus, customer channel control, and vertical scope choices.
| Leading Market Players |
|---|
| Flash Battery |
| Midac Batteries |
| Itavolt |
| FIAMM SpA |
| Saft Groupe SA |
| FAAM |
| Voltmec |
| Aliant Battery |
| Sovema Group |
| Others |
Pricing and Supply Chain Analysis
The Port of Catania freight corridor channels North African nickel and cobalt precursors into Italian cell plants, its cost volatility amplifying the spread between EU Battery Regulation-certified premium packs and uncertified economy alternatives while compressing margins for mid-tier producers lacking anchored offtake agreements.
Pricing Analysis
Certification level under EU Battery Regulation and CE marking frameworks creates the primary spread between qualified and unqualified suppliers. Contract-based long-term offtake agreements with Stellantis and Ferrari anchor premium pricing for Piedmont-based manufacturers, while spot-market cathode sourcing exposes second-tier producers to commodity-driven cost compression. Fleet operators consolidating procurement through battery-as-a-service platforms exert the strongest price sensitivity, whereas automaker qualification mandates permit pass-through of compliance investments.
Supply Chain Analysis
Contract manufacturing for electrode coating and formation stages concentrates among German and South Korean equipment vendors with established automotive qualification track records. Cathode precursor refining draws from Indonesian nickel and Congolese cobalt supply chains, with electrolyte additive sourcing resting on Chinese chemical manufacturers. Single-source vulnerability in high-purity lithium hydroxide creates structural exposure to export licensing disruptions. Distribution runs through direct OEM supply agreements for automotive applications, while aftermarket channels fragment across regional distributors serving price-sensitive replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where EU Battery Regulation compliance timelines and OEM qualification barriers erect switching costs that entrench early movers against latecomers lacking certification runway.
For Market Incumbents: Harden supplier development relationships with Stellantis and Ferrari through co-located pilot line investments in dry electrode coating. Deepen backward integration into cathode precursor sourcing via North African joint ventures to offset Southeast Asian supply concentration. Flash Battery and Midac Batteries must accelerate lithium-ion qualification cycles before REACH reformulation timelines extend competitor gaps. For New Entrants and Emerging Players: Build out vehicle-to-grid integration capabilities targeting Milan and Rome energy service companies as the most penetrable procurement channel. Southern Italy manufacturing zones in Sicily and Apulia offer labor cost arbitrage for secondary supply chain nodes. A go-to-market angle anchored in carbon passport documentation services addresses OEM delegated act preparation needs. For Investors and Strategic Acquirers: Carve-out targets emerge from European automotive supplier conglomerates divesting non-core battery management system divisions. Long-term viability centers on producers achieving EU Battery Regulation performance class qualification before carbon intensity thresholds harden. The signal to watch is Stellantis platform integration announcements triggering anchored offtake competition.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Coating Investment | Reduces formation energy consumption by half for Stellantis platform qualification. |
| Cathode Precursor Joint Venture | Secures North African nickel supply bypassing Southeast Asian refining bottlenecks. |
| Battery-as-a-Service Partnership | Captures fleet operator procurement consolidation across Milan-Rome logistics corridors. |
| EU Battery Regulation Early Compliance | Positions manufacturers for preferred supplier tiers under pending carbon intensity thresholds. |
| Vehicle-to-Grid Hardware Integration | Dual-purposes automotive cells for residential energy storage applications. |
Research Methodology
A standing panel of OEM platform engineers, cathode material procurement leads, ECHA regulatory affairs specialists, and fleet operator energy managers provided ongoing calibration across primary interview rounds. Secondary validation drew from EU Battery Regulation delegated act drafts, ECHA REACH substance authorization databases, Stellantis electrification roadmap disclosures, and Italian customs import records for lithium hydroxide and nickel sulfate. Bottom-up cell production capacity estimates triangulated against top-down automotive electrification demand projections.
Scenario bracketing around Stellantis platform rollout timing and EU Battery Regulation enforcement intensity shaped volume trajectories across the projection horizon. Segmentation dimensions modeled include cell chemistry architecture, end-user procurement model, nominal voltage class, and regional manufacturing cluster. CAGRs derived from fitted growth curves incorporating cathode price elasticity coefficients and OEM qualification lag parameters.
Stress conditions across Indonesian export licensing disruptions, ECHA electrolyte additive ban expansions, and green bond issuance volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on delegated act finalization pacing and OEM platform standardization timelines. Quarterly review of Stellantis supplier qualification announcements and ECHA substance authorization updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
European EV Battery Systems Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
North America Electric Vehicle Battery Materials Market