
 Brazil Data Center Networking Market | 2026-2036
Brazil Data Center Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Networking Market Insights
Wholesale distribution channels for networking hardware are reshaping how vendors reach Brazilian data center operators. Cisco Systems Inc. leverages its certified partner ecosystem to dominate enterprise routing deployments across the country. Juniper Networks Inc. specializes in high-performance switching for financial services data centers in São Paulo. Huawei Technologies Co. Ltd. competes aggressively on price-performance metrics for state-backed cloud infrastructure projects.
Brazil data center networking encompasses the physical and virtual infrastructure enabling data transmission, storage access, and traffic management within and between computing facilities, operating across Layer 2-7 protocols with throughput specifications ranging from 10 Gbps to 400 Gbps per port. Ethernet switches constitute the largest product category by installed base, though InfiniBand adoption accelerates among AI training clusters requiring sub-microsecond latency. SDN technology captures expanding share as cloud providers automate multi-tenant provisioning across colocation and hybrid deployment models. On-premises deployment retains dominance in regulated sectors such as banking and healthcare where data sovereignty requirements restrict off-site processing.
ANATEL certification mandates govern all telecommunications equipment marketed in Brazil, creating compliance barriers that favor established suppliers with local testing partnerships. BIS-equivalent national standards and ANVISA data protection rules for healthcare workloads further segment product requirements by end-use vertical. Stakeholders must monitor pending updates to Brazil's national data center efficiency framework and evaluate how emerging local content requirements under federal procurement rules will alter supplier qualification criteria for government cloud contracts.
Market Dynamics
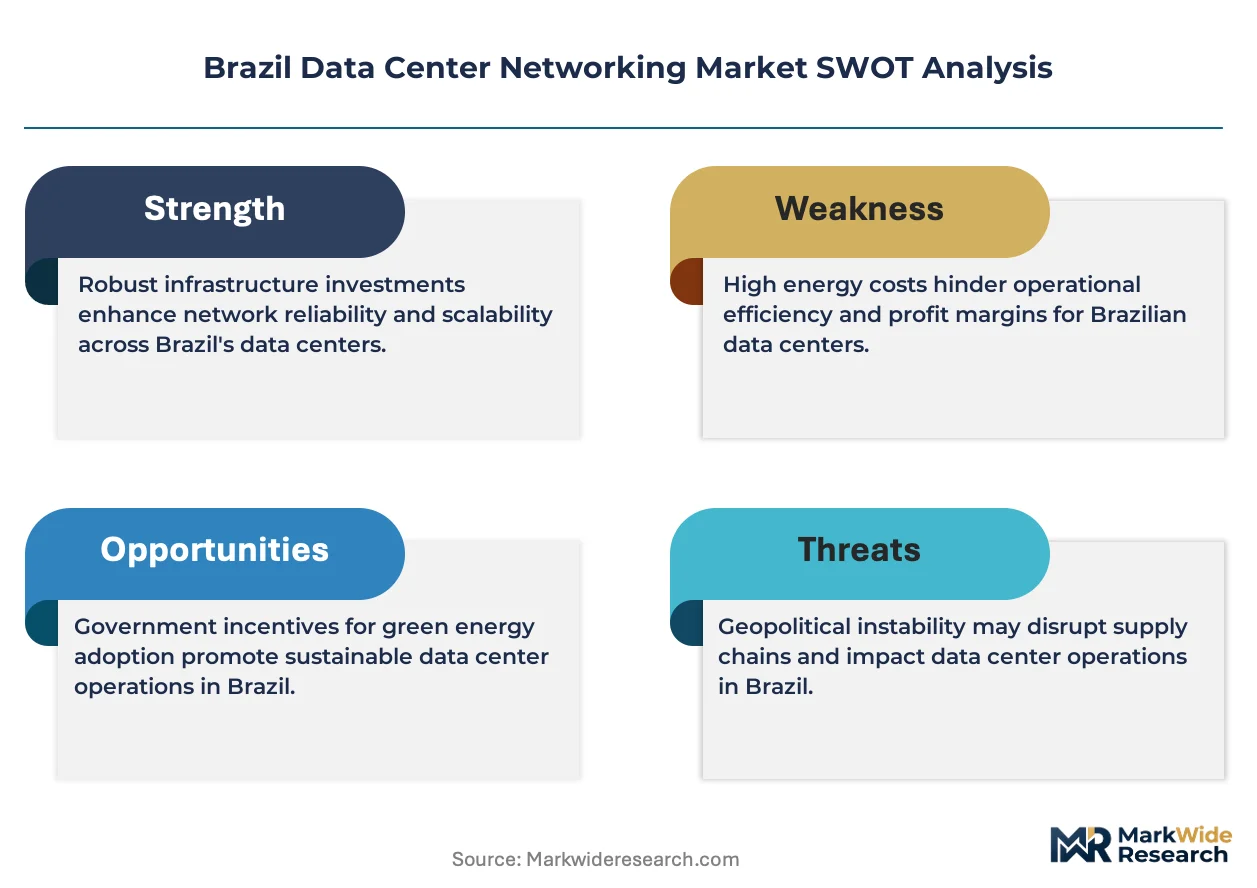
ANATEL's tightening certification timelines are compressing vendor qualification cycles, forcing established suppliers to accelerate local testing partnerships while freezing out smaller competitors lacking São Paulo laboratory access.
Growth Catalysts
- Hyperscale Cloud Expansion:São Paulo-Rio de Janeiro corridor operators are scaling 400 Gbps spine-leaf architectures to support multi-tenant AI training clusters, driving switch port density requirements upward.
- PLI-Style Incentives:Federal data center efficiency frameworks under development will reward facilities achieving PUE below 1.3 with tax credits, stimulating networking hardware refresh cycles.
- InfiniBand Migration:Financial services data centers in São Paulo are deploying RDMA-capable networks for high-frequency trading workloads, creating specialized demand for sub-microsecond latency infrastructure.
Market Restraints
- Import Duty Structure:ICMS state tax variations and IPI federal levies on telecommunications equipment inflate landed costs by 35-60% versus regional benchmarks, constraining budget elasticity for mid-tier colocation operators.
- Testing Bottleneck:ANATEL's three accredited laboratories in São Paulo face 6-9 month backlogs for new product homologation, delaying vendor time-to-revenue.
- Copper-Fiber Price Volatility:Optical transceiver component shortages and fiber cable import dependencies expose operators to exchange rate-driven cost spikes.
Strategic Opportunities
- Northeast Corridor Development:Fortaleza and Recife submarine cable landing stations are attracting edge computing investments, creating greenfield networking demand outside the saturated southeast.
- SD-WAN Convergence:Managed service providers are bundling software-defined WAN with colocation cross-connects, opening recurring revenue streams for infrastructure vendors.
- Healthcare Data Sovereignty:ANVISA-mandated local storage for patient records is driving hospital group investment in certified on-premises networking, bypassing public cloud restrictions.
Industry Challenges
- Certified Engineer Scarcity:CCIE and JNCIE-level professionals command 40% salary premiums in São Paulo, stretching operator opex for complex spine-leaf deployments.
- Multi-Vendor Integration Friction:Legacy Cisco environments resist seamless SDN controller integration with white-box switches, prolonging migration timelines and requiring custom API development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Networking Market |
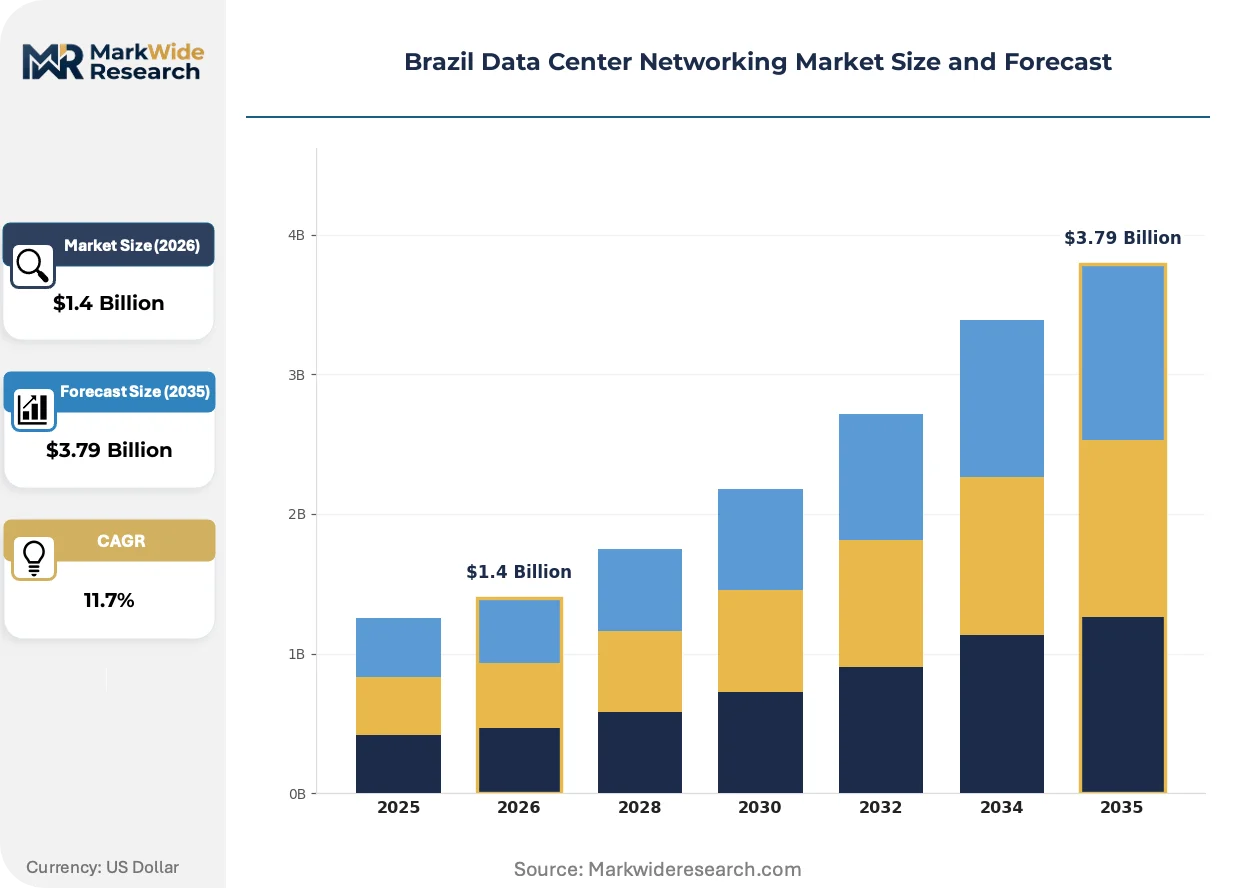
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Firewalls, Load Balancers Technology: Ethernet, Fiber Channel, InfiniBand, SDN End User: Telecommunications, IT Services, Cloud Providers, Enterprises Deployment: On-Premises, Colocation, Hybrid, Managed |
| Companies Covered | Cisco Systems Inc., Juniper Networks Inc., Huawei Technologies Co. Ltd., Schneider Electric, Eaton Corporation, Dell Technologies, NVIDIA, Emerson Electric Co., HP Development Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Networking Market Trends and Innovations
Silicon photonics and co-packaged optics are compressing power-per-bit economics, while regulatory pressure on data sovereignty accelerates architectural decisions around traffic localization and interconnection topology.
Co-packaged optical engines are replacing pluggable transceivers in top-of-rack switches, collapsing electrical trace lengths and cutting SerDes power by half. Hyperscale operators in São Paulo are piloting 51.2 Tbps silicon photonics switches for 2025 deployment. This integration is rendering obsolete the discrete optical module supply chain that dominated 100 Gbps and 400 Gbps generations.
ANATEL's revised Resolution 242 has tightened electromagnetic compatibility testing for data center switching equipment, requiring additional anechoic chamber validation. Vendors must now submit updated technical files for product line extensions previously grandfathered under older certifications. Banking and healthcare verticals are prioritizing suppliers with pre-approved hardware portfolios to avoid procurement delays.
Consumption-based networking procurement is displacing traditional capital purchase models among mid-market colocation tenants. Operators are offering cross-connect and port capacity as metered utilities, transferring switch hardware risk to facility owners. This shift is most pronounced in São Paulo's wholesale data centers serving fintech and e-commerce scale-ups with unpredictable traffic growth patterns.
Brazil Data Center Networking Market Segmentation
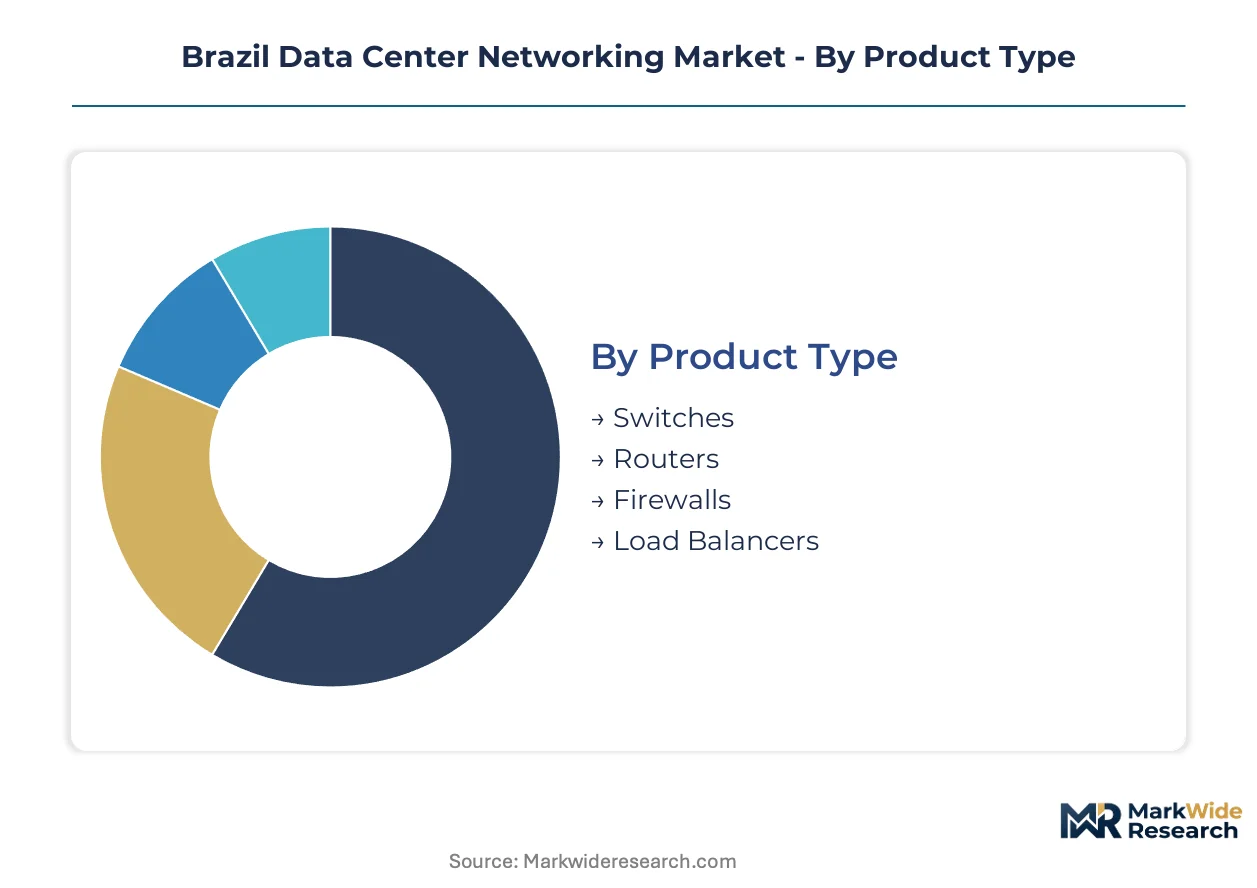
Brazil data center networking vendors calibrate product roadmaps around divergent replacement cycles. Hardware refresh timelines stretch from three years for core switching to seven-plus years for perimeter security appliances. Understanding these velocity differences separates inventory planning from speculative overstocking.
Product Type:
Ethernet switches turn over fastest as spine-leaf architectures scale port density every 18-24 months, while physical firewalls linger longest due to certificate-bound configuration lock-in.
- Switches:Layer 2-7 devices with 10 Gbps to 400 Gbps port speeds dominate hardware procurement volumes. São Paulo hyperscale facilities are driving 400 Gbps spine-leaf deployments for AI training clusters, with ANATEL certification backlogs forcing early qualification cycles.
- Routers:Edge and core routing platforms with BGP/OSPF protocol stacks manage inter-facility traffic flows. Financial services data centers in São Paulo deploy carrier-grade routers for low-latency connectivity to B3 exchange infrastructure, prioritizing redundant power supplies.
- Firewalls:Perimeter and internal segmentation appliances enforce zero-trust policies. Healthcare groups under ANVISA data protection mandates favor on-premises firewall deployments over cloud-native alternatives.
- Load Balancers:Application delivery controllers distribute traffic across server pools. E-commerce platforms operating from Rio de Janeiro colocation facilities are adopting container-native load balancing for microservices architectures.
Switches dominate installed base. Load balancers are where expansion concentrates.
Technology:
Cost tiers separate commodity Ethernet from premium InfiniBand, with SDN overlays capturing mid-market automation budgets.
- Ethernet:IEEE 802.3 standards-based switching constitutes the foundational interconnect protocol. Every São Paulo-Rio de Janeiro corridor facility runs Ethernet for general-purpose compute, with 25 Gbps server access now standard.
- InfiniBand:RDMA-capable networks deliver sub-microsecond latency for high-performance computing. State-backed research cloud projects are piloting InfiniBand for AI training clusters, bypassing Ethernet congestion control overhead.
- Fiber Channel:Storage area networking protocol for block-level data access. Banking data centers maintain Fiber Channel for legacy mainframe storage attachment despite NVMe-oF migration pressure.
- SDN:Software-defined networking decouples control plane from data plane for programmatic management. Mid-market colocation tenants in Fortaleza are adopting SDN overlays to automate multi-tenant provisioning without hardware forklift upgrades.
Ethernet dominates installed base. SDN is where expansion concentrates.
End User:
Customer type determines procurement sophistication, with cloud providers running continuous deployment pipelines and enterprises locked into capital budget cycles.
- Cloud Providers:Hyperscale operators with autonomous infrastructure teams and direct OEM relationships. São Paulo-based cloud operators are qualifying 51.2 Tbps silicon photonics switches ahead of general availability.
- IT Services:Managed service providers and systems integrators delivering outsourced infrastructure. These intermediaries aggregate demand across multiple enterprise clients, creating volume leverage for switch procurement negotiations.
- Telecommunications:Carrier-neutral facilities and telco-owned data centers with legacy circuit-switched heritage. ANATEL's infrastructure rules bind telecom operators to certified equipment lists with extended validation timelines.
- Enterprises:End-user organizations operating captive facilities for regulated workloads. Hospital groups under ANVISA mandates are building certified on-premises networking for patient record systems.
Enterprises dominate installed base. Cloud providers are where expansion concentrates.
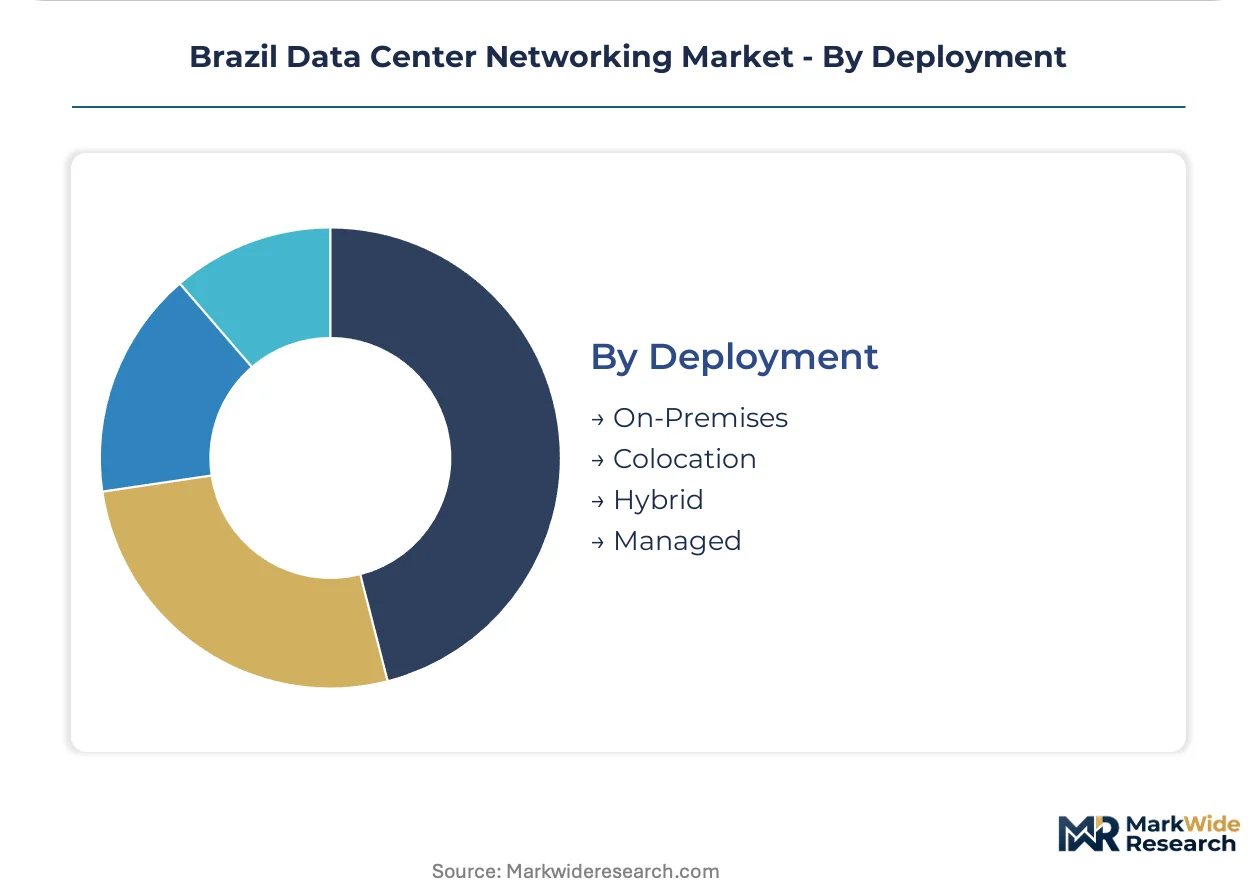
Deployment:
Geography within Brazil concentrates demand in the southeast, with northeast corridor greenfield sites adopting newer architectural patterns.
- On-Premises:Captive facilities owned and operated by end-user organizations. Banking and healthcare verticals in São Paulo retain on-premises deployments for data sovereignty compliance.
- Colocation:Wholesale and retail data centers offering space, power, and cross-connects. The São Paulo-Rio de Janeiro corridor hosts the densest colocation networking demand, with 400 Gbps port orders accelerating.
- Hybrid:Split workloads across private infrastructure and public cloud. Fintech scale-ups are adopting hybrid networking to burst compute to cloud while keeping transaction data on-premises.
- Managed:Fully outsourced infrastructure with networking as a service component. Northeast corridor edge computing investments in Fortaleza are attracting managed networking providers for submarine cable landing station connectivity.
On-premises dominates installed base. Colocation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANATEL's certification framework anchors demand concentration in Brazil's southeast corridor. Sub-regional variations reflect divergent infrastructure maturity and regulatory exposure across state boundaries.
São Paulo
Hyperscale cloud operators drive 400 Gbps spine-leaf deployments across metropolitan facilities. ANATEL's three accredited laboratories concentrate here, compressing vendor qualification timelines relative to national benchmarks. The São Paulo-Rio de Janeiro corridor hosts the densest colocation networking demand as AI training clusters scale port density requirements.
Rio de Janeiro
Submarine cable landing stations attract edge computing investments with low-latency connectivity to international financial markets. State-backed cloud infrastructure projects prioritize certified equipment lists with extended validation timelines. Barra da Tijuca and downtown districts concentrate enterprise data center networking procurement for regulated sectors.
Minas Gerais
Belo Horizonte's fintech ecosystem generates hybrid networking demand splitting workloads between private infrastructure and public cloud bursts. ANVISA-mandated local storage requirements for healthcare groups drive hospital investment in certified on-premises networking. The state's industrial corridor lags São Paulo in hyperscale facility density.
Rio Grande do Sul
Porto Alegre's agribusiness technology sector adopts managed networking services for edge computing deployments. Federal data center efficiency frameworks under development will reward facilities achieving PUE below 1.3 with tax credits, stimulating hardware refresh cycles. The southern region exhibits lower ANATEL certification backlogs than southeastern laboratories.
Bahia
Salvador's emerging status as a submarine cable hub creates greenfield networking demand outside the saturated southeast corridor. Northeast development programs attract edge computing investments with subsidized power tariffs. Local content requirements under federal procurement rules alter supplier qualification criteria for government cloud contracts in this region.
Brazil Data Center Networking Market Competitive Landscape
Established certification holders and price-performance challengers split the market along compliance-versus-cost axes. Vendor concentration remains moderate with tiered competitive dynamics separating premium-tier incumbents from mid-market specialists. Two strategic archetypes dominate: full-stack infrastructure providers with ANATEL pre-approved portfolios, and component specialists targeting specific latency or density requirements. Competitive moves center on local testing partnership expansion and silicon photonics qualification acceleration.
Within the full-stack tier, Cisco Systems Inc. and Juniper Networks Inc. exemplify certification-anchored positioning with São Paulo laboratory access. Huawei Technologies Co. Ltd. occupies a distinct cost-optimized segment competing aggressively for state-backed cloud infrastructure projects. Schneider Electric represents the infrastructure-integrated archetype bridging power and networking systems. These three companies collectively illustrate how regulatory compliance, price positioning, and vertical integration define competitive boundaries in this market.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Juniper Networks Inc. |
| Huawei Technologies Co. Ltd. |
| Schneider Electric |
| Eaton Corporation |
| Dell Technologies |
| NVIDIA |
| Emerson Electric Co. |
| HP Development Company |
| Others |
Pricing and Supply Chain Analysis
São Paulo's ANATEL-certified laboratory cluster concentrates vendor qualification capacity, granting pre-approved suppliers pricing power over mid-tier operators facing 6-9 month homologation backlogs. This geographic bottleneck feeds into a three-tier cost structure where certification status outweighs raw hardware specifications.
Pricing Analysis
Metropolitan São Paulo commands 15-25% port-rate premiums over Fortaleza and Recife facilities due to cross-connect density and submarine cable proximity. Pricing stratifies across ANATEL-certified premium tiers, volume-scaled standard tiers, and economy tiers accepting longer lead times. Cost compression in the mid-market intensifies as white-box switch vendors bypass traditional channel markups. Cloud providers exhibit lowest price sensitivity, while hospital groups under ANVISA mandates prioritize certification compliance over unit economics.
Supply Chain Analysis
Flex, Jabil, and Foxconn hold contract manufacturing capacity for switch and router assemblies serving the Brazilian market. Component sourcing draws from Taiwan for silicon photonics engines, China for optical transceivers, and Mexico for power supply units. Single-source vulnerability concentrates in 400 Gbps optical module supply. Distribution runs through Cisco-certified partner networks for enterprise routing, with direct OEM relationships dominating hyperscale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where ANATEL certification creates switching costs that freeze out unqualified competitors. Network effects concentrate among pre-approved vendor ecosystems.
For Market Incumbents: Pre-empt white-box encroachment by accelerating silicon photonics qualification through São Paulo laboratory partnerships. Deepen backward integration into optical engine supply to offset transceiver cost volatility. Lock in hospital group procurement through ANVISA-compliant managed service bundles before cloud-native alternatives mature. For New Entrants and Emerging Players: Establish a beachhead in Fortaleza and Recife edge computing deployments where certification backlogs are shorter and local content requirements favor new suppliers. Target agribusiness technology adopters in Rio Grande do Sul with managed SD-WAN offerings. Lead with consumption-based pricing to bypass capital budget cycles constraining mid-market colocation tenants. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with silicon photonics roadmaps over legacy chassis vendors. Long-term viability hinges on co-packaged optics adoption rates across the analysis window. Acquisition targets should display ANATEL pre-approved portfolios and established São Paulo laboratory relationships. Monitor hyperscaler 51.2 Tbps switch qualification announcements as inflection indicators for architecture transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Laboratory Partnership Expansion | Compresses vendor qualification timelines from 9 months to 4 months for spine-leaf switch portfolios. |
| Silicon Photonics Qualification Acceleration | Positions suppliers for 51.2 Tbps hyperscale deployments piloting in São Paulo facilities. |
| Healthcare Vertical Managed Service Launch | Captures ANVISA-mandated on-premises networking demand from hospital consolidation groups. |
| Northeast Corridor Edge Computing Investment | Exploits Fortaleza submarine cable landing station growth with greenfield networking infrastructure. |
| Consumption-Based Procurement Model Adoption | Transfers hardware risk to facility owners serving fintech scale-ups with volatile traffic patterns. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center operations directors, network engineering leads, ANATEL certification specialists, and colocation procurement managers; and secondary validation against ANATEL homologation databases, hyperscaler capex disclosures, submarine cable landing station registries, and hospital group IT procurement records. Bottom-up port-density estimates and top-down facility investment flows were triangulated to derive market sizing.
Forecast inputs span product type segmentation across switches, routers, firewalls, and load balancers; technology tiers separating Ethernet, InfiniBand, Fiber Channel, and SDN; and deployment models distinguishing on-premises, colocation, hybrid, and managed infrastructure. CAGRs were computed from annualized port shipment trajectories and average selling price evolution across the projection horizon. ANATEL regulatory timeline assumptions and silicon photonics adoption curves shaped scenario-weighted outputs.
Macroeconomic conditions sit as an overlay; deviation in BRL-USD exchange rates, ICMS state tax harmonization progress, or federal data center efficiency framework implementation would shift the trajectory. Forecasts embed assumptions regarding ANATEL laboratory capacity expansion and optical component supply normalization. Quarterly review of hyperscaler qualification announcements, ANATEL resolution updates, and northeast corridor edge computing investment flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Saudi Arabia Data Center Networking Market
Data Center and Networking
Content Delivery Network (CDN) Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Data Center Market
Data Center and Networking
Global Cloud Content Delivery Network Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Virtual Data Optimizer Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Global WAN Optimization Market