
 IoT in Commercial Construction Market | 2026-2036
IoT in Commercial Construction Market Size, Share, and Industry Trends Forecast 2026-2036
IoT in Commercial Construction Market Analysis
Healthcare facility construction is expanding as the dominant vertical for IoT sensor deployment, overtaking traditional office and retail segments. Trimble Inc. dominates the precision positioning layer for site digitization, while Hexagon AB anchors geospatial analytics integration across large commercial portfolios. Siemens AG competes through its building automation-to-construction data thread, leveraging hardware-software coupling that few rivals replicate.
IoT in commercial construction encompasses networked sensor arrays, wearable terminals, unmanned aerial vehicles, and edge computing nodes that capture, transmit, and analyze field data to optimize labor safety, equipment utilization, and project scheduling. These systems typically operate on low-latency protocols with mesh network resilience, processing telemetry from concrete maturity monitors, crane load sensors, and worker proximity badges to compress decision cycles from days to minutes. Sensors and smart equipment represent the deepest margin pools, as hardware-software bundles lock in recurring calibration and firmware update revenue streams. Edge computing is displacing pure cloud architectures where real-time structural health monitoring and autonomous heavy machinery command sub-50-millisecond response thresholds.
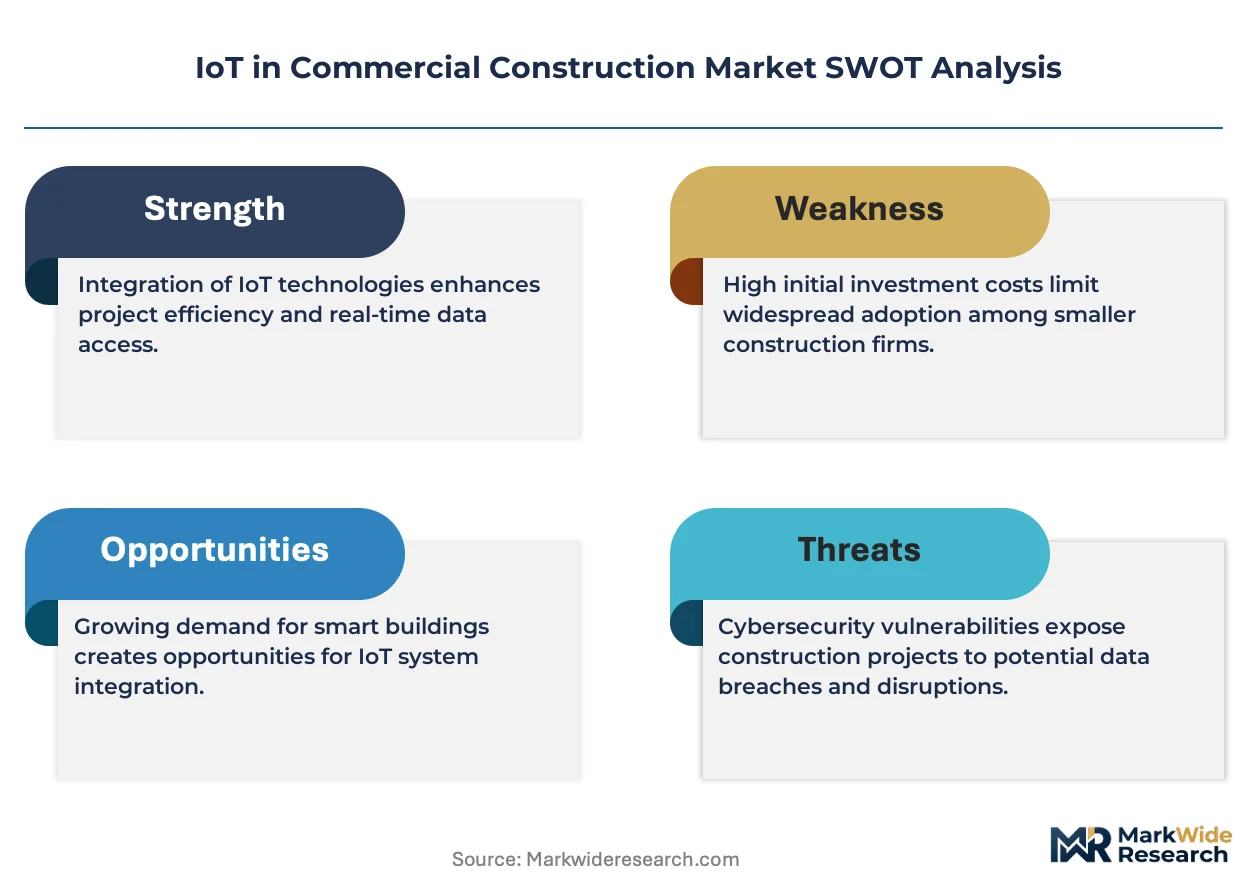
OSHA mandates in the United States, the EU Green Deal's building performance standards, and Japan's METI energy efficiency directives are tightening compliance baselines for connected job site infrastructure. These frameworks shape procurement specifications by embedding cybersecurity, interoperability, and carbon reporting requirements into commercial construction contracts. Stakeholders must monitor how regulatory divergence across jurisdictions fragments platform standards and inflates certification costs for multi-national deployments.
Market Dynamics
Edge computing architectures are unifying field telemetry with structural health monitoring, collapsing the latency gap that previously forced trade-offs between real-time responsiveness and centralized analytics in commercial construction environments.
Growth Catalysts
- EU Green Deal building performance standards:Germany's commercial portfolio operators face mandatory energy benchmarking disclosures that accelerate sensor deployment for carbon reporting compliance.
- Healthcare facility retrofit wave:Hospital construction and renovation projects now specify networked environmental controls and occupancy analytics as baseline procurement requirements.
- Mesh network resilience protocols:Low-latency communication standards enable continuous telemetry from concrete maturity monitors and crane load sensors across geographically dispersed job sites.
Market Restraints
- Semiconductor supply concentration:Edge computing node production depends on foundry capacity concentrated in Taiwan and South Korea, creating input volatility for hardware-software bundles.
- Interoperability certification costs:Divergent cybersecurity requirements across OSHA, EU AI Act, and Japan's METI directives fragment platform standards and inflate multi-jurisdictional deployment expenses.
- Legacy building management system lock-in:Existing Siemens and Honeywell automation infrastructure creates switching friction for new IoT-native entrants seeking commercial retrofit contracts.
Strategic Opportunities
- Autonomous heavy machinery integration:Sub-50-millisecond response thresholds for crane and excavator automation create demand for localized edge processing that pure cloud architectures cannot satisfy.
- Worker proximity badge analytics:Safety-conscious general contractors in the United States seek predictive incident modeling using real-time spatial positioning data from wearable terminals.
- Digital twin convergence:Building information modeling platforms are absorbing IoT telemetry streams to enable predictive maintenance contracts that extend vendor relationships beyond construction completion.
Industry Challenges
- Embedded systems cybersecurity expertise scarcity:Firmware vulnerability assessment and over-the-air update management require specialized talent pools that construction technology vendors struggle to staff.
- Multi-protocol integration complexity:Field deployments must reconcile proprietary mesh networks with open standards while maintaining deterministic latency for safety-critical structural monitoring applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT in Commercial Construction Market |
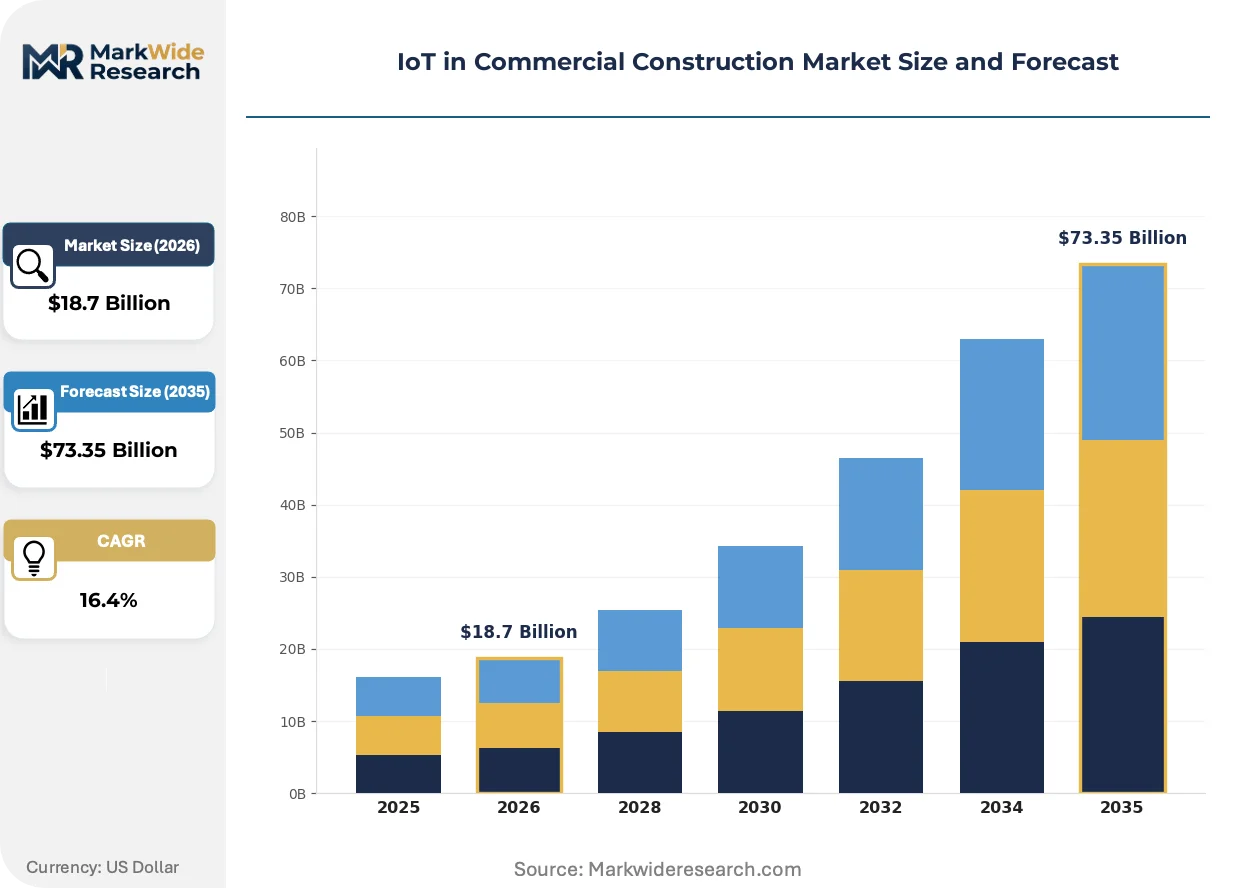
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Sensors, Smart Equipment, Drones Technology: RFID, GPS, Cloud Computing, Edge Computing Application: Site Management, Asset Tracking, Security Monitoring, Waste Management End User: Construction Firms, Project Managers, Architects, Contractors |
| Companies Covered | Hexagon AB, Siemens AG, Trimble Inc., Bosch, Autodesk Inc., Caterpillar Inc., Topcon Corporation, Oracle Construction & Engineering, Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT in Commercial Construction Market Emerging Trajectories
Telemetry compression and localized inference are redrawing the boundary between field devices and back-end infrastructure, enabling autonomous decision loops that previously required human intervention or cloud round-trips.
Digital thread platforms are unifying geospatial positioning data from unmanned aerial vehicles with ground-based sensor networks to create continuously updated as-built documentation. Large commercial portfolio operators in Germany and the Netherlands are deploying these integrated systems across multiple simultaneous projects, compressing schedule variance detection from weekly reports to hourly alerts. The structural consequence is collapsing rework cycles and shifting contractor liability toward real-time quality assurance obligations.
Japan's METI energy efficiency directives now mandate connected metering infrastructure for commercial buildings exceeding specific consumption thresholds, creating compliance-driven procurement specifications that embed IoT requirements into construction contracts. Industrial consequence includes mandatory interoperability testing against JIS standards before system commissioning. Healthcare and logistics facility developers face the tightest compliance timelines, accelerating partnerships between construction firms and certified systems integrators.
General contractors are unbundling equipment utilization analytics from traditional lease arrangements, purchasing telemetry subscriptions separately from physical machinery. Rental fleet operators in the United States face disintermediation pressure as construction firms source sensor-enabled assets directly from OEMs with captive financing arms. The shift is most visible in crane and concrete pumping equipment categories, where hour-by-hour productivity visibility justifies premium pricing for connected machine contracts.
IoT in Commercial Construction Market Segmentation
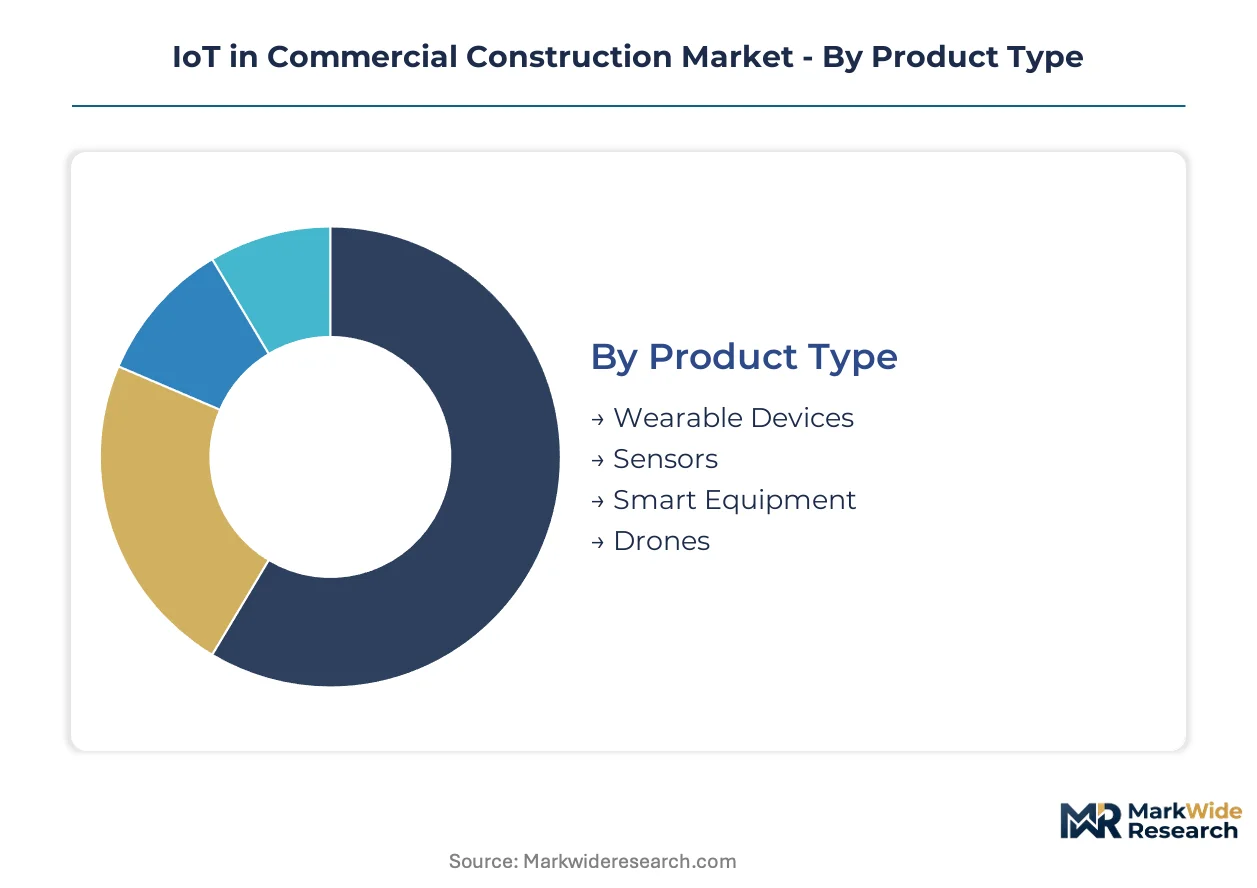
IoT deployment in commercial construction fragments across hardware form factors, communication protocols, and stakeholder workflows. Each segmentation axis reveals distinct procurement patterns and margin structures that shape vendor strategy and technology roadmaps.
Product Type:
Replacement cycles for field hardware compress as firmware-dependent features render older sensor generations obsolete within three to four years.
- Wearable Devices:Worker proximity badges and biometric monitors incorporate LTE-M and Bluetooth Low Energy radios for real-time location tracking. Demand clusters with general contractors in the United States facing OSHA recordable incident pressure.
- Sensors:Concrete maturity monitors, structural strain gauges, and environmental probes constitute the deepest recurring revenue pool through calibration subscriptions. German commercial portfolio operators deploy these most aggressively under EU Green Deal benchmarking mandates.
- Smart Equipment:OEM-embedded telemetry in cranes and excavators enables hour-by-hour utilization analytics.
- Drones:Unmanned aerial vehicles with photogrammetry payloads accelerate as-built documentation cycles.
Volume placements concentrate in Sensors; the faster expansion belongs to Wearable Devices.
Technology:
Cost tiers separate legacy connectivity from next-generation architectures, with premium pricing attaching to sub-50-millisecond latency guarantees.
- Edge Computing:Localized inference nodes process structural health telemetry without cloud round-trips, commanding hardware-software bundles at premium tiers. Autonomous heavy machinery integration in Japan and Germany drives specification.
- Cloud Computing:Centralized analytics platforms aggregate multi-site telemetry for portfolio-level benchmarking. Project managers favor these for schedule variance detection across dispersed job sites.
- RFID:Passive and active radio-frequency identification tags track material flow through supply chains.
- GPS:Satellite positioning enables geofencing and equipment location services.
Procurement volume tilts toward Cloud Computing; Edge Computing climbs the fastest as real-time safety applications proliferate.
Application:
Customer maturity varies by use case, with early adopters concentrating in compliance-driven monitoring functions.
- Site Management:Integrated platforms unify labor tracking, equipment scheduling, and environmental monitoring through single-pane dashboards. Construction firms in the Netherlands deploy these across simultaneous projects.
- Asset Tracking:Real-time location systems for tools, materials, and machinery reduce shrinkage and rental overruns. Contractors with thin margins prioritize this category.
- Security Monitoring:Perimeter sensors and access control integration protect high-value equipment overnight.
- Waste Management:Fill-level sensors on debris containers optimize haulage scheduling.
Asset Tracking captures the widest installation base; Site Management gains share fastest as digital thread platforms mature.
End User:
Buying authority fragments across project phases, with specification influence shifting from design through construction completion.
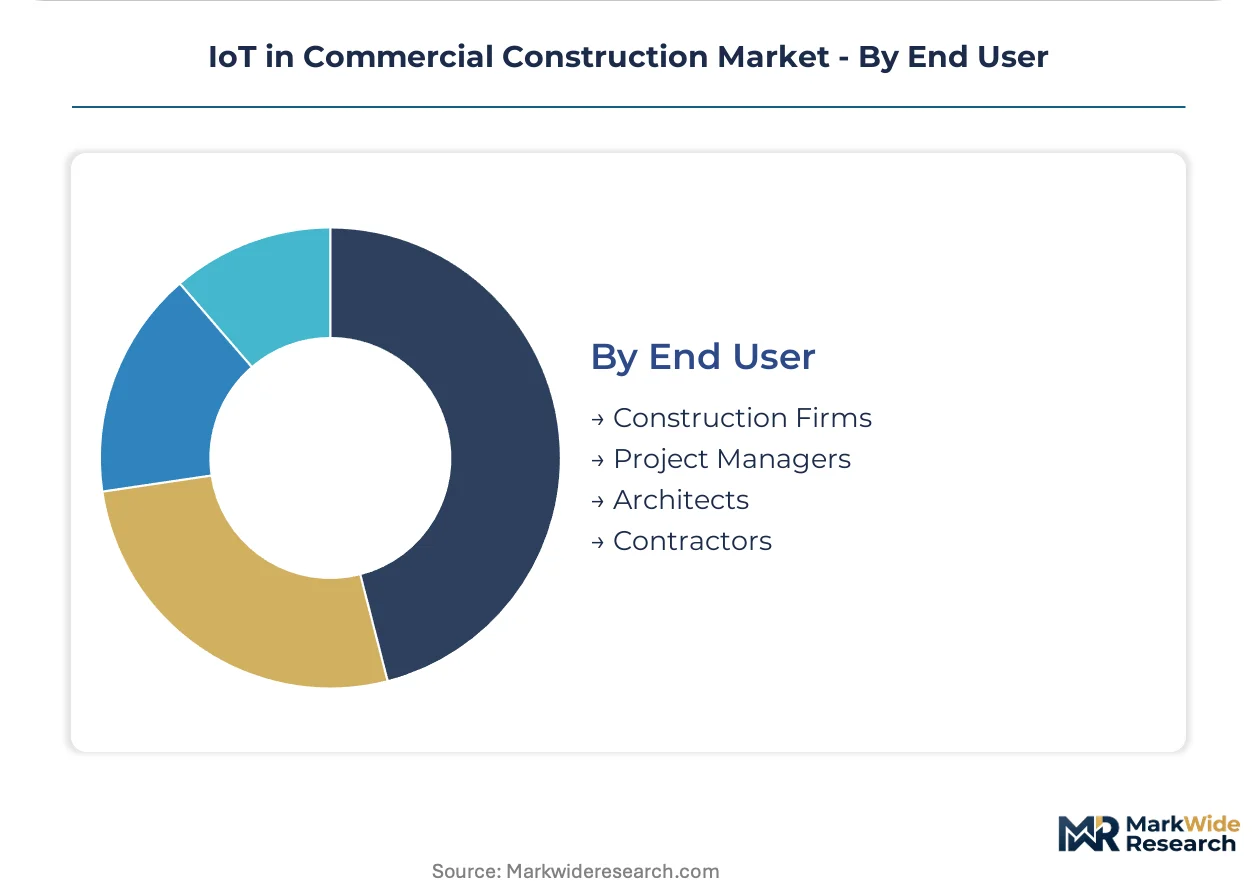
- Construction Firms:Enterprise general contractors negotiate enterprise telemetry subscriptions across equipment fleets and project portfolios. These stakeholders drive standardization demands that fragment smaller rivals.
- Project Managers:Site-level decision-makers procure point solutions for immediate schedule and safety pressures. Their buying cycles compress to weeks during active construction phases.
- Architects:Design-phase specification of building automation interfaces constrains later IoT integration choices.
- Contractors:Trade-specific subcontractors adopt wearable and tool-tracking systems for liability containment.
Construction Firms dominate current spending; Project Managers represent the fastest-expanding purchasing constituency as self-service analytics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's commercial building retrofit zones concentrate sensor deployment under EU Green Deal mandates, while Japan's METI efficiency directives and OSHA compliance pressure in the United States shape procurement specifications across three distinct regulatory environments.
Germany
Commercial portfolio operators in Frankfurt and Munich accelerate sensor deployment for mandatory energy benchmarking disclosures under the EU Green Deal. The country's building performance standards embed IoT requirements into construction contracts. Bavaria's industrial construction corridor leads edge computing adoption for real-time structural monitoring.
United States
OSHA recordable incident pressure drives demand for worker proximity badges and predictive safety analytics among general contractors. The agency's evolving mandates shape procurement specifications for connected job site infrastructure. Texas and California construction clusters deploy mesh network protocols across dispersed commercial developments.
Japan
METI energy efficiency directives mandate connected metering infrastructure for commercial buildings above consumption thresholds. The ministry's JIS standards compliance requirements accelerate partnerships between construction firms and certified systems integrators. Tokyo and Osaka healthcare facility developers face the tightest implementation timelines.
Netherlands
Digital thread platforms unify geospatial positioning with ground-based sensor networks across simultaneous commercial projects. The country's progressive building codes enable hourly schedule variance detection that collapses rework cycles. Randstad urban construction corridors lead as-built documentation automation.
China
Dual carbon goals and MIIT smart city directives accelerate IoT integration in commercial building stock. The ministry's GB standards shape interoperability requirements for construction technology procurement. Yangtze River Delta megacity clusters concentrate edge computing deployment for autonomous heavy machinery applications.
IoT in Commercial Construction Market Vendor Landscape
Top-tier vendors anchor precision positioning and building automation integration, while mid-tier specialists compete on vertical-specific sensor calibration services. The vendor base stratifies across three tiers: industrial conglomerates with captive construction technology divisions, pure-play geospatial analytics providers, and emerging edge computing hardware specialists. Two dominant competitive moves define current positioning: backward integration into semiconductor supply chains for edge node production, and strategic partnerships between OEMs and building information modeling platforms to extend vendor relationships beyond construction completion.
Among Sweden-based industrial technology groups, Hexagon AB exemplifies the geospatial analytics archetype through its positioning in measurement and reality capture systems. Siemens AG represents the building automation-to-construction data thread model, leveraging hardware-software coupling that anchors European commercial retrofit contracts. Trimble Inc. occupies the precision positioning tier for site digitization, with its United States origin reflecting North American demand concentration for connected construction workflows.
| Leading Market Players |
|---|
| Hexagon AB |
| Siemens AG |
| Trimble Inc. |
| Bosch |
| Autodesk Inc. |
| Caterpillar Inc. |
| Topcon Corporation |
| Oracle Construction & Engineering |
| Komatsu Ltd. |
| Others |
Supply Flow & Price Mechanics
Silicon wafer spot price indices cascade through edge computing node production into three-tier pricing structures across premium, standard, and economy levels for IoT hardware-software bundles. Taiwan foundry capacity constraints compress lead times for German commercial portfolio operators facing EU Green Deal compliance deadlines, forcing procurement teams toward spot-market premiums.
Pricing Analysis
Short lead-time premiums of 15-20% attach to edge computing nodes delivered within compressed windows for autonomous heavy machinery integration in Japan and Germany. Pricing stratifies across premium, standard, and economy tiers based on firmware customization depth and JIS/CE certification level. Cost compression in economy-tier sensor hardware intensifies because Chinese module suppliers are expanding MEMS foundry capacity. Project managers with thin margins exhibit highest price sensitivity; healthcare facility operators facing regulatory deadlines show lowest.
Supply Chain Analysis
EU Green Deal local-content mandates for public infrastructure procurement are reshaping sourcing patterns for commercial construction IoT deployments across member states. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; sensor module assembly draws from China, Vietnam, and Mexico. Raw material dependencies span silicon wafers, rare earth magnets for drone motors, and lithium cells for wearable power. Single-source vulnerability in Taiwan foundry capacity threatens hardware-software bundle availability. Distribution runs through certified systems integrators holding JIS, CE, and UL certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge computing node foundry capacity constraints prop pricing power for vendors with captive semiconductor supply, creating a supply-constrained market structure favoring backward-integrated players.
For Market Incumbents: Acquire firmware vulnerability assessment talent pools to counter cybersecurity expertise scarcity threatening recurring revenue from calibration subscriptions. Consolidate channel control through exclusive partnerships with Siemens and Honeywell-certified systems integrators in Germany and Japan. Threat of emerging edge computing hardware specialists from China's MIIT-backed ecosystem demands defensive certification investment in JIS and EU AI Act compliance. For New Entrants and Emerging Players: The 40% price-point gap between premium-tier edge computing bundles and economy-tier sensor hardware opens white-space targeting of mid-market construction firms in the Netherlands and Texas. Penetrate project manager constituencies through self-service analytics platforms with sub-50-millisecond latency guarantees. Go-to-market angle: hourly schedule variance detection compressing rework cycles for simultaneous commercial developments. For Investors and Strategic Acquirers: Distressed-cycle entries favor geospatial analytics specialists with EU Green Deal certification moats in Germany and the Netherlands. Long-term viability hinges on digital twin convergence extending vendor relationships beyond construction completion. Acquisition target archetype: edge computing hardware specialists with Taiwan foundry relationships. Signal to watch: METI directive expansion tightening JIS compliance timelines for healthcare facility developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Captive foundry capacity insulates German vendors from Taiwan supply volatility. |
| Digital Twin Platform Convergence | BIM-IoT integration extends Siemens and Hexagon relationships past project handover. |
| Certified Systems Integrator Partnership | JIS/CE/UL certification channels accelerate METI and EU Green Deal compliance. |
| Autonomous Machinery Edge Node Deployment | Sub-50-millisecond latency specifications lock in premium hardware-software bundles. |
| Worker Proximity Badge Analytics Launch | OSHA recordable incident pressure drives predictive safety subscriptions among US general contractors. |
Methodological Framework
Multi-period observation of edge computing node shipments, sensor deployment rates, and construction permit volumes anchored the trend analysis, supplemented by interviews with construction technology procurement directors, certified systems integrators, project managers, and OEM telemetry product managers. Secondary validation drew from EU building performance disclosure databases, METI efficiency directive filings, OSHA incident reports, and SEC construction technology segment disclosures. Bottom-up sensor unit economics triangulated against top-down commercial construction spend patterns.
Input-output matrices modeled hardware form factor, communication protocol latency tier, stakeholder workflow, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level unit trajectory analysis and pricing tier elasticity assumptions. Forecast inputs incorporated EU Green Deal compliance timeline acceleration, METI JIS certification expansion, and foundry capacity utilization rates.
Inputs from construction firm procurement databases and systems integrator order backlogs were available through the study window; gaps in real-time structural monitoring deployment rates for autonomous heavy machinery introduce uncertainty bands around edge computing adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Infrastructure Market