
 Canada Casein and Caseinate Market | 2026-2036
Canada Casein and Caseinate Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Casein and Caseinate Market Outlook
Capital-intensity divergence between large-scale dairy cooperatives and specialized ingredient processors is bifurcating competitive dynamics in the Canadian caseinate landscape. Agropur Cooperative leverages its captive milk supply across Quebec and Ontario to sustain backward-integrated casein production. Fonterra Co-operative Group Limited anchors its Canadian presence through technical-grade sodium caseinate exports to North American food manufacturers. Glanbia PLC differentiates via pharmaceutical-grade calcium caseinate positioning for clinical nutrition contracts.
Casein denotes a family of phosphoproteins comprising approximately 80% of bovine milk protein, precipitated at pH 4.6 and subsequently processed into soluble caseinate salts through alkali neutralization and spray drying for industrial applications. Caseinates function primarily as emulsifiers, water binders, and protein fortifiers across food and pharmaceutical matrices. Sodium caseinate commands the dominant volume position in food-grade applications, while pharmaceutical-grade calcium caseinate captures the highest margin pool within the grade taxonomy. Nutritional supplements represent the fastest-expanding application segment, driven by protein enrichment demand in ready-to-drink beverages and sports powders.
Health Canada enforces protein content and labeling standards under the Food and Drugs Act, while the Canadian Food Inspection Agency oversees dairy ingredient safety and Grade A milk sourcing protocols for casein manufacture. The Canadian Dairy Commission's supply management framework shapes raw milk pricing and allocation, directly constraining domestic casein production economics. Stakeholders must monitor evolving protein fortification claims regulation and dairy processing capacity expansion in Alberta and Manitoba to secure supply positioning.
Market Dynamics
The Canadian Dairy Commission's supply management framework constrains raw milk allocation, forcing caseinate processors to compete for limited domestic protein feedstock against fluid milk and cheese operations.
Growth Catalysts
- Protein fortification mandates:Health Canada's updated Food and Drug Regulations tighten protein content labeling thresholds, compelling sports nutrition manufacturers in Ontario and Quebec to expand caseinate procurement for compliant product formulations.
- Prairie dairy belt concentration:Fluid milk processing clusters in Alberta and Manitoba generate surplus raw casein streams, enabling domestic ingredient processors to reduce import dependency for sodium caseinate production.
- Clinical nutrition expansion:Pharmaceutical-grade calcium caseinate demand from hospital and long-term care facilities is accelerating contract volumes for high-margin nutritional applications.
Market Restraints
- Raw milk price volatility:The Canadian Dairy Commission's administered pricing mechanism ties casein production economics to federal milk price adjustments, compressing processor margins during cost-pass-through lags.
- Import dependency for technical grades:Domestic sodium caseinate capacity shortages force food manufacturers to source from New Zealand and European cooperatives, exposing supply chains to currency and shipping cost fluctuations.
- Plant protein substitution:Pea and oat protein isolates from Prairie pulse processors are capturing share in ready-to-drink beverage applications where emulsification requirements are less stringent.
Strategic Opportunities
- Manitoba processing corridor:Underutilized dairy infrastructure in the Portage la Prairie region offers brownfield expansion sites for caseinate spray-drying capacity serving North American export markets.
- Regenerative agriculture incentives:Federal Sustainable Canadian Agricultural Partnership programs subsidize on-farm methane reduction, potentially lowering the carbon intensity score of domestic casein for EU export eligibility.
- Direct-to-manufacturer platforms:B2B ingredient marketplaces are bypassing traditional dairy broker networks, enabling Prairie processors to capture margin previously allocated to distribution intermediaries.
Industry Challenges
- Fractionation expertise scarcity:Specialized technicians capable of operating membrane filtration and isoelectric precipitation systems are concentrated in Quebec, constraining expansion timelines for Western Canadian facilities.
- Pharmaceutical-grade certification timelines:Health Canada and Canadian Food Inspection Agency dual-track approvals for calcium caseinate drug master files extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Casein and Caseinate Market |
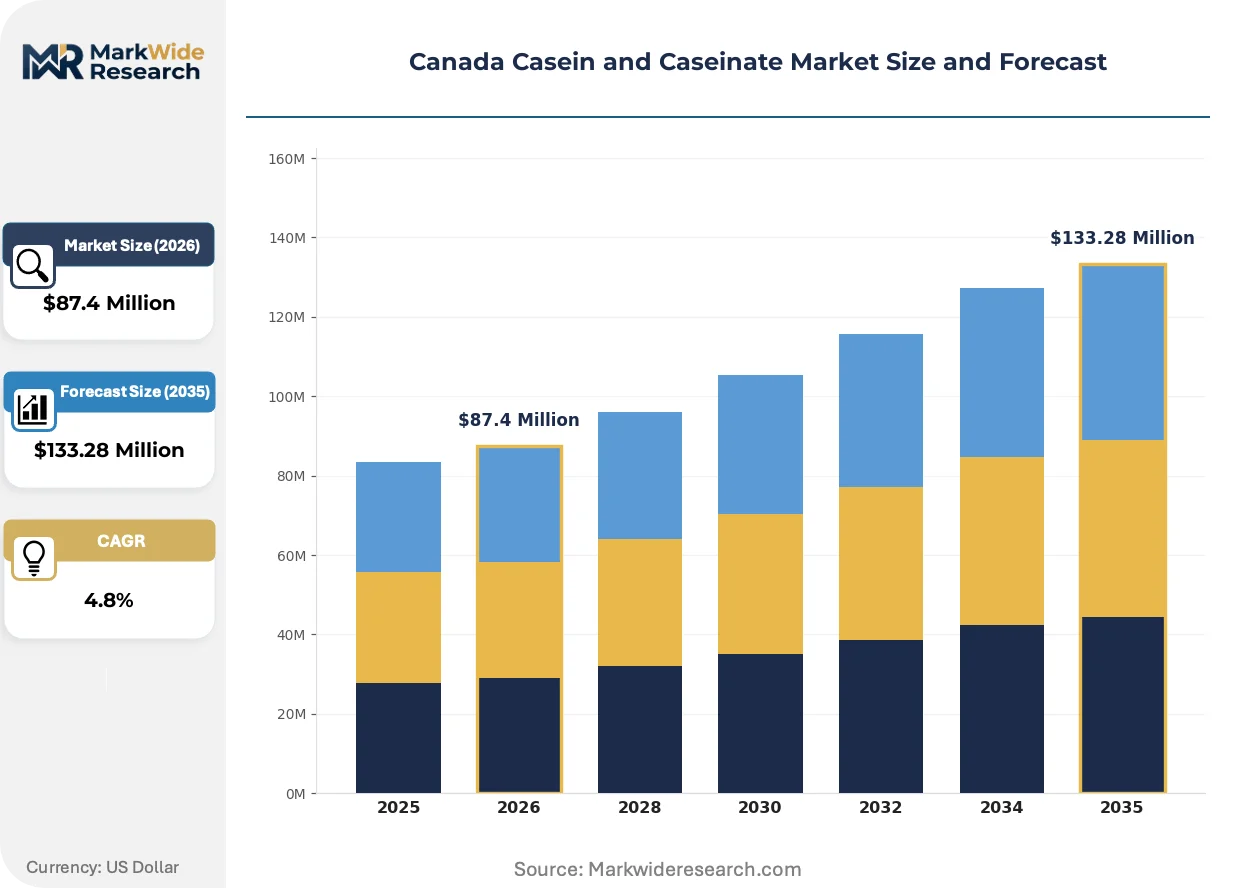
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $133.28 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcasein, Sodium Caseinate, Calcium Caseinate, Potassium Caseinate Application: Dairy Products, Nutritional Supplements, Bakery Products, Confectionery Grade: Food Grade, Tech Grade, Pharmaceutical Grade, Industrial Grade End User: Food Processing, Pharmaceutical Industry, Dietary Supplements, Animal Feed |
| Companies Covered | Arla Foods amba, Fonterra Co-operative Group Limited, Glanbia PLC, Farbest-Tallman Foods Corporation, FrieslandCampina Ingredients, Agropur Cooperative, Nestlé S.A., Kerry Group, Saputo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Casein and Caseinate Market Strategic Shifts
Enzymatic casein hydrolysate production is reshaping competitive positioning, enabling manufacturers to serve premium segments with faster-absorbing protein formats while regulatory scrutiny intensifies on label claims and sourcing transparency.
Membrane filtration technology is supplanting traditional acid precipitation in Ontario processing facilities. Sports nutrition contract manufacturers in Toronto and Guelph are adopting ceramic microfiltration to preserve native protein structures. This shift is compressing energy costs per kilogram of sodium caseinate while improving solubility profiles for ready-to-drink applications.
Health Canada's updated protein content verification protocols under the Food and Drugs Act are tightening analytical requirements for fortification claims. Third-party laboratory certification costs are rising for domestic processors. Prairie-based ingredient suppliers are responding by investing in in-house HPLC testing capacity to accelerate batch release timelines.
Consolidation among Canadian dairy cooperatives is altering procurement patterns for independent caseinate processors. Long-term supply agreements with captive milk pools are replacing spot-market purchasing in Ontario and Quebec. This concentration is most visible in the sports powder segment, where manufacturers face binary supplier choices between integrated cooperatives and import-reliant traders.
Canada Casein and Caseinate Market Segmentation
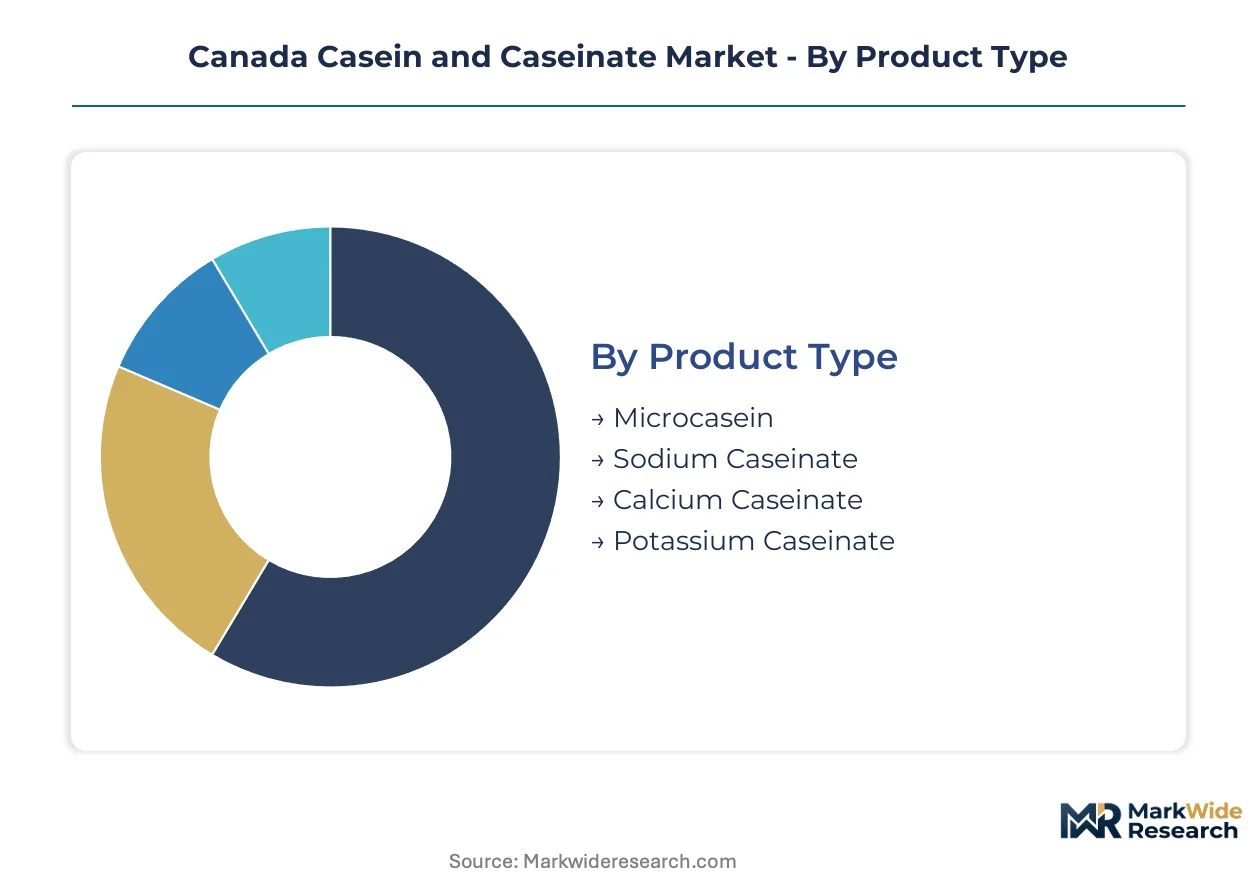
Segmentation in the Canadian casein and caseinate market reveals how supply chain configuration shapes procurement patterns across distinct product specifications and end-use requirements. Understanding these divides helps processors align production capacity with the divergent technical and regulatory demands of food manufacturers versus pharmaceutical contractors.
Product Type:
Sodium caseinate dominates bulk ingredient channels serving Ontario and Quebec food processors, while pharmaceutical-grade calcium caseinate flows through specialized distribution networks to clinical nutrition formulators.
- Sodium Caseinate:This alkali-neutralized salt delivers superior emulsification and water-binding properties for processed cheese and coffee whitener applications. Sports nutrition manufacturers in Toronto and Guelph are expanding procurement volumes for ready-to-drink protein beverages. Supply tightens when the Canadian Dairy Commission reallocates fluid milk quotas toward cheese production.
- Calcium Caseinate:Slower gastric emptying makes this form preferred for sustained-release protein delivery in medical foods and elderly nutrition. Hospital and long-term care facilities in Alberta and Manitoba are accelerating contract volumes for tube-feeding formulations. Health Canada's drug master file requirements extend commercialization timelines for new suppliers.
- Microcasein:Micellar casein concentrate with intact native protein structure serves premium sports powder applications where slow digestion is valued.
- Potassium Caseinate:Low-sodium alternative for specialized cardiac and renal nutrition products, capturing niche share in pharmaceutical compounding.
By volume, sodium caseinate leads. By growth pace, calcium caseinate is climbing the fastest.
Application:
Cost tier differentiation separates commodity dairy applications from premium nutritional positioning, with regulatory compliance costs widening the margin gap between segments.
- Nutritional Supplements:Protein fortification in powders and ready-to-drink formats commands the highest ingredient specification standards. Prairie-based contract manufacturers are investing in in-house HPLC testing to meet Health Canada's tightened protein content verification protocols. Pea protein isolates from Manitoba pulse processors are capturing share in less emulsion-critical beverage applications.
- Dairy Products:Processed cheese, coffee whiteners, and cultured products rely on caseinates for texture stabilization and melt characteristics. Agropur Cooperative's backward-integrated supply secures captive volumes for this segment, constraining spot-market availability for independent processors.
- Bakery Products:Dough conditioning and protein enrichment in commercial bread and pastry operations, with sodium caseinate preferred for its neutral flavor profile.
- Confectionery:Aeration and fat stabilization in whipped candies and chocolate coatings, representing a stable but slow-expanding application niche.
By revenue concentration, nutritional supplements sit at the top. By expansion trajectory, the same segment is gaining share fastest.
Grade:
Customer type determines certification burden and pricing power, with pharmaceutical buyers accepting extended approval timelines for assured supply security.
- Food Grade:Standard specification for general ingredient applications with Canadian Food Inspection Agency oversight of dairy safety protocols. Prairie fluid milk processing clusters generate surplus raw casein streams that feed domestic food-grade sodium caseinate production, reducing import dependency.
- Pharmaceutical Grade:Stringent purity requirements for enteral and parenteral nutrition products. Dual-track Health Canada and Canadian Food Inspection Agency approvals extend commercialization cycles by 18-24 months, creating barriers to entry that protect incumbent suppliers.
- Tech Grade:Intermediate specification for industrial adhesives and coatings applications, sourced primarily from New Zealand and European imports due to domestic capacity constraints.
- Industrial Grade:Lowest specification tier for non-food technical applications including paper sizing and textile finishing, with minimal domestic production.
By margin pool, pharmaceutical grade leads. By volume throughput, food grade dominates.
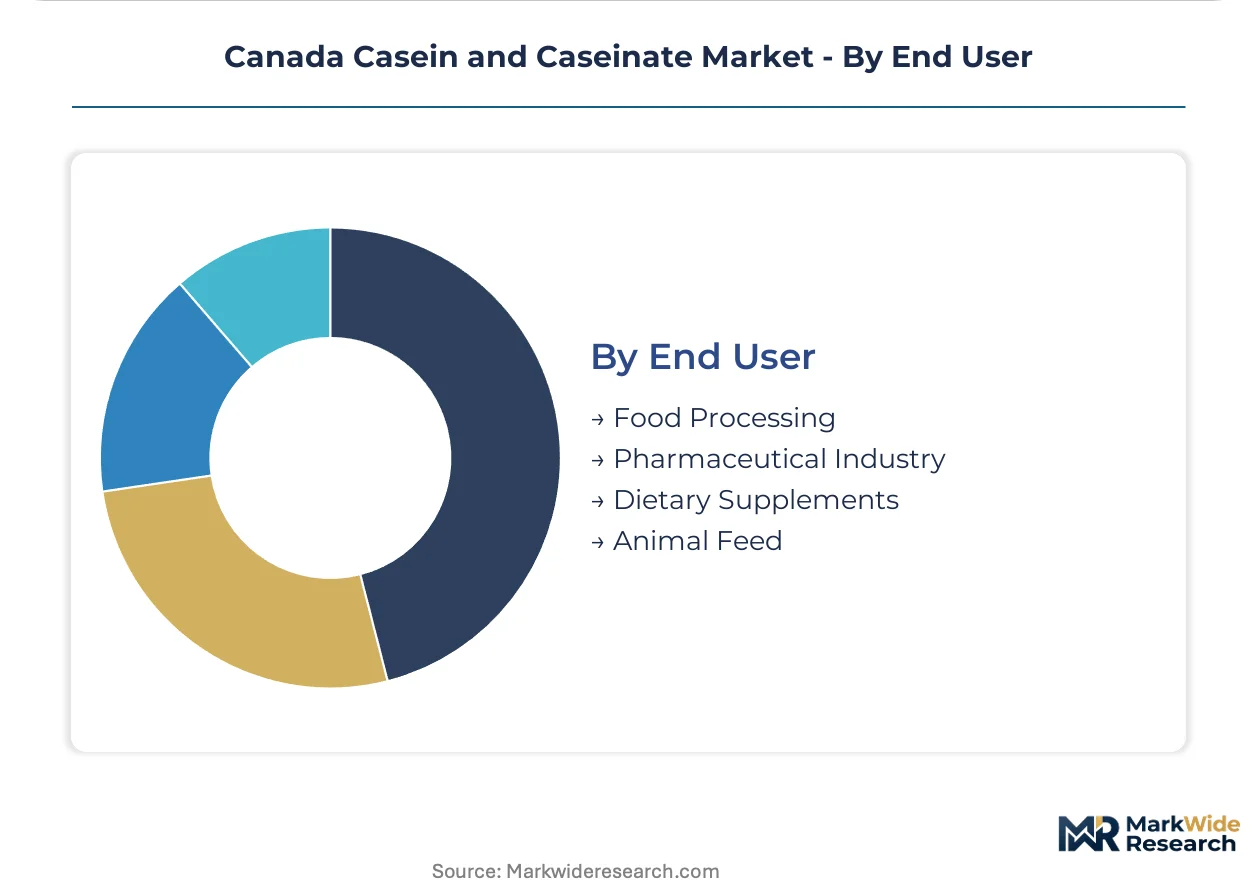
End User:
Supply concentration aligns with geographic clustering of processing infrastructure, with Prairie dairy belt expansion altering historical Ontario-Quebec dominance.
- Food Processing:Large-scale dairy and bakery manufacturers represent the foundational demand base. The Canadian Dairy Commission's supply management framework forces caseinate processors to compete for limited domestic protein feedstock against fluid milk and cheese operations.
- Dietary Supplements:Sports nutrition and wellness brands drive specification innovation. Underutilized dairy infrastructure in Manitoba's Portage la Prairie region offers brownfield expansion sites for spray-drying capacity serving this segment's North American export demand.
- Pharmaceutical Industry:Clinical nutrition and medical food formulators require assured supply chains with batch traceability. Specialized technicians capable of operating membrane filtration systems are concentrated in Quebec, constraining Western Canadian facility expansion.
- Animal Feed:Calf milk replacer and pet food applications, sensitive to raw milk price volatility under the Canadian Dairy Commission's administered pricing mechanism.
By procurement scale, food processing leads. By contract value growth, dietary supplements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's casein and caseinate trade flows reflect a structural deficit in technical-grade sodium caseinate, forcing Prairie processors to source from New Zealand and European cooperatives while exporting pharmaceutical-grade calcium caseinate to American clinical nutrition formulators.
Ontario
Sports nutrition contract manufacturers in Toronto and Guelph are expanding sodium caseinate procurement for ready-to-drink protein beverages. Health Canada's updated Food and Drug Regulations tighten protein content labeling thresholds, compelling formulation adjustments. Membrane filtration adoption in Ontario processing facilities is compressing energy costs per kilogram while improving solubility profiles.
Quebec
Agropur Cooperative leverages backward-integrated milk supply to sustain captive casein production for processed cheese and coffee whitener applications. The Canadian Dairy Commission's supply management framework forces independent processors to compete for limited protein feedstock against fluid milk operations. Specialized technicians capable of operating isoelectric precipitation systems concentrate in this province, constraining Western facility expansion timelines.
Alberta
Fluid milk processing clusters in the Prairie dairy belt generate surplus raw casein streams, enabling domestic ingredient processors to reduce import dependency. Federal Sustainable Canadian Agricultural Partnership programs subsidize on-farm methane reduction, potentially lowering carbon intensity scores for EU export eligibility. Edmonton-area dairy infrastructure is underutilized relative to processing capacity in neighboring provinces.
Manitoba
Underutilized dairy infrastructure in the Portage la Prairie region offers brownfield expansion sites for caseinate spray-drying capacity serving North American export markets. Hospital and long-term care facilities in Winnipeg are accelerating pharmaceutical-grade calcium caseinate contract volumes for tube-feeding formulations. Prairie pulse processors in this province are capturing share in ready-to-drink applications with pea protein isolates where emulsification requirements are less stringent.
Canada Casein and Caseinate Market Competitive Environment
Concentration sits with large-scale dairy cooperatives that control captive milk pools, while specialized ingredient processors compete for limited spot-market supply. The Canadian market exhibits bifurcated dynamics between backward-integrated producers and import-reliant traders. Two strategic archetypes dominate: cooperative-owned processing networks with guaranteed feedstock access, and pharmaceutical-grade specialists commanding premium pricing through Health Canada certification. Competitive moves center on long-term supply agreement renegotiation and brownfield capacity expansion in underutilized Prairie infrastructure.
Within the cooperative tier, Agropur Cooperative and Fonterra Co-operative Group Limited exemplify feedstock-secured positioning, while Glanbia PLC occupies a specialist niche in pharmaceutical-grade calcium caseinate. Agropur's Quebec-Ontario milk pool integration represents the backward-integrated archetype, whereas Fonterra's technical-grade sodium caseinate exports anchor New Zealand-origin supply for North American food manufacturers. Glanbia's clinical nutrition focus demonstrates how Health Canada drug master file approvals create defendable positioning in high-margin segments.
| Leading Market Players |
|---|
| Arla Foods amba |
| Fonterra Co-operative Group Limited |
| Glanbia PLC |
| Farbest-Tallman Foods Corporation |
| FrieslandCampina Ingredients |
| Agropur Cooperative |
| Nestlé S.A. |
| Kerry Group |
| Saputo |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for pharmaceutical-grade calcium caseinate concentrate purchasing power among hospital procurement managers in Alberta and Manitoba, while Prairie dairy belt fluid milk processing clusters constrain spot-market sodium caseinate availability and amplify price volatility for independent Ontario processors.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical-grade calcium caseinate and standard food-grade sodium caseinate runs wide, with contract-based long-term offtake dominating hospital and clinical nutrition procurement while commodity spot pricing governs sports nutrition spot purchases. Price differentiation stems from Health Canada drug master file certification status and volume scale, with certified batches commanding substantial premia over uncertified food-grade alternatives. Cost compression in technical-grade sodium caseinate is intensifying because New Zealand and European import dependency exposes processors to currency fluctuation. Sports nutrition manufacturers in Toronto and Guelph exhibit highest price sensitivity due to thin formulation margins, while pharmaceutical formulators demonstrate lowest sensitivity given assured supply security requirements.
Supply Chain Analysis
Forty-five to sixty-day lead times for New Zealand-origin sodium caseinate shipments expose Canadian food manufacturers to logistics chokepoint risk at Vancouver port terminals. Geographic supply concentration centers on New Zealand, the Netherlands, and domestic Prairie dairy belt processing clusters. Raw material dependencies rest on fluid milk quotas administered by the Canadian Dairy Commission, alkali neutralization chemicals, and pharmaceutical-grade calcium feedstock. Tariff exposure on technical-grade imports from European cooperatives threatens margin stability for independent Ontario processors. Distribution runs through dairy cooperative captive networks for backward-integrated players and ingredient broker channels for import-reliant traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology adoption represents a high-growth disruption in this market, with Health Canada's tightened protein content verification protocols under the Food and Drugs Act accelerating capital deployment toward in-house HPLC testing capacity.
For Market Incumbents: Shield captive milk pool access through long-term supply agreement renegotiation with the Canadian Dairy Commission, locking in fluid milk allocation priority over cheese operations. Fortify Quebec-based fractionation expertise concentration by sponsoring specialized technician training programs at Manitoba polytechnic institutions, preempting Western facility expansion bottlenecks. Deepen backward integration into Prairie spray-drying capacity to capture brownfield expansion economics in Portage la Prairie. For New Entrants and Emerging Players: Direct-to-manufacturer B2B platform services present an underexploited service-layer gap where incumbent dairy broker networks extract excessive margin from Prairie processors. Penetrate the pharmaceutical-grade calcium caseinate segment through Health Canada drug master file fast-track partnerships with established clinical nutrition formulators in Alberta hospital systems. Deploy regulatory compliance-as-a-service positioning to accelerate batch release timelines for independent sports nutrition contract manufacturers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative-owned processing network concentration is displacing import-reliant trader viability across Ontario and Quebec procurement channels. Target brownfield dairy infrastructure assets in Manitoba's Portage la Prairie corridor with membrane filtration retrofit potential. Monitor Health Canada protein fortification claim enforcement intensity as the critical inflection signal for pharmaceutical-grade certification investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Ceramic microfiltration adoption in Ontario facilities compresses energy costs per kilogram while improving sodium caseinate solubility profiles. |
| Health Canada Drug Master File Submission | Dual-track approval pathway for calcium caseinate extends commercialization cycles but creates defendable positioning in clinical nutrition. |
| Prairie Brownfield Capacity Expansion | Underutilized Portage la Prairie dairy infrastructure offers spray-drying sites serving North American export demand. |
| Regenerative Agriculture Certification | Federal Sustainable Canadian Agricultural Partnership methane reduction subsidies lower carbon intensity scores for EU export eligibility. |
| Direct-to-Manufacturer Platform Launch | B2B ingredient marketplaces bypass traditional dairy broker networks, capturing margin previously allocated to distribution intermediaries. |
Study Parameters
A standing panel of dairy cooperative procurement directors, sports nutrition contract manufacturing executives, Health Canada regulatory affairs specialists, and Prairie fluid milk processing plant managers provided ongoing calibration across primary interview cycles. Secondary validation drew from Canadian Dairy Commission quota allocation records, Health Canada Food and Drug Regulations filings, Canadian Food Inspection Agency dairy safety inspection reports, and provincial agricultural ministry production statistics. Bottom-up capacity modeling across Alberta and Manitoba processing clusters triangulated against top-down demand estimation from Ontario and Quebec formulation facilities.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by product type, application tier, grade specification, and end-user category, with provincial production cluster and regulatory jurisdiction overlays. CAGRs were derived from fitted growth curves incorporating Canadian Dairy Commission milk price adjustment schedules, membrane filtration adoption rates, and Health Canada enforcement intensity proxies for protein content verification protocols.
Underlying assumptions cover sustained Canadian Dairy Commission supply management continuity, stable Health Canada regulatory enforcement trajectories, and Prairie dairy belt infrastructure utilization recovery, with deviation risk concentrated in raw milk price volatility pass-through lags and pharmaceutical-grade certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Cheese Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
United States Dairy Market
Dairy Products
Butter Powder Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Flavoured Milk Market
Dairy Products
Plain Yogurt Market
Dairy Products
Nigeria Yogurt Drinks Market
Dairy Products
White Cheese Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Low Fat Cheese Market
Dairy Products
A2 Protein Milk Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Recombined Milk Products Market
Dairy Products
United States Milk Protein Market