
 Asia-Pacific Dairy Market | 2026-2036
Asia-Pacific Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dairy Market Analysis
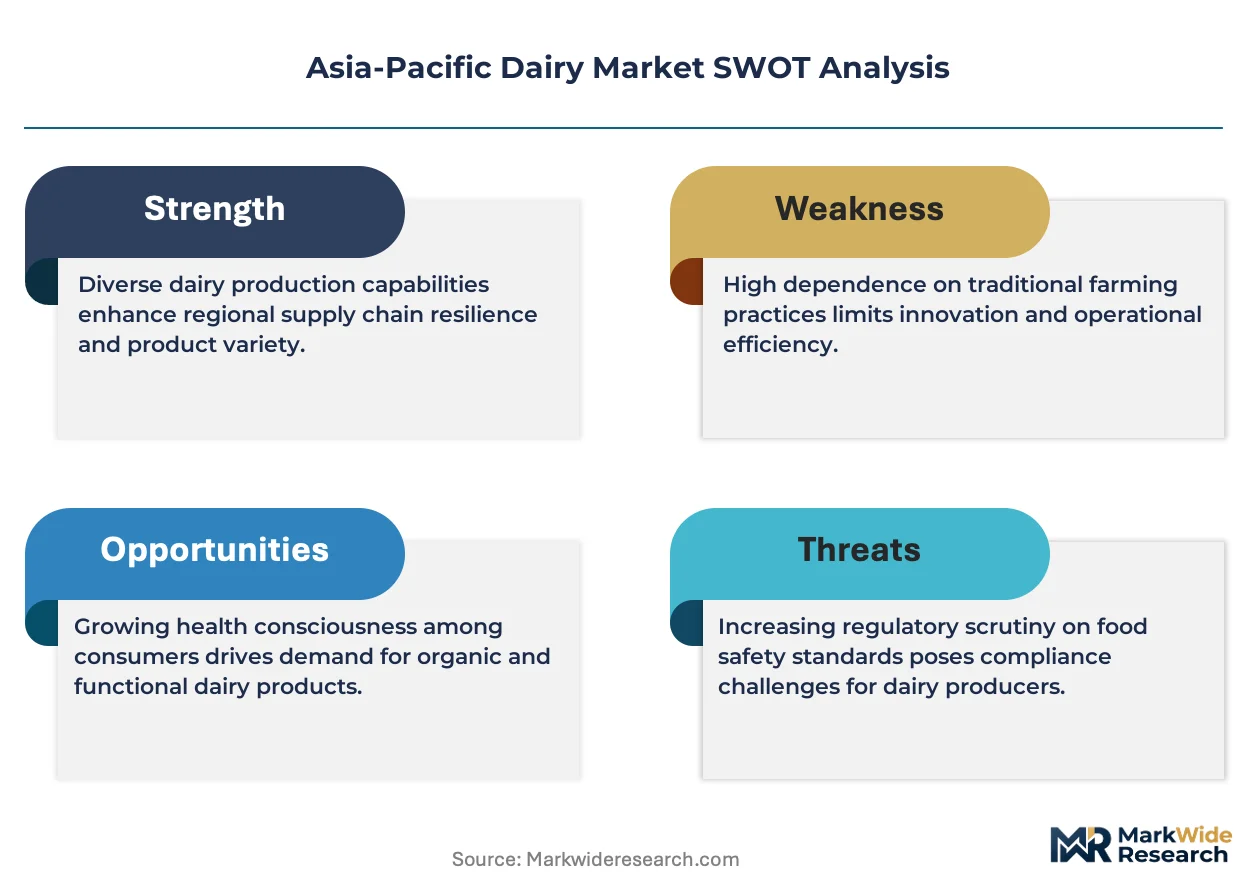
Aseptic processing and extended-shelf-life technology is reconfiguring how dairy processors balance freshness logistics with distribution radius in tropical Asia-Pacific climates. China Mengniu Dairy leverages ultra-high-temperature systems to anchor shelf-stable milk penetration across lower-tier Chinese cities. Inner Mongolia Yili Industrial Group sustains integrated pasture-to-plant operations that dominate raw milk sourcing security. Fonterra Co-operative Group navigates co-operative governance constraints while extending ingredient supply relationships into Southeast Asian food manufacturing.
Asia-Pacific dairy encompasses fluid milk, fermented products, fats, and concentrated proteins derived from bovine, buffalo, and caprine sources, typically standardized to specific fat and solids-not-fat percentages for commercial consistency. Cold-chain infrastructure gaps in Indonesia, Vietnam, and the Philippines perpetuate reliance on heat-treated formats with ambient stability exceeding six months. Yogurt commands margin concentration due to probiotic positioning and premium pricing elasticity in urban China and Japan. Cheese trails as the fastest-expanding product type, propelled by Western culinary integration in South Korean and Australian food service channels. Tetra Pak aseptic cartons retain packaging dominance where refrigeration continuity remains unreliable.
FSSAI in India enforces progressively stricter antibiotic residue thresholds and packaged food labeling norms that elevate compliance costs for informal sector suppliers. Japan's MHLW and China's SAMR maintain divergent probiotic health claim frameworks, fragmenting new product registration pathways across the region. Australia's FSANZ coordinates with Codex Alimentarius on dairy export standards, shaping market access for Oceanian processors into ASEAN. Stakeholders must monitor regulatory harmonization momentum between RCEP members, as mutual recognition agreements on dairy safety testing could redraw competitive boundaries faster than capacity investments.
Market Dynamics
Cold-chain infrastructure deficits across Southeast Asia are forcing dairy processors toward aseptic and extended-shelf-life formats that trade freshness premiums for distribution reach. This structural tension between product integrity and market access defines competitive strategy for regional operators.
Growth Catalysts
- Urban consumption upgrading:Tier-one Chinese cities demonstrate accelerating demand for probiotic yogurt and specialty cheese categories. Premium positioning in these markets supports margin expansion beyond commodity fluid milk economics.
- FSSAI traceability mandates:India's tightened packaged milk labeling requirements are formalizing procurement relationships between organized processors and certified dairy cooperatives. Informal sector suppliers face exclusion pressure.
- Aseptic packaging diffusion:Tetra Pak carton systems enable ambient distribution where refrigeration continuity fails. Indonesian and Vietnamese food service operators now source UHT milk for institutional channels previously served by powder reconstitution.
Market Restraints
- Raw milk supply concentration:China's Mengniu and Yili control pasture-to-plant integration across Inner Mongolia. Independent processors face captive supply constraints and input cost volatility during seasonal production dips.
- Antibiotic residue compliance:FSSAI threshold enforcement elevates testing costs for small-scale Indian suppliers. Informal sector participants lack laboratory infrastructure to meet progressive standards.
- Probiotic claim fragmentation:Divergent health claim frameworks between Japan's MHLW and China's SAMR force duplicate registration investments. New product launches face timeline extension and regulatory arbitrage complexity.
Strategic Opportunities
- Cheese category expansion:Western culinary integration in South Korean and Australian food service channels creates white space for specialty and processed cheese formats. Domestic production capacity remains underdeveloped relative to import dependency.
- RCEP harmonization momentum:Mutual recognition agreements on dairy safety testing could reduce redundant certification burdens. Australian and New Zealand exporters stand to benefit from streamlined ASEAN market access.
- Direct-to-retail cold chain:E-commerce grocery platforms in Chinese tier-two cities enable bypass of traditional wholesale layers. Temperature-controlled last-mile investments unlock premium product penetration beyond conventional retail footprints.
Industry Challenges
- Aseptic technician scarcity:UHT system operation and maintenance require specialized training unavailable in Vietnamese and Philippine labor markets. Processor expansion plans face workforce bottlenecks.
- Legacy cold-chain asset stranding:Existing refrigerated distribution networks in Indonesia deliver insufficient coverage for fermented product formats. Capital reallocation toward ambient-stable production lines encounters organizational resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dairy Market |
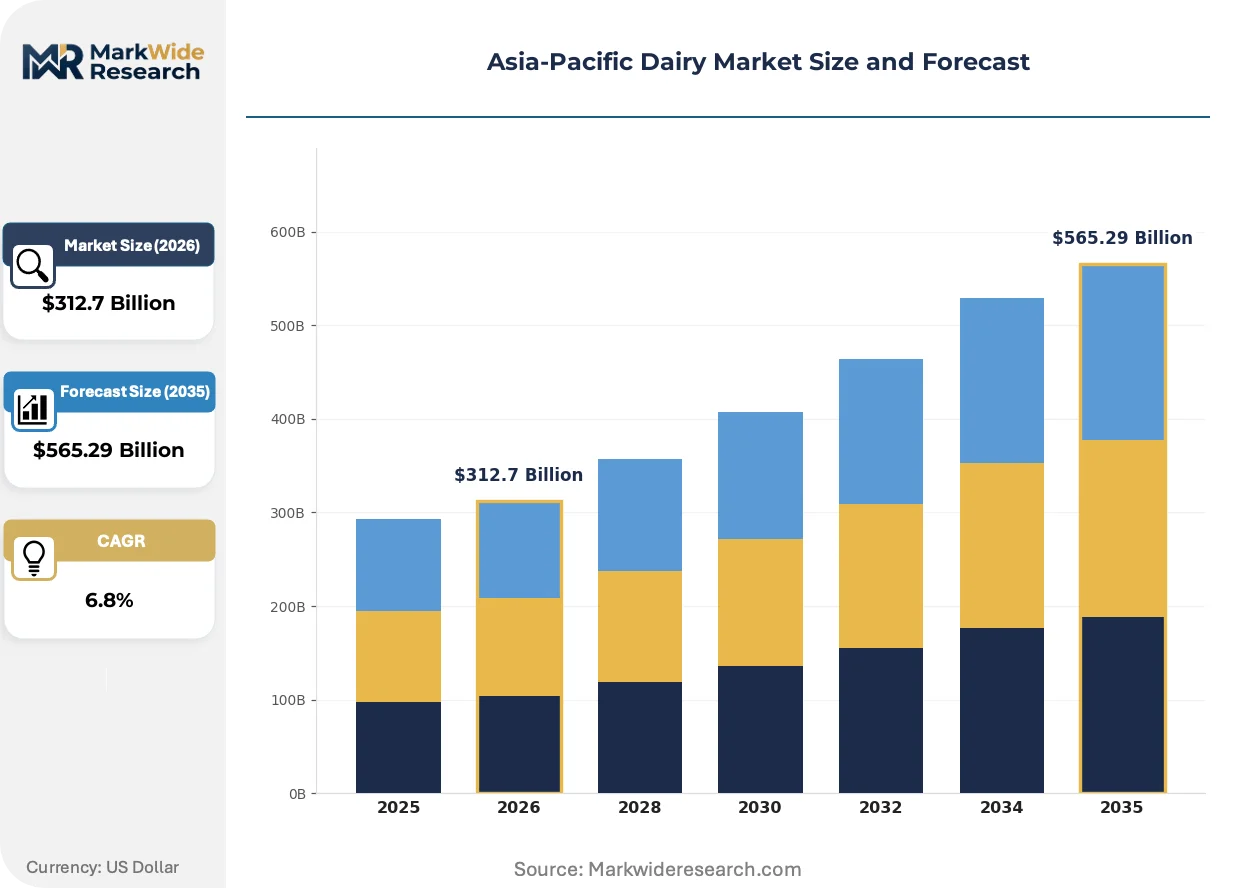
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter End User: Households, Food Service, Retailers, Industrial Users Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Direct Sales Packaging Type: Bottles, Tetra Packs, Pouches, Cans |
| Companies Covered | Gujarat Co-operative Milk Marketing Federation, China Mengniu Dairy, Inner Mongolia Yili Industrial Group, Hatsun Agro Product, Meiji Holdings, Yakult Honsha, Fonterra Co-operative Group, Danone, Nestlé, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dairy Market Emerging Trajectories
Aseptic processing advances and regulatory divergence are simultaneously compressing distribution constraints and fragmenting compliance pathways across Asia-Pacific dairy markets. Technology adoption and policy response now determine competitive positioning more than scale economics alone.
Ultra-high-temperature sterilization systems are collapsing the traditional trade-off between freshness positioning and geographic reach in tropical climates. Chinese processors deploy these systems to anchor shelf-stable milk penetration in lower-tier cities where cold-chain continuity remains unreliable. The technology is collapsing radius limitations that previously confined premium fluid milk to urban cores with dependable refrigeration.
SAMR's probiotic health claim framework diverges from Japan's MHLW standards, creating parallel registration requirements for cross-border product launches. This regulatory friction elevates compliance costs for fermented dairy innovators seeking multi-market presence. Chinese and Japanese operators now maintain separate formulation and labeling strategies rather than pursuing harmonized regional portfolios.
Food service operators across Southeast Asia are consolidating dairy procurement through centralized purchasing agreements with integrated processors. Traditional wholesale layering through multiple intermediaries faces displacement as institutional buyers demand traceability documentation and volume pricing transparency. This concentration pattern is most visible in Vietnamese and Indonesian hotel and restaurant chains sourcing UHT and condensed milk formats.
Asia-Pacific Dairy Market Segmentation
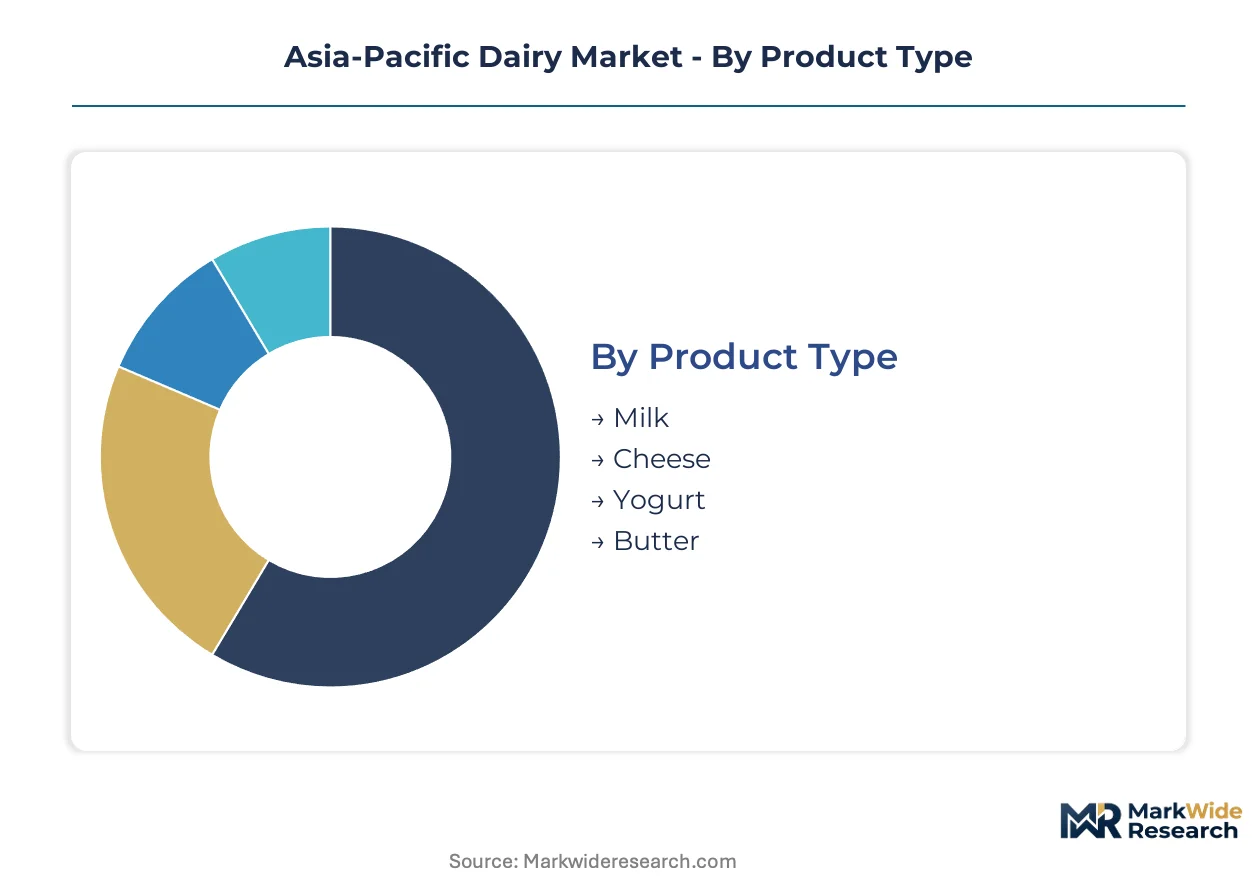
Segmentation in Asia-Pacific dairy reveals how product integrity requirements, channel infrastructure gaps, and end-use concentration patterns reshape competitive priorities across tropical and temperate climate zones. Understanding these divisions clarifies why aseptic formats dominate Indonesian distribution while fresh fermented products command premium positioning in Japanese convenience retail.
Product Type:
After-sales service intensity varies sharply across dairy formats, with extended-shelf-life systems demanding technical maintenance contracts that commodity fluid milk simply does not require.
- Milk:Standardized fluid milk carries fat percentages ranging from skim to full-cream, with ultra-high-temperature processing enabling ambient distribution across Southeast Asian markets lacking refrigeration continuity. Demand concentrates most visibly in Chinese tier-two and tier-three cities where Mengniu and Yili deploy shelf-stable formats to bypass cold-chain limitations. Tetra Pak aseptic carton systems anchor this segment's packaging infrastructure.
- Yogurt:Fermented dairy with live probiotic cultures requires temperature-controlled distribution throughout the supply chain, limiting viable radius to markets with dependable cold-chain infrastructure. Urban China and Japan demonstrate the strongest demand concentration, with premium positioning supported by health claim differentiation under divergent SAMR and MHLW regulatory frameworks. Margin structures here exceed commodity fluid milk economics substantially.
- Cheese:Western culinary integration in South Korean and Australian food service channels propels specialty and processed formats; domestic production capacity remains underdeveloped relative to import dependency.
- Butter:Concentrated milk fat serves bakery and food manufacturing applications across ASEAN, with Australian and New Zealand exporters supplying bulk ingredient volumes.
Milk holds the largest share; momentum sits with cheese as Western dietary patterns penetrate East Asian food service channels.
End User:
Cost tier stratification separates premium household purchasers from price-sensitive institutional buyers negotiating centralized procurement agreements.
- Households:Direct consumption purchases concentrate in urban centers with established modern retail infrastructure, particularly Chinese tier-one cities and Japanese metropolitan areas. Probiotic yogurt and premium fluid milk command household spending allocation due to health positioning and convenience factors.
- Food Service:Hotels, restaurants, and institutional catering operations across Vietnam and Indonesia are consolidating dairy procurement through direct processor relationships, displacing traditional wholesale layering. UHT and condensed milk formats dominate this channel where traceability documentation and volume pricing transparency have become non-negotiable requirements.
- Retailers:Supermarket and convenience store chains function as intermediaries with increasing private-label penetration in mature markets like Australia and Japan.
- Industrial Users:Food manufacturers source concentrated proteins and milk fats for processed product formulations, with Fonterra maintaining ingredient supply relationships across Southeast Asian manufacturing bases.
Food service represents the fastest-expanding demand tier; retailers retain the largest transaction volume concentration.
Distribution Channel:
Channel selection directly reflects refrigeration reliability and last-mile temperature control capabilities across diverse national infrastructures.
- Supermarkets:Modern retail chains with integrated cold-chain infrastructure dominate fresh dairy distribution in Australia, Japan, and urban China. These outlets support premium yogurt and specialty cheese formats requiring continuous temperature maintenance.
- Online Retail:E-commerce grocery platforms enable direct-to-consumer delivery with temperature-controlled logistics, unlocking market penetration beyond conventional retail footprints in Chinese tier-two cities. JD.com and Alibaba's Hema formats exemplify this channel's expansion trajectory.
- Convenience Stores:High-frequency purchase locations in Japan and South Korea stock single-serve fermented products and flavored milk beverages for immediate consumption occasions.
- Direct Sales:Dairy cooperatives and processor-owned distribution networks serve rural Indian markets where formal retail penetration remains limited; FSSAI traceability mandates are formalizing these procurement relationships.
Supermarkets command the largest share; online retail is climbing the fastest as digital grocery platforms expand temperature-controlled fulfillment capabilities.
Packaging Type:
Packaging technology selection balances product protection requirements against distribution infrastructure realities and consumer convenience expectations.
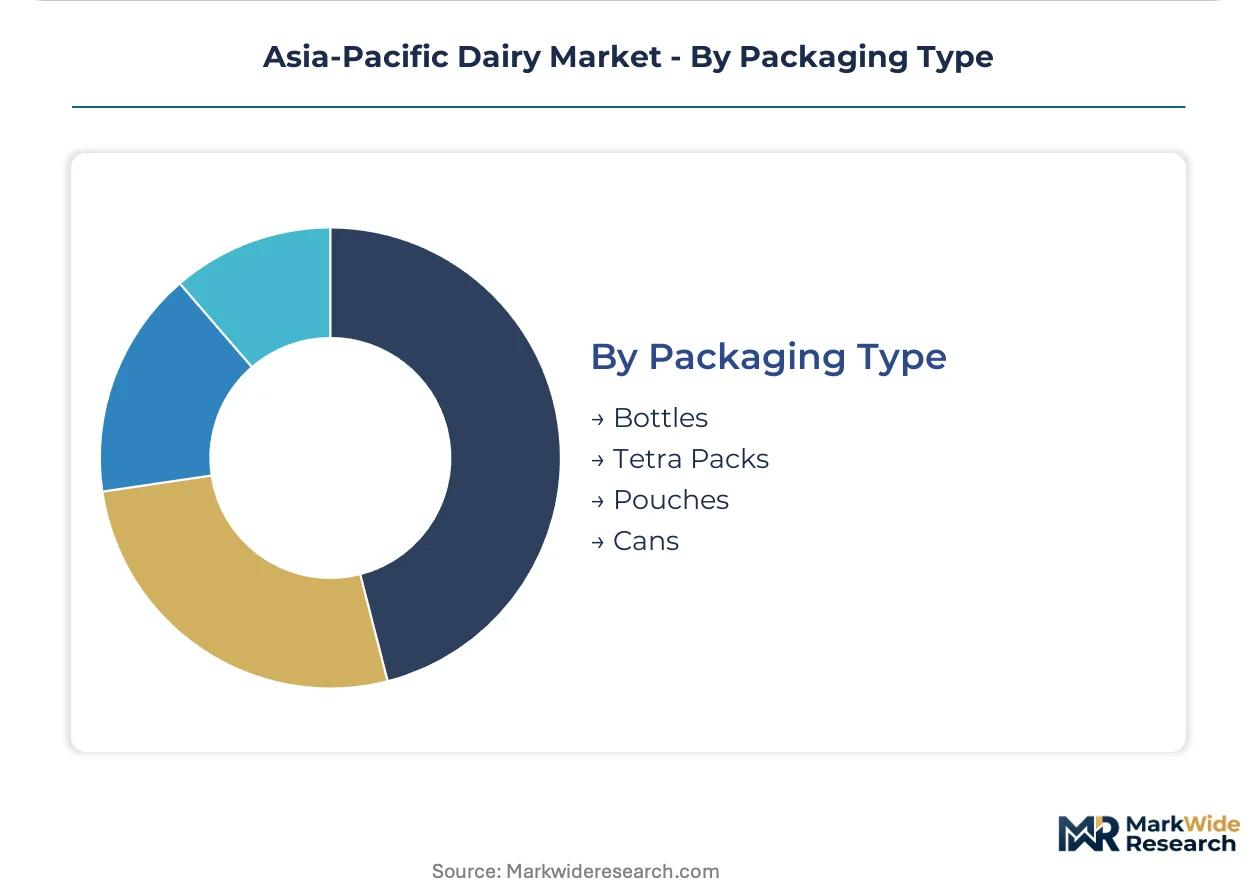
- Tetra Packs:Aseptic carton systems from Tetra Pak enable ambient-stable distribution where refrigeration continuity fails, dominating Southeast Asian markets across Indonesia, Vietnam, and the Philippines. These formats support six-month shelf stability for UHT milk penetration into lower-tier cities.
- Bottles:Polyethylene terephthalate and glass containers serve fresh pasteurized milk distribution in cold-chain-reliable markets including Japan, Australia, and Chinese tier-one cities. Premium positioning and freshness signaling drive bottle selection despite higher logistics costs.
- Pouches:Flexible film packaging offers cost-efficient formats for price-sensitive mass markets, particularly in Indian household consumption and Southeast Asian condensed milk applications.
- Cans:Metal packaging preserves concentrated and evaporated milk products for institutional food service and industrial manufacturing applications across ASEAN processing sectors.
Tetra Packs retain the largest installed base; pouches are gaining share fastest in cost-optimized mass market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics vary sharply across the Asia-Pacific dairy landscape. Australia and New Zealand maintain substantial surplus positions serving ASEAN food manufacturing demand, while China, Japan, and South Korea rely on ingredient imports to bridge domestic production shortfalls.
China
Tier-one cities drive probiotic yogurt and specialty cheese consumption as urban households upgrade dietary patterns. SAMR maintains divergent health claim frameworks from regional counterparts, forcing duplicate product registrations for cross-border launches. Inner Mongolia pasture-to-plant integration anchors raw milk security for processors serving Beijing and Shanghai metropolitan corridors.
India
FSSAI traceability mandates are formalizing procurement between organized processors and certified dairy cooperatives, squeezing informal sector participation. Antibiotic residue thresholds now require laboratory infrastructure beyond small-scale supplier capabilities. Gujarat and Maharashtra dairy clusters concentrate processing capacity for national distribution networks.
Japan
MHLW probiotic standards differ from Chinese SAMR frameworks, fragmenting regional product development pathways. Convenience retail channels stock single-serve fermented products for high-frequency consumption occasions. Tokyo-Osaka metropolitan corridors concentrate premium yogurt demand and cold-chain infrastructure investment.
Australia
FSANZ coordination with Codex Alimentarius shapes dairy export standards governing ASEAN market access. Bulk ingredient supply relationships extend into Southeast Asian food manufacturing bases. Victorian and New South Wales production clusters dominate butter and milk powder export volumes.
Vietnam
Food service operators consolidate dairy procurement through direct processor relationships, displacing traditional wholesale intermediaries. Cold-chain infrastructure gaps perpetuate reliance on UHT formats with ambient stability exceeding six months. Ho Chi Minh City hotel and restaurant chains now source traceable milk products for institutional channels.
Asia-Pacific Dairy Market Vendor Landscape
On the supply side, the industry is bifurcated between integrated pasture-to-plant operators and ingredient-focused exporters serving regional manufacturing demand. The competitive terrain separates captive raw milk controllers from technology licensors and brand marketers. Three archetypes dominate: cooperative governance structures with farmer ownership, state-affiliated national champions with domestic supply security, and multinational nutrition platforms with regional brand portfolios. Capacity expansion and regulatory compliance technology represent the primary competitive vectors reshaping participant positioning.
Among cooperative-structured suppliers, Fonterra Co-operative Group and Gujarat Co-operative Milk Marketing Federation exemplify farmer-governed models that anchor procurement relationships across dispersed production bases. China Mengniu Dairy occupies a position within the state-affiliated tier that leverages integrated supply chains for domestic market penetration. These three entities represent distinct governance archetypes—Antipodean export cooperative, Indian federal cooperative, and Chinese national champion—each responding to divergent regulatory and infrastructure constraints across their respective home markets.
| Leading Market Players |
|---|
| Gujarat Co-operative Milk Marketing Federation |
| China Mengniu Dairy |
| Inner Mongolia Yili Industrial Group |
| Hatsun Agro Product |
| Meiji Holdings |
| Yakult Honsha |
| Fonterra Co-operative Group |
| Danone |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
Antibiotic residue compliance thresholds under India's FSSAI compress margins for informal suppliers while elevating procurement premiums for certified cooperatives, simultaneously widening price spreads between organized and unorganized supply tiers and accelerating consolidation toward traceable cold-chain networks.
Pricing Analysis
Aseptic technology-generation pricing gaps separate premium UHT formats from conventional pasteurized milk and emerging extended-shelf-life innovations. Three-tier pricing structure across premium probiotic yogurt, standard fluid milk, and economy reconstituted powder segments reflects cold-chain reliability and certification grade differentiation. Pricing pressure stems from raw milk supply concentration in Inner Mongolia, where Mengniu and Yili exercise captive sourcing leverage. Food service operators demonstrate lowest price sensitivity due to traceability mandates, while rural Indian households remain most responsive to cost shifts.
Supply Chain Analysis
Tariff exposure between Australia and ASEAN markets dominates supply chain risk calculations for bulk ingredient exporters. Raw milk sourcing concentrates in China, New Zealand, and India; feed grain dependencies and aseptic packaging equipment imports create secondary vulnerability nodes. Single-source vulnerability characterizes Tetra Pak's aseptic carton dominance across Southeast Asian ambient distribution channels. Distribution runs through processor-direct relationships with Vietnamese and Indonesian hotel chains, displacing traditional wholesale layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FSSAI traceability mandates and divergent probiotic claim frameworks across SAMR and MHLW jurisdictions erect compliance barriers that favor incumbent scale and specialized technical infrastructure.
For Market Incumbents: Pre-empt informal sector displacement in India by accelerating certified cooperative procurement partnerships before FSSAI enforcement tightens further. Invest in aseptic technician training programs to resolve workforce bottlenecks constraining Vietnamese and Philippine expansion. Backward integration into pasture operations secures raw milk supply security against seasonal volatility.
For New Entrants and Emerging Players: Establish a beachhead in specialty cheese formats for South Korean food service channels, where Western culinary integration outpaces domestic production capacity. Target Australian ingredient supply relationships with ASEAN food manufacturers seeking Fonterra alternatives. Lead with RCEP harmonization positioning to streamline cross-border safety testing documentation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated pasture-to-plant operators with regulatory compliance infrastructure already deployed. Long-term viability over the coming decade rests on cold-chain asset positioning in Chinese tier-two cities and traceability technology ownership. Watch for mutual recognition agreement momentum between RCEP members as the inflection signal for competitive boundary shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Capacity Expansion | UHT system deployment unlocks ambient distribution across Indonesian and Vietnamese cold-chain gaps. |
| Traceability Technology Investment | FSSAI-compliant labeling systems secure organized processor procurement relationships in India. |
| Direct Food Service Partnerships | Processor-direct agreements with Ho Chi Minh City hotel chains displace wholesale intermediaries. |
| Probiotic Claim Harmonization | Parallel SAMR and MHLW registration strategies reduce cross-border launch friction. |
| E-commerce Cold-Chain Buildout | Temperature-controlled last-mile networks enable JD.com and Hema penetration beyond tier-one cities. |
Methodological Framework
A standing panel of dairy procurement directors at Southeast Asian food service operators, FSSAI compliance officers at Indian cooperatives, aseptic packaging engineers at Tetra Pak deployment sites, and cold-chain logistics managers at Chinese e-commerce platforms provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from customs trade databases, SAMR and MHLW regulatory filings, Codex Alimentarius standards documentation, and processor financial disclosures. Bottom-up volume modeling and top-down value triangulation anchored forecast integrity.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, end-user category, distribution channel infrastructure, and packaging technology generation. CAGRs derived from growth driver elasticity modeling against cold-chain investment trajectories and regulatory enforcement timelines. Forecast inputs incorporated RCEP harmonization momentum indicators and urban consumption upgrading patterns in Chinese metropolitan corridors.
Sensitivities concentrate around FSSAI enforcement intensity, RCEP mutual recognition agreement progress, and aseptic technician workforce development rates in Southeast Asian markets. Forecasts reflect documented assumptions regarding infrastructure investment continuity and regulatory divergence persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Specialty Cheese Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Milk Protein Crisps Market
Dairy Products
Organic Milk Protein Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Ricotta Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Flavoured Milk Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Goat Milk Products Market
Dairy Products
Organic Milk Powder Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Global Grass Fed Dairy Product Market