
 Nigeria Yogurt Drinks Market | 2026-2036
Nigeria Yogurt Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Yogurt Drinks Market Intelligence
Market Context
NAFDAC's updated dairy fortification standards is broadening the cost-of-entry calculus for new entrants seeking shelf space in Nigeria's formal retail channels. FrieslandCampina WAMCO Nigeria PLC leverages its backward integration into local milk collection networks to sustain margin resilience against imported input volatility. Nestlé Nigeria PLC anchors premium positioning through specialized pediatric and adult nutrition lines that command dedicated refrigerator space in urban supermarkets.
Product Definition and Segment Structure
Nigeria yogurt drinks comprise fermented dairy or dairy-alternative beverages containing live or inactive cultures, typically standardized to protein content between 2.5% and 3.5% and packaged in single-serve formats for ambient or chilled distribution. The category serves both refreshment and functional nutrition purposes, with probiotic strains increasingly specified for digestive health claims. Flavored variants dominate volume throughput in open-market and convenience channels, while probiotic positioning captures margin pools through pharmacy and modern-trade placements. Tetra Pak aseptic formats are displacing traditional bottles in rural penetration strategies due to ambient stability and lower logistics burden.
Regulatory Environment and Outlook
NAFDAC, the Standards Organisation of Nigeria, and state-level environmental health agencies collectively enforce dairy safety, labeling accuracy, and cold chain compliance across Nigeria's federated regulatory landscape. SON's mandatory product certification creates non-tariff barriers that favor capitalized incumbents with dedicated quality assurance laboratories. Stakeholders must monitor evolving NAFDAC guidance on probiotic strain approvals and sugar content thresholds, as these parameters will determine which SKUs retain distribution licenses in formal channels.
Market Dynamics
NAFDAC's dairy fortification mandates and cold chain infrastructure investments are compressing margins for informal processors while accelerating formalization of Nigeria's yogurt drinks value chain.
Growth Catalysts
- NAFDAC fortification standards:Mandatory micronutrient enrichment requirements are pushing traditional open-market producers toward licensed manufacturing, expanding addressable market for compliant SKUs in formal retail channels.
- Urban household consumption clusters:Lagos and Abuja metropolitan areas demonstrate concentrated demand for probiotic-positioned products, creating anchor markets that subsidize rural distribution economics.
- Aseptic packaging technology:Tetra Pak ambient-stable formats reduce refrigeration dependency, enabling shelf presence in northern Nigerian states with limited cold chain penetration.
Market Restraints
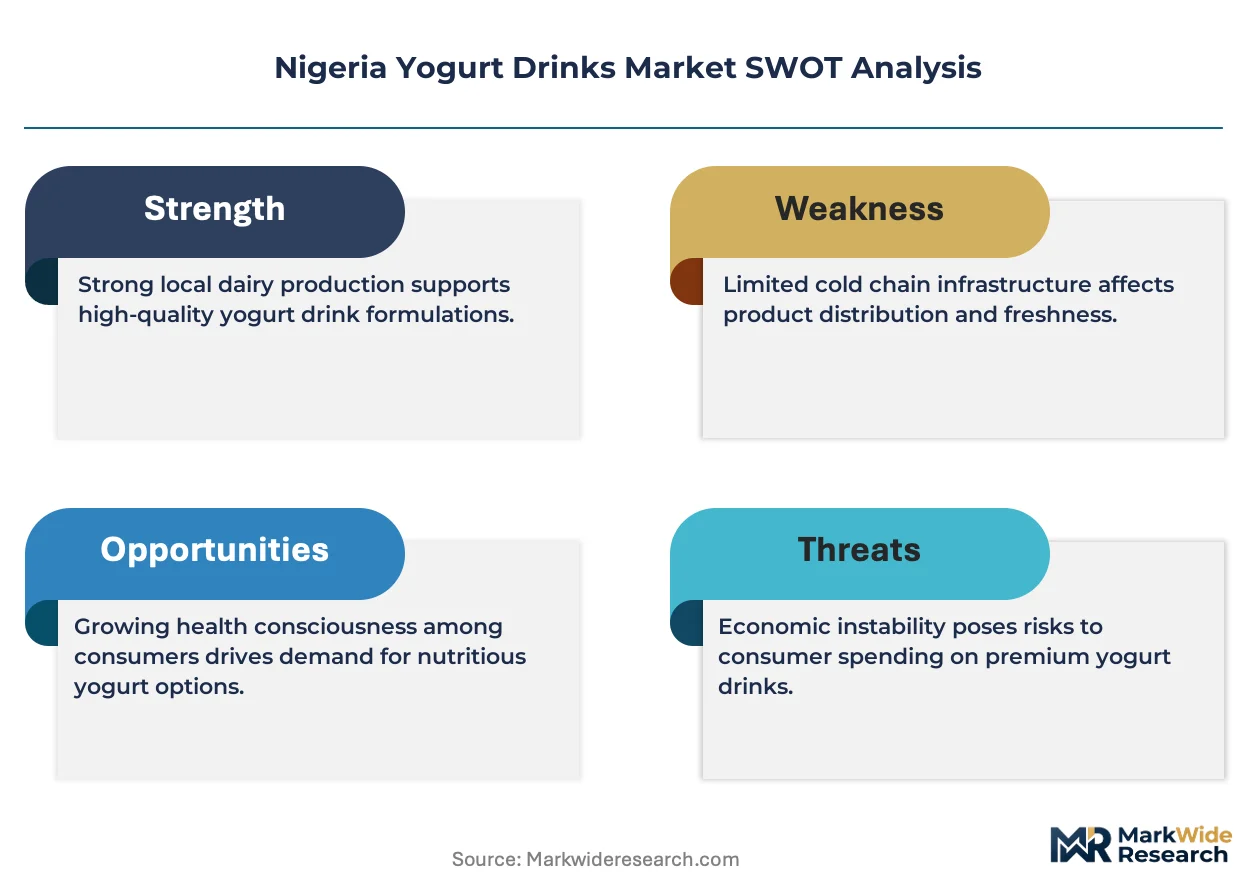
- Imported milk powder price volatility:Nigeria's dependence on foreign exchange-denominated dairy inputs exposes processors to naira depreciation risk, compressing gross margins during currency stress periods.
- SON certification backlog:Mandatory product certification timelines create inventory holding costs and delay revenue recognition for new market entrants lacking established quality assurance infrastructure.
- Raw milk supply fragmentation:Smallholder dairy collection networks in northern Nigeria suffer from seasonal yield variation and adulteration risks, constraining backward integration economics for processors.
Strategic Opportunities
- South-East corridor underpenetration:Anambra and Enugu states exhibit modern trade growth without matching yogurt drinks category development, presenting first-mover advantages for chilled distribution investment.
- Pharmacy channel expansion:Digestive health claims positioning enables placement alongside OTC medications, capturing margin premiums from health-seeking consumers outside conventional grocery occasions.
- Sugar content threshold anticipation:Proactive reformulation ahead of prospective NAFDAC guidance preserves license continuity and positions compliant brands for potential front-of-pack labeling advantages.
Industry Challenges
- Cold chain technician scarcity:Qualified refrigeration maintenance personnel are concentrated in Lagos and Abuja, limiting reliable chilled distribution expansion into secondary cities.
- Probiotic strain validation timelines:NAFDAC approval processes for novel bacterial cultures extend product development cycles, delaying functional claim launches against competitor first-movers.
- Legacy distributor credit systems:Open-market trade channels operate on informal consignment arrangements that strain working capital and complicate receivables risk management for formalizing processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Yogurt Drinks Market |
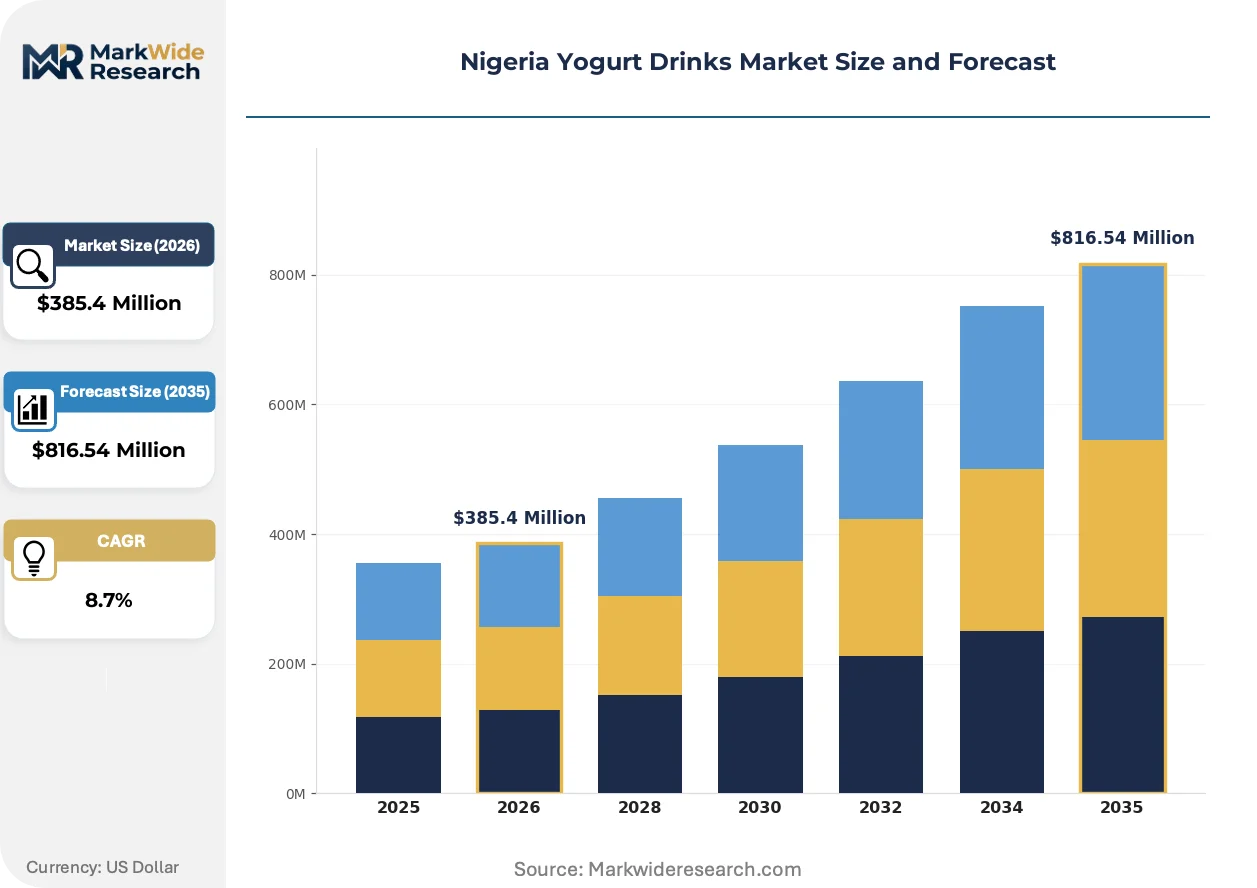
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Organic, Probiotic Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online, Retailers Consumer Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Nestlé Nigeria PLC, Viju Industries Limited (Vitamilk), Chi Limited (Chivita), TGI Group (Gino), Seven-Up Bottling Company Limited, FrieslandCampina WAMCO Nigeria PLC (Peak), Danone S.A. (Fan Milk International), Integrated Dairies Limited, Promasidor Nigeria Limited (Cowbell), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Yogurt Drinks Market Strategic Shifts & Innovations
Aseptic processing advances and regulatory tightening are converging to reshape formulation priorities and channel economics across Nigeria's yogurt drinks landscape.
Tetra Pak's ambient-stable carton formats are absorbing volume share from traditional HDPE bottles in rural penetration strategies, enabling processors to bypass refrigeration infrastructure gaps while maintaining shelf stability. Northern Nigerian distributors are adopting these formats at accelerating rates, compressing logistics costs and expanding daily distribution radius from urban production centers. The technology is absorbing margin pressure from diesel-powered cold transport while unlocking price points accessible to mass-market consumption occasions.
NAFDAC's evolving guidance on probiotic strain approvals and sugar content thresholds is forcing preemptive reformulation investments across licensed manufacturers. The regulatory uncertainty is compressing SKU rationalization timelines, with processors consolidating flavor ranges to preserve compliance agility. Pediatric and adult nutrition lines face the most stringent scrutiny, driving dedicated quality assurance hiring and third-party laboratory testing expenditures.
Urban supermarket buyers are consolidating refrigerator space allocations toward certified functional brands, displacing informal market suppliers from modern trade channels. This procurement concentration is compressing shelf access for unlicensed processors while rewarding capitalized incumbents with dedicated cold storage positioning. The shift is most visible in Lagos Island and Abuja's Central Business District retail clusters, where pharmacy-adjacent placement commands premium slotting fees.
Nigeria Yogurt Drinks Market Segmentation
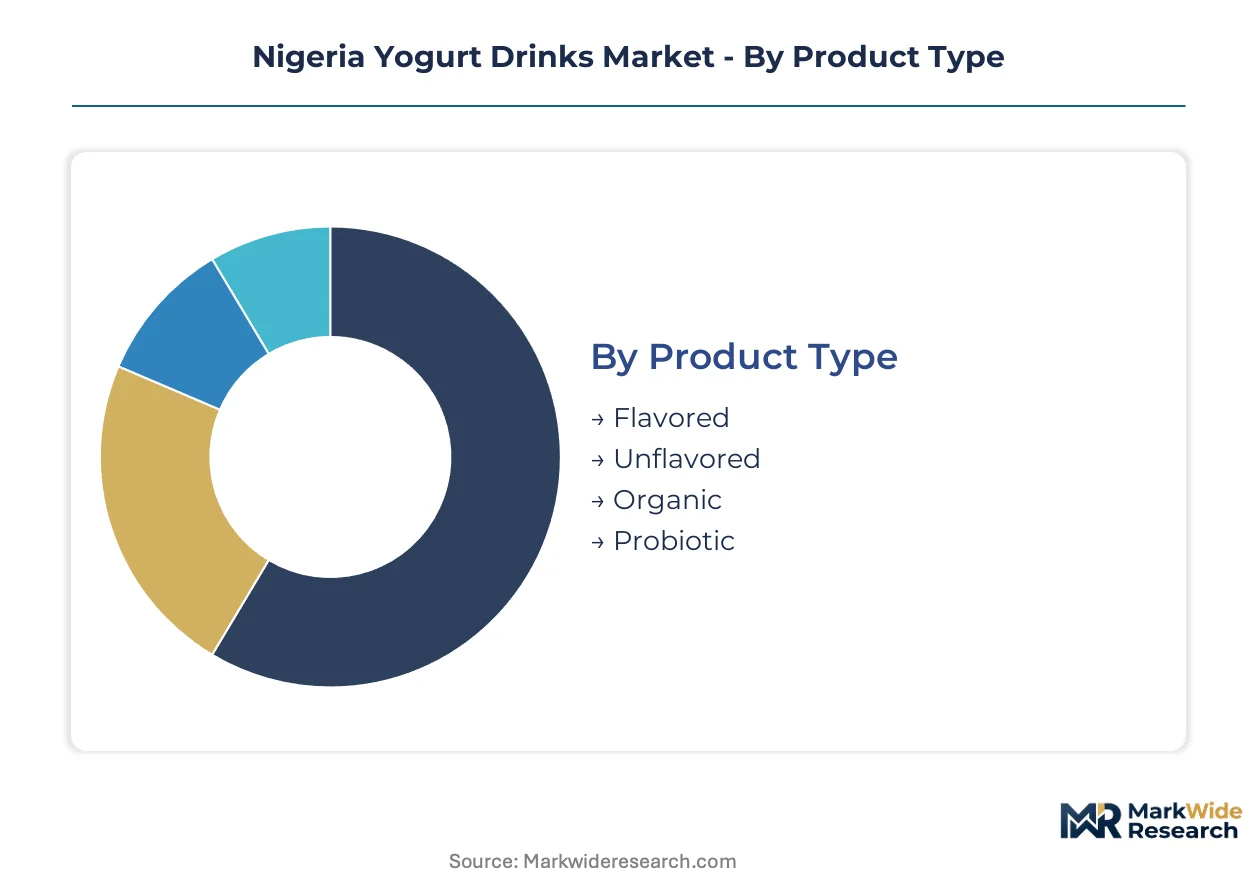
Segmentation reveals how NAFDAC compliance investments and cold chain capabilities are concentrating manufacturing capacity toward specific product-packaging combinations. Understanding these divides exposes where margin pools form and which distribution investments unlock addressable demand.
Product Type:
Supply concentration favors segments with the technical infrastructure to meet fortification mandates and probiotic strain validation requirements.
- Flavored:Sugar-adjusted formulations with fruit or vanilla profiles dominate volume throughput in open-market and convenience channels. Lagos and Abuja households drive repeat purchase frequency for chilled variants positioned as refreshment alternatives to carbonated soft drinks.
- Probiotic:Live culture specifications require dedicated fermentation controls and NAFDAC strain documentation. Pharmacy channel placement in urban centers captures health-seeking consumers willing to pay premiums for digestive health claims.
- Unflavored:Plain fermented dairy base serves ingredient markets and price-sensitive bulk consumption in northern states with limited cold chain penetration.
- Organic:Certified milk sourcing and additive-free positioning targets expatriate communities and high-income enclaves in Ikoyi and Maitama districts.
Flavored variants absorb the bulk of installed capacity; probiotic positioning is expanding most quickly.
Packaging Type:
Cost tier differentiation separates ambient-stable formats from refrigeration-dependent alternatives, reshaping distribution economics across Nigeria's infrastructure gradients.
- Tetra Packs:Aseptic carton technology enables shelf-stable distribution without cold chain dependency. Northern Nigerian distributors adopt these formats to extend daily distribution radius from Kaduna and Kano production hubs while bypassing diesel-powered refrigeration costs.
- Bottles:HDPE and PET formats retain share in chilled premium segments where visual product differentiation commands supermarket refrigerator space. Lagos Island retail clusters favor transparent bottles for probiotic visibility claims.
- Pouches:Flexible film sachets dominate price-accessible rural markets through informal trade channels with minimal packaging cost burden.
- Cans:Aluminum formats occupy niche positioning for on-the-go consumption occasions in Abuja Central Business District vending and foodservice outlets.
Bottles retain the bulk of refrigerated channel capacity; Tetra Packs are climbing the fastest as ambient distribution expands.
Distribution Channel:
Volume concentration in modern trade is accelerating formalization pressure on traditional supply arrangements.
- Supermarkets:Organized retail chains in Lagos and Abuja enforce NAFDAC license verification and dedicated cold storage compliance. Refrigerator space allocation increasingly favors certified functional brands with proven turnover velocity.
- Convenience Stores:Neighborhood proximity formats bridge formal and informal trade, accepting limited SKU ranges on consignment terms that strain processor working capital.
- Retailers:Open-market stall networks and traditional trade dominate aggregate volume in southern Nigeria's dense urban settlements.
- Online:E-commerce platforms capture emerging demand from time-constrained professionals in Lekki and Wuse districts, though cold chain reliability limits category penetration.
Retailers absorb the bulk of volume throughput; supermarkets are gaining share fastest as modern trade penetration deepens.
Consumer Age Group:
Application-specific formulation requirements divide manufacturing priorities between pediatric nutrition and adult refreshment positioning.
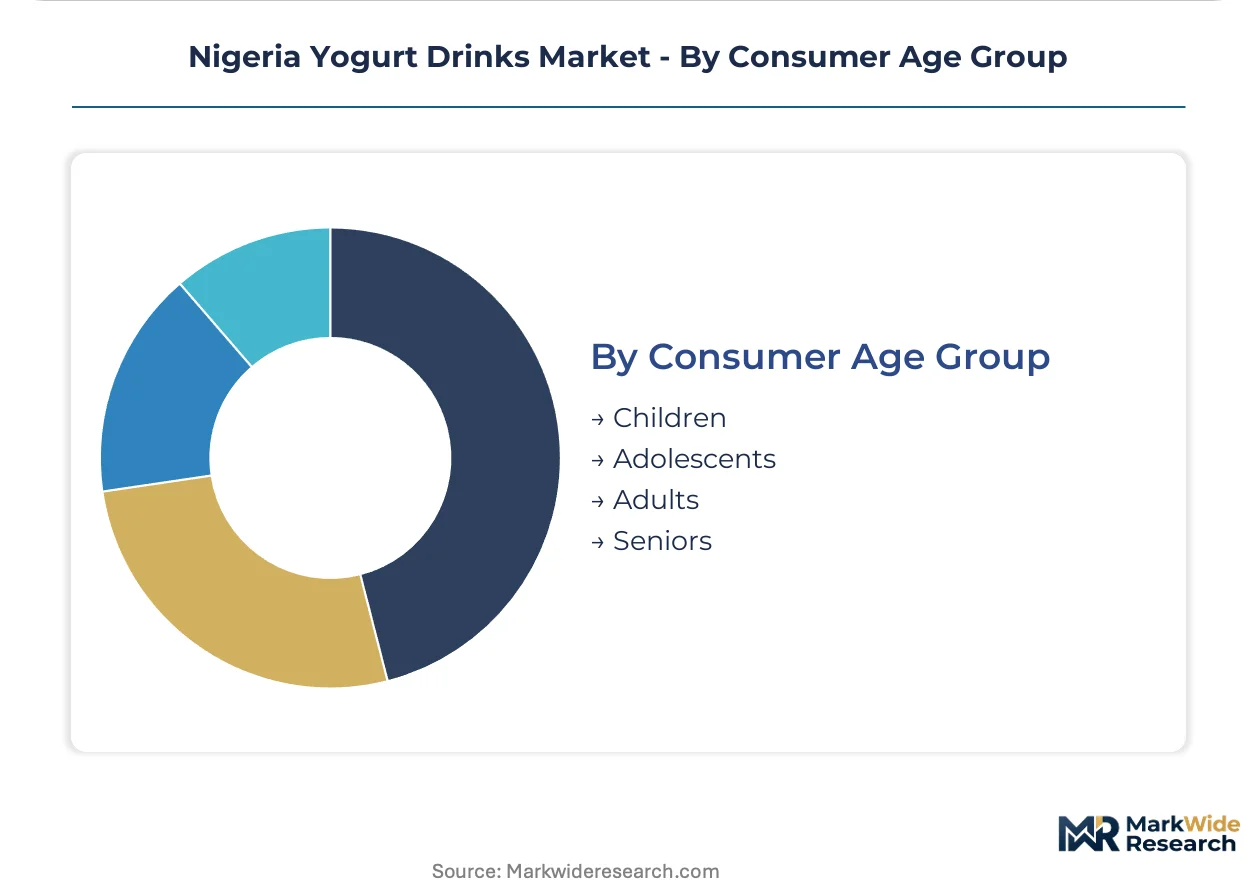
- Children:Fortified formulations with controlled sugar profiles and child-friendly flavors command dedicated production lines with stringent quality assurance protocols. School feeding program specifications influence bulk procurement decisions.
- Adults:Functional positioning around digestive health and meal replacement drives probiotic SKU development for urban professional consumption occasions.
- Adolescents:Flavored refreshment variants with social media-responsive packaging design target secondary school and university campus proximity channels.
- Seniors:Low-lactose and high-calcium formulations occupy emerging niche positioning through pharmacy and specialized nutrition retail.
Adults absorb the bulk of current capacity investment; children-oriented fortified variants are expanding most quickly as school nutrition programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nigerian Export Processing Zones Authority's tax incentives for food processing clusters have concentrated yogurt drinks manufacturing capacity around Lagos and Ogun State corridors. NAFDAC's dairy fortification mandates and SON certification requirements create regulatory moats that favor processors with established quality infrastructure in these designated zones.
Lagos State
Urban household consumption clusters in Lagos Island, Lekki, and Ikeja drive premium probiotic demand through modern trade channels. NAFDAC's cold chain compliance inspections concentrate enforcement resources on these high-volume retail corridors. FrieslandCampina WAMCO Nigeria PLC anchors production gravity in Ogun State border zones to access Lagos distribution networks.
Federal Capital Territory
Abuja's Central Business District and Wuse districts exhibit concentrated demand for pharmacy-channel probiotic positioning among health-seeking professionals. The Standards Organisation of Nigeria maintains certification laboratory capacity in the FCT, reducing compliance timelines for processors serving northern markets. Tetra Pak ambient formats penetrate satellite towns where cold chain infrastructure remains limited.
Oyo State
Ibadan's emerging modern trade clusters and university campus proximity channels absorb flavored variant volume at price points below Lagos premiums. State environmental health agencies enforce dairy safety protocols that push informal processors toward licensed manufacturing. Chi Limited's Chivita brand maintains distribution presence through consolidated retailer networks in Bodija and Ring Road markets.
Kano State
Northern Nigeria's largest urban center exhibits demand concentration for shelf-stable Tetra Pak formats that bypass refrigeration dependency. Seasonal raw milk supply fragmentation from smallholder networks constrains backward integration economics for processors seeking local sourcing. Danone S.A.'s Fan Milk International leverages established cold distribution infrastructure from historical ice cream operations.
Rivers State
Port Harcourt's oil-sector professional population sustains premium positioning for imported-input formulations with dedicated pediatric nutrition claims. NAFDAC's port inspection protocols for dairy imports create inventory holding costs that favor processors with bonded warehouse capacity. Promasidor Nigeria Limited's Cowbell brand competes through price-accessible sachet formats in informal trade channels.
Nigeria Yogurt Drinks Market Key Industry Players
European-heritage multinationals anchor one tier through backward integration into local milk collection; Nigerian-owned specialists hold volume positions in flavored and price-accessible segments. The vendor base concentrates around capitalized incumbents with dedicated NAFDAC compliance infrastructure and established cold chain partnerships. Three archetypes dominate: integrated dairy processors with captive milk supply, beverage conglomerates leveraging cross-category distribution, and regional specialists in ambient-stable formats. Competitive moves center on SKU rationalization ahead of sugar content regulatory guidance and Tetra Pak technology licensing for northern market penetration.
Among European-heritage integrated processors, FrieslandCampina WAMCO Nigeria PLC and Danone S.A. occupy positions defined by captive milk collection networks and historical cold chain infrastructure. Nestlé Nigeria PLC exemplifies the nutrition-specialist archetype through pediatric and adult functional positioning that commands dedicated refrigerator space. Nigerian-owned volume players Viju Industries Limited and Chi Limited represent the flavored-segment tier, competing through price-accessible formulations and consolidated traditional trade distribution.
| Leading Market Players |
|---|
| Nestlé Nigeria PLC |
| Viju Industries Limited (Vitamilk) |
| Chi Limited (Chivita) |
| TGI Group (Gino) |
| Seven-Up Bottling Company Limited |
| FrieslandCampina WAMCO Nigeria PLC (Peak) |
| Danone S.A. (Fan Milk International) |
| Integrated Dairies Limited |
| Promasidor Nigeria Limited (Cowbell) |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between NAFDAC-licensed and informal processors manifests in divergent pricing power and supply chain architectures across Nigeria's yogurt drinks landscape. Premium shelf placement in Lagos supermarkets commands dedicated cold storage investment, while ambient-stable Tetra Pak formats enable price-accessible penetration through informal distributor networks with minimal refrigeration burden.
Pricing Analysis
Short lead-time premiums attach to chilled probiotic SKUs with validated strain documentation, while spot inventory of ambient-stable formats trades at volume discounts through northern distributor networks. Three-tier pricing structure across premium, standard, and economy levels reflects NAFDAC compliance grade, cold chain reliability, and packaging format sophistication. Pricing pressure stems from naira depreciation against foreign exchange-denominated milk powder inputs, compressing margins for import-dependent processors. Price sensitivity concentrates in northern rural markets where sachet formats dominate; least sensitivity appears among urban pharmacy-channel buyers seeking digestive health claims.
Supply Chain Analysis
Direct-to-supermarket channels handle hyperscale demand from Lagos and Abuja modern trade buyers enforcing NAFDAC license verification and dedicated refrigerator space allocation. Geographic supply concentration centers on Nigeria's South-West corridor, with secondary production nodes in Kaduna and Kano serving northern ambient-distribution markets. Raw material dependencies include imported milk powder, probiotic culture strains, and aseptic packaging substrates from European and Asian suppliers. Supply chain risk hinges on single-source vulnerability for foreign exchange-denominated dairy inputs during currency stress periods. Distribution runs through consolidated retailer networks in open-market southern settlements and Tetra Pak-enabled distributor radii in cold chain-limited northern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAFDAC's tightening fortification mandates and cold chain compliance requirements are accelerating formalization pressure that will consolidate manufacturing capacity toward capitalized incumbents with dedicated quality infrastructure.
For Market Incumbents: Hedge against imported input volatility through backward integration into northern Nigerian milk collection networks and captive probiotic strain cultivation capabilities. Lock in pharmacy-channel refrigerator space allocations ahead of supermarket buyer consolidation toward certified functional brands. Defensive capacity investment in Kaduna production hubs captures Tetra Pak-enabled northern distribution economics while insulating margin structure from diesel-powered cold transport costs. For New Entrants and Emerging Players: E-commerce subscription models targeting time-constrained professionals in Lekki and Wuse districts offer white-space penetration with minimal cold chain infrastructure requirements. South-East corridor underpenetration in Anambra and Enugu states presents first-mover advantage for chilled distribution investment ahead of modern trade maturation. Pharmacy-adjacent placement alongside OTC medications captures health-seeking consumer premiums outside conventional grocery occasions. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing Tetra Pak technology licensing and established northern distributor relationships given ambient-stable format expansion. Long-term viability over a multi-year horizon favors processors with demonstrated NAFDAC compliance track records and consolidated traditional trade networks. Monitor NAFDAC guidance publication timelines on sugar content thresholds as inflection indicator for SKU rationalization winners and license continuity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Local Milk Supply | Captive sourcing from northern Nigerian smallholder networks insulates margin against naira depreciation on imported powder. |
| Tetra Pak Technology Licensing | Aseptic carton capabilities unlock ambient distribution economics across cold chain-limited northern states. |
| Pharmacy Channel Expansion | Digestive health claims positioning commands premium slotting fees alongside OTC medications in urban centers. |
| Sugar Content Proactive Reformulation | Preemptive NAFDAC compliance preserves license continuity and front-of-pack labeling advantages ahead of regulatory guidance. |
| South-East Distribution Investment | Anambra and Enugu modern trade growth without matching category development offers first-mover shelf capture. |
Research Approach
Independent corroboration across NAFDAC regulatory filings, SON certification databases, and Tetra Pak equipment deployment records underwrites the qualitative findings on manufacturing capacity distribution. Primary interviews with dairy processing plant managers, modern trade category buyers, cold chain logistics operators, and pharmacy procurement heads combined with secondary validation from customs import records, retail audit data, and state environmental health agency enforcement reports. Bottom-up triangulation across installed production capacity and top-down demand estimation from household consumption clusters anchored volume and value outputs.
Comparable-period anchoring to historical NAFDAC licensing waves and cold chain infrastructure investment cycles established the forecast window's baseline trajectory. Segmentation dimensions modeled include product type, packaging format, distribution channel, and consumer age group across the projection horizon. CAGRs derived from trend extrapolation of urban household consumption cluster expansion, modern trade penetration rates, and ambient-stable format adoption curves in northern states. Industry-specific forecast inputs incorporated probiotic strain approval timelines and school feeding program procurement specifications.
The model holds under stable NAFDAC regulatory enforcement and naira exchange rate assumptions; deviation in foreign exchange volatility or accelerated sugar content mandate implementation would shift capacity investment timing and SKU rationalization patterns. Practitioners should monitor SON certification backlog durations and northern raw milk supply seasonality for early signals of supply chain constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Organic Milk Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Cream Powder Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Blue Cheese Market
Dairy Products
Butter Concentrate Market
Dairy Products
India Milk Protein Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Dairy Carton Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Russia Whey Protein Market
Dairy Products
US Cheese Market
Dairy Products
Global Milk Protein Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Low Cholesterol Cheese Market