
 Plain Yogurt Market | 2026-2036
Plain Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Plain Yogurt Market Insights
Subscription-based recurring delivery of plain yogurt is restructuring how manufacturers secure household pantry share. Danone SA leverages its direct-to-consumer platform in North America to lock in monthly replenishment cycles. Chobani LLC anchors its market presence through extensive retail distribution and specialty Greek yogurt positioning. Arla Foods amba sustains competitive pressure with cooperative-backed milk supply contracts that stabilize input costs.
Plain yogurt is a fermented dairy product containing live bacterial cultures, typically Lactobacillus bulgaricus and Streptococcus thermophilus, with milk solids content ranging from eight to sixteen percent depending on style. It serves as a functional food ingredient and standalone protein source across retail and foodservice channels. Greek and skyr formats command premium shelf positioning due to elevated protein density and straining process intensity. Online retailers represent the fastest-growing distribution channel as fulfillment infrastructure penetrates secondary cities. Plastic cup packaging still dominates volume but faces margin compression from sustainability-driven shifts toward recyclable alternatives.
The EU Farm to Fork Strategy and EFSA nutrition labeling requirements are tightening additive disclosure and protein content verification across member states. The FDA and USDA maintain parallel oversight of Grade A milk sourcing and live culture viability claims in the United States. Stakeholders must monitor evolving packaging material regulations and fermentation process certification standards to preserve market access across jurisdictions.
Market Dynamics
The EU Farm to Fork Strategy is compressing formulation flexibility while protein density claims face intensified EFSA verification, forcing manufacturers to reengineer recipes ahead of compliance deadlines without sacrificing the taste profiles that secure retail shelf placement.
Growth Catalysts
- EFSA protein verification standards:Stricter labeling requirements are elevating consumer trust in verified Greek and skyr varieties, accelerating premium tier uptake across German and French households.
- Live culture viability protocols:Enhanced fermentation process documentation is differentiating authentic artisanal producers from commoditized imports in Brittany cooperative supply chains.
- Recyclable packaging mandates:Sustainability-driven material shifts are opening private-label partnerships with Parisian retail chains seeking ESG-aligned dairy procurement.
Market Restraints
- Milk solids input volatility:Fluctuating dairy commodity prices strain margin stability for manufacturers dependent on cooperative-backed supply contracts.
- Plastic packaging dependency:Dominance of cup-based formats creates stranded asset risk as EU single-use directives accelerate material transition timelines.
- Strained skyr production capacity:Limited Icelandic-style fermentation infrastructure concentrates supply among specialized facilities, constraining volume scaling.
Strategic Opportunities
- Direct-to-consumer subscription platforms:Monthly replenishment cycles are capturing household pantry share previously held by impulse retail purchases.
- Foodservice ingredient positioning:Plain yogurt's functional versatility as a marinade base and sauce foundation is penetrating commercial kitchen procurement specifications.
- EU Green Deal packaging incentives:Biodegradable material innovation subsidies are reducing R&D barriers for sustainable format development.
Industry Challenges
- Fermentation specialist talent scarcity:Shortage of technicians trained in thermophilic culture management complicates artisanal scale-up efforts.
- Cross-jurisdiction certification complexity:Divergent FDA and EFSA live culture viability documentation requirements fragment quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plain Yogurt Market |
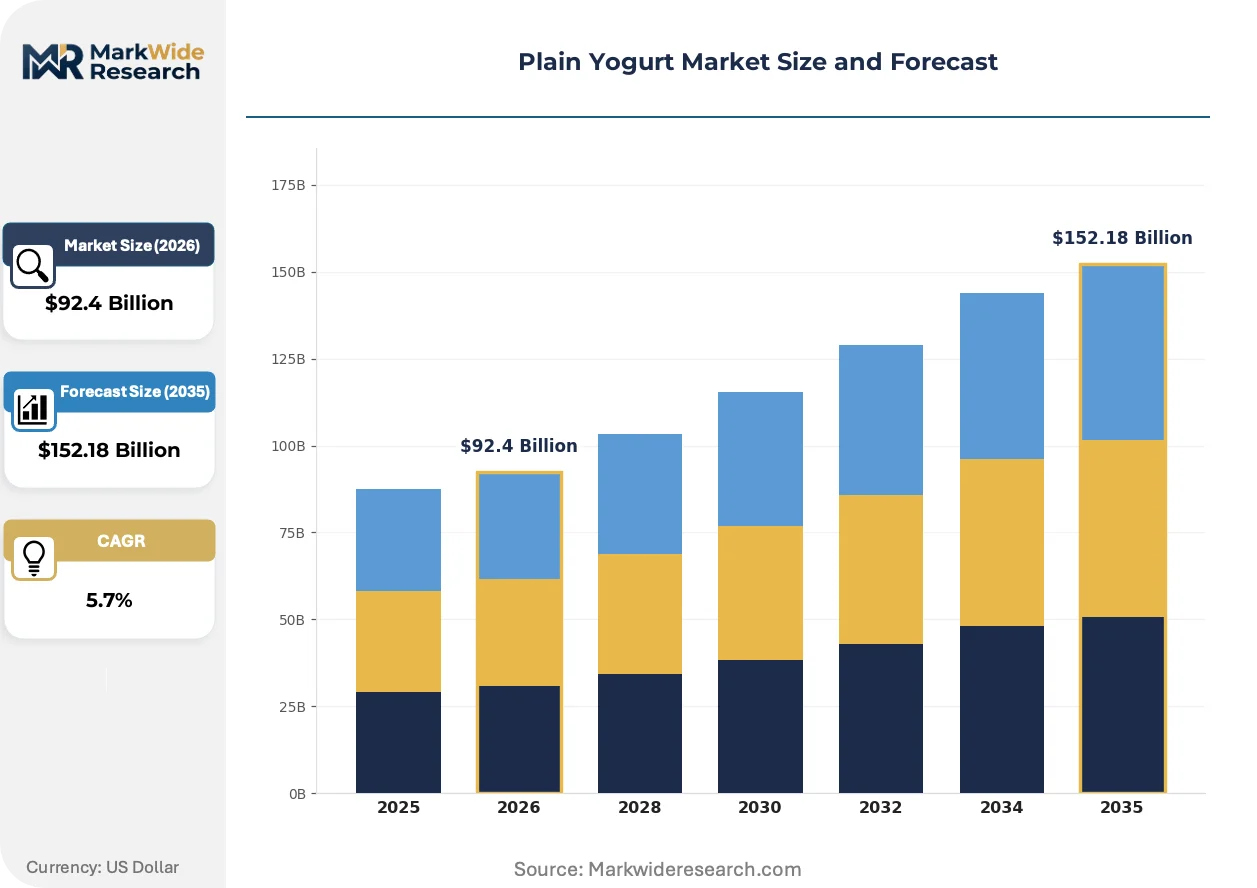
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $152.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Fat, Whole Milk, Greek, Skyr Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores Packaging Type: Plastic Cup, Glass Jar, Tetra Pack, Pouch End User: Households, Restaurants, Cafes, Food Processing Companies |
| Companies Covered | Chobani LLC, Danone SA, Arla Foods amba, Nestle SA, FAGE International SA, Lactalis American Group Inc., General Mills Inc., FrieslandCampina, China Mengniu Dairy Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plain Yogurt Market Trends and Innovations
Refrigerated last-mile fulfillment infrastructure is compressing delivery windows for perishable dairy, while formulation science advances enable cleaner labels without sacrificing shelf stability. These forces are simultaneously reshaping competitive positioning and consumer access patterns.
Precision fermentation technology is decentralizing protein production economics. Alternative dairy startups in Denmark and the Netherlands are adopting microbial culture platforms to replicate casein structures without bovine supply chains. Early foodservice adopters in Copenhagen and Amsterdam are integrating these ingredients into hybrid yogurt formulations, compressing reliance on traditional dairy cooperatives.
EFSA's evolving nutrition labeling framework is tightening additive disclosure thresholds across member states. Manufacturers reformulating for clean-label compliance face compressed R&D timelines as Brittany artisanal cooperatives set de facto standards for Parisian retail buyers. French private-label distributors are demanding batch-level traceability documentation that exceeds baseline EU requirements.
Subscription-based replenishment models are displacing supermarket impulse purchasing among health-conscious urban households. Direct-to-consumer platforms in Germany and France are capturing pantry share through algorithmic flavor rotation and flexible delivery windows. This behavioral pivot concentrates lifetime value among digitally engaged segments while eroding traditional retail foot traffic in metropolitan markets.
Plain Yogurt Market Segmentation
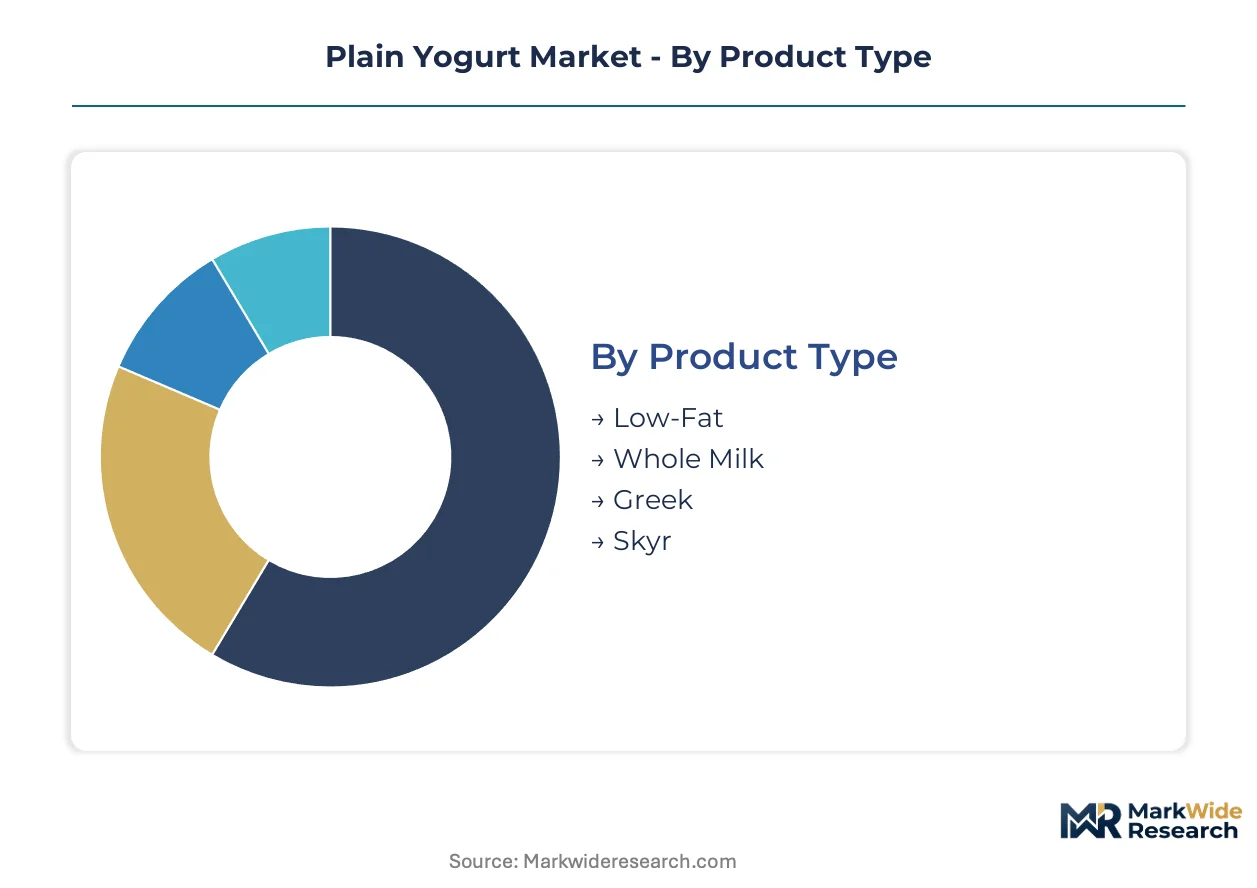
Plain yogurt segmentation reveals divergent margin structures across protein density tiers and fulfillment models. Manufacturers optimize portfolio mix between commoditized volume formats and premium strained varieties. Channel strategy increasingly separates pantry-stock subscription demand from impulse-driven retail pickup.
Product Type:
Volume leadership sits with traditional formulations, while premium density drives value expansion.
- Low-Fat:Standardized milk solids content of eight to ten percent with reduced butterfat profiles. German health-conscious households favor this format for daily consumption, though EFSA protein verification requirements are compressing margin flexibility on baseline claims.
- Greek:Strained varieties concentrate protein to fifteen to twenty percent through whey separation processes. Demand concentrates in French metropolitan markets where Parisian retail chains prize verified density credentials for private-label positioning.
- Whole Milk:Full-fat formulations retain natural butterfat for flavor intensity and satiety signaling. Brittany artisanal cooperatives supply premium iterations to specialty buyers seeking clean-label credentials.
- Skyr:Icelandic-style fermentation achieves exceptional protein density through extended culturing and mechanical separation. Limited fermentation infrastructure constrains supply scaling despite premium pricing power in Nordic-influenced markets.
Today's leader: Greek. Tomorrow's challenger: Skyr.
Distribution Channel:
Physical retail still moves volume, but digital penetration is restructuring household replenishment patterns.
- Supermarkets:Dominant shelf space allocation with refrigerated section placement driving impulse selection. French and German chains are consolidating SKU counts toward verified premium tiers.
- Online Retailers:Subscription platforms capture recurring pantry share through algorithmic replenishment timing. Cold-chain fulfillment infrastructure expansion into secondary cities is accelerating this channel's expansion trajectory.
- Health Food Stores:Curated assortments emphasizing organic certification and live culture viability documentation. Parisian independent retailers set de facto standards for artisanal cooperative supply relationships.
- Convenience Stores:Single-serve formats for immediate consumption occasions. Limited refrigeration capacity restricts assortment depth to mainstream low-fat and standard whole milk varieties.
Supermarkets anchor current volume. Online platforms are gaining share fastest among urban households.
Packaging Type:
Sustainability mandates are forcing material transition timelines across format categories.
- Plastic Cup:Polypropylene and polystyrene formats dominate unit economics but face stranded asset risk from EU single-use directives. German retailers are demanding recycled content minimums that compress margin structures.
- Glass Jar:Premium positioning through reusability signaling and aesthetic differentiation. Brittany cooperatives favor this format for Parisian private-label lines targeting ESG-aligned procurement specifications.
- Tetra Pack:Aseptic carton technology enables ambient distribution with extended shelf stability. French food processing companies specify this format for ingredient-scale procurement.
- Pouch:Flexible packaging reduces material intensity and logistics cube for direct-to-consumer shipment. Emerging adoption in subscription platform fulfillment for portion-controlled consumption.
Plastic cups hold volume dominance. Glass jars command premium positioning.
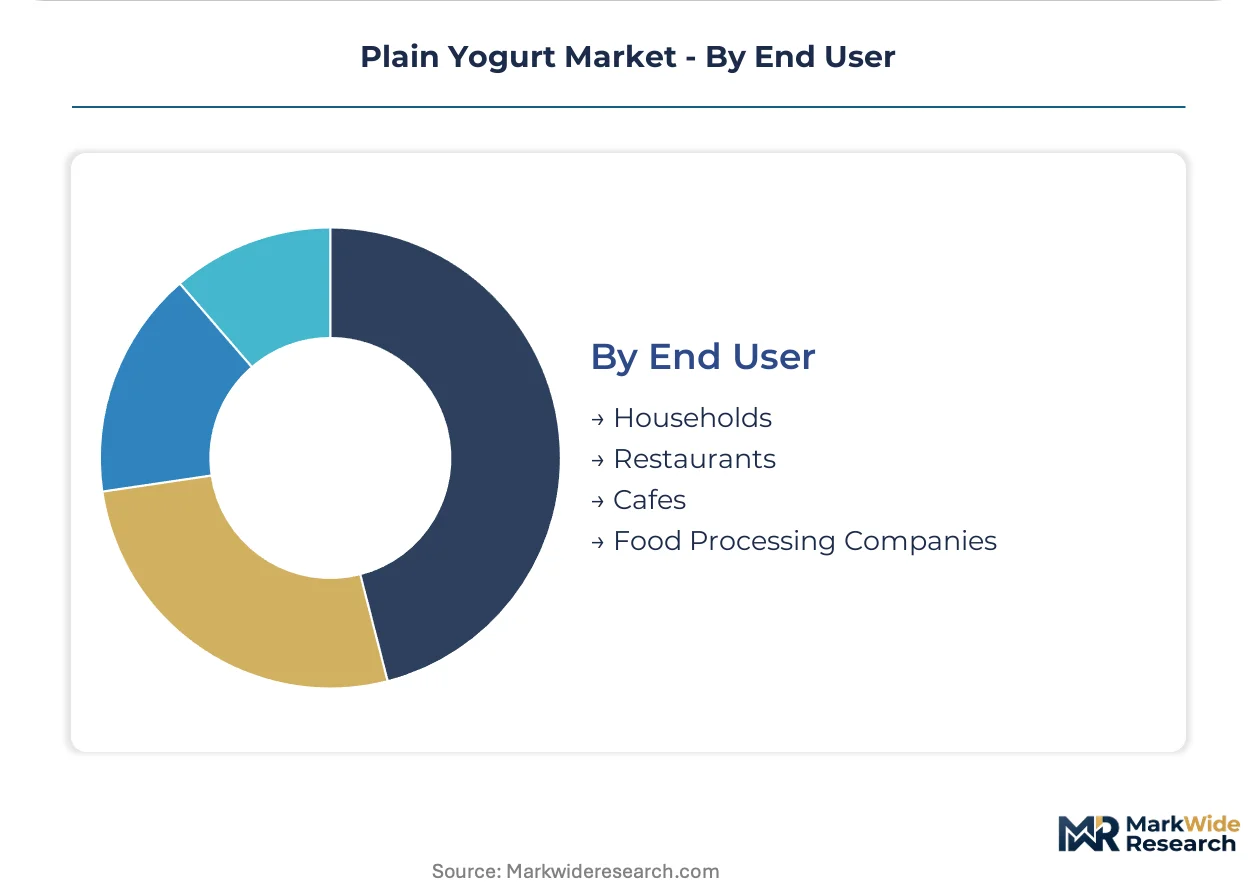
End User:
Household consumption patterns diverge sharply from commercial ingredient demand specifications.
- Households:Individual and family-unit consumption across breakfast, snacking, and recipe applications. German and French urban segments are shifting toward subscription replenishment away from supermarket impulse purchasing.
- Food Processing Companies:Industrial-scale procurement for sauce bases, marinades, and baked good formulations. EFSA additive disclosure requirements are tightening batch-level traceability documentation demands.
- Restaurants:Foodservice specifications prioritize consistency and functional performance in hot and cold applications. Copenhagen and Amsterdam operators are piloting precision fermentation hybrid formulations.
- Cafes:Smoothie and bowl assembly applications emphasizing visual appeal and protein density signaling. Limited volume per outlet constrains direct manufacturer relationships.
Households generate current volume concentration. Food processing companies present structural expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France diverge in plain yogurt procurement patterns despite sharing EU regulatory frameworks. German households prioritize subscription-based replenishment through digital platforms, while French demand concentrates around artisanal cooperative supply chains serving metropolitan retail.
Germany
Urban households in Berlin and Munich are shifting toward algorithmic subscription models for Greek and low-fat varieties. EFSA protein verification standards are compressing formulation flexibility for domestic manufacturers. Bavaria's dairy processing clusters around Munich supply verified premium tiers to pan-European retail chains.
France
Parisian retail buyers prize Brittany-sourced artisanal skyr and whole milk formulations for private-label positioning. The EU Farm to Fork Strategy is tightening additive disclosure thresholds ahead of baseline EU requirements. Brittany cooperatives near Rennes and Quimper dominate premium glass-jar supply to Île-de-France distribution networks.
United States
Direct-to-consumer platforms capture recurring pantry share in metropolitan corridors along the Northeast and West Coast. FDA Grade A milk sourcing protocols and USDA live culture viability claims create dual-jurisdiction compliance burdens. Upstate New York fermentation facilities supply Chobani LLC's retail and subscription distribution architecture.
China
Tier-one cities including Shanghai and Beijing are expanding cold-chain infrastructure for perishable dairy fulfillment. SAMR dairy labeling standards and GB food safety codes govern import and domestic production specifications. Mengniu Dairy's processing footprint in Inner Mongolia anchors supply to eastern coastal demand centers.
Netherlands
Amsterdam foodservice operators are piloting precision fermentation hybrid formulations alongside conventional dairy procurement. EU Green Deal packaging incentives are accelerating biodegradable material R&D for pouch and carton formats. FrieslandCampina's cooperative structure in the northern provinces stabilizes milk solids input for strained yogurt production.
Plain Yogurt Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium strained varieties consolidating around vertically integrated dairy cooperatives while private-label volume flows through outsourced processing networks. Three archetypes dominate: cooperative-backed heritage players with captive milk supply, direct-to-consumer platform operators leveraging subscription economics, and multinational diversified food corporations optimizing cross-category procurement leverage. Competitive moves center on cold-chain fulfillment infrastructure expansion and fermentation specialist talent acquisition.
Within the cooperative archetype, Arla Foods amba and FrieslandCampina exemplify farmer-owned structures that stabilize input costs through backward integration into milk supply. Danone SA occupies a position bridging branded premium positioning with direct-to-consumer platform development in North American markets. Chobani LLC anchors the specialty Greek yogurt tier through retail distribution density and category-defining product format innovation.
| Leading Market Players |
|---|
| Chobani LLC |
| Danone SA |
| Arla Foods amba |
| Nestle SA |
| FAGE International SA |
| Lactalis American Group Inc. |
| General Mills Inc. |
| FrieslandCampina |
| China Mengniu Dairy Company Limited |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation technology is compressing traditional dairy economics while concentrating supply leverage among early adopters in Denmark and the Netherlands, simultaneously reshaping input cost structures and procurement patterns for conventional manufacturers.
Pricing Analysis
Capacity additions in Iceland and specialized facilities across the Nordic region are reshaping price floors for skyr varieties, though limited fermentation infrastructure maintains premium tier elevation. Three-tier pricing structure across premium, standard, and economy levels separates verified Greek and skyr densities from commoditized low-fat formats, with EFSA protein verification serving as the primary quality-grade differentiator. Cost compression in standard low-fat tiers is intensifying because German retailers are demanding recycled content minimums that squeeze margin structures. Household subscription segments show least price sensitivity due to algorithmic replenishment lock-in, while food processing companies exhibit highest sensitivity to batch-level traceability premiums.
Supply Chain Analysis
Milk solids supply rests on cooperative structures in Germany, France, and the Netherlands that stabilize input costs through farmer-owned governance. Live thermophilic cultures, specialized straining equipment, and cold-chain logistics equipment constitute critical input dependencies. Single-source vulnerability concentrates in Icelandic skyr fermentation infrastructure, where limited facility count creates supply bottleneck risk. Distribution runs through Parisian retail chain procurement offices for premium artisanal tiers, while direct-to-consumer platforms bypass traditional wholesale layers for subscription household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA additive disclosure thresholds run stricter than FDA Grade A protocols, creating a regulatory arbitrage window for manufacturers with dual-certification capabilities to capture premium positioning in EU markets while maintaining US access.
For Market Incumbents: Extend fermentation specialist training programs to address talent scarcity constraining artisanal scale-up efforts. Secure backward integration into Brittany cooperative supply chains to defend premium glass-jar positioning against Parisian private-label consolidation. Channel control through direct-to-consumer platform investment offers margin protection against retail SKU rationalization.
For New Entrants and Emerging Players: Precision fermentation microbial culture platforms offer technology-first wedge into Copenhagen and Amsterdam foodservice procurement specifications for hybrid yogurt formulations. White-space targets concentrate in biodegradable pouch packaging for subscription fulfillment and precision fermentation ingredient supply to industrial food processors. Go-to-market through EU Green Deal packaging innovation subsidies reduces R&D capital barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract manufacturers lacking verified premium tier credentials or cold-chain fulfillment infrastructure. Long-term viability over a multi-year horizon favors cooperative-backed heritage players with captive milk supply and established Parisian retail relationships. The signal to watch is EFSA batch-level traceability documentation requirements exceeding baseline EU mandates, which would accelerate consolidation toward compliant integrated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Specialist Talent Acquisition | Addresses scarcity constraining artisanal scale-up in Brittany and Bavaria processing clusters. |
| Direct-to-Consumer Platform Launch | Captures recurring pantry share through algorithmic replenishment timing in German urban households. |
| Biodegradable Packaging R&D Investment | Aligns with EU Green Deal subsidies while reducing stranded asset risk from single-use directives. |
| EFSA Dual-Certification Investment | Enables premium private-label positioning for Parisian retail chains seeking verified density claims. |
| Precision Fermentation Partnership | Integrates alternative protein sources into hybrid formulations for Copenhagen foodservice pilots. |
Research Methodology
Multiple input streams — executive interviews with dairy cooperative managers, fermentation process engineers, and Parisian retail category buyers; regulatory filings with EFSA and FDA; and trade data from EU dairy processing associations — were reconciled through bottom-up facility capacity modeling and top-down consumption pattern validation. Secondary sources included EFSA nutrition labeling guidance documents, EU Farm to Fork Strategy implementation reports, and cold-chain logistics operator disclosures.
Historical volume trajectories were cross-referenced against panel input from subscription platform operators and foodservice procurement directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include protein density tier, distribution channel architecture, packaging material type, and end-user application. CAGRs were derived from trend extrapolation adjusted for regulatory compliance timeline impacts and infrastructure build-out rates in precision fermentation and refrigerated last-mile fulfillment.
The model holds under stable EFSA enforcement timelines and cooperative milk supply contract continuity; deviation in Icelandic fermentation facility expansion or EU single-use directive acceleration would shift volume and value trajectories. A small set of named triggers — EFSA protein verification standard tightening, precision fermentation cost parity achievement, and major retailer ESG procurement mandate adoption — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Drinkable Yogurt Market
Dairy Products
Germany Dairy Market
Dairy Products
Condensed Milk Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Camel Dairy Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Yogurt Drink Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
North America Fluid Milk Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Low Fat Cheese Market