
 Autonomous Commercial Vehicles Market | 2026-2036
Autonomous Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Commercial Vehicles Market Insights
Asset-light fleet leasing and pay-per-mile financing is narrowing the capital barrier for mid-size logistics operators to deploy autonomous trucks. Daimler Truck AG leverages its integrated powertrain and autonomous software stack to sustain technology leadership in heavy-duty segments. Waymo anchors its position through billions of mapped freight corridors and redundant sensor architectures. PACCAR Inc competes through manufacturing scale and dealer network density across North American commercial routes.
Autonomous commercial vehicles integrate LiDAR, radar, and computer vision systems with drive-by-wire chassis to execute navigation, obstacle detection, and lane-keeping without human intervention, operating primarily to reduce per-mile logistics costs and extend freight hauling windows beyond human driver hour limits. Trucks dominate current deployment volumes due to predictable highway routes and concentrated shipper demand, while sensor fusion architectures capture expanding margin pools as redundancy requirements tighten. Delivery vehicles represent the fastest-growing vehicle type as last-mile operators pilot small autonomous vans for urban parcel distribution.
The US NHTSA and FMCSA shape product standards through testing protocols and operational permitting frameworks, while the EU AI Act and type-approval regulations under the EU Green Deal constrain algorithmic transparency and emissions profiles for vehicles entering European roads. Stakeholders must monitor how California DMV permit classifications and Arizona DOT autonomous vehicle statutes create divergent compliance pathways that fragment fleet deployment strategies across state borders. Fleet operators and technology providers should track which regulatory jurisdiction offers the clearest liability framework before committing capital to scaled commercial launches.
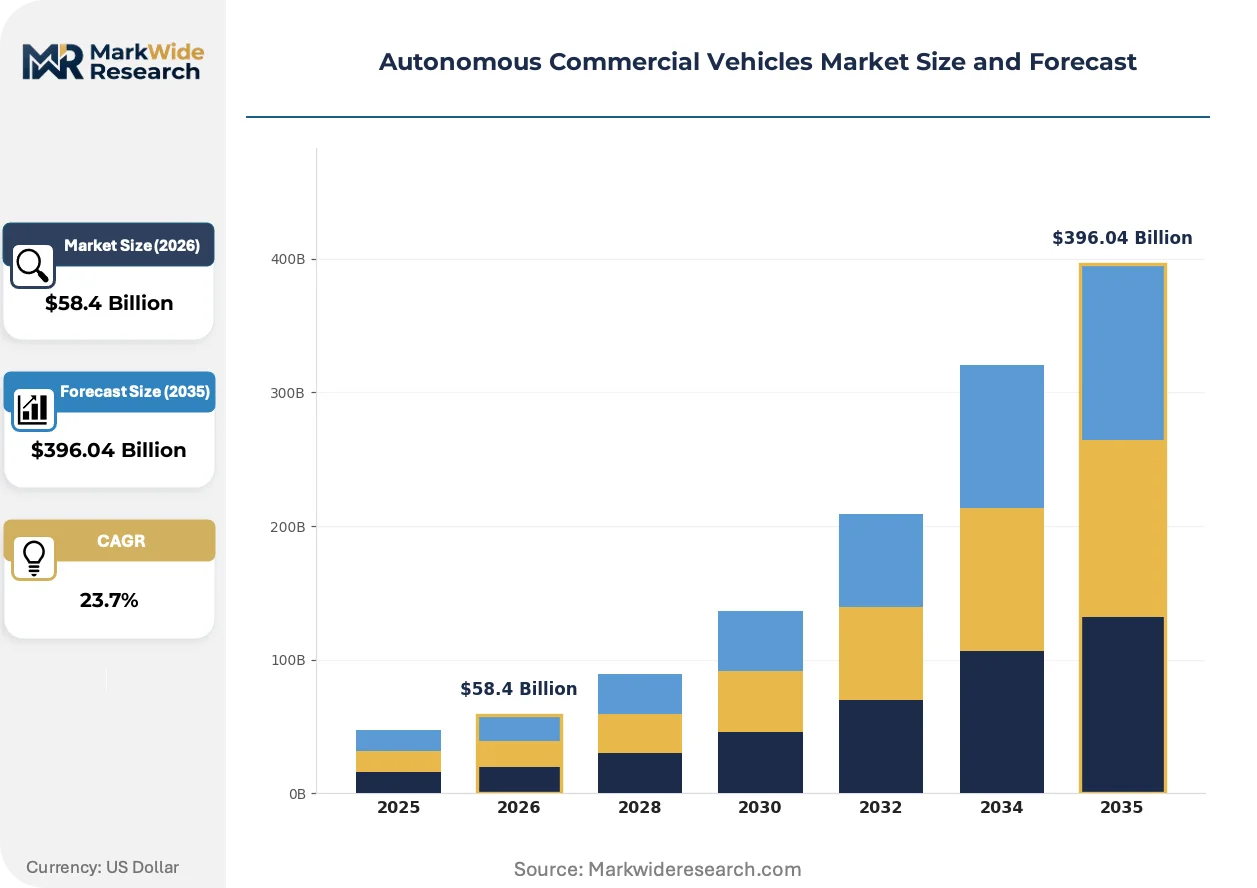
Market Dynamics
Sensor fusion architectures and redundant compute systems are compressing development timelines for autonomous commercial vehicle deployment, while fragmented state-level permitting frameworks in the United States force fleet operators to navigate divergent compliance pathways across freight corridors.
Growth Catalysts
- FMCSA Hours-of-Service Rule Flexibility:The US Federal Motor Carrier Safety Administration's evolving guidance on autonomous truck operations extends allowable freight hauling windows beyond human driver limits, unlocking continuous route economics for long-haul corridors.
- LiDAR Cost Curves:Solid-state LiDAR manufacturing scale is collapsing unit costs for perception systems, enabling mid-size logistics operators to spec autonomous-capable tractors without fleet-wide capital commitment.
- Freight Corridor Clustering:Dense testing infrastructure across Texas, Arizona, and California creates network effects where mapped highway segments and maintenance facilities concentrate, reducing per-mile validation costs for new entrants.
Market Restraints
- LiDAR Supply Concentration:Production of 1550nm wavelength LiDAR units concentrates among a limited set of specialized photonics manufacturers, creating single-source vulnerability for redundant perception stacks.
- California DMV Permit Fragmentation:The California Department of Motor Vehicles operates a multi-tier testing and deployment permit system that imposes distinct insurance, reporting, and safety driver requirements compared to neighboring Arizona DOT statutes.
- Edge Case Data Scarcity:Rare weather events and anomalous road debris scenarios remain underrepresented in training datasets, constraining neural network generalization for commercial liability acceptance.
Strategic Opportunities
- EU AI Act Algorithmic Transparency Pathways:Early compliance with European Union artificial intelligence disclosure requirements positions autonomous truck developers for preferential type-approval under EU Green Deal emissions integration frameworks.
- Last-Mile Delivery Van Convergence:Urban parcel distribution networks present unserved demand for small autonomous vehicles operating below 25 mph, with lower safety-critical thresholds than interstate trucking applications.
- Teleoperations Hub Networks:Remote human supervision centers enable graduated autonomy deployment where vehicles handle highway segments independently while teleoperators manage complex urban ingress and egress maneuvers.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 automotive safety certification expertise remains concentrated among a limited pool of specialists, extending system validation timelines for autonomous chassis integration programs.
- Retrofit Integration Complexity:Drive-by-wire actuator installation on existing Class 8 truck platforms requires extensive electrical architecture redesign, complicating fleet upgrade paths for asset-heavy operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Commercial Vehicles Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $396.04 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Buses, Vans, Delivery Vehicles Technology: LiDAR, Computer Vision, Radar, Sensor Fusion End User: Logistics, Public Transport, Retail, Government Deployment Model: On-Premises, Cloud-Based, Hybrid, Fleet Managed |
| Companies Covered | Volvo Group, Daimler Truck AG, PACCAR Inc, Hyundai Motor Company, IVECO, Einride AB, Waymo, Aurora Innovation, Torc Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Commercial Vehicles Market Trends and Innovations
Software-defined vehicle architectures are decoupling hardware refresh cycles from capability upgrades, allowing fleet operators to extend tractor asset life while receiving over-the-air perception and path-planning improvements.
Camera-first perception stacks augmented by radar backup are rendering obsolete early-generation LiDAR-dominant sensor configurations that carried excessive unit cost and maintenance burden. Regional less-than-truckload carriers in the southwestern United States are adopting these streamlined architectures for hub-to-hub shuttle routes. The cost compression is enabling autonomous capability in mid-duty segments previously excluded by sensor economics.
The EU AI Act's risk classification framework for autonomous vehicle algorithms is mandating documented training data provenance and explainable decision trails for commercial deployment on European roads. Developers must now maintain algorithmic audit trails that trace specific navigation decisions to source sensor inputs and model versions. Heavy-duty truck programs targeting German freight corridors are restructuring data governance pipelines to satisfy these documentation requirements ahead of type-approval submissions.
Shippers are unbundling driver services from tractor asset contracts, contracting directly with autonomous fleet operators for dedicated lane capacity while retaining flexibility on equipment specification. This disintermediation of traditional driver-leasing arrangements concentrates procurement power among large retail and e-commerce distribution networks. The pattern is most visible in Texas-to-California produce and consumer goods corridors where volume commitments justify dedicated autonomous lane investment.
Autonomous Commercial Vehicles Market Segmentation
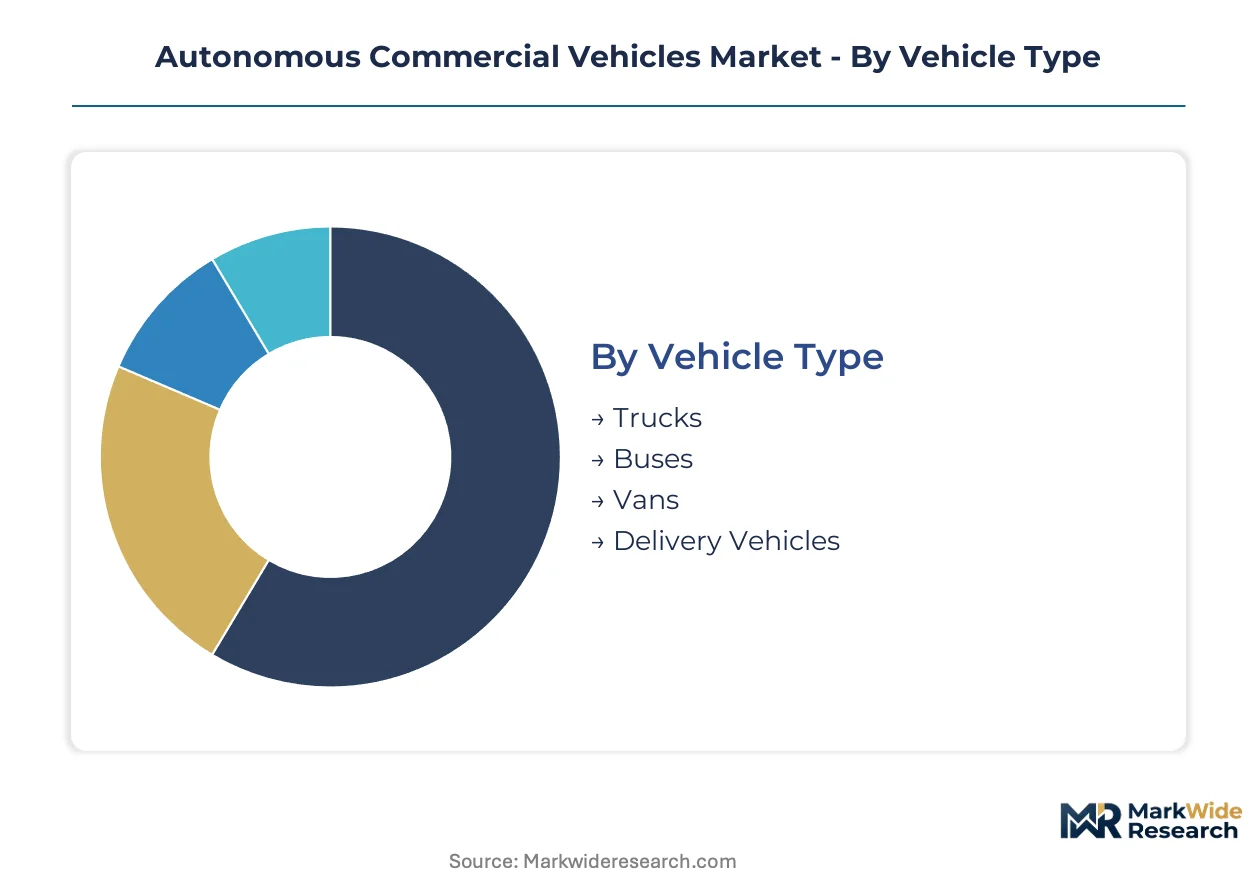
Segmentation in autonomous commercial vehicles exposes where capital commitments concentrate and where service intensity varies. Fleet operators structure procurement differently across vehicle classes and technology stacks, while deployment models determine recurring revenue attachment rates for platform providers.
Vehicle Type:
After-sales service intensity escalates with vehicle mass and operational duty cycle, creating divergent margin profiles across fleet categories.
- Trucks:Heavy-duty Class 8 tractors integrate redundant drive-by-wire actuators and thermal-managed compute enclosures for continuous highway operation. Demand clusters along Texas-Arizona-California freight corridors where hub-to-hub distances justify autonomous capital expenditure against driver wage arbitrage.
- Delivery Vehicles:Compact urban vans below 10,000 lbs GVW employ streamlined camera-radar perception stacks without LiDAR, enabling sub-$50,000 autonomy retrofit costs. Last-mile parcel networks in southwestern U.S. metropolitan zones pilot these for fixed-route distribution from micro-fulfillment centers.
- Vans:Mid-duty commercial vans serve regional less-than-truckload shuttles with intermediate sensor configurations balancing cost and highway capability.
- Buses:Fixed-route transit buses require specialized pedestrian-detection algorithms and ADA-compliant accessibility integration, extending validation timelines.
By volume, trucks lead. By growth pace, delivery vehicles are expanding most quickly.
Technology:
Cost tier stratification separates premium redundancy configurations from streamlined architectures targeting price-sensitive fleet segments.
- Sensor Fusion:Multi-modal perception combining LiDAR, radar, and camera inputs delivers the fault tolerance required for FMCSA-compliant driver-out operation on interstate corridors. Southwestern U.S. logistics fleets specify these systems for 24-hour continuous hauling where single-sensor failure risks catastrophic liability.
- Computer Vision:Deep-learning camera stacks with semantic segmentation achieve sufficient reliability for geofenced urban delivery below 25 mph, collapsing hardware costs for last-mile deployment.
- LiDAR:1550nm wavelength units provide long-range object detection but concentrate supply risk among limited photonics manufacturers.
- Radar:4D imaging radar supplements optical systems in adverse weather, gaining specification in safety-critical heavy-duty applications.
By installed base, sensor fusion dominates. By cost compression trajectory, computer vision is gaining share fastest.
End User:
Application-specific operational constraints shape technology packaging and service contract structures.
- Logistics:Asset-light fleet operators and dedicated contract carriers pursue autonomous tractors for long-haul density, unbundling driver services from equipment procurement.
- Retail:E-commerce distribution networks contract directly for lane capacity, concentrating procurement power among large shippers.
- Public Transport:Municipal transit authorities require extensive safety validation and union coordination, slowing deployment.
- Government:Defense and postal applications fund experimental programs with modified procurement risk tolerance.
By current deployment, logistics leads. By pilot expansion rate, retail is climbing the fastest.
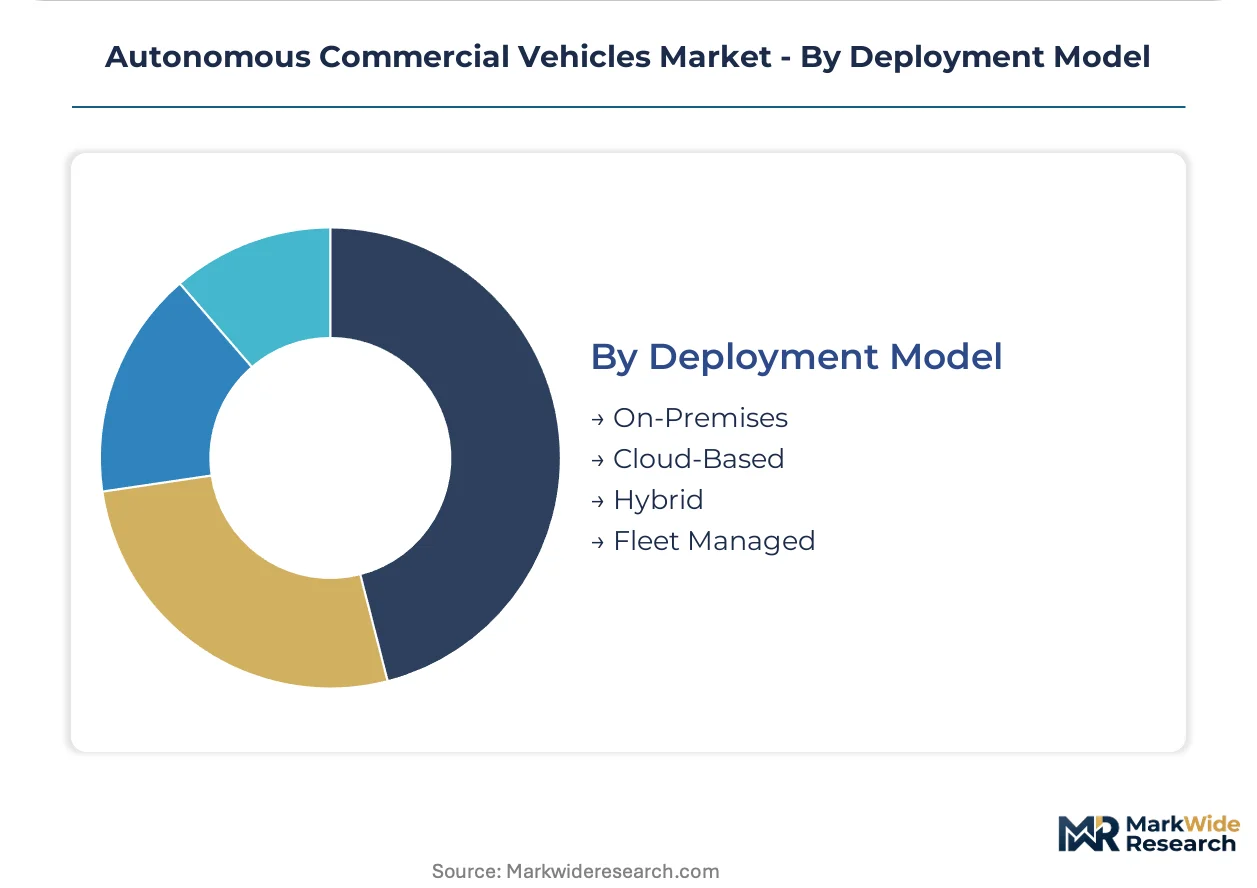
Deployment Model:
Customer type and fleet scale determine whether operators favor capital expenditure or operational expenditure structures.
- Fleet Managed:Turnkey autonomy-as-a-service bundles hardware, software, remote supervision, and maintenance under per-mile pricing, eliminating capital barriers for mid-size operators.
- Hybrid:Split architectures process perception locally while offloading HD map updates and fleet optimization to cloud infrastructure, balancing latency and compute cost.
- Cloud-Based:Fully centralized processing enables rapid algorithm updates but demands continuous connectivity, constraining rural route viability.
- On-Premises:Self-hosted compute and data governance satisfy EU AI Act documentation requirements for European market entry.
By contract value concentration, fleet managed leads. By regulatory positioning, hybrid shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level permitting frameworks are accelerating autonomous truck deployment across freight-intensive corridors. Germany's KBA type-approval pathways and the EU AI Act's algorithmic transparency mandates are shaping European market entry strategies. China's MIIT standards and dual carbon goals are steering domestic OEM development priorities.
United States
The FMCSA hours-of-service rule flexibility enables continuous 24-hour freight hauling on interstate corridors. The NHTSA safety framework mandates redundant perception system validation for driver-out operations. Texas-Arizona-California freight corridors concentrate testing infrastructure and state permit clustering.
Germany
Heavy-duty logistics demand and automotive OEM headquarters density drive autonomous truck R&D investment. The KBA and EU AI Act impose algorithmic audit trail requirements for commercial deployment. Baden-Württemberg's Stuttgart region hosts powertrain and autonomous software integration facilities.
China
Domestic freight volume and port automation demand accelerate commercial vehicle autonomy programs. MIIT standards and dual carbon goals mandate emissions-integrated autonomous system architectures. The Yangtze River Delta clusters LiDAR manufacturing and drive-by-wire chassis development.
Japan
Aging driver demographics and precision manufacturing standards create autonomous logistics adoption pressure. METI guidelines and JIS safety standards govern functional safety certification for commercial deployment. The Chubu region around Nagoya concentrates automotive supplier networks for sensor fusion integration.
Autonomous Commercial Vehicles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented technology tiers. Established truck manufacturers leverage integrated chassis and powertrain control to bundle autonomous capabilities. Technology providers and automotive suppliers represent distinct strategic archetypes. Competitive moves concentrate on strategic partnerships for sensor supply security and geographic expansion through regulatory jurisdiction targeting.
Among European-headquartered truck manufacturers, Volvo Group and Daimler Truck AG exemplify integrated powertrain-autonomy strategies. Waymo anchors the technology-provider archetype through mapped corridor density. Torc Robotics occupies a position within the autonomous software specialist tier.
| Leading Market Players |
|---|
| Volvo Group |
| Daimler Truck AG |
| PACCAR Inc |
| Hyundai Motor Company |
| IVECO |
| Einride AB |
| Waymo |
| Aurora Innovation |
| Torc Robotics |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta's LiDAR manufacturing concentration shapes downstream pricing power for autonomous commercial vehicle perception systems, with solid-state photonics capacity expansion in Chinese provinces directly compressing unit costs for North American fleet operators.
Pricing Analysis
Certification level (ISO 26262 functional safety grade) creates the primary spread between premium and standard autonomous system tiers. Three-tier pricing structure across premium, standard, and economy levels segments by redundancy configuration and after-sales service bundling. Pricing pressure stems from solid-state LiDAR cost compression as Chinese manufacturing scales. Mid-size logistics operators exhibit highest price sensitivity, while dedicated contract carriers prioritize fault tolerance over unit economics.
Supply Chain Analysis
1550nm wavelength LiDAR emitters and indium gallium arsenide photodetectors anchor upstream feedstock dependencies for long-range perception systems. China, Taiwan, and Germany concentrate specialized photonics manufacturing for autonomous vehicle sensors. Single-source vulnerability persists for solid-state scanning mechanisms. Distribution runs through Tier 1 automotive suppliers integrating perception stacks with drive-by-wire chassis platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
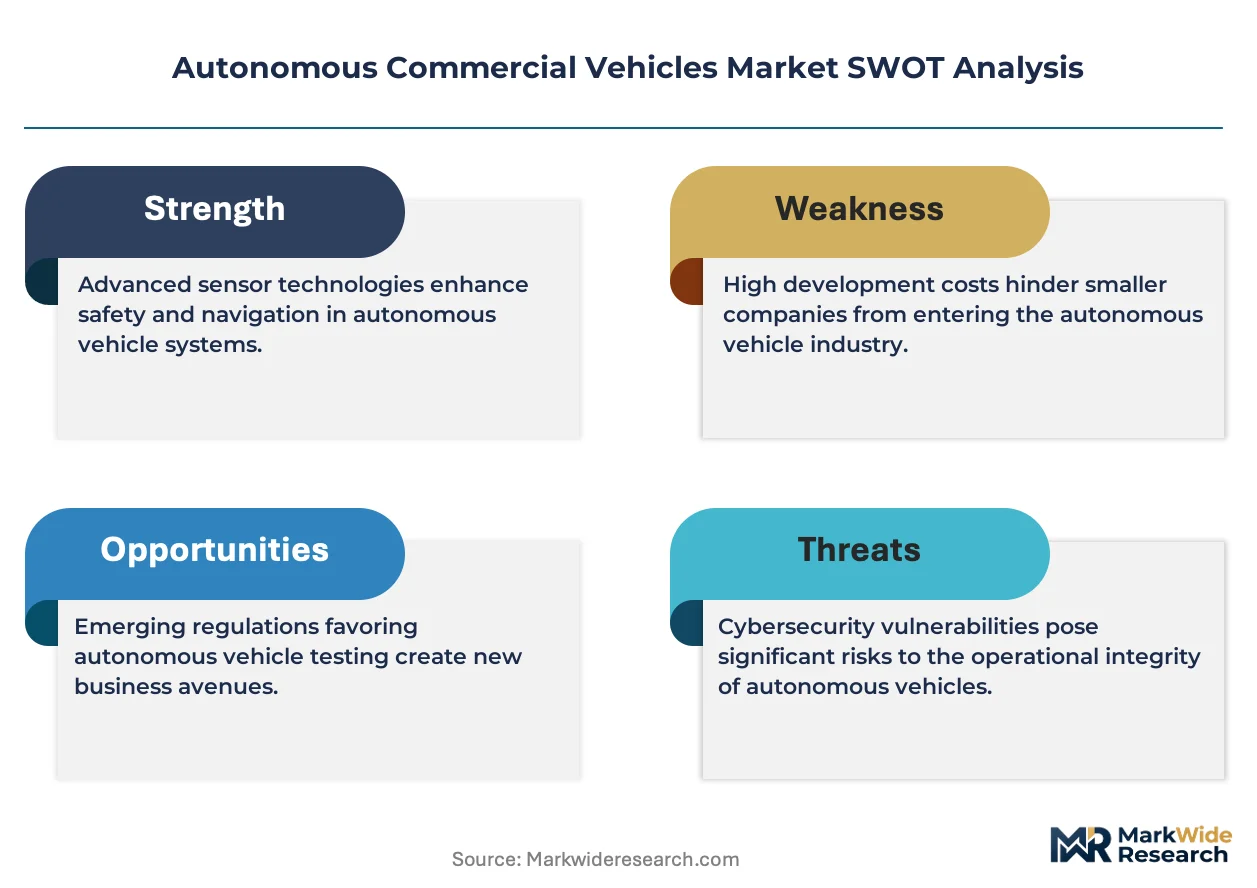
ISO 26262 functional safety engineer scarcity constrains validation timelines, with certification bottlenecks determining which autonomous truck developers achieve commercial deployment first.
For Market Incumbents: Insulate sensor supply security through captive partnerships with 1550nm LiDAR manufacturers or backward integration into solid-state photonics production. Secure Arizona DOT and Texas DOT permit holdings before California DMV regulatory fragmentation widens compliance cost gaps against emerging entrants. For New Entrants and Emerging Players: Pursue last-mile delivery van autonomy below 25 mph where safety-critical thresholds and hardware costs collapse entry barriers. Target southwestern U.S. metropolitan zones with fixed-route micro-fulfillment distribution contracts. Lead with camera-radar perception stacks priced under $50,000 per vehicle retrofit. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined vehicle platform providers with over-the-air capability delivery and fleet data network effects. Long-term viability hinges on regulatory jurisdiction clarity rather than pure technical performance. Monitor FMCSA driver-out operation guidance expansion as the inflection signal for scaled capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Supply Agreement | Secures 1550nm LiDAR allocation from Yangtze River Delta manufacturers for redundant perception stacks. |
| Regulatory Permit Portfolio | Builds multi-state testing authority across Texas, Arizona, and California freight corridors. |
| Teleoperations Hub Network | Enables graduated autonomy deployment with remote supervision for complex urban maneuvers. |
| Software-Defined Vehicle Platform | Decouples hardware refresh from capability upgrades via over-the-air perception improvements. |
| EU AI Act Compliance Pathway | Positions for preferential KBA type-approval through algorithmic audit trail documentation. |
Research Methodology
Cross-validation between fleet operator procurement interviews and NHTSA regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged autonomous truck platform engineers, logistics fleet procurement directors, FMCSA regulatory affairs specialists, and Tier 1 supplier integration managers. Secondary sources encompassed NHTSA safety framework documents, FMCSA hours-of-service guidance updates, California DMV permit classifications, and EU AI Act implementation texts. Bottom-up unit economics modeling triangulated against top-down market sizing across vehicle type and technology tier segments.
Calibration against historical deployment rates in Texas-Arizona-California corridors refined penetration assumptions across the projection horizon. Segmentation dimensions encompassed vehicle class, sensor architecture redundancy level, deployment model, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to pilot program expansion patterns. Industry-specific inputs included LiDAR cost curve trajectories and FMCSA driver-out operation timeline scenarios.
Macroeconomic conditions sit as an overlay; deviation in freight volume indices, semiconductor supply availability, or lithium-ion battery costs would shift the trajectory. Forecasts embed assumptions on regulatory clarity progression and sensor cost compression rates. Cross-checking against IHS Markit commercial vehicle production data and ACT Research freight demand indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Blind Spot Detection Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle ECU Market