
 Global Autonomous Trucks Market | 2026-2036
Global Autonomous Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autonomous Trucks Market Analysis
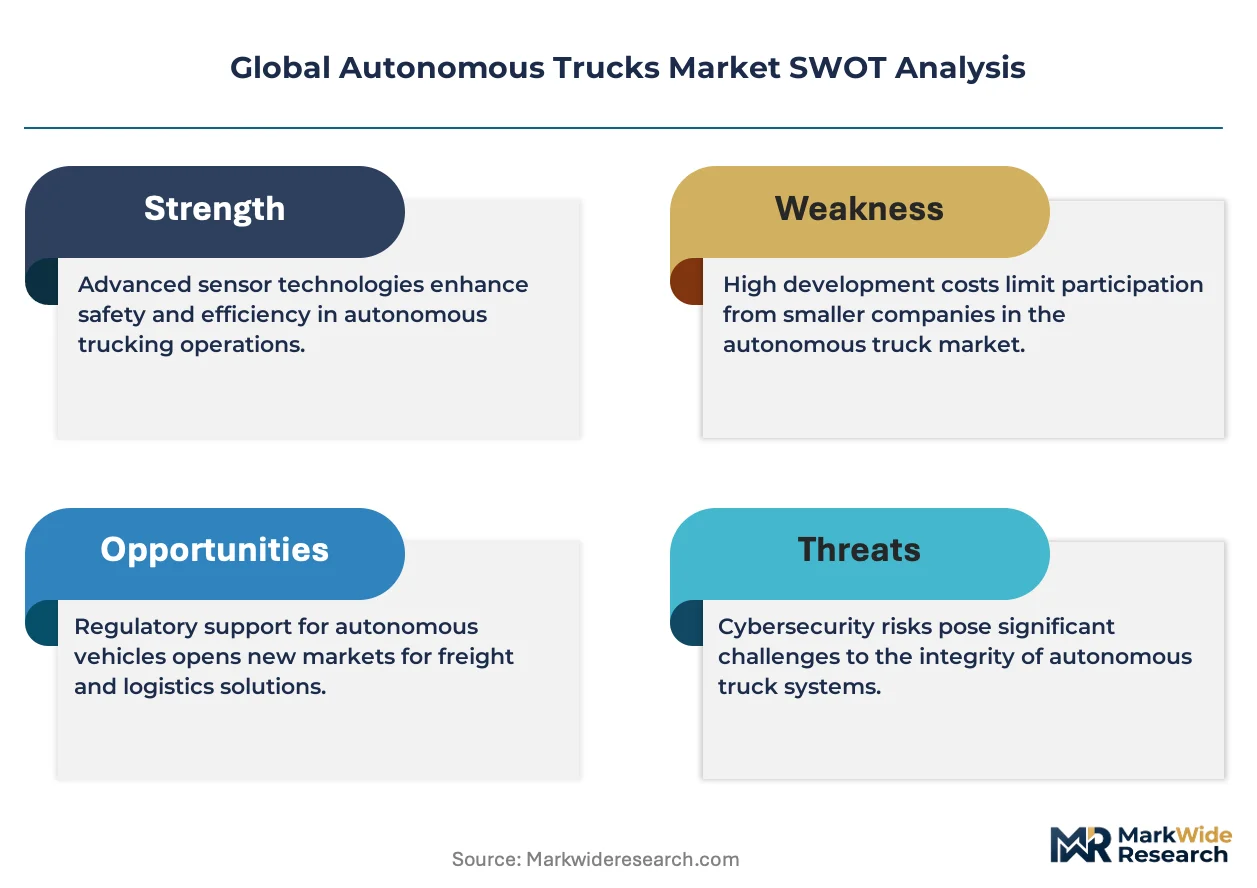
A chronic shortage of long-haul truck drivers is redrawing competitive priorities across the freight automation sector. Waymo leverages its Waymo Driver stack to anchor autonomous freight operations between Dallas and Houston. Daimler Truck sustains manufacturing scale through integrated powertrain and chassis platforms purpose-built for automation retrofit. Einride differentiates via pod-style electric autonomous units designed exclusively for closed-loop logistics corridors rather than open highway deployment.
Autonomous trucks are heavy-duty commercial vehicles equipped with LiDAR arrays, radar units, and computer vision systems capable of executing driving tasks without continuous human oversight across predefined routes. Long-haul trucks dominate current deployment because highway environments present lower perceptual complexity than urban last-mile settings. Sensor fusion architectures command premium engineering investment as fleets demand redundant perception layers capable of operating through degraded weather conditions where single-modality systems fail.
The US DOT, NHTSA, and FMCSA collectively govern vehicle safety standards, autonomous system certification, and commercial driver hour regulations that determine where and how autonomous trucks enter revenue service. EMA and EU AI Act requirements in Europe impose additional algorithmic transparency and liability frameworks on manufacturers seeking cross-border deployment. Stakeholders must track which regulatory jurisdiction certifies the driver-out operation first, as that precedent will cascade through insurance underwriting, shipper contracts, and fleet procurement criteria worldwide.
Market Dynamics
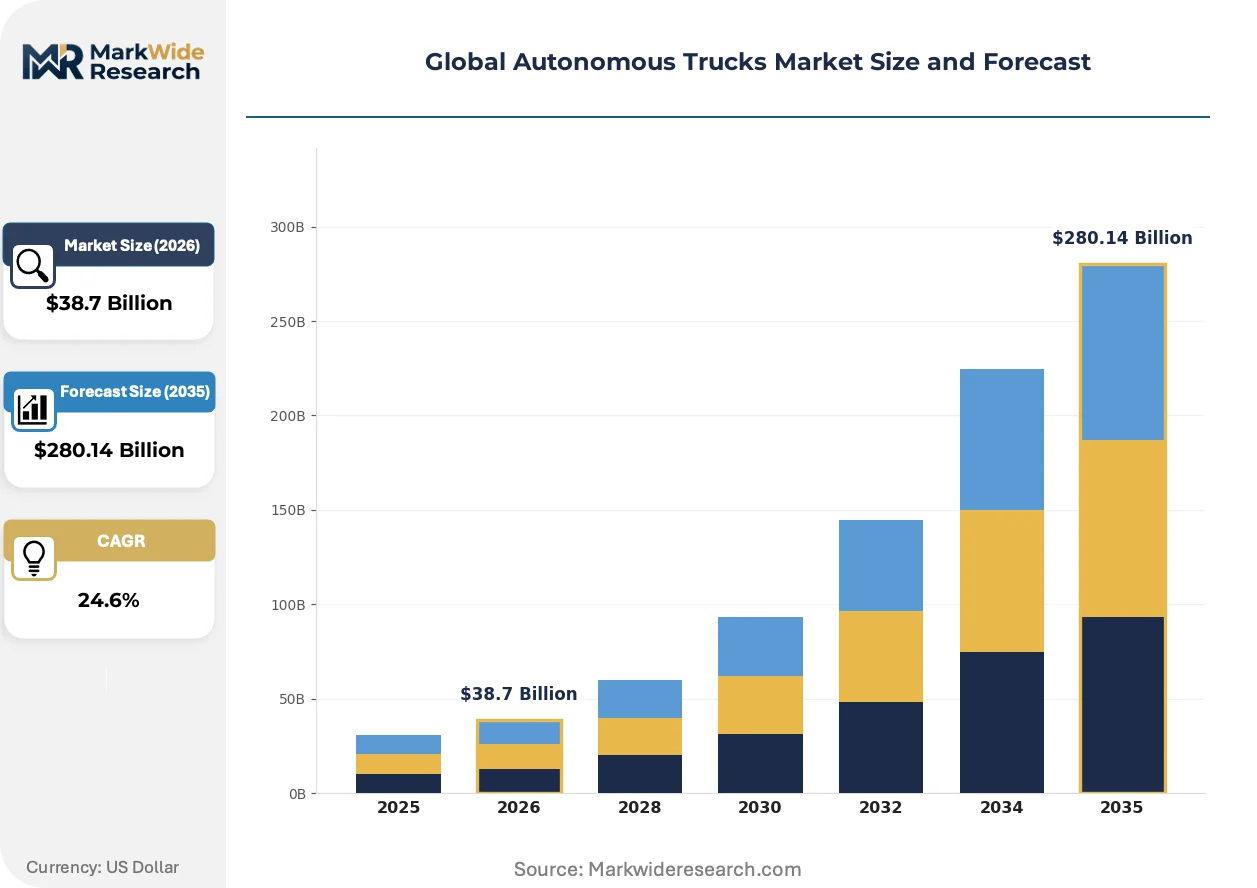
The chronic shortage of long-haul truck drivers is compressing freight carrier margins and accelerating capital deployment toward autonomous systems capable of operating without continuous human oversight.
Growth Catalysts
- FMCSA Hours-of-Service Reform:The US federal commercial driver hour limits constrain fleet utilization rates, pushing logistics operators toward autonomous alternatives that circumvent human fatigue constraints entirely.
- LiDAR Cost Collapse:Solid-state sensor manufacturing advances have reduced perception hardware expenses below the threshold where fleet-scale deployment becomes economically viable for mid-sized carriers.
- Arizona Regulatory Sandbox:The state's permissive autonomous vehicle testing framework has concentrated pilot programs along the I-10 corridor, creating infrastructure density that attracts complementary supplier investment.
Market Restraints
- LiDAR Supply Concentration:High-fidelity sensor production concentrates among a limited set of specialized manufacturers, exposing fleet procurement timelines to single-source vulnerability.
- EU AI Act Liability Framework:Algorithmic transparency requirements and strict liability provisions impose compliance costs that delay European deployment relative to North American timelines.
- Weather-Degraded Perception:Sensor fusion architectures still fail in heavy precipitation and dense fog, constraining operational domains to arid and semi-arid climate zones.
Strategic Opportunities
- Platooning Corridors:Coordinated multi-vehicle convoys on dedicated highway segments offer fuel efficiency gains and liability reduction through reduced human driver counts.
- India Industrial Zone Automation:Captive mining and port logistics applications present closed-loop deployment environments with simplified regulatory pathways compared to open-road certification.
- 5G-V2X Convergence:Integration of vehicle-to-infrastructure communication with edge computing networks enables predictive routing that reduces sensor redundancy requirements and hardware costs.
Industry Challenges
- Systems Safety Engineering Talent:Functional safety certification under ISO 26262 requires specialized expertise that remains scarce relative to fleet operator hiring demand.
- Teleoperation Infrastructure Capex:Remote human oversight centers demand redundant connectivity, physical security, and geographic distribution that strain capital allocation priorities.
- Cross-Border Regulatory Fragmentation:Divergent autonomous vehicle certification standards between the US, Canada, and Mexico complicate unified North American freight network planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autonomous Trucks Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long-Haul Trucks, Delivery Trucks, Tow Trucks, Refuse Trucks Technology: LiDAR, Computer Vision, Radar, Sensor Fusion End User: Logistics Companies, Retailers, Construction Firms, E-Commerce Companies Deployment: On-Premise, Cloud-Based, Hybrid, Fleet-Based |
| Companies Covered | Aurora Innovation, Kodiak Robotics, Plus.ai, Inceptio Technology, Torc Robotics, Einride, Waymo, Daimler Truck, AB Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autonomous Trucks Market Emerging Trajectories
Sensor fusion architectures and edge computing deployments are restructuring how autonomous trucks perceive environments and execute driving decisions without continuous cloud connectivity.
High-definition solid-state LiDAR is displacing mechanical spinning arrays as the dominant perception modality for highway-speed autonomous trucks. Tier 1 automotive suppliers are integrating these sensors into pre-wired chassis platforms that freight carriers can retrofit without complete vehicle replacement. This hardware transition is compressing the timeline for driver-out certification by reducing point-of-failure counts in safety-critical perception stacks.
The EU AI Act's risk-based classification system is imposing algorithmic audit requirements on autonomous system manufacturers seeking European type approval. Developers must document training data provenance and decision-logic interpretability, increasing engineering overhead but creating competitive moats against less resourced entrants. German freight corridors are experiencing deployment delays as KBA certification processes adapt to these transparency mandates.
Shippers are consolidating procurement around carriers offering guaranteed autonomous-ready capacity on specific corridors rather than traditional rate-per-mile contracts. Large retail distributors in Texas and California are rewriting tender requirements to prioritize fleets with certified driver-out capabilities on the I-35 and I-10 routes. This contractual evolution is pressuring asset-light brokers to secure autonomous capacity partnerships or cede volume to vertically integrated operators with owned autonomous fleets.
Global Autonomous Trucks Market Segmentation
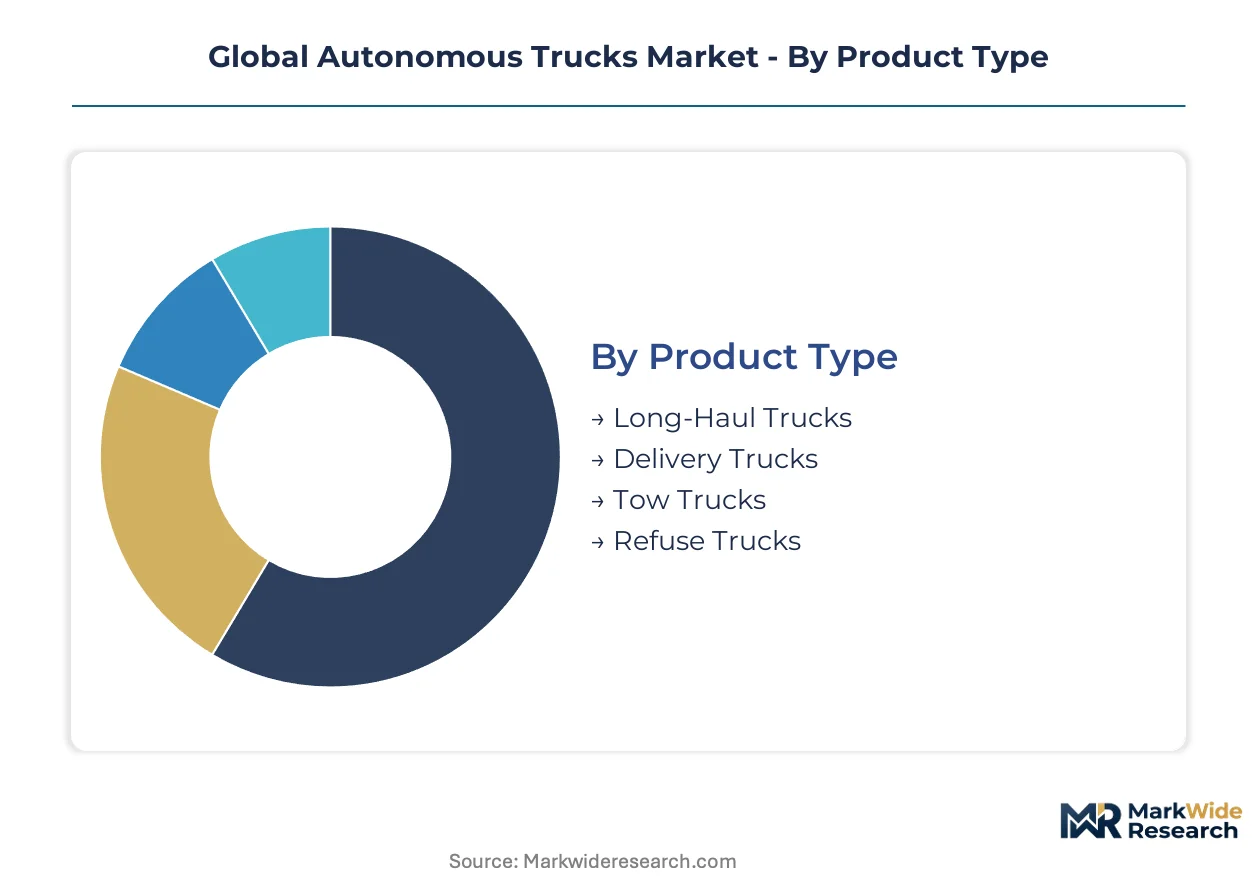
Segmentation reveals how autonomous truck deployment concentrates across operational domains and technology readiness levels. Product architecture, perception modality, and fleet ownership structure determine which configurations achieve regulatory clearance first.
Product Type:
Long-haul variants dominate North American pilot corridors while delivery configurations face steeper urban complexity barriers. Export demand for mining-sector autonomous haulers concentrates in Australia and Chile.
- Long-Haul Trucks:Highway-speed Class 8 tractors engineered for hub-to-hub freight corridors with redundant braking and steering actuators. Deployment concentrates along I-10 and I-35 in the southwestern United States where Arizona DOT maintains permissive testing frameworks and minimal weather interference.
- Delivery Trucks:Medium-duty urban distribution vehicles operating at lower speeds with enhanced pedestrian detection protocols. European cities under EU AI Act jurisdiction impose stricter algorithmic audit requirements that delay certification relative to North American timelines.
- Tow Trucks:Specialized recovery vehicles with manipulator arm integration for disabled vehicle retrieval.
- Refuse Trucks:Low-speed municipal waste collection units operating on fixed residential routes with predictable stop patterns.
Long-Haul Trucks holds the largest share; momentum sits with Delivery Trucks as last-mile automation protocols mature.
Technology:
Cost tiers separate premium multi-modality stacks from single-sensor economy configurations. Volume production favors solid-state architectures over mechanical spinning arrays.
- LiDAR:Solid-state and mechanical spinning arrays emitting pulsed laser light for centimeter-precision depth mapping. Manufacturing scale in Shenzhen and San Jose has compressed unit economics below fleet deployment thresholds for mid-sized carriers.
- Computer Vision:Convolutional neural networks processing RGB camera feeds for lane detection and traffic sign recognition. German KBA certification processes demand enhanced training data documentation under EU AI Act transparency mandates.
- Radar:Frequency-modulated continuous-wave sensors penetrating precipitation for velocity and range detection.
- Sensor Fusion:Redundant multi-modality architectures combining LiDAR, radar, and camera inputs through probabilistic state estimation.
Sensor Fusion commands premium pricing; LiDAR is gaining share fastest as solid-state manufacturing achieves automotive-grade reliability.
End User:
Customer type determines route predictability and thus regulatory pathway complexity. Captive industrial applications move faster than open-road freight.
- Logistics Companies:Asset-heavy freight carriers operating scheduled line-haul services between distribution centers. Pilot programs between Dallas and Houston demonstrate viable unit economics for hub-to-hub autonomous corridors.
- Retailers:Private fleet operators managing inbound supply chains from port terminals to regional distribution nodes. California-based retail distributors now specify autonomous-ready capacity in procurement tenders.
- Construction Firms:Project-site material haulers operating in geofenced environments with controlled access.
- E-Commerce Companies:Direct-to-consumer fulfillment networks requiring flexible routing and high-frequency stop patterns.
Logistics Companies anchor current deployment; E-Commerce Companies are expanding most quickly as sortation center density enables structured last-mile automation.
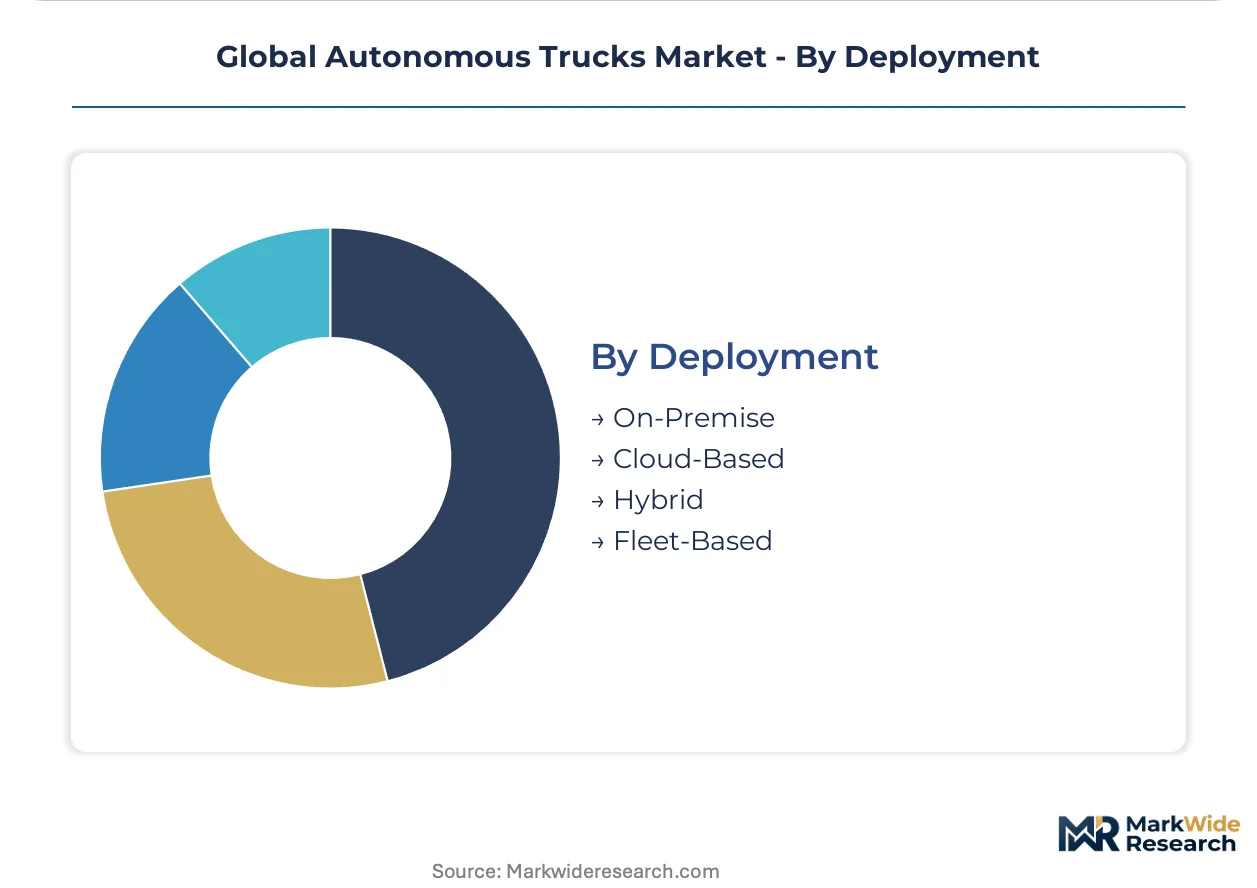
Deployment:
Maturity levels separate production-grade fleet systems from experimental cloud-dependent architectures. Edge computing requirements favor on-premise processing for safety-critical functions.
- On-Premise:Embedded computing platforms executing perception and planning algorithms within vehicle-mounted hardware. Southwestern United States carriers prefer this architecture to maintain operational continuity through cellular dead zones.
- Cloud-Based:Remote processing architectures dependent on continuous connectivity for mapping updates and fleet coordination. European operators under GDPR constraints face data residency requirements that complicate cross-border cloud routing.
- Hybrid:Tiered architectures processing safety-critical functions locally while offloading optimization tasks to edge nodes.
- Fleet-Based:Centralized management systems coordinating multi-vehicle operations through dedicated V2X infrastructure.
On-Premise dominates safety-critical applications; Hybrid is climbing the fastest as 5G-V2X convergence reduces redundant onboard computing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's evolving autonomous vehicle safety standards anchor deployment timelines across the United States, while regulatory fragmentation between national jurisdictions creates divergent certification pathways for manufacturers seeking multi-country operations.
United States
Hub-to-hub freight corridors between Dallas and Houston attract concentrated pilot investment from logistics operators seeking to circumvent FMCSA hours-of-service constraints. Arizona DOT maintains the most permissive testing framework nationwide, enabling driver-out trials along the I-10 corridor through Phoenix and Tucson. Texas DOT coordinates with private fleet operators to designate autonomous-ready highway segments with standardized V2X infrastructure.
Germany
KBA certification processes under EU AI Act transparency mandates delay commercial deployment relative to North American timelines. Baden-Württemberg hosts automotive supplier clusters developing solid-state LiDAR manufacturing capacity for European OEM integration. Munich-based freight operators pilot hub-to-hub automation on A9 motorway segments while awaiting algorithmic audit completion.
China
MIIT autonomous vehicle type approval processes prioritize closed-loop industrial applications over open-road freight certification. Yangtze River Delta logistics hubs in Shanghai and Suzhou deploy captive autonomous haulers within port terminal boundaries. Shenzhen sensor manufacturers achieve automotive-grade solid-state LiDAR scale that compresses unit economics for domestic fleet procurement.
Japan
METI R&D subsidies target platooning corridor development on Tomei and Meishin expressways connecting Tokyo and Osaka. Nagoya-based automotive suppliers integrate redundant braking actuators into chassis platforms purpose-built for automation retrofit. Kansai region freight operators coordinate with highway operators to designate dedicated autonomous vehicle lanes through mountainous terrain segments.
Australia
Captive mining haulage applications in Western Australia's Pilbara region bypass open-road regulatory complexity entirely. Fortescue and Rio Tino operate autonomous haul truck fleets exceeding 500 units across controlled-access mine sites. Perth-based technology providers export autonomous haulage expertise to Chilean and Mongolian mining operations seeking similar closed-loop deployment models.
Global Autonomous Trucks Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium sensor fusion stacks coexist with economy single-modality configurations. The vendor base organizes around three strategic archetypes: full-stack autonomy developers, Tier 1 automotive suppliers with pre-wired chassis platforms, and captive industrial operators with closed-loop deployment expertise. Dominant competitive moves include strategic partnerships between software developers and fleet operators, and geographic expansion through regulatory sandbox entry.
Within the full-stack autonomy tier, Aurora Innovation and Kodiak Robotics exemplify venture-backed developers pursuing driver-out certification on specific highway corridors before scaling geographically. Waymo occupies a position bridging consumer robotaxi and freight automation applications, leveraging accumulated perception data across both domains. Daimler Truck anchors the OEM-integrated archetype through captive manufacturing of automation-ready powertrain and chassis platforms. AB Volvo represents European-based competition pursuing KBA certification under EU AI Act algorithmic transparency requirements. Plus.ai and Inceptio Technology sit within the China-focused developer cluster targeting MIIT closed-loop approvals ahead of open-road deployment.
| Leading Market Players |
|---|
| Aurora Innovation |
| Kodiak Robotics |
| Plus.ai |
| Inceptio Technology |
| Torc Robotics |
| Einride |
| Waymo |
| Daimler Truck |
| AB Volvo |
| Others |
Supply Flow & Price Mechanics
Twenty-four-week lead times for solid-state LiDAR arrays concentrate pricing power among Shenzhen and San Jose sensor manufacturers, while freight carriers with forward-positioned chassis inventory capture margin relief from volatile perception hardware costs. This inventory positioning advantage separates mid-sized fleet operators locked into spot procurement from vertically integrated logistics groups with captive Tier 1 supplier relationships.
Pricing Analysis
Geographic price spreads between Arizona DOT-permissive testing corridors and EU AI Act certification zones exceed thirty percent for equivalent sensor fusion stacks. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 functional safety grade and fleet-scale volume commitments. Cost compression in economy single-modality configurations is intensifying because Shenzhen solid-state manufacturing achieves automotive-grade scale. Asset-light brokers exhibit highest price sensitivity, while captive mining operators in Western Australia demonstrate lowest sensitivity due to closed-loop deployment certainty.
Supply Chain Analysis
Just-in-time sensor procurement dominates North American pilot programs, whereas strategic stockpiling of redundant LiDAR arrays characterizes Australian mining haulage operators mitigating single-source vulnerability. Manufacturing concentrates in China, Germany, and the United States for solid-state emitters, precision optics, and edge computing modules respectively. Component dependencies span gallium nitride semiconductors, rare-earth optical substrates, and automotive-grade Ethernet chipsets. Tariff exposure on Chinese-manufactured perception hardware constitutes the primary structural risk. Distribution runs through Tier 1 automotive supplier channels for retrofit chassis platforms and direct OEM integration for factory-built automation-ready tractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous truck sector approaches a platform-economics inflection where V2X infrastructure interoperability determines which corridor networks achieve driver-out certification first, consolidating procurement power around integrated fleet operators with owned communication backbone.
For Market Incumbents: Secure exclusive V2X corridor partnerships with state DOT authorities in Texas and Arizona before emerging full-stack developers accumulate sufficient perception data for regulatory submission. Anchor manufacturing scale through backward integration into solid-state LiDAR supply agreements. Prioritize ISO 26262 certification investment as the defensive moat against venture-backed entrants lacking functional safety engineering depth. For New Entrants and Emerging Players: Lead with closed-loop industrial applications in Indian port terminals and Chilean mining zones where simplified regulatory pathways bypass open-road certification complexity. Target captive logistics corridors with predictable geofenced routes rather than hub-to-hub highway networks dominated by incumbents. Pursue teleoperation-as-a-service partnerships with mid-sized carriers lacking capital for redundant connectivity infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because the first jurisdiction certifying driver-out operation will cascade through insurance underwriting, shipper contracts, and fleet procurement criteria worldwide. Acquisition target archetype: full-stack developers with accumulated highway perception data exceeding ten million miles on specific corridors. Watch NHTSA autonomous vehicle safety standard finalization as the inflection signal determining deployment timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| V2X Infrastructure Partnership | Texas DOT coordination with private fleet operators standardizes autonomous-ready highway segments for I-35 corridor deployment. |
| Solid-State LiDAR Supply Agreement | Shenzhen sensor manufacturers compress unit economics below fleet-scale deployment thresholds for mid-sized carriers. |
| Closed-Loop Industrial Deployment | Western Australian mining operators bypass open-road regulatory complexity through controlled-access captive haulage applications. |
| Algorithmic Audit Completion | German KBA certification processes under EU AI Act mandates delay commercial deployment relative to North American timelines. |
| Teleoperation Infrastructure Buildout | Remote human oversight centers demand redundant connectivity and geographic distribution that strain capital allocation priorities. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FMCSA regulatory filings, NHTSA autonomous vehicle safety standards, and Arizona DOT testing framework documentation. Interviews with fleet operations directors, Tier 1 automotive supplier procurement leads, and V2X infrastructure engineers combined with SEC 10-K disclosures from publicly traded developers and customs records for LiDAR component trade flows. Bottom-up unit economics modeling triangulates against top-down market size validation from vehicle production databases.
Segmentation dimensions modeled span product architecture, perception modality, fleet ownership structure, and deployment maturity across the analysis window. CAGRs derive from corridor-specific adoption curve assumptions weighted by regulatory clearance probability and sensor cost trajectory inputs. Freight carrier utilization rate improvements and driver wage inflation differentials anchor demand-side forecast parameters.
The analysis sits within stated boundaries; outcomes outside Arizona DOT permissive framework expansion or EU AI Act certification timeline compression would require recalibration. Forecasts reflect documented assumptions regarding solid-state LiDAR manufacturing scale and FMCSA hours-of-service reform implementation. Revision becomes warranted when NHTSA autonomous vehicle safety standard finalization crosses thresholds enabling driver-out commercial deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Africa Autonomous Navigation Market