

Connected Vehicle Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Vehicle Technology Market Insights
Automotive-grade cybersecurity certification is unwinding legacy hardware architectures across the connected vehicle stack. Robert Bosch leverages its tier-one supplier relationships to embed secure gateway modules directly into vehicle networks. Continental AG anchors European V2X deployment through its cross-border corridor projects with infrastructure operators. Qualcomm differentiates by supplying integrated cellular modems that consolidate 4G, 5G, and C-V2X on single chipsets.
Connected vehicle technology encompasses embedded systems, wireless communication modules, and software platforms that enable real-time data exchange between vehicles, infrastructure, and cloud services through protocols operating across sub-6 GHz and millimeter-wave spectrum bands. Its primary purpose is to enhance traffic safety, optimize fleet utilization, and enable automated driving functions through continuous sensor fusion and over-the-air updates. V2X communication commands the largest share of technology investment due to its foundational role in cooperative intelligent transport systems, while edge computing deployment is expanding fastest as latency-sensitive applications such as collision avoidance outpace cloud-only architectures. Fleet management leads application adoption because commercial operators capture measurable fuel and labor savings from real-time vehicle tracking and predictive diagnostics.
The European Telecommunications Standards Institute shapes V2X protocol harmonization, while the U.S. Department of Transportation's ITS Joint Program Office drives federal pilot funding for connected corridor infrastructure. China's Ministry of Industry and Information Technology mandates dual-mode cellular-V2X and direct short-range communication compatibility for new vehicle type approvals. Stakeholders must monitor spectrum allocation decisions at national regulators, as 5.9 GHz band reclassification in multiple jurisdictions threatens dedicated short-range communication deployment timelines and forces technology portfolio recalibration.
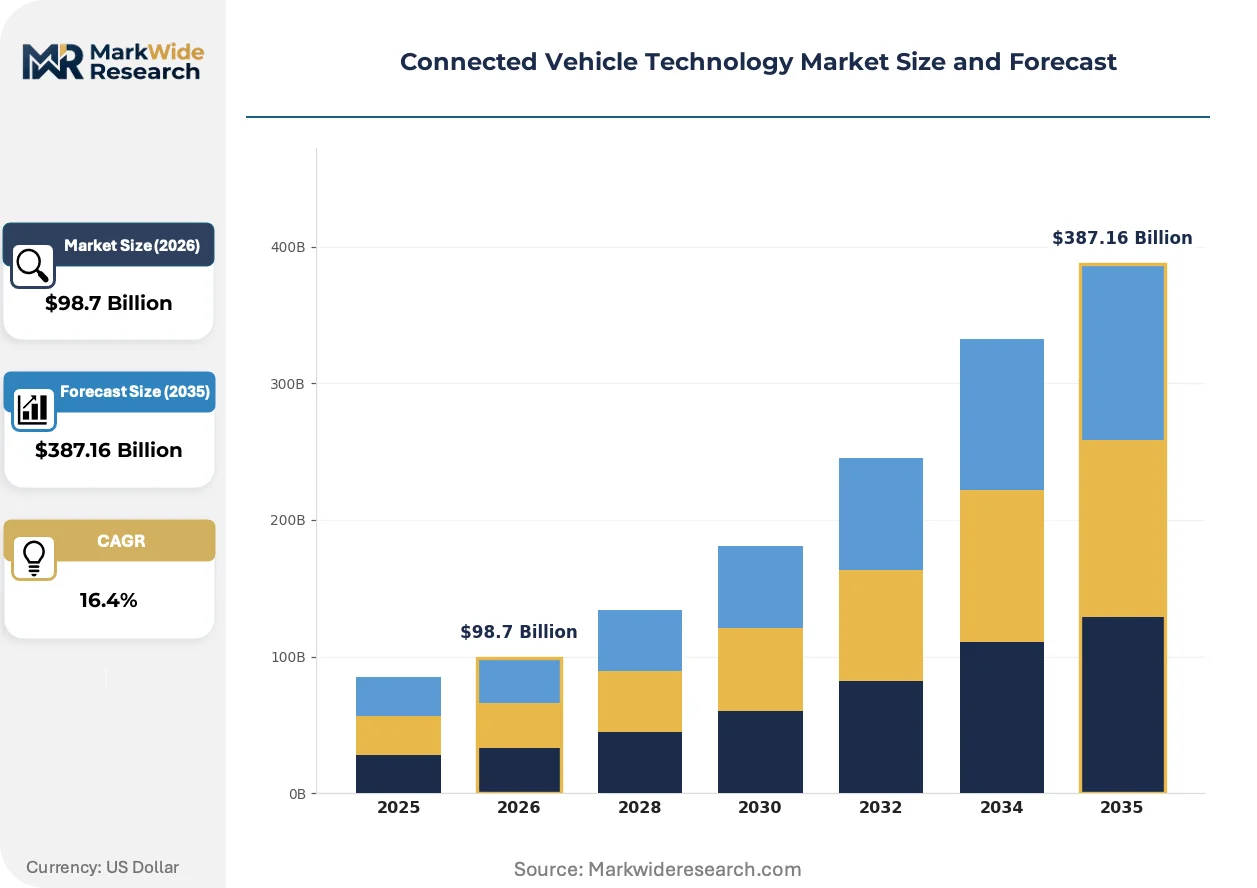
Market Dynamics
The European Union's Cyber Resilience Act is forcing automotive OEMs to unwind legacy electronic architectures and revalidate entire vehicle networks against mandatory baseline security standards. This regulatory pressure is compressing supplier certification timelines and redistributing competitive advantage toward tier-one module integrators with pre-certified gateway platforms.
Growth Catalysts
- Cellular-V2X Mandates:China's MIIT requires dual-mode C-V2X and DSRC compatibility for all new vehicle type approvals, accelerating chipset consolidation toward single-modem solutions.
- Fleet Telematics Expansion:Commercial operators across Germany, the United States, and Japan are deploying predictive diagnostics platforms to capture measurable fuel and labor savings from real-time vehicle tracking.
- Edge Computing Deployment:Latency-sensitive collision avoidance applications are outpacing cloud-only architectures, driving hardware investment into roadside units and onboard processing modules.
Market Restraints
- Semiconductor Supply Concentration:Advanced cellular modem fabrication concentrates among a limited set of foundry operators in Taiwan and South Korea, creating vulnerability to geopolitical disruption.
- Spectrum Reclassification Risk:National regulators in multiple jurisdictions are reconsidering 5.9 GHz band allocation, threatening dedicated short-range communication deployment timelines and forcing portfolio recalibration.
- Integration Cost Burden:Retrofitting secure gateway modules into legacy vehicle network architectures requires substantial electrical engineering rework and validation cycles.
Strategic Opportunities
- Cross-Border V2X Corridors:Infrastructure operators along the Rotterdam-Frankfurt-Vienna freight axis are piloting harmonized cooperative intelligent transport systems with standardized roadside unit deployment.
- Predictive Maintenance Platforms:Commercial fleet operators in Brazil and India represent underpenetrated demand for remote diagnostics and over-the-air software update capabilities.
- 5G-Advanced Convergence:The integration of non-terrestrial network satellite links with terrestrial cellular infrastructure is creating redundant connectivity for autonomous convoy platooning applications.
Industry Challenges
- Automotive Cybersecurity Certification:The UN R155 and R156 type approval processes require documented security management systems and software update capabilities that most component suppliers lack.
- Multi-Protocol Integration Complexity:Vehicle networks must simultaneously manage C-V2X, DSRC, 4G, 5G, and satellite links without interference, demanding sophisticated antenna and RF front-end engineering.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Vehicle Technology Market Trends and Innovations
Software-defined vehicle architectures are decoupling hardware refresh cycles from functional capability upgrades, enabling continuous monetization through subscription-enabled feature activation. This shift is redistributing value capture from discrete component sales toward recurring service revenue streams.
Edge computing infrastructure for connected vehicles is fragmenting the traditional cloud-centric data processing model. Roadside units deployed along highway corridors in Germany and the United States now handle sub-100-millisecond collision warnings locally. Tier-one suppliers are integrating multi-access edge computing capabilities directly into cellular modem chipsets. This distributed architecture is compressing reliance on centralized cloud platforms for safety-critical applications.
The U.S. Department of Transportation's ITS Joint Program Office is accelerating federal pilot funding for connected corridor infrastructure through the Infrastructure Investment and Jobs Act. State departments of transportation in Michigan, Arizona, and Pennsylvania are competing for deployment grants that mandate interoperable V2X equipment procurement. Equipment vendors must certify against SAE J2945/1 standards to qualify for federal reimbursement, filtering the supplier base toward pre-qualified integrators.
Commercial fleet operators are consolidating procurement decisions at the enterprise level rather than delegating to regional maintenance managers. Large logistics providers in North America and Western Europe are mandating unified telematics platforms across mixed-vehicle fleets to standardize fuel reporting and driver behavior analytics. This concentration is displacing fragmented aftermarket device installations with factory-embedded OEM solutions in heavy-duty truck segments.
Connected Vehicle Technology Market Segmentation
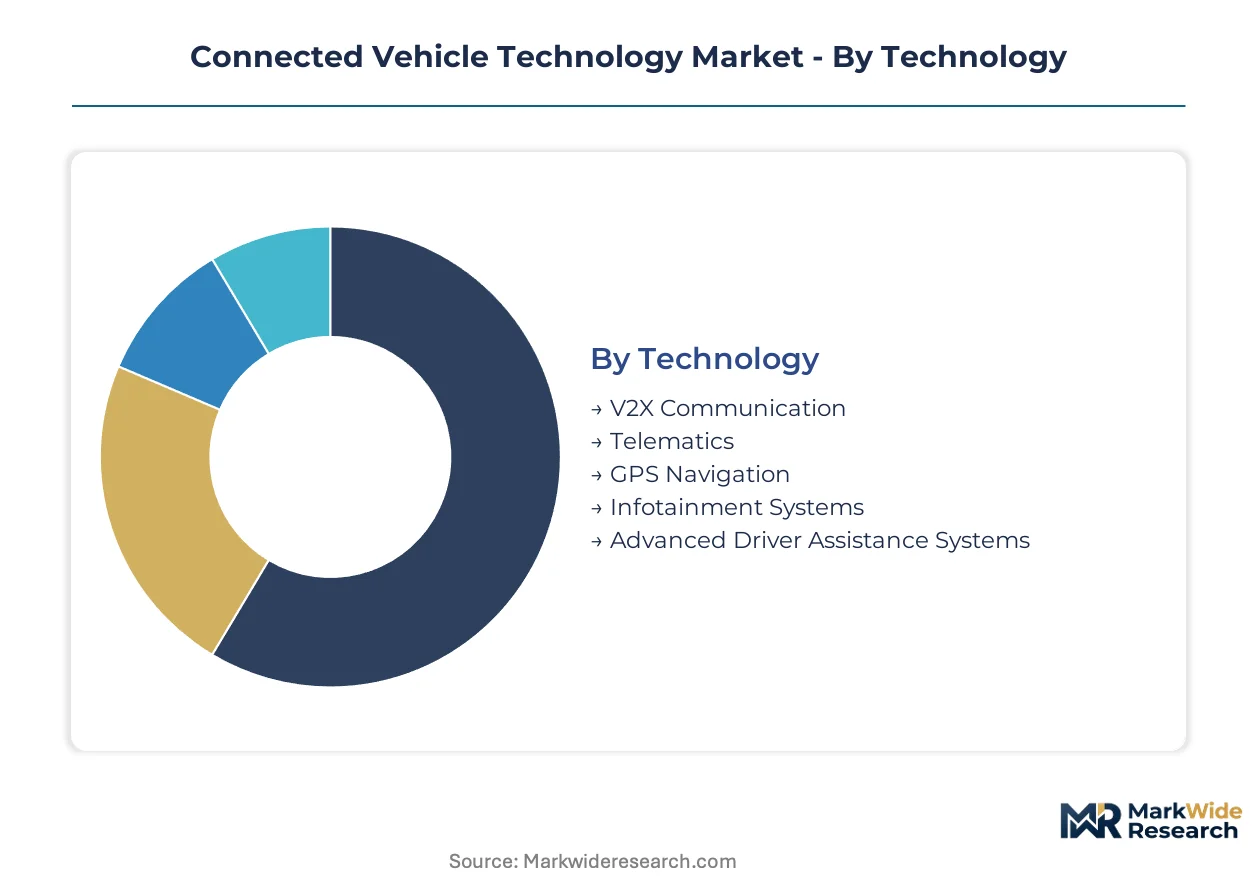
Technology diversity across the connected vehicle stack creates distinct procurement channels, with hardware-intensive segments flowing through tier-one automotive suppliers and software-centric categories monetizing via direct OEM licensing and aftermarket platform subscriptions.
Technology:
Channel architecture splits between embedded hardware modules supplied through tier-one integrators and software platforms distributed via direct enterprise licensing, with regulatory certification requirements determining route-to-market economics.
- V2X Communication:Dedicated short-range and cellular protocols enable real-time vehicle-to-infrastructure data exchange. Germany's KBA anchors European type approval processes, while China's MIIT mandates dual-mode compatibility, compressing chipset consolidation timelines toward single-modem solutions.
- Telematics:Embedded cellular modems and GPS receivers transmit vehicle diagnostics and location data to fleet management platforms. Demand concentrates among North American commercial operators optimizing route efficiency, with subscription revenue models displacing upfront hardware sales.
- GPS Navigation:Satellite positioning systems with real-time traffic integration.
- Infotainment Systems:In-vehicle entertainment and connectivity hubs with over-the-air update capabilities.
- Advanced Driver Assistance Systems:Sensor fusion platforms enabling automated braking and lane-keeping functions.
By volume, Telematics leads. By growth pace, V2X Communication is gaining share fastest.
Application:
Cost tier stratification separates enterprise fleet deployments with measurable fuel savings from consumer-facing applications dependent on insurance premium discounts for adoption traction.
- Fleet Management:Real-time vehicle tracking, predictive diagnostics, and driver behavior analytics platforms. Large logistics providers in the United States and Germany mandate unified telematics across mixed-vehicle fleets, standardizing fuel reporting and displacing fragmented aftermarket installations.
- Safety Enhancement:Collision avoidance and cooperative intelligent transport systems. Pilot corridors along Rotterdam-Frankfurt-Vienna freight routes validate harmonized roadside unit deployment, with sub-100-millisecond latency requirements driving edge computing investment.
- Traffic Management:Urban congestion monitoring and signal optimization systems.
- Predictive Maintenance:Remote diagnostics and component failure forecasting.
- Usage-Based Insurance:Premium pricing tied to actual driving behavior and mileage data.
Fleet Management commands the largest revenue pool. Safety Enhancement exhibits the steepest expansion trajectory.
End User:
Customer type concentration shifts procurement authority from regional maintenance managers toward centralized enterprise technology offices, particularly among ride-hailing and logistics operators with multi-thousand vehicle deployments.
- OEMs:Vehicle manufacturers embedding connected systems at factory assembly. Factory-embedded solutions in heavy-duty truck segments displace aftermarket installations as procurement consolidates at the enterprise level across North America and Western Europe.
- Ride-Hailing Services:Mobility platforms requiring real-time fleet visibility and passenger safety monitoring. Urban deployment density in São Paulo and Mumbai creates concentrated demand for low-latency vehicle tracking and automated incident response.
- Vehicle Leasing Companies:Fleet owners monetizing residual value through usage data.
- Public Transportation Operators:Municipal bus and rail systems optimizing service frequency.
- Government Agencies:Federal and state departments funding connected corridor infrastructure.
OEMs anchor volume. Ride-Hailing Services are expanding most quickly.
Deployment:
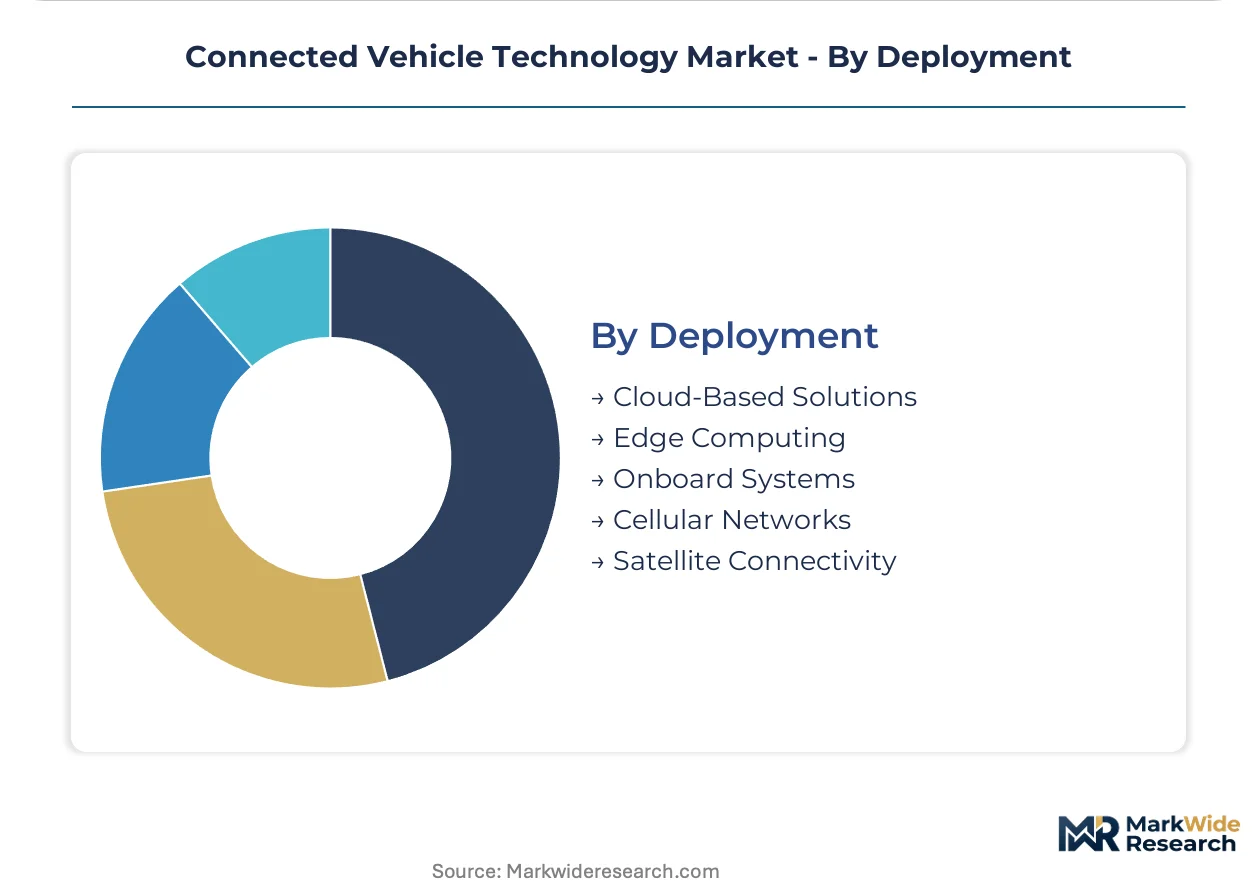
Maturity gradients separate established cellular networks from emerging satellite and edge architectures, with latency requirements determining architecture selection for safety-critical versus convenience applications.
- Cloud-Based Solutions:Centralized data processing and storage platforms. Convenience applications including infotainment content delivery and non-urgent diagnostics flow through cloud architectures, though latency constraints limit safety-critical deployment.
- Edge Computing:Distributed roadside and onboard processing units. Germany's highway corridors deploy multi-access edge computing capabilities directly into cellular modem chipsets, handling collision warnings locally without cloud dependency.
- Onboard Systems:Vehicle-resident processing hardware with local data storage.
- Cellular Networks:4G and 5G terrestrial infrastructure for wide-area connectivity.
- Satellite Connectivity:Non-terrestrial network links for redundant autonomous convoy communications.
Cellular Networks dominate current volume. Edge Computing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in connected vehicle technology tilt toward net-import positions in Western Europe and North America, while East Asian economies maintain component export surpluses in cellular modems and semiconductor substrates.
United States
Commercial fleet operators in Michigan and Arizona drive telematics hardware procurement. The Department of Transportation's ITS Joint Program Office channels Infrastructure Investment and Jobs Act funding toward connected corridor pilots. Equipment vendors in Detroit cluster around SAE J2945/1 certification requirements to qualify for federal reimbursement.
Germany
Automotive OEMs anchor V2X pilot programs requiring secure gateway modules. The KBA anchors European type approval processes under UN R155 and R156 cybersecurity mandates. Suppliers along the Rotterdam-Frankfurt-Vienna freight axis deploy harmonized roadside units for cooperative intelligent transport systems.
China
Domestic vehicle type approvals mandate dual-mode C-V2X and DSRC compatibility. MIIT regulations compress chipset consolidation timelines toward single-modem solutions. Shenzhen and Shanghai manufacturing clusters supply integrated cellular platforms for regional OEMs.
Japan
METI coordinates cross-ministry standards for automated driving and V2X interoperability. Domestic OEMs embed factory-telemetics solutions in heavy-duty truck segments. Nagoya and Tokyo metropolitan areas concentrate supplier R&D investment in sensor fusion platforms.
South Korea
Advanced cellular modem fabrication concentrates among foundry operators serving global automotive customers. The Seoul Capital Area hosts semiconductor design houses developing 5G-Advanced convergence architectures. Busan-Ulsan industrial corridors supply RF front-end components for multi-protocol vehicle networks.
Connected Vehicle Technology Market Competitive Landscape
Concentration sits with tier-one automotive suppliers possessing pre-certified gateway platforms and direct OEM relationships. The vendor base stratifies between integrated module manufacturers and specialized software platform providers. Two strategic archetypes dominate: vertically integrated component suppliers with captive semiconductor access, and pure-play telematics platform vendors monetizing via recurring service revenue. Competitive moves center on cross-border corridor partnerships and edge computing capability integration into cellular modem chipsets.
Within the tier-one supplier tier, Robert Bosch and Continental AG exemplify integrated module manufacturers with established automotive relationships, while Qualcomm occupies a position representing semiconductor-centric platform consolidation. These three entities anchor distinct competitive vectors: Bosch leverages secure gateway embedding, Continental anchors European V2X deployment through infrastructure partnerships, and Qualcomm differentiates via single-chipset cellular convergence.
| Leading Market Players |
|---|
| Robert Bosch |
| HARMAN International |
| Continental AG |
| DENSO Corporation |
| Aptiv |
| Qualcomm |
| TomTom |
| Panasonic |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Ninety-day chipset lead times from Taiwan and South Korea foundries concentrate pricing power among integrated modem suppliers, while tier-one automotive module integrators pass through cost volatility via annual contract renegotiations with OEM procurement offices.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on UN R155 certification grade and volume scale, with pre-certified secure gateway modules commanding substantial premiums over uncertified alternatives. Cost compression in the standard tier is intensifying because Chinese MIIT mandates are accelerating chipset consolidation timelines. Fleet operators with multi-thousand vehicle deployments exhibit the lowest price sensitivity, while regional aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Taipei-Hsinchu corridor foundry capacity underwrites global cellular modem fabrication for automotive applications. Supply concentrates in Taiwan, South Korea, and China for advanced semiconductor substrates, with RF front-end components sourcing from Busan-Ulsan industrial corridors. The supply chain draws from silicon wafers, compound semiconductor substrates, and automotive-grade packaging materials. Single-source vulnerability concentrates at 5nm and 7nm process nodes. Distribution runs through tier-one module integrators with direct OEM assembly line relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as enterprise fleet procurement consolidates at headquarters level, displacing regional aftermarket vendors and creating niches for specialized telematics platform providers with direct OEM licensing capabilities.
For Market Incumbents: Secure pre-certified gateway platform volumes by embedding security modules directly into vehicle network architectures before UN R156 software update mandates harden competitive barriers. Deepen backward integration into cellular modem chipsets to reduce foundry concentration exposure. Channel control through exclusive tier-one supplier relationships remains the critical defensive lever against semiconductor-centric platform consolidators. For New Entrants and Emerging Players: Differentiate on edge computing integration by targeting Brazil and India commercial fleet operators with predictive maintenance platforms that bypass established OEM embedded solutions. The most penetrable segment sits among mid-size logistics providers with 500-5,000 vehicle fleets lacking unified telematics standardization. A direct enterprise SaaS licensing model with over-the-air update capabilities bypasses tier-one module integrator gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because cybersecurity certification requirements are hardening competitive moats faster than technology cycles refresh. Acquisition targets should display pre-certified gateway platforms under UN R155 with active tier-one supplier relationships. The signal to watch is 5.9 GHz spectrum reclassification decisions at national regulators, which would force portfolio recalibration and create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Gateway Platform Certification | UN R155 compliance locks in tier-one supplier relationships ahead of regulatory deadlines. |
| Edge Computing Capability Integration | Multi-access edge computing in cellular modems reduces cloud dependency for collision avoidance. |
| Cross-Border V2X Corridor Partnerships | Rotterdam-Frankfurt-Vienna freight axis pilots validate harmonized roadside unit deployment. |
| Single-Modem Chipset Consolidation | Dual-mode C-V2X and DSRC compatibility compresses hardware complexity for MIIT compliance. |
| Predictive Maintenance Platform Expansion | Brazil and India fleet operators represent underpenetrated demand for remote diagnostics capabilities. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and fleet operations technology officers; and secondary validation against vehicle production databases, IHS Markit registration data, SEC semiconductor company filings, and national regulator spectrum allocation notices. Bottom-up unit economics triangulated against top-down market sizing across technology and application segments.
Across the projection horizon, the analytical framework modeled volume and value trajectories by V2X communication protocol, telematics deployment model, fleet management application intensity, and regional regulatory cluster. CAGRs derived from technology adoption curve analysis and OEM platform refresh cycle timing. Forecast inputs included chipset consolidation timelines under MIIT mandates and edge computing infrastructure deployment rates along priority highway corridors.
The analysis sits within stated boundaries; outcomes outside sustained 5.9 GHz spectrum allocation or accelerated UN R155 enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding semiconductor supply normalization and tier-one supplier certification completion rates. Practitioners should keep alternative scenarios live as national regulator spectrum decisions and automotive cybersecurity mandate enforcement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.