
 North America Automotive Parts Magnesium Die Casting Market | 2026-2036
North America Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Parts Magnesium Die Casting Market Analytics
Tier-1 supplier networks across Michigan and Ontario are reshaping procurement patterns for magnesium structural castings as automakers consolidate vendor bases for EV architectures. Shiloh Industries leverages its multi-material stamping and casting portfolio to anchor programs with Detroit-based OEMs. Nemak sustains a dominant position in powertrain housings through captive magnesium melting and high-volume die casting scale.
Automotive parts magnesium die casting refers to the net-shape manufacturing process where molten magnesium alloy—typically AZ91D or AM60B with 8-9% aluminum content—is injected into hardened steel dies under pressures exceeding 1,000 bar to produce thin-walled, high-strength components. The process yields parts 33% lighter than comparable aluminum castings, serving primarily as mass-reduction solutions for vehicle structures and powertrains where every kilogram saved improves fuel economy or extends electric range. Structural components command the deepest margin pools due to crashworthiness certification requirements and longer qualification cycles, while high-pressure die casting technology leads unit volume by a wide margin given its cycle-time advantages over gravity and semi-solid alternatives. Transmission housings represent the fastest-growing application segment as multi-speed e-axle designs proliferate across hybrid and battery-electric platforms.
NHTSA crashworthiness standards and EPA fuel economy mandates jointly determine magnesium adoption rates by setting mass-reduction targets that aluminum alone cannot satisfy cost-effectively. The IRA's domestic content bonuses for North American-assembled electric vehicles further steer sourcing decisions toward qualified regional die casters with proven OEM track records. Stakeholders must monitor how NHTSA updates to pedestrian impact rules and EPA fleet-average thresholds alter the business case for magnesium-intensive body structures versus competing multi-material approaches.
Market Dynamics
The EPA's tightened corporate average fuel economy standards are compressing design cycles across Michigan and Ontario assembly corridors, forcing powertrain engineers toward magnesium-intensive architectures that aluminum alone cannot satisfy cost-effectively.
Growth Catalysts
- CAFE Standards:The EPA's fleet-average thresholds mandate mass reduction that magnesium die castings deliver at 33% weight savings versus aluminum alternatives, accelerating adoption in transmission housings.
- IRA Domestic Content:The Inflation Reduction Act's North American assembly bonuses steer EV sourcing toward qualified regional die casters with proven OEM track records.
- E-Axle Proliferation:Multi-speed electric axle designs across hybrid and battery-electric platforms multiply housing complexity and magnesium casting opportunities.
Market Restraints
- Primary Magnesium Volatility:US and Canadian die casters face input cost instability tied to Chinese magnesium smelter output and energy price swings.
- Die Life Limitations:AZ91D's high aluminum content accelerates thermal fatigue in hardened steel tooling, compressing maintenance intervals versus aluminum die casting.
- Aluminum Substitution:High-pressure aluminum casting advances threaten magnesium's cost position in non-structural applications where crashworthiness certification is absent.
Strategic Opportunities
- Structural Battery Enclosures:EV platforms across the Great Lakes manufacturing belt require crash-certified magnesium castings for integrated battery housing structures.
- NHTSA Pedestrian Impact Rules:Updated hood and front-end compliance standards favor magnesium's energy absorption characteristics over stiffer aluminum alternatives.
- Semi-Solid Convergence:Thixomolding advances combined with high-pressure die casting automation create hybrid process opportunities for complex thin-wall geometries.
Industry Challenges
- Tooling Engineer Scarcity:Die design for magnesium's solidification behavior demands specialized thermal management expertise concentrated among retiring specialists.
- Qualification Timeline Compression:OEM crashworthiness certification cycles for structural castings extend 18-24 months, misaligning with compressed EV platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Parts Magnesium Die Casting Market |
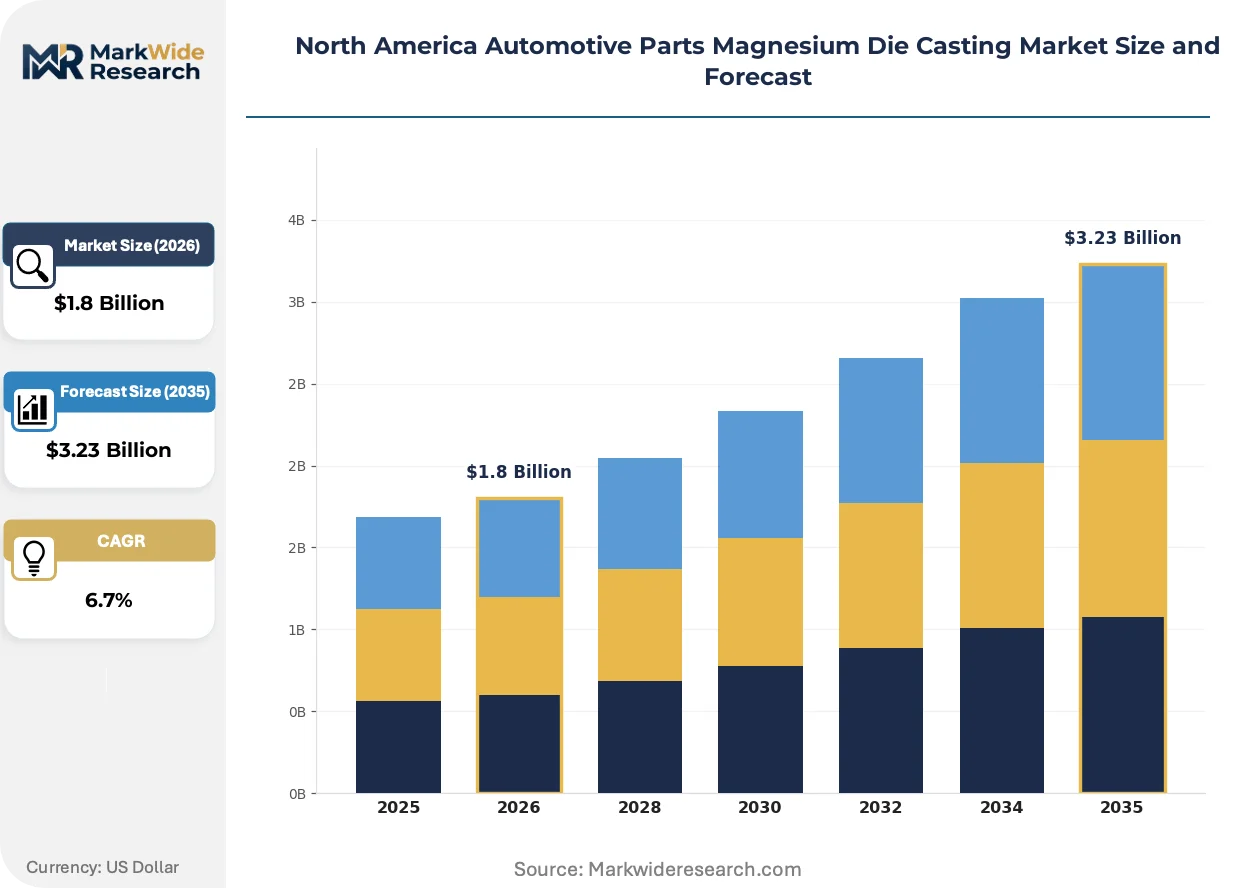
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Structural Components, Engine Blocks, Transmission Housings, Wheel Rims Product Type: Die-Cast Parts, Cast Alloy, Magnesium Ingots, Extruded Components End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Auto Assemblers Technology: High-Pressure Die Casting, Gravity Die Casting, Squeeze Casting, Semi-Solid Casting |
| Companies Covered | Shiloh Industries, Nemak, Meridian Lightweight Technologies, Ryobi Die Casting, Linamar Corporation, Gibbs Die Casting Group, Georg Fischer AG, Martinrea Honsel, Pace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Parts Magnesium Die Casting Market Evolving Landscape
Multi-material stamping and casting integration is reshaping how Tier-1 suppliers anchor programs with Detroit-based OEMs, collapsing traditional boundaries between process technologies.
Thixomolding semi-solid magnesium injection systems are rendering obsolete conventional high-pressure die casting for complex thin-wall geometries. Tier-1 suppliers across Ontario are adopting these systems for dashboard support beams and steering column brackets. The technology is rendering obsolete gravity casting methods that cannot achieve comparable mechanical properties at equivalent cycle times.
The EPA's corporate average fuel economy standards are tightening enforcement thresholds for 2027-2032 model years. Automakers must document fleet-wide mass reduction trajectories that magnesium-intensive powertrain housings help satisfy. Transmission housing suppliers across Michigan and Ohio are responding with expanded AZ91D casting capacity to capture compliance-driven procurement.
Consolidated vendor bases are compressing supplier qualification cycles for EV architectures. Tier-1 networks are displacing fragmented multi-source arrangements with single-source magnesium casting partnerships. This concentration is most visible across the Michigan-Ontario assembly corridor where OEMs prioritize die casters with captive melting and proven high-volume scale.
North America Automotive Parts Magnesium Die Casting Market Segmentation
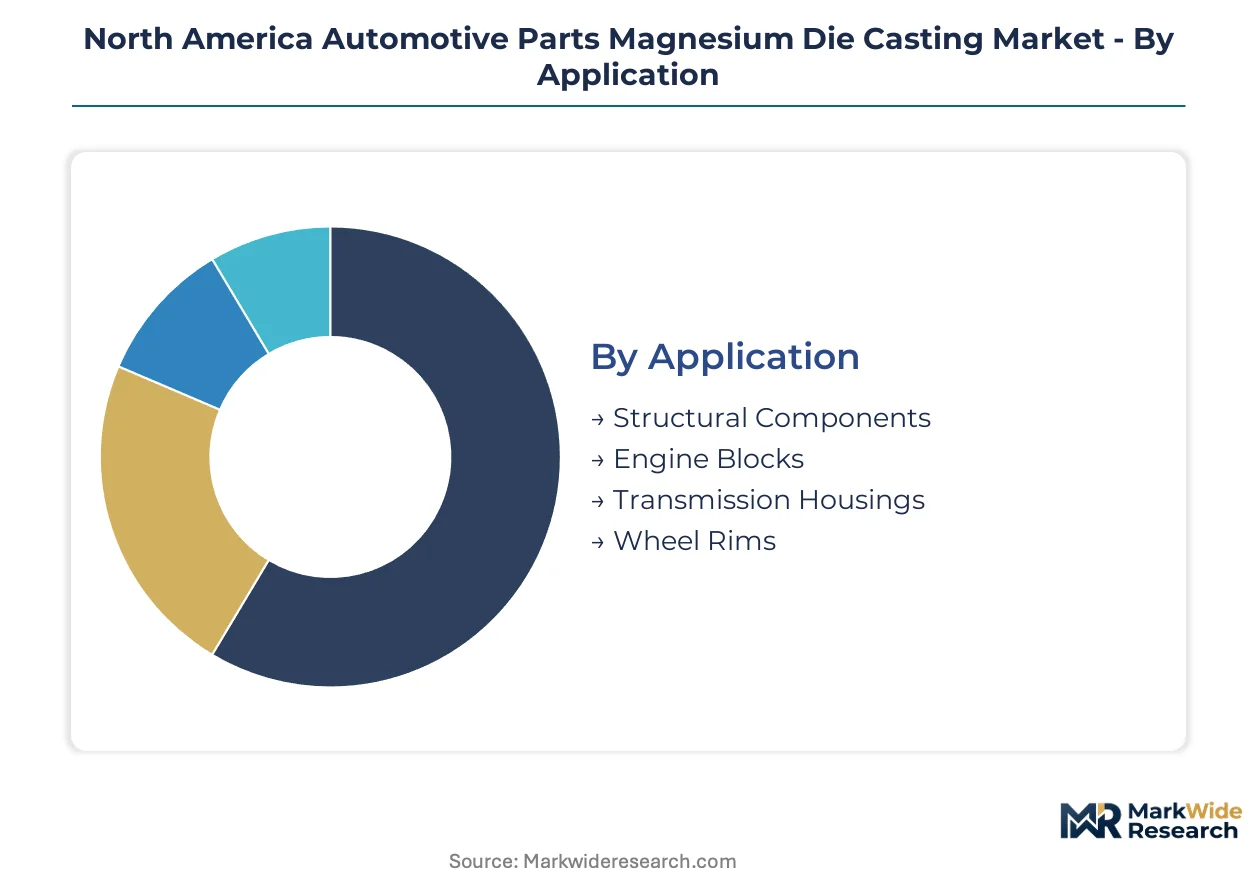
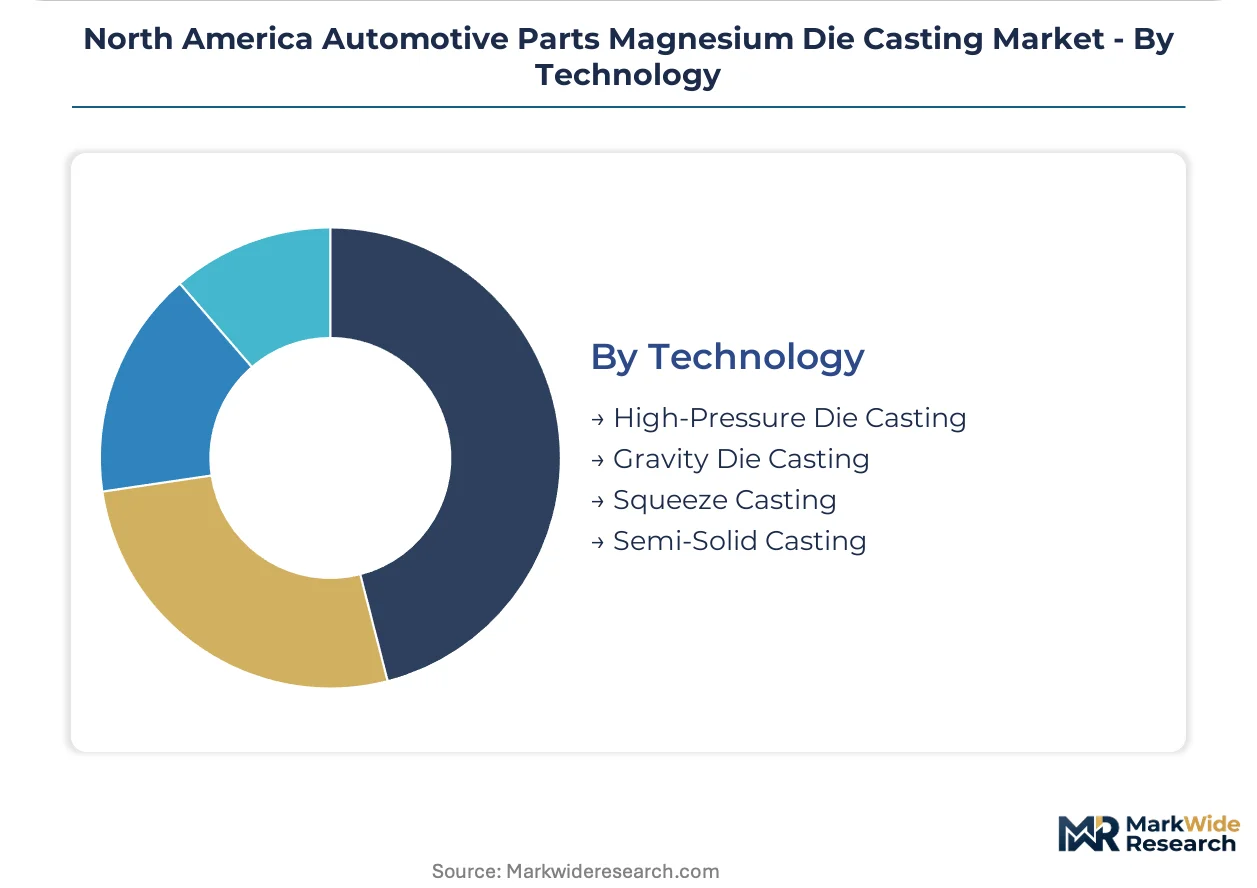
Magnesium die casting procurement patterns diverge sharply across application types and manufacturing technologies. Each segmentation dimension reveals distinct margin structures, qualification barriers, and supply chain configurations that determine competitive positioning in North American automotive programs.
Application:
Cost tier determines magnesium adoption intensity, with crash-certified structural applications commanding premium pricing versus commodity powertrain housings.
- Structural Components:AZ91D and AM60B alloys deliver crashworthiness certification for body-in-white applications. Demand concentrates across Michigan and Ontario EV platforms where mass reduction targets exceed aluminum capabilities. NHTSA pedestrian impact compliance drives hood and front-end adoption.
- Transmission Housings:Multi-speed e-axle designs for hybrid and battery-electric vehicles multiply housing complexity. Michigan-based suppliers expand AZ91D capacity to capture OEM compliance-driven procurement for fleet-average fuel economy standards.
- Engine Blocks:Conventional internal combustion applications face substitution pressure from aluminum and composite alternatives.
- Wheel Rims:Aftermarket and performance vehicle segments sustain limited volume despite weight advantages.
Structural components command the established base. The steepest expansion runs through transmission housings.
Product Type:
Volume concentration tracks manufacturing integration depth, with finished die-cast parts capturing value that upstream alloy suppliers cannot access.
- Die-Cast Parts:Net-shape components eliminate machining operations for transmission housings and structural brackets. Tier-1 suppliers across the Great Lakes manufacturing belt consolidate procurement around qualified die casters with captive melting capacity.
- Cast Alloy:Secondary magnesium alloy ingots feed captive foundry operations at major Tier-1 suppliers. Ontario-based processors maintain tolling relationships with Detroit OEM supply chains.
- Magnesium Ingots:Primary metal sourcing faces Chinese supply concentration and tariff exposure.
- Extruded Components:Limited automotive penetration outside crash absorption beams and seat frames.
Die-cast parts anchor the revenue base. Cast alloy supply is climbing the fastest as vertical integration accelerates.
End User:
Customer type dictates qualification timelines and contract structures, with OEM direct relationships demanding longest certification cycles.
- OEMs:Detroit-based automakers specify magnesium-intensive designs for EV platforms under EPA fleet-average mandates. Direct procurement relationships require 18-24 month crashworthiness certification cycles.
- Tier-1 Manufacturers:Shiloh Industries and Nemak anchor supply chains through multi-material stamping and casting portfolios. These suppliers intermediate between raw casters and final assembly.
- Aftermarket Suppliers:Performance wheel and accessory segments sustain fragmented demand outside regulatory compliance drivers.
- Auto Assemblers:Contract manufacturing arrangements for niche vehicle programs.
Tier-1 manufacturers hold the established procurement volume. OEM direct sourcing is gaining share fastest as EV platform consolidation proceeds.
Technology:
Process maturity shapes equipment investment requirements and cycle-time economics, with high-pressure systems dominating volume production.
- High-Pressure Die Casting:Cycle-time advantages exceed 40% versus gravity alternatives. Hardened steel dies withstand AZ91D injection pressures above 1,000 bar for thin-wall transmission housings across Michigan and Ohio foundries.
- Semi-Solid Casting:Thixomolding systems achieve superior mechanical properties for dashboard support beams. Ontario Tier-1 suppliers adopt these systems as conventional gravity methods become obsolete for complex geometries.
- Gravity Die Casting:Limited to thick-section components where solidification control is less critical.
- Squeeze Casting:Niche applications in high-integrity structural nodes requiring porosity elimination.
High-pressure die casting commands the installed capacity base. Semi-solid casting is expanding most quickly as thixomolding automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ambassador Bridge and Detroit River rail tunnels channel cross-border magnesium alloy flows between Michigan foundries and Ontario assembly plants. This infrastructure underwrites North America's densest automotive die casting corridor.
United States
Michigan anchors US magnesium die casting demand through Detroit Three EV platform commitments. The EPA's tightened CAFE standards for 2027-2032 model years mandate fleet-wide mass reduction trajectories. Foundries across Ohio and Indiana expand AZ91D capacity to capture transmission housing procurement from hybrid and battery-electric powertrain programs.
Canada
Ontario's Great Lakes manufacturing belt concentrates Tier-1 magnesium casting operations serving Detroit OEM supply chains. The country's national automotive regulator aligns crashworthiness certification with NHTSA standards to maintain integrated North American production. Windsor-Toronto corridor facilities process secondary magnesium alloys for structural battery enclosures on emerging EV platforms.
Mexico
Bajío Region assembly plants generate downstream demand for magnesium transmission housings in hybrid vehicle exports. The USMCA regional content rules steer Tier-1 suppliers toward North American-sourced castings. Querétaro and Guanajuato industrial parks attract die casting investment to serve both US and domestic OEM programs.
North America Automotive Parts Magnesium Die Casting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The North American magnesium die casting market exhibits concentrated supply-side structure around captive melting operations and high-volume foundry scale. Two strategic archetypes dominate: multi-material Tier-1 suppliers with stamping-casting integration capabilities, and dedicated magnesium specialists with captive alloy production. Competitive moves center on vendor base consolidation for EV architectures and backward integration into secondary magnesium supply.
Within the multi-material integration tier, Shiloh Industries and Nemak exemplify archetypes combining diverse process portfolios with OEM direct relationships. Meridian Lightweight Technologies occupies a position among dedicated magnesium specialists with geographic naming suggesting North American operational concentration. These anchors represent contrasting pathways—portfolio breadth versus process depth—in securing long-term platform supply agreements.
| Leading Market Players |
|---|
| Shiloh Industries |
| Nemak |
| Meridian Lightweight Technologies |
| Ryobi Die Casting |
| Linamar Corporation |
| Gibbs Die Casting Group |
| Georg Fischer AG |
| Martinrea Honsel |
| Pace Industries |
| Others |
Value Network & Pricing Analysis
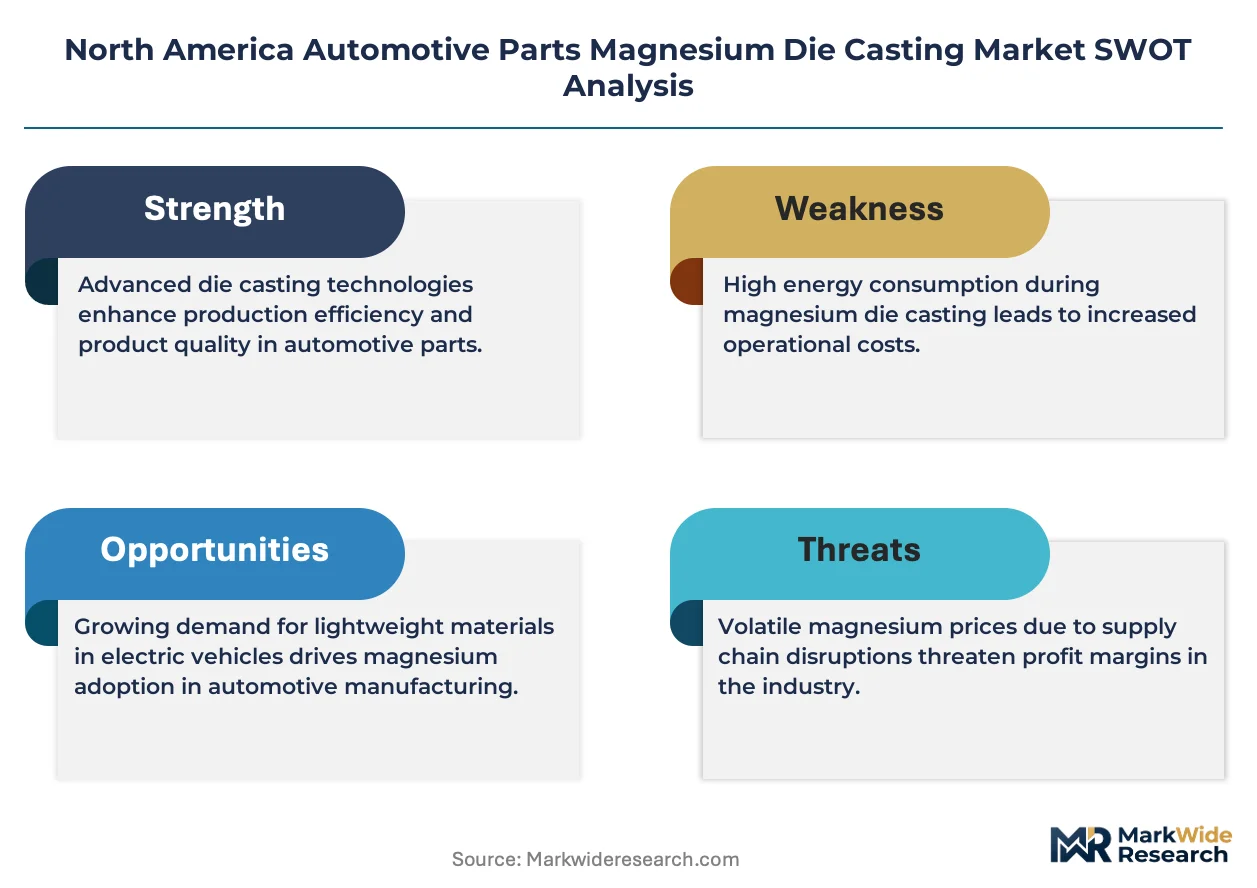
Chinese primary magnesium smelter concentration feeds directly into margin capture at North American die casters with captive secondary alloy operations. EPA compliance-driven procurement from Detroit Three OEMs sustains premium pricing for crash-certified structural castings despite raw material volatility.
Pricing Analysis
Volume-discount tiering separates structural component contracts from commodity transmission housing orders. Pricing stratifies across crashworthiness-certified premium tiers, standard powertrain applications, and economy-grade non-structural brackets. Cost compression in standard-tier housings is intensifying because high-pressure aluminum casting advances threaten magnesium's position. Tier-1 manufacturers exhibit highest price sensitivity due to OEM cost-down mandates, while OEM direct sourcing of structural castings shows lowest sensitivity given NHTSA certification barriers.
Supply Chain Analysis
Contract-manufacturing concentration rests with Nemak, Shiloh Industries, and Meridian Lightweight Technologies across Michigan and Ontario foundry networks. Geographic supply concentration centers on China for primary magnesium ingots, Canada for secondary alloy processing, and Mexico for hybrid vehicle transmission housing assembly. Raw material dependencies draw from Chinese smelter output, AZ91D alloy additives, and hardened steel die tooling. Single-source vulnerability runs through Chinese primary magnesium supply subject to export quota fluctuations. Distribution runs through cross-border Ambassador Bridge corridors linking Windsor-Toronto processing to Detroit assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM vendor base consolidation for EV platforms has shifted procurement leverage toward Detroit Three automakers, compressing Tier-1 supplier margins while elevating qualification barriers for new entrants.
For Market Incumbents: Insulate structural casting margins by deepening captive secondary magnesium supply and accelerating Thixomolding automation for thin-wall geometries. Aluminum substitution in non-structural applications poses immediate threat; backward integration into tolling relationships with Ontario alloy processors defends cost position against Chinese raw material volatility. For New Entrants and Emerging Players: Build out semi-solid casting capacity for dashboard support beams and steering column brackets where Thixomolding automation gaps persist among established suppliers. The penetrable white space sits in structural battery enclosures for Great Lakes EV platforms lacking qualified regional die casters. A go-to-market angle through NHTSA pedestrian impact certification partnerships with Tier-1 engineering houses bypasses 18-month OEM direct qualification cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-material Tier-1 suppliers seeking exit liquidity as EV platform consolidation matures. Long-term viability hinges on structural casting exposure versus commodity powertrain housing dependence. The signal to watch is EPA fleet-average threshold enforcement intensity for 2027-2032 model years, which determines magnesium-intensive design penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Secondary Alloy Capacity | Insulates margin from Chinese primary magnesium price swings through in-house AZ91D production. |
| Thixomolding Automation Investment | Captures structural bracket opportunities as gravity casting methods become obsolete for complex geometries. |
| NHTSA Pedestrian Impact Certification | Unlocks hood and front-end magnesium adoption where energy absorption requirements favor AZ91D over aluminum. |
| Cross-Border Foundry Expansion | Positions capacity within USMCA regional content rules for IRA bonus-eligible EV assembly. |
| Multi-Speed E-Axle Housing Partnerships | Aligns with hybrid and battery-electric transmission complexity multiplying magnesium casting content per vehicle. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distribution heads; and secondary validation through vehicle production databases, IHS Markit registration data, EPA CAFE compliance filings, and USMCA trade flow records. Bottom-up capacity modeling at individual foundry level triangulated against top-down OEM platform magnesium content assumptions.
Forecast inputs considered propulsion architecture segmentation across internal combustion, hybrid, and battery-electric platforms; content per vehicle trajectories for transmission housings and structural components; and regional production cluster shifts across the Michigan-Ontario-Ohio manufacturing belt. CAGRs were derived from installed capacity expansion announcements, OEM platform launch schedules, and alloy substitution elasticity modeling. Industry-specific inputs incorporated NHTSA crashworthiness certification timeline compression and IRA domestic content bonus qualification thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese primary magnesium smelters to consolidate export pricing would shift outcomes beyond modeled ranges. Quarterly review of EPA fleet-average enforcement intensity and NHTSA pedestrian impact rule updates is advised to detect inflection in structural casting demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive AHSS Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Automotive AC Compressor Market