
 UK Automotive Parts Magnesium Die Casting Market | 2026-2036
UK Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Parts Magnesium Die Casting Market Analytics
Electric vehicle powertrain architectures is pivoting toward magnesium-intensive designs for battery housings and motor enclosures. Gibbs Die Casting anchors its position through captive engineering relationships with domestic OEM transmission programs. Meridian Lightweight Technologies dominates structural housing applications with proprietary thin-wall casting capabilities. Georg Fischer sustains competitive footing via integrated alloy development and machining operations serving tier-1 supply chains.
UK Automotive Parts Magnesium Die Casting encompasses the precision forming of magnesium-aluminum alloys into net-shape automotive components using reusable steel molds under controlled thermal and pressure conditions, typically achieving wall thicknesses below 2.5 millimeters for weight-critical applications. The process serves primarily to reduce vehicle mass in compliance with stringent emissions protocols while maintaining structural integrity under dynamic loading. High Pressure Die Casting occupies the largest share of production volume, driven by cycle-time efficiency in mass-production environments for engine components and transmission housings. Vacuum Die Casting represents the fastest-expanding technology segment, as porosity-sensitive chassis parts and safety-critical structural castings command premium qualification thresholds from OEMs.
The UK's Vehicle Certification Agency enforces whole-vehicle type approval standards that directly dictate magnesium alloy performance benchmarks for crash structures and fire resistance. BSI Group maintains material certification protocols for automotive magnesium grades, creating compliance barriers for non-accredited suppliers. The Health and Safety Executive regulates molten metal handling and fume exposure limits across foundry operations, elevating capital requirements for process containment systems. Stakeholders must monitor evolving EU-UK regulatory divergence on substance restrictions and end-of-life vehicle recycling mandates that could reshape alloy specification and sourcing obligations.
Market Dynamics
The West Midlands automotive cluster is concentrating engineering talent and magnesium die casting capacity around Jaguar Land Rover's electrification roadmap, creating a captive supply ecosystem that locks out peripheral competitors.
Growth Catalysts
- EV Battery Housing Demand:Electric vehicle architectures require lightweight, thermally stable enclosures that magnesium thin-wall castings deliver. OEM powertrain divisions specify these housings for pack-level weight reduction targets.
- BSI Material Certification:The British Standards Institute's accredited magnesium grade protocols create qualification barriers that favor established UK foundries with existing test data libraries.
- West Midlands Cluster Density:Proximity between Tier-1 engineering centers and Meridian Lightweight Technologies' Telford facility compresses prototype-to-production cycles for structural housing programs.
Market Restraints
- Silicon Carbide Price Volatility:Refractory consumables for molten metal containment face supply pressure from semiconductor sector competition, elevating foundry operating costs.
- Chinese Primary Magnesium Concentration:Over 80% of global magnesium ingot production sits within Shaanxi province smelters, exposing UK die casters to export quota disruptions and freight rate spikes.
- Aluminum High-Pressure Casting Substitution:Al-Si-Mg alloys with equivalent strength-to-weight ratios threaten magnesium adoption in non-thermal-critical brackets and mounts.
Strategic Opportunities
- Scottish Renewable Energy Integration:Offshore wind turbine nacelle manufacturers seek magnesium gearbox housings; Scottish supply chain development grants could offset transport costs from English foundries.
- Vehicle Certification Agency Fire Resistance Mandates:Updated type approval standards for battery enclosure flame containment favor magnesium's superior ignition temperature over polymer composites.
- Digital Twin Convergence:Real-time porosity prediction algorithms fused with vacuum die casting cells enable first-article qualification without destructive testing, opening safety-critical chassis applications.
Industry Challenges
- Tooling Engineer Scarcity:UK technical colleges graduate fewer die casting specialists than retirement rates demand; Meridian and Georg Fischer compete for Moldflow simulation talent.
- Vacuum System Capex Burden:Chassis-grade porosity specifications require sealed shot chamber investments exceeding standard high-pressure cell costs by 40-60%.
- OEM Platform Certification Timelines:Jaguar Land Rover's PPAP gates for structural castings extend 18-24 months, freezing capacity allocation before volume commitments materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Parts Magnesium Die Casting Market |
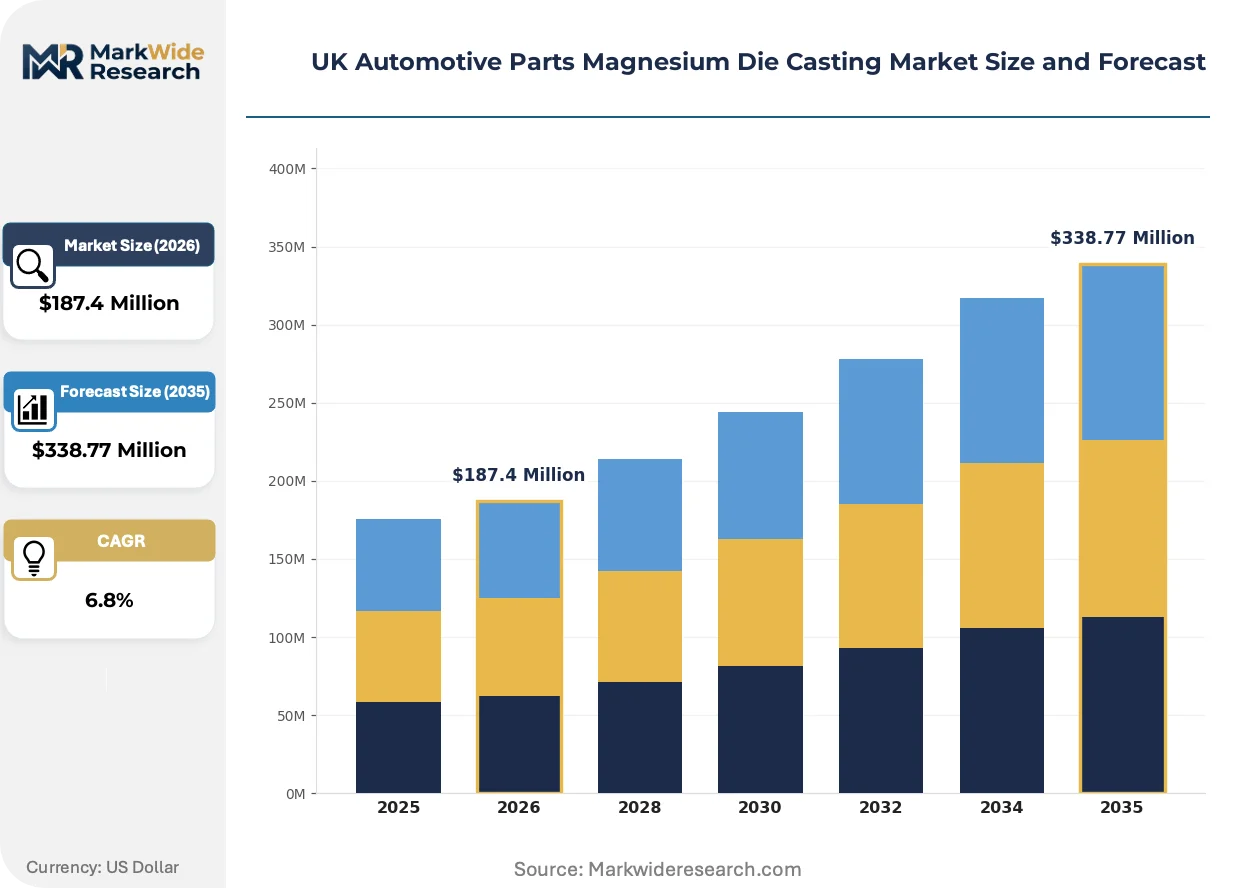
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Interior Trim, Chassis Parts End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Prototype, Mass Production, Custom Fabrication, Assembly Technology: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Vacuum Die Casting |
| Companies Covered | Gibbs Die Casting, Pace Industries, Shiloh Industries, Georg Fischer, Meridian Lightweight Technologies, Brabant Alucast, George Fischer Ltd, MK Group Of Companies, Dynacast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Parts Magnesium Die Casting Market Evolving Landscape
Process digitization and alloy formulation advances are compressing qualification cycles for safety-critical magnesium applications while regulatory fire-safety mandates reshape material specification protocols across UK automotive programs.
Thixomolding semi-solid magnesium forming is integrating into powertrain housing production lines, enabling near-net-shape geometry with 30% thinner walls than conventional high-pressure methods. Tier-1 suppliers adopt this for motor enclosures where dimensional stability under thermal cycling is paramount. The technology is integrating quality assurance workflows by embedding CT-scan validation directly into cell automation, collapsing inspection bottlenecks.
REACH substance restriction consultations are evaluating magnesium alloy additives for end-of-life vehicle recyclability compliance, pressuring foundries to document scrap stream purity. The Health and Safety Executive's molten metal fume exposure limits are tightening containment specifications for automated pouring operations. Vacuum die casting segments respond by sealing melt transfer systems, prioritizing chassis bracket programs where porosity tolerance thresholds are tightest.
Long-term supply agreements are displacing spot purchasing for primary magnesium ingot, as UK foundries seek price stability against Chinese export volatility. Procurement teams at Gibbs Die Casting and Meridian negotiate 3-5 year tolling contracts with smelter partners, transferring inventory risk upstream. This behavior is most pronounced in West Midlands operations serving Jaguar Land Rover's fixed-price platform contracts.
UK Automotive Parts Magnesium Die Casting Market Segmentation
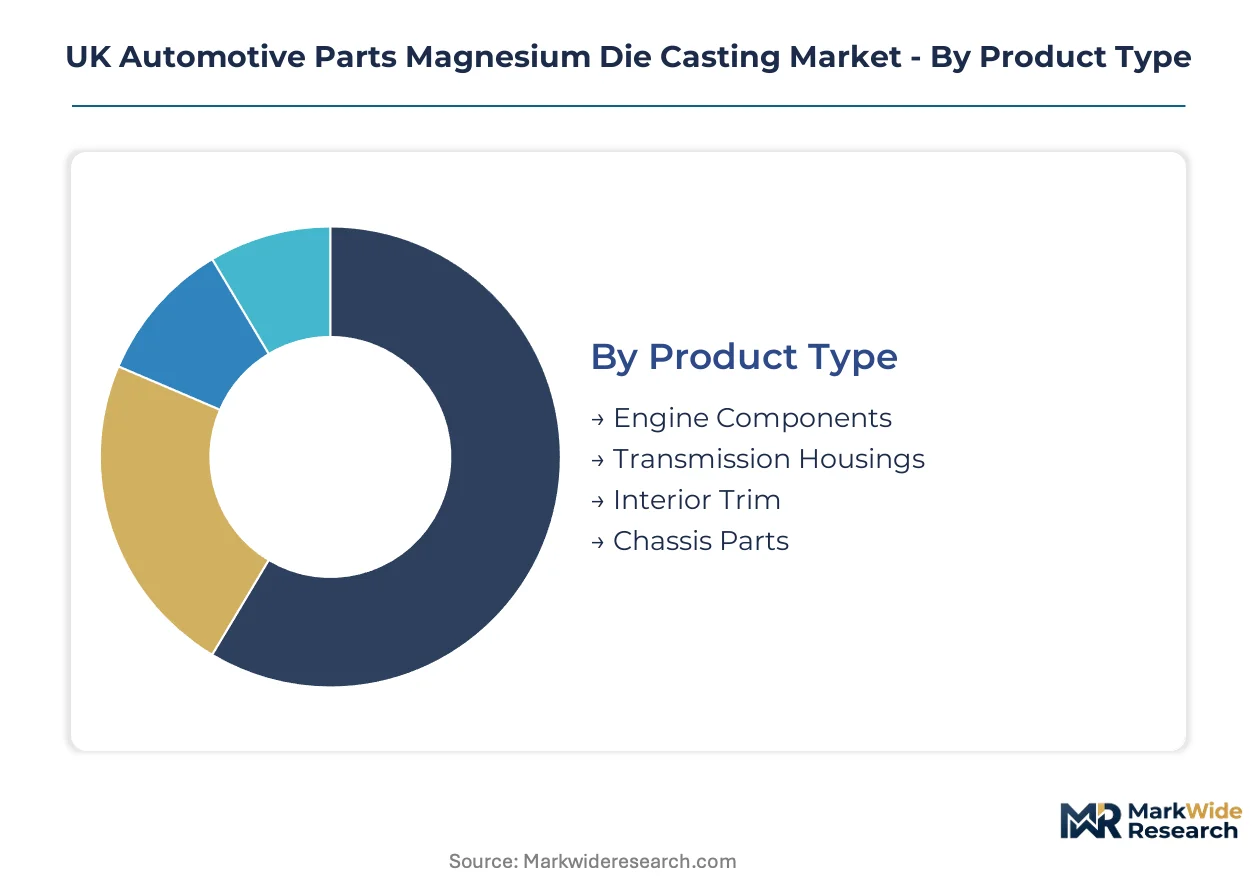
Magnesium die casting procurement patterns diverge sharply by buyer sophistication and volume commitment. OEMs demand PPAP-validated structural castings with 24-month qualification horizons, while aftermarket channels prioritize interchangeable brackets with compressed lead times. Understanding these buyer archetypes shapes capacity allocation and margin capture across UK foundries.
Product Type:
Component complexity and thermal loading requirements separate premium housing programs from commodity bracket supply.
- Transmission Housings:These multi-cavity castings integrate cooling jackets and bearing bores with wall thicknesses below 2.5 millimeters. Jaguar Land Rover's electrified powertrain roadmap concentrates demand around Solihull engineering centers, where Meridian Lightweight Technologies maintains captive prototype-to-production workflows.
- Engine Components:Structural integrity under cyclic thermal stress defines specification thresholds for oil pans and valve covers. Gibbs Die Casting anchors volume commitments through long-term supply agreements with domestic OEM transmission divisions, locking capacity three to five years forward.
- Interior Trim:Decorative bezels and structural seat frames prioritize surface finish over mechanical loading.
- Chassis Parts:Suspension brackets and steering column housings face porosity-sensitive qualification gates from the Vehicle Certification Agency.
Volume sits with transmission housings; growth tilts toward chassis parts as crashworthiness standards tighten.
End User:
Integration depth into vehicle platform engineering determines supplier selection criteria and contract duration.
- Tier-1 Suppliers:These intermediaries aggregate magnesium casting demand across multiple OEM platforms, achieving scale economies that justify dedicated tooling investments. Their procurement teams negotiate fixed-price contracts with West Midlands foundries, transferring raw material volatility risk upstream through tolling arrangements.
- OEMs:Direct sourcing relationships concentrate around powertrain housing programs where intellectual property protection is paramount. Jaguar Land Rover's in-house casting specifications exceed industry-standard magnesium grades, creating qualification barriers for non-captive suppliers.
- Vehicle Assemblers:Final assembly operations source standardized brackets and mounts through spot purchasing mechanisms.
- Aftermarket Providers:Replacement part distributors prioritize inventory turnover over metallurgical traceability.
Revenue concentrates with Tier-1 suppliers; margin expansion tracks toward OEM direct programs.
Manufacturing Stage:
Process maturity and tooling amortization schedules separate development-phase supply from volume production economics.
- Mass Production:High-pressure die casting cells achieve 90-second cycle times for transmission housings, amortizing six-figure tooling investments across million-unit platforms. The West Midlands cluster concentrates this capacity around Jaguar Land Rover's fixed-price electrification contracts.
- Prototype:Soft-tooling and gravity casting methods validate geometry before hard-tooling commitment. Rapid iteration demands compress supplier selection to foundries with in-house machining and CT-scan validation capabilities.
- Custom Fabrication:Low-volume specialty vehicles and motorsport applications require manual finishing and lot-traceable metallurgy.
- Assembly:Sub-component integration of castings with inserts and fasteners adds value downstream of primary forming.
Capital deployment favors mass production; prototype services command premium pricing.
Technology:
Porosity tolerance thresholds and cycle time economics determine process selection for each application class.
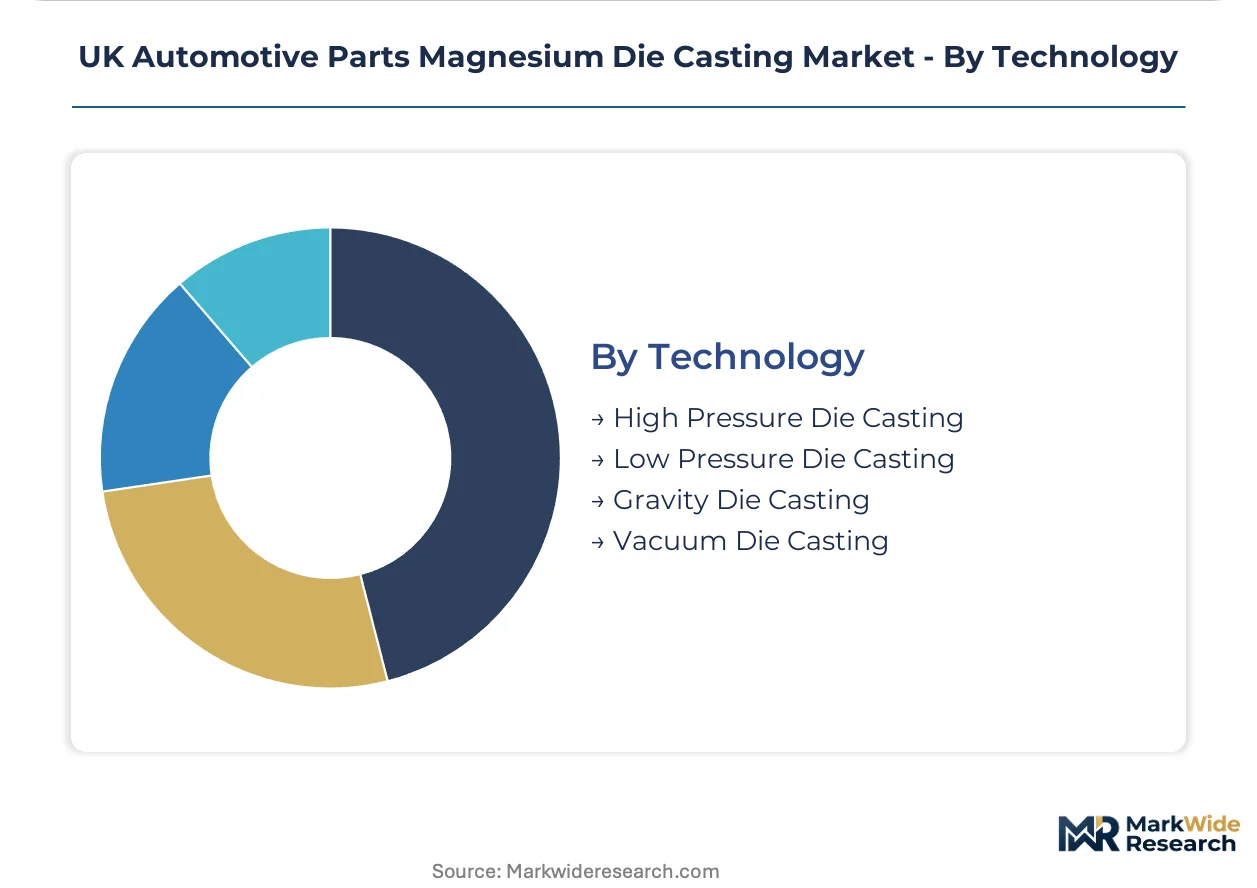
- Vacuum Die Casting:Sealed shot chambers eliminate entrapped air for safety-critical chassis brackets facing Vehicle Certification Agency structural approval. Capex premiums of 40-60% over standard high-pressure cells restrict adoption to programs with multi-year volume commitments.
- High Pressure Die Casting:Conventional cold-chamber machines dominate transmission housing production through cycle-time efficiency. Georg Fischer and Gibbs Die Casting operate legacy cell fleets across Midlands foundries, serving tier-1 supply chains with qualified process windows.
- Low Pressure Die Casting:Directional solidification benefits wheel and structural beam applications requiring weldability.
- Gravity Die Casting:Manual pouring suits prototype volumes and thick-walled components where porosity tolerance is relaxed.
Installed base concentrates in high pressure die casting; vacuum systems are expanding most quickly for chassis applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced Manufacturing Parks and enterprise zones across England's industrial heartlands are concentrating magnesium die casting capacity through targeted rate relief and infrastructure grants. This spatial clustering aligns foundry investment with OEM electrification timelines and regulatory compliance mandates.
West Midlands
Jaguar Land Rover's Solihull engineering headquarters drives structural housing demand for electrified powertrain programs. The Vehicle Certification Agency enforces whole-vehicle type approval standards that dictate magnesium alloy performance benchmarks for crash structures. Birmingham and Coventry host Meridian Lightweight Technologies' Telford facility alongside Gibbs Die Casting operations, creating captive prototype-to-production workflows.
East Midlands
Transmission component suppliers anchor demand for high-pressure die cast housings serving domestic OEM transmission divisions. The Health and Safety Executive regulates molten metal fume exposure limits across foundry operations, elevating capital requirements for process containment systems. Derby and Leicester concentrate legacy casting capacity with established BSI Group material certification protocols.
Scotland
Offshore wind turbine nacelle manufacturers seek magnesium gearbox housings for renewable energy infrastructure. Scottish supply chain development grants could offset transport costs from English foundries for qualifying programs. Glasgow and Edinburgh engineering consultancies interface with Highlands manufacturing zones exploring secondary applications.
North West England
Automotive supplier networks maintain machining and finishing operations for magnesium structural components. BSI Group accredited magnesium grade protocols create qualification barriers favoring established foundries with existing test data libraries. Manchester and Liverpool logistics corridors facilitate just-in-time delivery to Midlands assembly plants.
UK Automotive Parts Magnesium Die Casting Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with captive engineering relationships locking in multi-year supply commitments for transmission programs. The vendor base concentrates around three operational archetypes: integrated alloy developers with captive machining, thin-wall casting specialists serving structural housing applications, and high-volume producers anchored to legacy OEM transmission divisions. Consolidation pressure intensifies as electrification timelines compress qualification windows. Strategic moves center on securing long-term tolling contracts for primary magnesium ingot and embedding digital twin capabilities for porosity prediction.
Among UK-based operations, Gibbs Die Casting occupies a position within the captive supplier archetype through its Midlands foundry footprint. Meridian Lightweight Technologies exemplifies the thin-wall structural specialist tier with Telford-based capacity. Georg Fischer Ltd represents the integrated alloy-to-machining model serving tier-1 supply chains with qualified process windows.
| Leading Market Players |
|---|
| Gibbs Die Casting |
| Pace Industries |
| Shiloh Industries |
| Georg Fischer |
| Meridian Lightweight Technologies |
| Brabant Alucast |
| George Fischer Ltd |
| MK Group Of Companies |
| Dynacast |
| Others |
Value Network & Pricing Analysis
OEM direct-sourcing concentration around Jaguar Land Rover's electrification programs anchors contract-based pricing with fixed-price multi-year terms. Tier-1 suppliers negotiate tolling arrangements that transfer Chinese ingot volatility upstream, while spot purchasers absorb freight rate spikes without volume leverage.
Pricing Analysis
Short lead-time premiums compress margins for prototype-phase castings as West Midlands foundries prioritize 18-24 month PPAP-locked capacity. Three-tier pricing structure across premium, standard, and economy levels separates Vehicle Certification Agency-certified chassis grades from uncertified bracket supply. Cost compression in high-pressure transmission housings intensifies because aluminum substitution threats erode magnesium's weight advantage. Aftermarket distributors exhibit highest price sensitivity; OEM direct programs tolerate premium qualification costs for intellectual property protection.
Supply Chain Analysis
Dual-sourcing mandates from Jaguar Land Rover procurement require Meridian and Georg Fischer to maintain parallel qualification tracks for identical housing geometries. Primary magnesium ingot draws from China, Russia, and Israel; secondary alloy supply rests on UK scrap recovery rates. Silicon carbide refractory dependence creates single-source vulnerability when semiconductor sector demand spikes. Distribution runs through West Midlands Tier-1 engineering centers with just-in-time sequencing to Solihull assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry operators face a vertical-integration race where captive alloy development and machining capability determine platform access. Control over primary magnesium tolling contracts represents the decisive upstream lever separating qualified suppliers from spot-market exposed competitors.
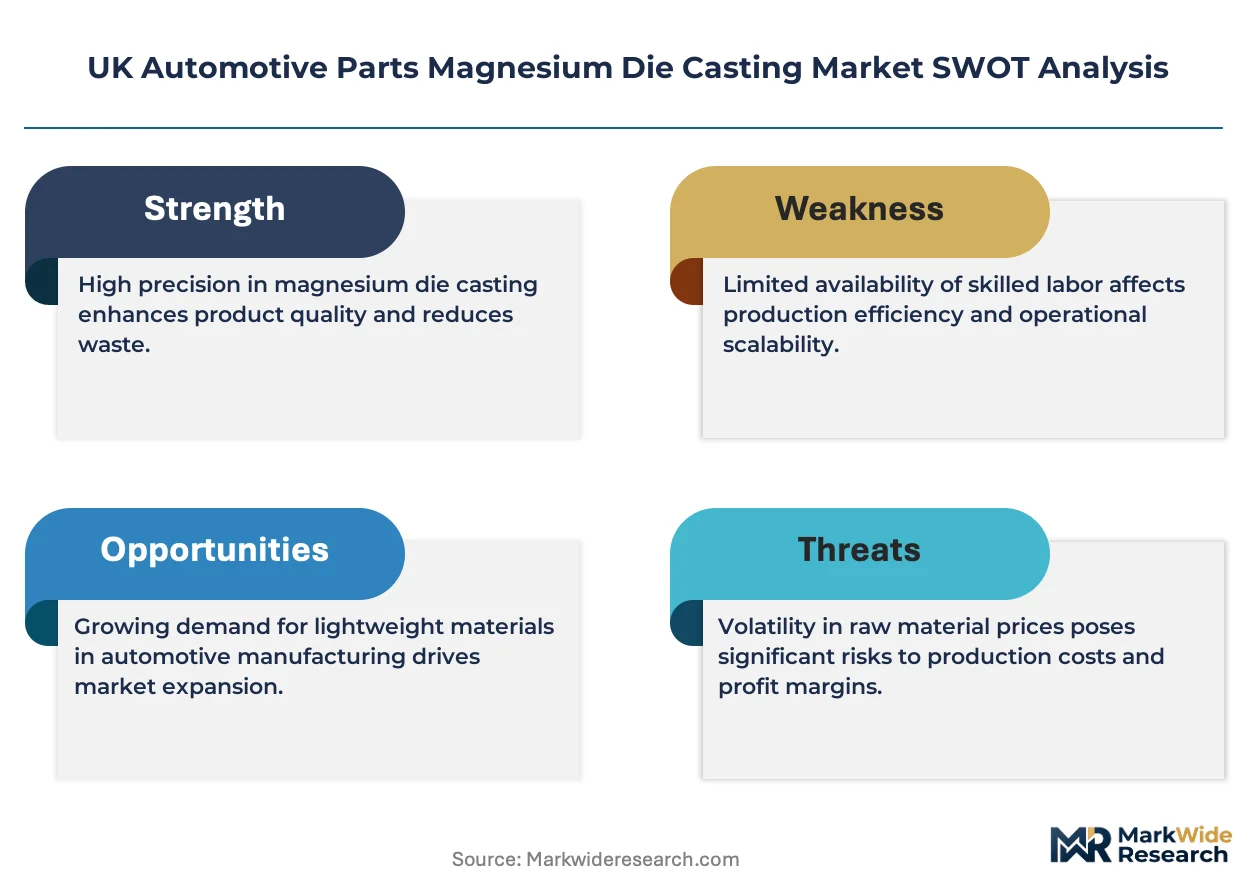
For Market Incumbents: To counter aluminum high-pressure casting substitution in non-thermal brackets, Meridian Lightweight Technologies and Gibbs Die Casting should deepen backward integration into primary magnesium tolling partnerships. Vacuum die casting capacity addition in Telford secures chassis-grade qualification gates before 18-24 month OEM platform timelines freeze allocation. For New Entrants and Emerging Players: Digital twin simulation services for porosity prediction offer the lowest-capital route into safety-critical supply chains without hard-tooling investment. Scottish offshore wind gearbox housing demand presents the most penetrable geography, with supply chain development grants offsetting transport costs from English foundry zones. Lead with CT-scan validation partnerships to compress prototype-to-production cycles for qualifying programs. For Investors and Strategic Acquirers: The window for entry favors thin-wall casting specialists with existing BSI Group certification libraries and captive machining operations. Long-term viability hinges on 5-10 year tolling contract coverage against Chinese export quota disruption. Watch Jaguar Land Rover platform certification announcement velocity as the inflection signal for capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Primary Magnesium Tolling Agreement | Long-term ingot contracts with Shaanxi smelter partners lock price stability against export quota volatility. |
| Vacuum Die Casting Cell Deployment | Sealed shot chamber investment opens Vehicle Certification Agency chassis bracket qualification pathways. |
| Digital Twin Porosity Prediction | Real-time simulation integration collapses first-article qualification timelines for safety-critical castings. |
| Thixomolding Process Adoption | Semi-solid forming enables 30% wall thickness reduction for EV motor enclosure thermal stability. |
| Scottish Supply Chain Expansion | Offshore wind nacelle gearbox housing demand diversifies revenue beyond automotive platform dependence. |
Research Methodology
Multi-period observation of magnesium alloy price spreads, OEM platform certification timelines, and foundry capacity utilization anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, Health and Safety Executive compliance officers, and BSI Group certification auditors. Secondary validation drew from UK Vehicle Certification Agency type approval databases, Health and Safety Executive enforcement notices, customs import records for primary magnesium ingot, and SEC filings of listed automotive supplier groups. Bottom-up casting volume estimates triangulated against top-down OEM electrification content-per-vehicle projections.
Segment-weighting applied technology-specific growth differentials across high-pressure, vacuum, and thixomolding process categories, with end-user splits between OEM direct, Tier-1 aggregator, and aftermarket channels. Propulsion architecture segmentation separated battery electric, hybrid, and internal combustion powertrain housing demand. CAGRs derived from fitted trend lines across the analysis window, with alloy substitution elasticity and Chinese export policy scenarios as sensitivity inputs.
The model holds under stable Chinese primary magnesium export quota enforcement and continued Jaguar Land Rover electrification platform commitment; deviation in Shaanxi smelter operating rates or UK-EU regulatory divergence on end-of-life vehicle recycling mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Speed Bump Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Automotive Differential Housing Market