
 Brazil Automotive Parts Magnesium Die Casting Market | 2026-2036
Brazil Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Parts Magnesium Die Casting Market Outlook
Passenger vehicle lightweighting is expanding as Brazilian OEMs chase fuel efficiency targets and electrification roadmaps. Gibbs Die Casting Group anchors its position through captive magnesium sourcing relationships across South American smelters. Meridian Lightweight Technologies differentiates via proprietary thin-wall casting expertise for transmission housings. Rima Industrial leverages domestic magnesium extraction assets to control raw material costs against import volatility.
Brazil automotive parts magnesium die casting involves injecting molten magnesium alloys—typically AZ91D or AM60B with 90% magnesium content—into hardened steel molds under pressures exceeding 70 MPa to produce near-net-shape components. The process yields parts 33% lighter than comparable aluminum castings, serving brake pedal brackets, steering column housings, and seat frames where mass reduction directly improves vehicle efficiency metrics. Structural parts command premium positioning as crashworthiness certification complexity rises, while high-pressure die casting dominates volume throughput for engine component production. Vacuum die casting gains traction among Tier-1 suppliers targeting porosity-sensitive powertrain applications where leak-tightness standards intensify.
ANVISA workplace exposure limits and INMETRO material certification requirements shape foundry capital allocation toward fume extraction and alloy traceability systems. The national environmental regulator, IBAMA, enforces air emission thresholds that push smaller independents toward consolidation or technology upgrades. Stakeholders must monitor PROCONVE emission phase transitions and their ripple effects on powertrain architecture decisions that determine magnesium casting specification volumes.
Market Dynamics
INMETRO certification requirements for automotive materials are forcing foundries to reallocate capital toward alloy traceability systems and vacuum die casting equipment, compressing margins for independents while favoring integrated producers with captive magnesium supply.
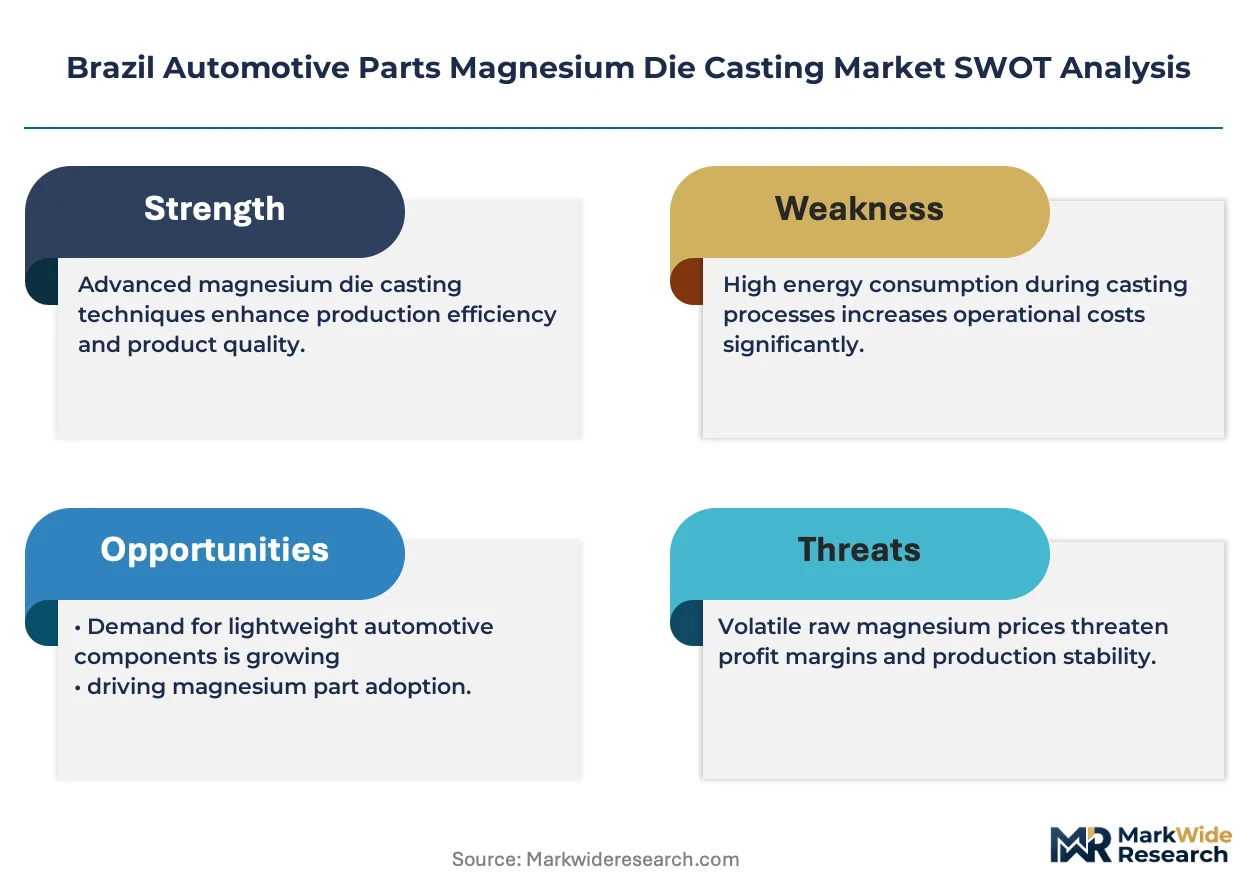
Growth Catalysts
- PROCONVE emission phase transitions:Tightening tailpipe standards are accelerating powertrain lightweighting mandates across Brazilian OEM assembly plants.
- Electric vehicle powertrain housings:Battery enclosure demand from São Paulo state's electrification supplier corridor is pulling magnesium casting volumes upward.
- Thin-wall casting expertise:Transmission housing specifications below 2.5mm wall thickness are unlocking mass reduction credits for fuel efficiency compliance.
Market Restraints
- Magnesium ingot import dependency:Domestic primary magnesium extraction capacity constraints expose foundries to Atlantic shipping rate volatility and currency fluctuation.
- ANVISA workplace exposure protocols:Fume extraction system mandates impose six-figure capital burdens on sub-scale operators below 5,000-ton annual throughput.
- Aluminum high-pressure die casting substitution:Mature aluminum supply chains and lower alloy prices capture brake bracket applications where crashworthiness requirements permit.
Strategic Opportunities
- Minas Gerais secondary smelter corridor:Untapped magnesium recycling infrastructure near Belo Horizonte industrial parks offers 40% raw material cost reduction potential.
- Seat frame structural magnesium conversion:Front-row seat backrest assemblies remain underpenetrated versus European specification rates.
- IBAMA air emission credit trading:Early fume capture technology adopters can monetize surplus permits to subsidize vacuum casting upgrades.
Industry Challenges
- High-pressure die casting technician scarcity:Specialized mold maintenance and thermal management skills command 35% wage premiums above general foundry labor.
- Multi-certification timeline compression:Simultaneous INMETRO material approval and OEM crashworthiness validation cycles extend new product introduction to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Parts Magnesium Die Casting Market |
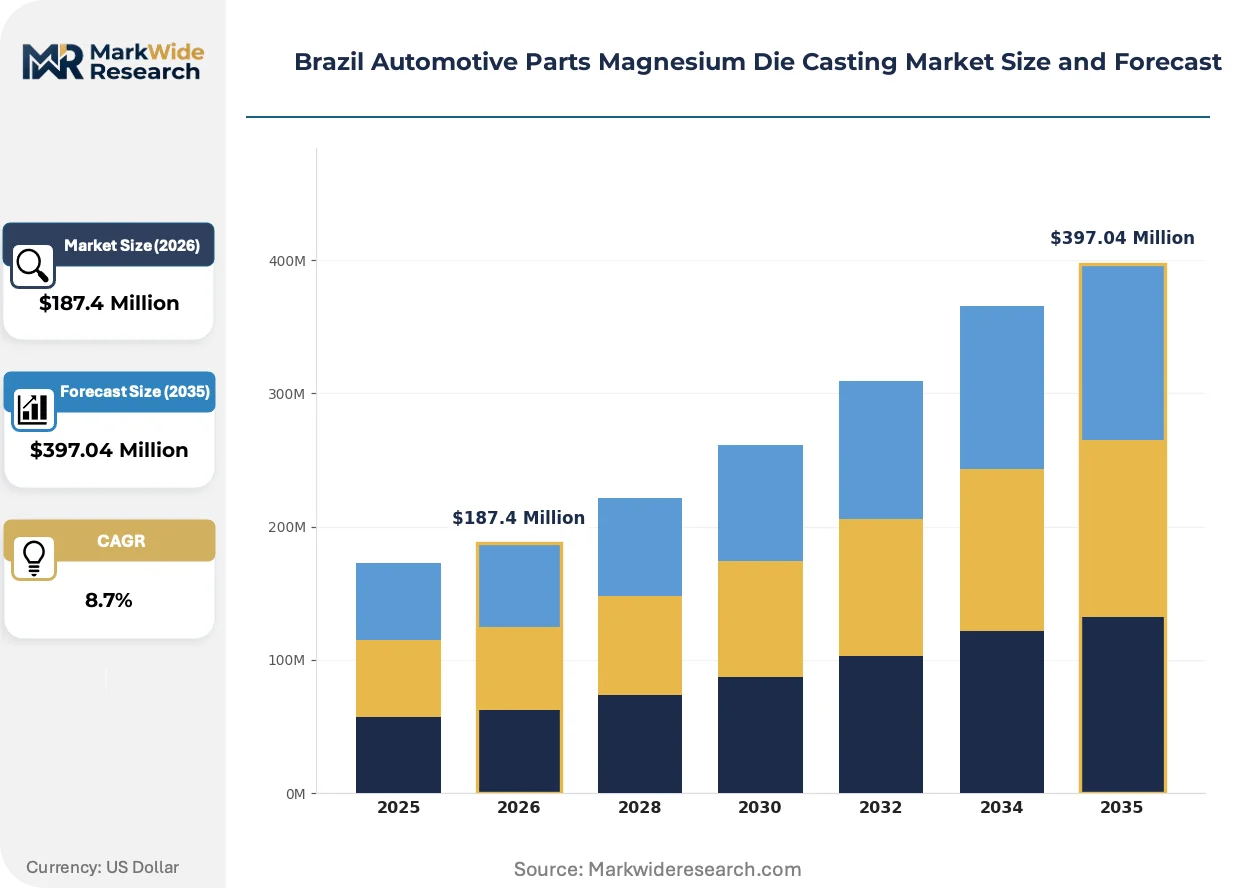
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Structural Parts, Trim Parts Application: OEMs, Aftermarket, Commercial Vehicles, Passenger Vehicles Technology: High-Pressure Die Casting, Vacuum Die Casting, Semi-Solid Die Casting, Gravity Die Casting End User: Automobile Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Repair Shops |
| Companies Covered | Gibbs Die Casting Group, Pace Industries, Shiloh Industries Inc., Georg Fischer AG, Meridian Lightweight Technologies, Rima Industrial, Dynacast, Brabant Alucas, Magic Precision Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Parts Magnesium Die Casting Market Strategic Shifts
Vacuum-assisted die casting technology is compressing porosity defect rates and enabling leak-tight powertrain applications previously reserved for aluminum gravity casting.
Thixomolding semi-solid magnesium processing is overtaking conventional high-pressure die casting for steering column housings requiring weldable microstructures. Tier-1 suppliers in ABC Paulista are retrofitting 3,500-ton presses with electromagnetic stirring systems. This technology is overtaking legacy hot-chamber methods for structural safety-critical components where porosity tolerance sits below 0.5%.
IBAMA Resolution 491/2018 air emission thresholds are mandating regenerative thermal oxidizer installation across independent foundries below 10,000-ton capacity. The regulation compresses operational flexibility for batch producers serving aftermarket segments. Smaller operators in Rio Grande do Sul are consolidating or exiting rather than absorbing seven-figure compliance capex.
Fleet procurement contracts are consolidating magnesium casting specification authority at OEM central engineering centers, displacing historical Tier-1 supplier design autonomy. Long-term supply agreements now bundle alloy sourcing, casting, and machining under single-source accountability. This concentration is most visible in São Paulo state where Volkswagen and Stellantis anchor regional demand.
Brazil Automotive Parts Magnesium Die Casting Market Segmentation
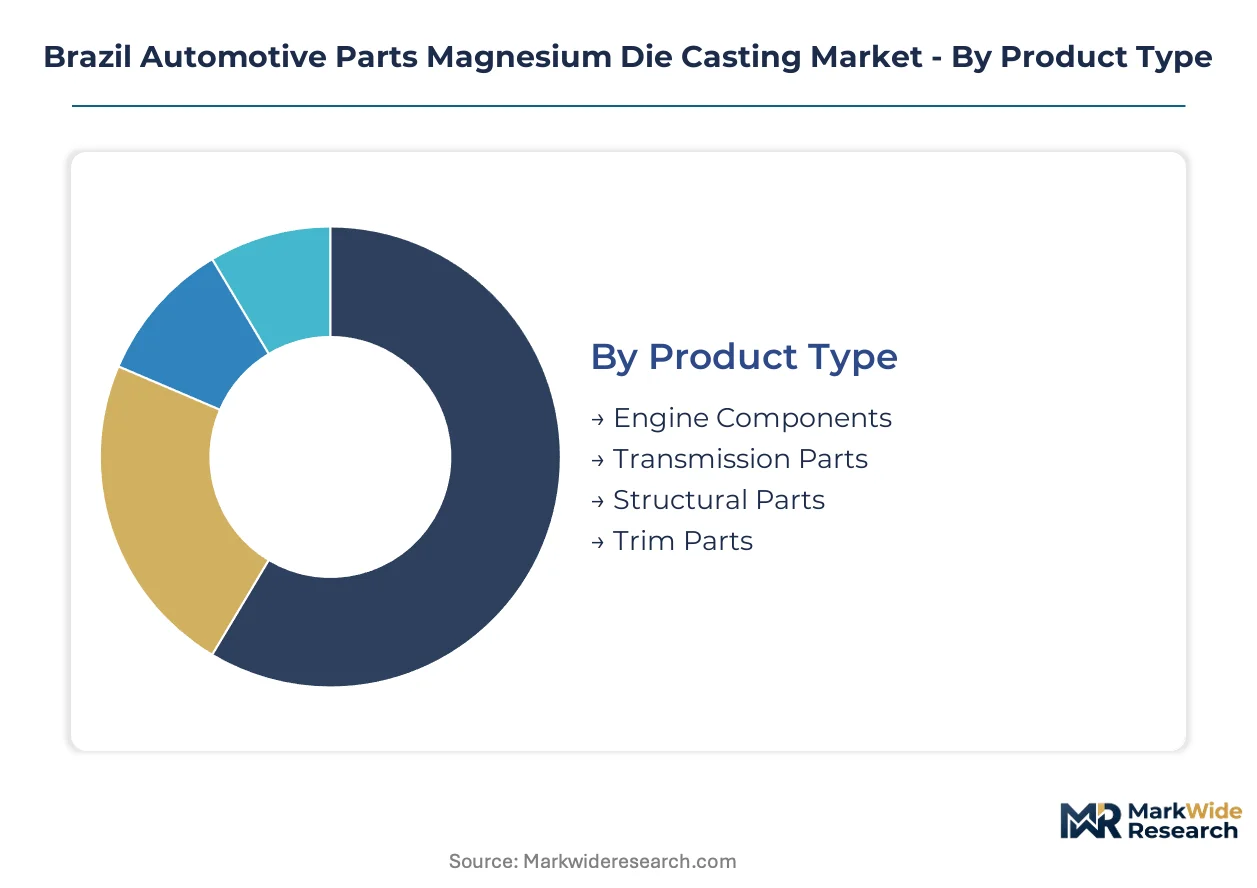
Magnesium die casting specifications diverge sharply across automotive subsystems, with powertrain architectures and crashworthiness mandates dictating alloy selection and process technology. Foundry investment decisions hinge on segment-specific margin profiles and certification timelines.
Product Type:
Component replacement cycles and lightweighting upgrade trajectories reshape foundry capacity allocation across engine, transmission, and structural applications.
- Engine Components:AZ91D alloy dominates oil pan and valve cover castings where thermal conductivity and creep resistance balance cost. São Paulo state OEM assembly plants specify these for compact passenger vehicle platforms chasing PROCONVE efficiency targets.
- Transmission Parts:AM60B alloy thin-wall housings below 2.5mm thickness enable mass reduction credits for fuel economy compliance. ABC Paulista supplier clusters concentrate vacuum die casting capacity here for leak-tight dual-clutch transmission enclosures.
- Structural Parts:Crashworthiness-certified seat frames and steering column housings command premium positioning through INMETRO validation complexity.
- Trim Parts:Interior decorative castings prioritize surface finish over mechanical properties, serving lower-specification vehicle trims with shorter tooling amortization.
Engine components sit at the top of the volume ranking, with structural parts climbing the fastest as electrification shifts mass reduction priorities toward battery enclosure integration.
Application:
Customer-type concentration patterns reveal where procurement authority centralizes and where aftermarket fragmentation persists.
- OEMs:Volkswagen and Stellantis anchor direct sourcing relationships with captive design specification authority. Long-term supply agreements bundle alloy sourcing, casting, and machining under single-source accountability with 18-24 month validation cycles.
- Passenger Vehicles:Compact and mid-size platforms drive magnesium specification for brake pedal brackets and seat frames where 33% mass reduction versus aluminum translates directly to efficiency metrics.
- Commercial Vehicles:Heavy-duty powertrain housings prioritize durability over lightweighting, limiting magnesium penetration to ancillary brackets.
- Aftermarket:Fragmented demand across independent repair networks concentrates in Rio Grande do Sul, where smaller foundries face IBAMA emission compliance consolidation pressure.
OEM procurement dominates volume share, with passenger vehicle applications expanding most quickly through electrification platform mandates.
Technology:
Process maturity curves and capital intensity gradients separate volume producers from specialty contractors.
- High-Pressure Die Casting:Conventional hot-chamber methods dominate engine component throughput at 70+ MPa injection pressures. ABC Paulista clusters operate 3,500-ton presses for AZ91D transmission housings with cycle times optimized for automotive just-in-sequence delivery.
- Vacuum Die Casting:Porosity-sensitive powertrain applications require leak-tight microstructures below 0.5% defect rates. Tier-1 suppliers retrofitting equipment target battery enclosure specifications where thermal management demands precision.
- Semi-Solid Die Casting:Thixomolding with electromagnetic stirring enables weldable steering column housings for structural safety-critical assemblies.
- Gravity Die Casting:Lower-volume prototyping and aftermarket production persists where tooling amortization constraints exclude high-pressure methods.
High-pressure die casting maintains volume leadership, with vacuum die casting gaining share fastest through electrification powertrain specification.
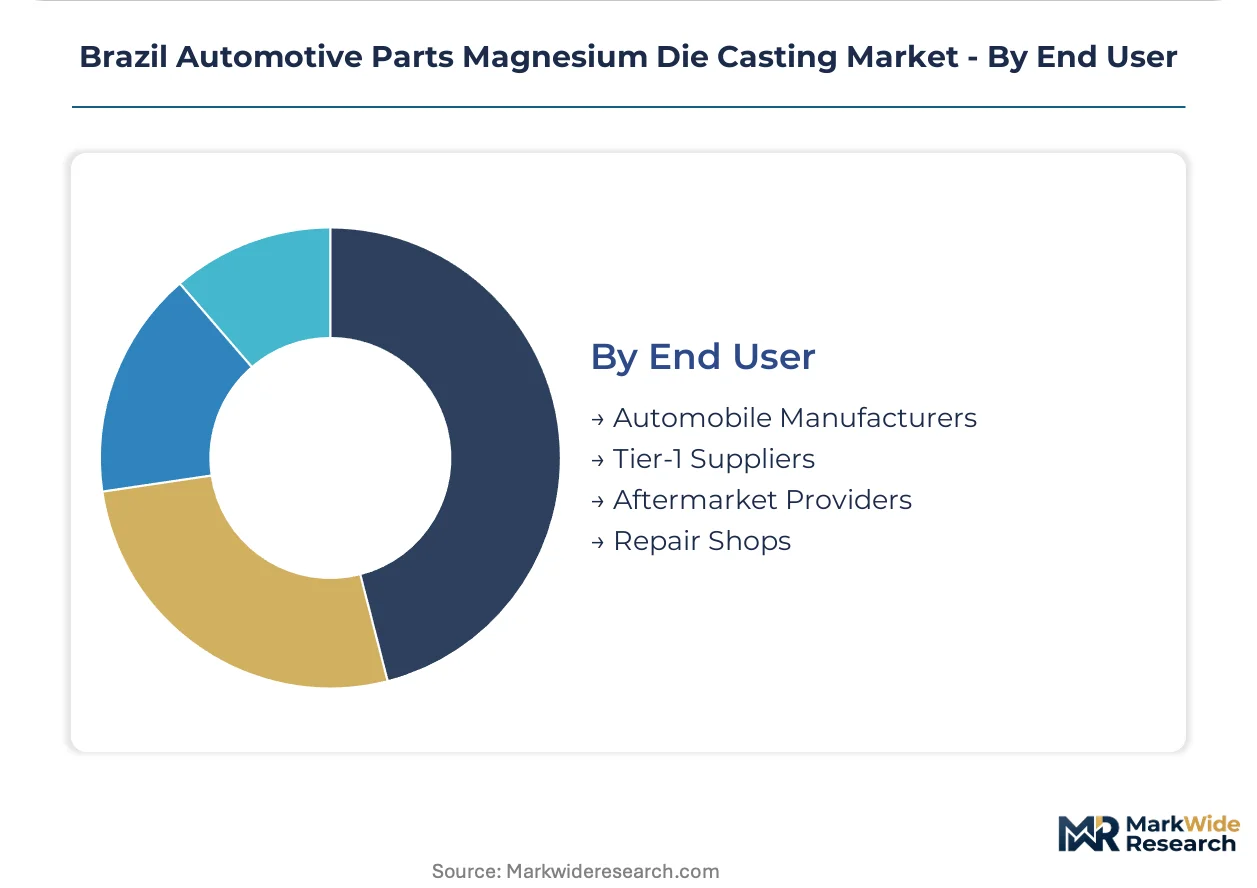
End User:
Supply chain tier positioning determines margin capture and technical specification authority.
- Tier-1 Suppliers:Meridian Lightweight Technologies and Gibbs Die Casting Group concentrate design-to-delivery accountability for transmission housings. These entities control thin-wall casting expertise and captive magnesium sourcing relationships.
- Automobile Manufacturers:Central engineering centers in São Paulo state consolidate magnesium casting specification authority, displacing historical supplier design autonomy through fleet procurement contracts.
- Aftermarket Providers:Brake bracket and trim component distributors serve secondary vehicle life cycles with reduced certification burdens.
- Repair Shops:Minimal direct magnesium casting procurement; replacement parts flow through authorized dealer networks or independent distributors.
Tier-1 suppliers command the highest volume concentration, with automobile manufacturers accelerating direct specification fastest through electrification platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ABC Paulista supplier clusters anchor Brazilian magnesium die casting capacity, concentrating Tier-1 foundries within São Paulo state's automotive manufacturing corridor. State-level regulatory differentiation and industrial park incentives reshape sub-regional competitive positioning.
São Paulo
Compact passenger vehicle platforms from Volkswagen and Stellantis assembly plants drive AZ91D alloy demand for oil pans and valve covers. PROCONVE emission phase transitions mandate lightweighting specifications that Tier-1 suppliers convert into transmission housing contracts. São Paulo state's ABC Paulista corridor concentrates vacuum die casting retrofit investments targeting battery enclosure thermal management.
Minas Gerais
Untapped magnesium recycling infrastructure near Belo Horizonte industrial parks offers raw material cost reduction potential for secondary smelter development. IBAMA air emission thresholds push smaller foundries toward consolidation or technology upgrades. The secondary smelter corridor attracts backward-integrated producers seeking captive magnesium supply security.
Rio Grande do Sul
Aftermarket brake bracket and trim component demand fragments across independent repair networks with reduced certification burdens. IBAMA Resolution 491/2018 compliance capex pressures batch producers serving secondary vehicle life cycles. Smaller operators face exit decisions rather than absorbing regenerative thermal oxidizer installation costs.
Rio de Janeiro
Port infrastructure supports magnesium ingot import flows exposed to Atlantic shipping rate volatility and currency fluctuation. ANVISA workplace exposure protocols impose fume extraction system mandates on sub-scale operators. The state's industrial parks lag São Paulo in vacuum die casting equipment density.
Paraná
Automotive supplier park development near Curitiba attracts Tier-2 foundry investments chasing just-in-sequence delivery contracts. INMETRO certification requirements extend new product introduction timelines to 18-24 months. The state competes for magnesium casting specification authority against established São Paulo engineering centers.
Brazil Automotive Parts Magnesium Die Casting Market Competitive Environment
Capacity expansion dominates the current landscape as foundries retrofit 3,500-ton presses with electromagnetic stirring systems. The market structures around integrated producers with captive magnesium supply, independent specialists in thin-wall casting, and sub-scale operators facing regulatory consolidation pressure. Strategic archetypes include backward-integrated smelter-foundries, technology-licensed precision casters, and OEM-captive Tier-1 suppliers. M&A activity and vacuum die casting equipment deployment constitute the primary competitive moves reshaping market share distribution.
Among North American-based fabricators, Gibbs Die Casting Group and Pace Industries occupy positions within the integrated producer tier. Meridian Lightweight Technologies exemplifies the technology-differentiated archetype through its proprietary thin-wall casting positioning. Rima Industrial anchors the backward-integrated segment with domestic magnesium extraction assets. Georg Fischer AG represents European-engineered precision casting expertise applied to Brazilian powertrain specifications. These entities collectively illustrate how geographic origin and supply chain configuration determine competitive positioning within ANVISA-regulated foundry operations.
| Leading Market Players |
|---|
| Gibbs Die Casting Group |
| Pace Industries |
| Shiloh Industries Inc. |
| Georg Fischer AG |
| Meridian Lightweight Technologies |
| Rima Industrial |
| Dynacast |
| Brabant Alucas |
| Magic Precision Inc. |
| Others |
Value Chain & Pricing Dynamics
Magnesium ingot import costs from Atlantic shipping lanes cascade through São Paulo foundry pricing tiers, compressing margins for independents lacking captive smelter relationships while integrated producers capture cost pass-through advantages in OEM contract negotiations.
Pricing Analysis
Distributor markup layers separate spot-market magnesium alloy purchasers from direct-to-OEM contract holders securing volume discounts. Pricing stratifies across INMETRO-certified premium castings, standard high-pressure die cast components, and economy-grade aftermarket brake brackets. Cost compression in the independent foundry tier is intensifying due to ANVISA fume extraction mandates. Aftermarket distributors serving Rio Grande do Sul repair networks exhibit highest price sensitivity, while Volkswagen and Stellantis central engineering centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Atlantic freight rate volatility from Chinese and Russian primary magnesium exporters directly impacts Brazilian foundry input costs. Domestic supply draws from Rima Industrial's Minas Gerais extraction assets alongside imported AZ91D and AM60B alloy shipments. Single-source vulnerability concentrates in high-purity magnesium ingot streams subject to currency fluctuation. Distribution runs through ABC Paulista Tier-1 supplier clusters for OEM just-in-sequence delivery, with secondary channels serving aftermarket fragmentation in southern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PROCONVE emission phase transitions compound regulatory demand for lightweight powertrain components, establishing magnesium die casting as a structural beneficiary of Brazilian automotive efficiency mandates.
For Market Incumbents: Anchor market position through backward integration into Minas Gerais secondary smelter infrastructure, securing captive magnesium supply against Atlantic shipping volatility. Accelerate vacuum die casting equipment deployment to capture battery enclosure specifications from electrification platforms. Defend against aluminum substitution in brake bracket applications by emphasizing crashworthiness-certified AZ91D casting portfolios.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in structural seat frame assemblies offers white-space entry below Meridian Lightweight Technologies' thin-wall positioning. Target underpenetrated front-row seat backrest conversions where European specification rates exceed Brazilian adoption. Pursue technology licensing arrangements with electromagnetic stirring equipment providers to bypass proprietary process barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where IBAMA Resolution 491/2018 compliance capex exceeds sub-scale operator balance sheet capacity. Long-term viability favors backward-integrated smelter-foundries with captive raw material security and OEM validation track records. Monitor PROCONVE phase transition announcements as inflection indicators for powertrain lightweighting specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Magnesium Smelter Development | Minas Gerais secondary smelter corridors reduce raw material cost exposure to Atlantic shipping volatility. |
| Vacuum Die Casting Equipment Retrofit | ABC Paulista Tier-1 suppliers target battery enclosure leak-tightness specifications from electrification platforms. |
| INMETRO Certification Investment | Alloy traceability systems unlock OEM direct sourcing contracts with 18-24 month validation cycles. |
| Thixomolding Process Licensing | Electromagnetic stirring technology enables weldable steering column housing penetration in structural safety-critical segments. |
| Regenerative Thermal Oxidizer Installation | IBAMA air emission credit trading monetizes surplus permits to subsidize vacuum casting upgrades. |
Study Parameters
Bottom-up automotive platform modeling reconciled against top-down magnesium alloy consumption tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, foundry operations managers, and ANVISA compliance officers combined with secondary validation from INMETRO certification databases, IBAMA emission registry filings, and vehicle production statistics. Trade flow analysis of Atlantic magnesium ingot shipments triangulates against domestic extraction capacity disclosures from Rima Industrial and secondary smelter development permits.
Historical trendline analysis of PROCONVE phase transition impacts on powertrain architecture decisions informs the projection framework across the analysis window. Segmentation dimensions encompass product type, application, process technology, and end-user tier, with vehicle class and propulsion architecture serving as automotive-specific forecast inputs. CAGRs derive from weighted average of platform-level content-per-vehicle trajectories and foundry capacity expansion announcements, cross-referenced against OEM electrification roadmaps.
Caveats apply where PROCONVE timeline acceleration or Atlantic shipping disruption could materially shift the outlook. Forecasts reflect assumptions regarding alloy substitution elasticity and regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Engine Bearings Market