
 Electric Vehicle Brake Pad Market | 2026-2036
Electric Vehicle Brake Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Brake Pad Market Insights
The capital-intensity gap between integrated brake system suppliers and component-only manufacturers is collapsing as electrification demands simultaneous mastery of thermal management software and friction material science. Brembo S.p.A. leverages its motorsport-derived cooling architectures to command premium positioning in high-performance EV platforms. Akebono Brake Industry Co., Ltd. anchors its competitive stance through proprietary copper-free formulations that preempt regulatory restrictions across multiple jurisdictions. Robert Bosch GmbH extends its influence by bundling brake pads with integrated electronic control systems, tightening account control at OEM specification stages.
Electric vehicle brake pads are friction components engineered to operate within regenerative braking architectures, typically incorporating non-asbestos organic matrices or ceramic composites with thermal thresholds exceeding conventional internal-combustion equivalents to accommodate reduced mechanical braking frequency. Their primary commercial purpose centers on delivering consistent friction performance during emergency stops while minimizing particulate emissions that conflict with tightening environmental standards. Ceramic formulations now lead value contribution due to their low dust profiles and compatibility with premium EV weight distributions, while electromagnetic technology segments attract disproportionate R&D allocation as automakers pursue brake-by-wire architectures. OEM channels concentrate margin pools through multi-year platform supply agreements, though aftermarket retailers compete aggressively on installation-network density as EV parc ages.
The EPA regulates friction material composition under copper-reduction mandates, while ECHA's REACH restrictions constrain specific binder chemistries and heavy-metal content in pads sold across European markets. China's GB standards and SAMR enforcement create parallel certification requirements that fragment supplier testing protocols. Stakeholders must monitor divergence between regional particulate limits and regenerative-system integration standards to anticipate where formulation R&D investments convert to commercial advantage.
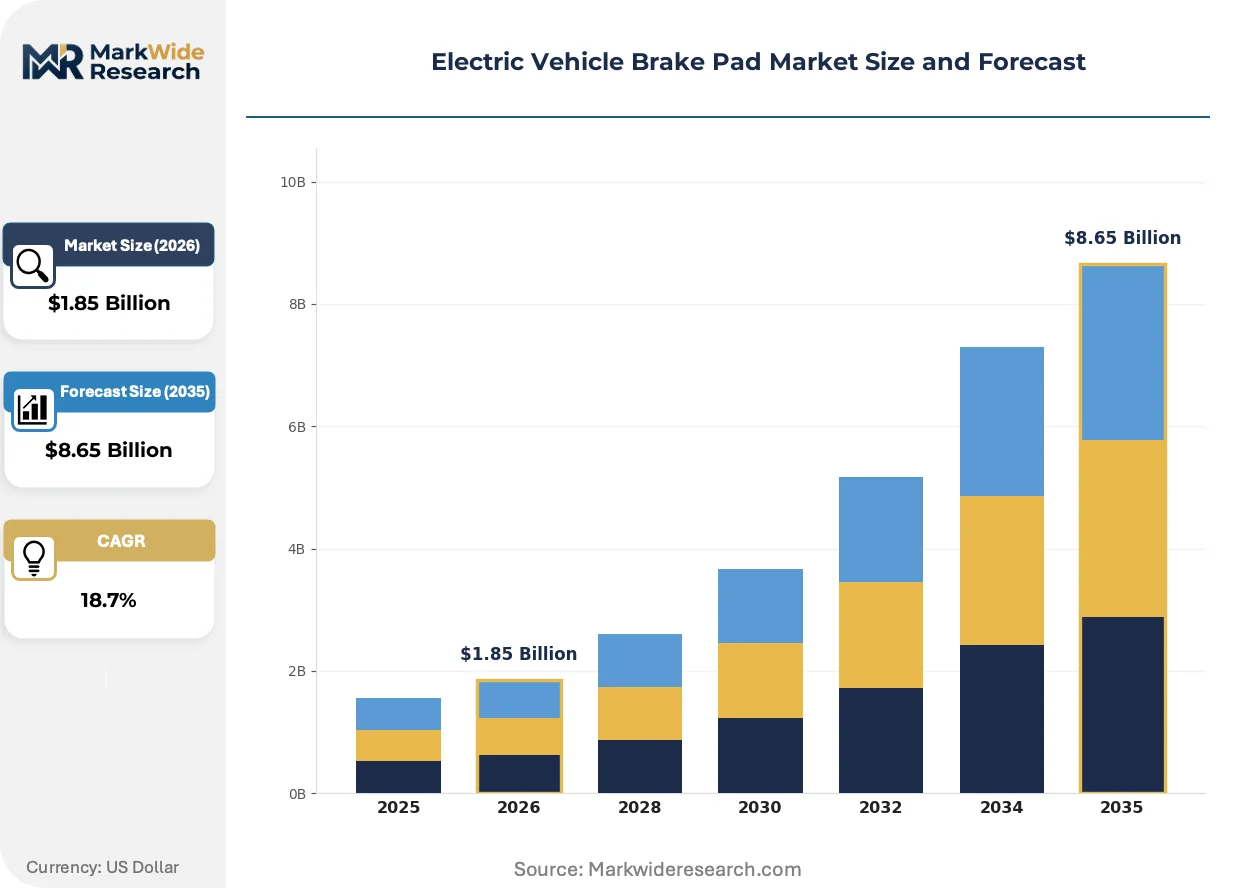
Market Dynamics
Regenerative braking architectures are compressing mechanical brake utilization rates, forcing suppliers to engineer pads that withstand thermal cycling stress from infrequent but high-load emergency stops while maintaining friction stability across extended dormant periods.
Growth Catalysts
- Copper-reduction mandates:EPA friction material standards and ECHA REACH restrictions on heavy-metal content are disqualifying legacy formulations, creating replacement demand for compliant ceramic and non-asbestos organic matrices.
- Fleet electrification:Commercial vehicle operators in Germany's automotive corridor are specifying extended-service-interval brake components to minimize total cost of ownership across electric truck and bus platforms.
- Thermal management integration:Brake-by-wire architectures require pads engineered for compatibility with electromagnetic actuation systems and real-time temperature telemetry.
Market Restraints
- Raw material concentration:High-purity ceramic fiber supply concentrates among limited Japanese and Chinese producers, exposing formulators to input cost volatility and qualification delays.
- Technical performance gaps:Low-dust formulations struggle to match the cold-weather bite coefficients of conventional semi-metallic pads, limiting adoption in Nordic climates.
- Regulatory fragmentation:Divergent particulate emissions testing protocols between EPA, ECHA, and China's SAMR force redundant certification cycles that extend product launch timelines.
Strategic Opportunities
- Aftermarket channel expansion:Independent service networks in the United States are building EV-specific installation capabilities to capture aging parc maintenance as early-adopter vehicles exit warranty coverage.
- Technology convergence:Integration of brake pad thermal sensors with vehicle telematics platforms enables predictive wear monitoring and just-in-time replacement scheduling.
- Regulatory tailwinds:California's Advanced Clean Trucks regulation and parallel EU CO2 standards for heavy-duty vehicles are accelerating electric commercial vehicle deployment and associated brake system demand.
Industry Challenges
- Skill scarcity:Formulation chemists with simultaneous expertise in friction material science and embedded thermal sensing electronics command premium compensation and limited availability.
- Certification bottlenecks:OEM platform supply agreements require 18-24 month validation cycles including dynamometer testing and fleet trials, compressing window for technology refresh.
- Integration complexity:Legacy brake system architectures in retrofit applications resist seamless incorporation of regenerative-compatible pad geometries and sensor mounting provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Brake Pad Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Semi-Metallic, Organic, Carbon-Composite End User: OEMs, Aftermarket Retailers, Fleet Managers, Automotive Service Providers Material: Reinforced Steel, Synthetic Resin, Copper Fiber, High-Performance Plastics Technology: Electromagnetic, Regenerative, Hydraulic, Electronic Control Systems |
| Companies Covered | Brembo S.p.A., Akebono Brake Industry Co., Ltd., TRW Aftermarket, ATE Brakes, Robert Bosch GmbH, NRS Brakes, ADVICS Co., Ltd., Federal-Mogul Corporation, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Brake Pad Market Trends and Innovations
Ceramic composite formulations are displacing conventional friction materials as the default specification for premium electric vehicle platforms, while brake-by-wire architectures and embedded sensing capabilities are redefining component value propositions.
Copper-free ceramic matrices are fragmenting the supplier landscape as proprietary binder chemistries differentiate performance tiers. Luxury EV OEMs in Germany and California are adopting these formulations for their low dust profiles and reduced wheel contamination. The technology is fragmenting procurement patterns, with platform engineers now specifying pad-and-sensor bundles rather than discrete friction components.
EPA copper-reduction mandates for friction materials are tightening compositional requirements through 2025 implementation deadlines. Formulators must eliminate copper content exceeding trace thresholds while maintaining fade resistance and NVH performance. North American aftermarket distributors are accelerating inventory transitions to preempt regulatory enforcement and avoid stranded stock positions.
Fleet procurement is consolidating brake system sourcing under multi-year platform agreements that bundle pads with calipers, rotors, and electronic controls. Independent distributors are responding with specialized EV service certification programs and direct technician training relationships. This consolidation is most visible among German commercial vehicle operators specifying integrated thermal management across electric truck and bus deployments.
Electric Vehicle Brake Pad Market Segmentation
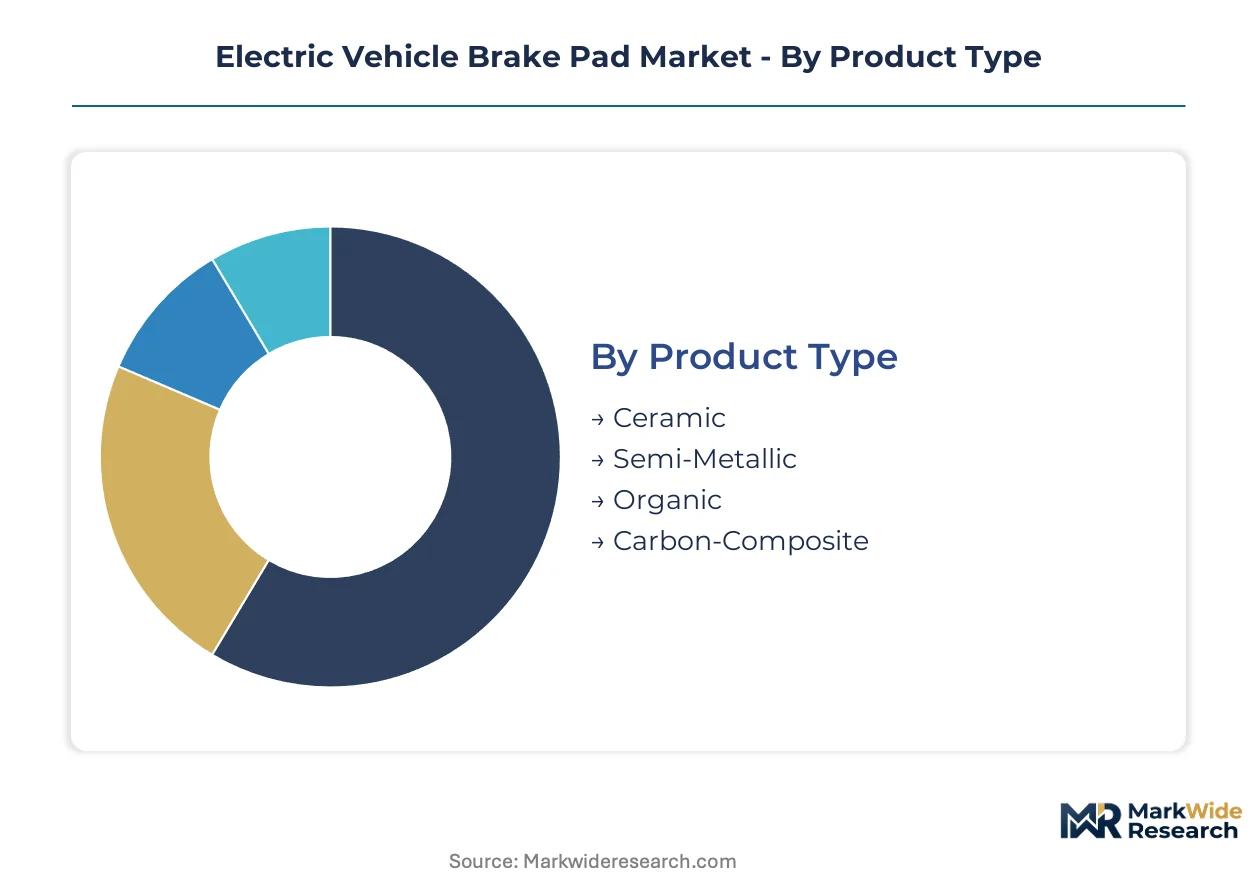
Segmentation in the electric vehicle brake pad market reveals how regenerative braking architectures reshape material requirements and procurement patterns. Suppliers must align formulation portfolios with divergent thermal cycling demands across product tiers while navigating distinct qualification protocols for OEM and aftermarket channels.
Product Type:
Ceramic formulations face intensifying substitution pressure from carbon-composite alternatives as premium EV platforms pursue weight reduction targets.
- Ceramic:Non-asbestos organic matrices with copper-free binder chemistries dominate premium platform specifications. German luxury EV manufacturers source these formulations for low dust profiles and compatibility with extended service intervals mandated by fleet electrification programs.
- Semi-Metallic:Iron and steel fiber composites retain cost positioning in commercial vehicle segments where cold-weather bite coefficients outweigh dust concerns. Nordic operators specify these formulations for electric bus platforms despite REACH compliance penalties on copper content.
- Organic:Glass and rubber-modified compounds serve entry-level EV production with reduced thermal thresholds.
- Carbon-Composite:Carbon-ceramic hybrids command motorsport-derived positioning for high-performance electric platforms.
Semi-metallic formulations retain volume leadership across price-sensitive commercial deployments; carbon-composite holds the steepest expansion curve as brake-by-wire architectures proliferate.
End User:
Procurement concentration varies sharply by channel, with fleet managers consolidating sourcing under multi-year thermal management agreements.
- OEMs:Platform engineers bundle brake pads with integrated electronic control systems, requiring 18-24 month validation cycles. California-based EV manufacturers specify pad-and-sensor combinations for real-time wear telemetry.
- Aftermarket Retailers:Independent distributors in the United States build EV-specific installation networks to capture aging parc maintenance. These channels compete on technician certification density rather than formulation differentiation.
- Fleet Managers:German commercial operators negotiate extended-service-interval components for electric truck platforms.
- Automotive Service Providers:Franchise networks source compliant formulations to preempt EPA enforcement on copper-reduction mandates.
OEM channels capture margin concentration through specification control; aftermarket retailers are gaining share fastest as early-adopter vehicles exit warranty coverage.
Material:
Input cost volatility fragments supplier positioning based on access to qualified fiber sources.
- Reinforced Steel:High-tensile steel fibers anchor semi-metallic formulations for heavy-duty electric commercial vehicles. Japanese producers concentrate supply, exposing formulators to qualification delays and price swings.
- Synthetic Resin:Phenolic and polyimide binders enable copper-free ceramic matrices that satisfy EPA friction material standards. Formulators with proprietary resin chemistries differentiate fade resistance performance.
- Copper Fiber:Legacy content faces phase-out under copper-reduction mandates, stranding inventory positions.
- High-Performance Plastics:PEEK and PPS composites serve sensor integration housings in brake-by-wire architectures.
Reinforced steel maintains input volume dominance; synthetic resin binders are climbing the fastest as regulatory deadlines approach.
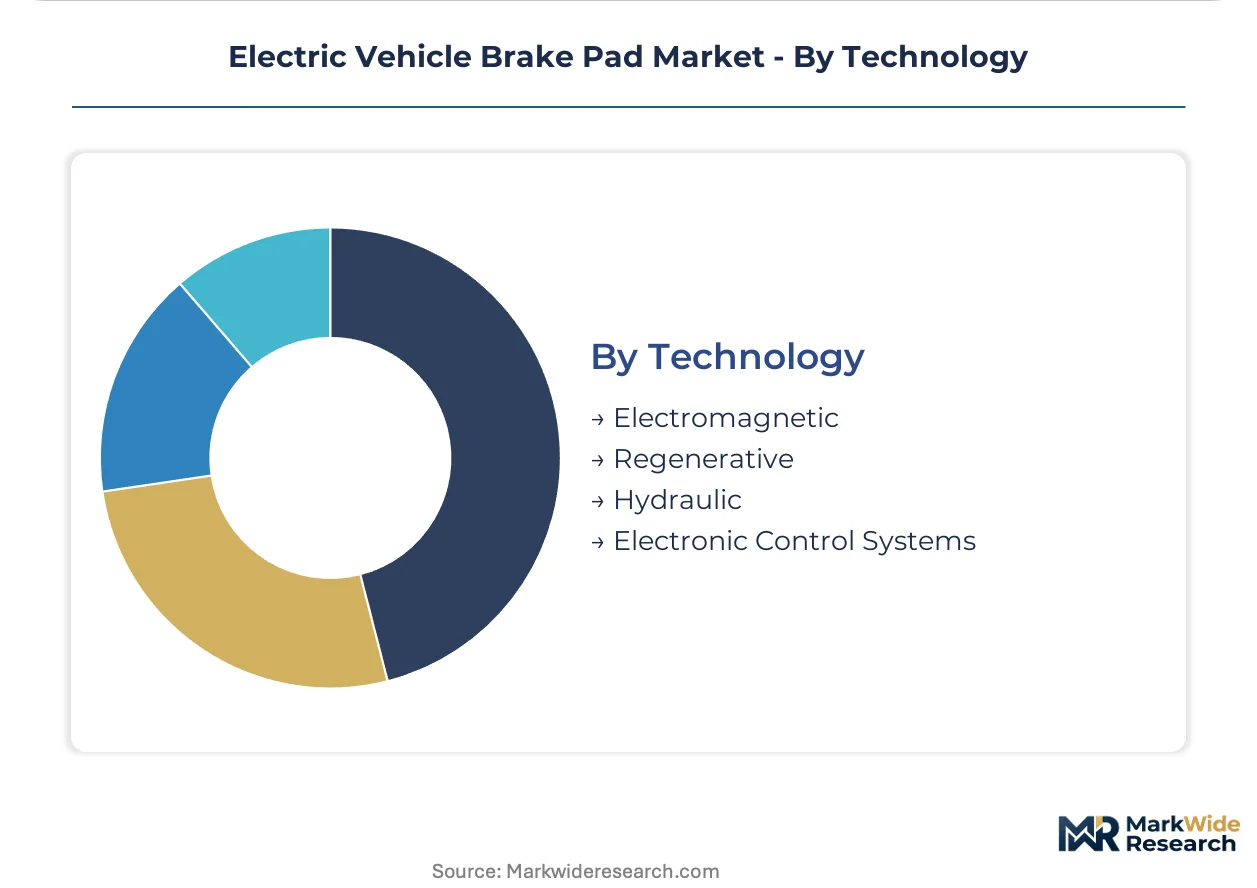
Technology:
Integration complexity separates suppliers capable of embedded sensing from component-only manufacturers.
- Electromagnetic:Brake-by-wire actuation systems eliminate hydraulic lines, requiring pads engineered for precise clamp force response. German automotive corridor OEMs specify electromagnetic compatibility for premium platform integration.
- Regenerative:Blended braking algorithms demand friction materials stable across infrequent high-load emergency stops. Thermal cycling durability determines supplier qualification for electric truck and bus deployments.
- Hydraulic:Legacy architectures persist in retrofit applications and entry-level EV platforms.
- Electronic Control Systems:Sensor-embedded pads enable predictive maintenance through vehicle telematics platforms.
Regenerative technology anchors current installed base; electromagnetic systems are expanding most quickly as automakers pursue full brake-by-wire architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive corridor while Chinese manufacturers compete on ceramic fiber cost structures. The United States captures aftermarket margin through EPA-driven formulation transitions. Japan anchors high-purity input supply.
United States
California's Advanced Clean Trucks regulation accelerates electric commercial vehicle deployment across the Pacific Coast. EPA copper-reduction mandates force inventory transitions at aftermarket distributors nationwide. Detroit-area OEMs specify integrated brake-by-wire systems for premium EV platforms.
Germany
Fleet managers in Baden-Württemberg negotiate extended-service-interval components for electric truck and bus platforms. ECHA REACH restrictions on heavy-metal content disqualify legacy formulations across European markets. Stuttgart's automotive engineering cluster drives brake system integration for luxury EV manufacturers.
China
GB standards and SAMR enforcement create parallel certification requirements that fragment supplier testing protocols. Domestic OEMs in the Yangtze River Delta source ceramic matrices for mass-market EV production. Shanghai-based producers concentrate high-purity ceramic fiber supply.
Japan
METI industrial policy supports brake-by-wire R&D for next-generation EV architectures. JIS standards govern friction material performance testing for domestic and export markets. Aichi Prefecture's automotive supplier network specializes in thermal management component integration.
South Korea
Seoul Capital Area OEMs pursue electromagnetic brake system architectures for premium EV platforms. MFDS-equivalent automotive standards align with international friction material certification protocols. Busan-Ulsan industrial corridor hosts ceramic composite research facilities serving regional automakers.
Electric Vehicle Brake Pad Market Competitive Landscape
Concentration sits with diversified automotive suppliers possessing simultaneous friction material and electronic control capabilities. Tier-one brake system integrators command specification control at OEM platform stages through multi-year supply agreements. Component specialists and aftermarket distributors occupy fragmented positions below. Competitive moves center on technology licensing for brake-by-wire architectures and strategic partnerships for ceramic fiber supply security.
Within the integrated-system tier, Brembo S.p.A. and Robert Bosch GmbH exemplify suppliers bundling brake pads with electronic control systems. Akebono Brake Industry Co., Ltd. occupies a position among formulation specialists emphasizing copper-free matrices. These three represent divergent strategic anchors: motorsport-derived thermal architectures, control-system integration breadth, and preemptive regulatory compliance through material science.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| Akebono Brake Industry Co., Ltd. |
| TRW Aftermarket |
| ATE Brakes |
| Robert Bosch GmbH |
| NRS Brakes |
| ADVICS Co., Ltd. |
| Federal-Mogul Corporation |
| BorgWarner |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at high-purity ceramic fiber producers in Japan and China sits above regional averages, compressing marginal cost curves for compliant brake pad formulators while elevating price floors for copper-free ceramic matrices. This scale concentration rewards integrated suppliers with captive fiber access, forcing component-only manufacturers toward cost-absorbing qualification delays or premium input sourcing.
Pricing Analysis
The customization-premium spread separates configured-to-order ceramic formulations for German luxury EV platforms from standard non-asbestos organic matrices serving mass-market production. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal threshold performance, with EPA copper-reduction mandates eliminating economy-tier legacy formulations. Cost compression in standard-grade semi-metallic pads intensifies as Nordic commercial operators demand cold-weather bite coefficients despite REACH compliance penalties. Fleet managers exhibit lowest price sensitivity due to total cost of ownership calculations, while independent aftermarket distributors face acute margin pressure from stranded copper-containing inventory.
Supply Chain Analysis
Japan and China anchor high-purity ceramic fiber production, with Aichi Prefecture suppliers specializing in thermal management component integration and Yangtze River Delta producers serving mass-market EV ceramic matrices. Synthetic resin binders for copper-free formulations draw from phenolic and polyimide chemical complexes concentrated in Germany and the United States. Single-source vulnerability concentrates in Japanese reinforced steel fiber supply for semi-metallic commercial vehicle pads. Distribution runs through OEM platform supply agreements bundling pads with electronic controls, alongside independent aftermarket networks building EV-specific installation density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle brake pad demand sits in early-cycle expansion as fleet electrification programs accelerate specification of extended-service-interval components across commercial vehicle platforms.
For Market Incumbents: Fortify backward integration into high-purity ceramic fiber supply to preempt Japanese producer qualification bottlenecks. Deepen thermal management software capabilities to defend specification control against brake-by-wire entrants. Prioritize copper-free formulation R&D investment ahead of EPA enforcement deadlines to avoid stranded certification cycles. For New Entrants and Emerging Players: Anchor in aftermarket channel expansion across the United States where early-adopter EV parc is aging out of warranty coverage. Target independent service network certification partnerships as the most penetrable entry vector, bypassing OEM platform supply agreement lock-in. Lead with predictive wear monitoring technology bundled with compliant ceramic formulations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with proprietary copper-free binder chemistries and embedded sensing integration capabilities. Five-to-ten year viability hinges on brake-by-wire architecture adoption curves and regulatory enforcement timing across multiple jurisdictions. Monitor divergence between EPA copper-reduction implementation and ECHA REACH heavy-metal restrictions as the critical inflection signal for formulation R&D return on investment.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Formulation Certification | EPA friction material standards disqualify legacy compositions, creating replacement demand for compliant ceramic matrices. |
| Brake-by-Wire Architecture Development | German automotive corridor OEMs specify electromagnetic compatibility for premium platform integration and thermal telemetry. |
| Ceramic Fiber Supply Security | Japanese high-purity fiber concentration exposes formulators to input cost volatility and extended qualification timelines. |
| Aftermarket Network Certification | Independent United States distributors build EV-specific installation capabilities to capture aging parc maintenance revenue. |
| Predictive Maintenance Integration | Sensor-embedded pads enable just-in-time replacement scheduling through vehicle telematics platform connectivity. |
Research Methodology
The analysis maps ceramic composite, semi-metallic, organic, and carbon-composite brake pad sub-sectors, each validated through OEM platform engineers, aftermarket distributor procurement leads, fleet maintenance managers, and thermal management R&D directors. Primary interview findings triangulate against vehicle production databases, EPA friction material regulatory filings, ECHA REACH substance restriction updates, and customs trade records for ceramic fiber inputs. Bottom-up segment sizing and top-down market reconciliation ensure cross-validation across the projection horizon.
Consistency checks against external benchmarks validate volume and value outputs across product type, end user, material composition, and technology segmentation dimensions. The analytical framework models propulsion architecture evolution and content per vehicle shifts without year-specific assumptions. CAGRs derive from installed base projections, replacement cycle compression, and regulatory deadline impacts. Industry-specific forecast inputs include fleet electrification program announcements and brake-by-wire platform adoption curves.
Decision-makers should treat outputs as directional under stable regulatory enforcement schedules and fiber supply continuity assumptions; material deviation would warrant model refresh. Specific risk factors include copper-reduction mandate delay or acceleration, ceramic fiber export restriction implementation, and brake-by-wire architecture standardization timing. Recalibration cycles align with material shifts in EPA enforcement actions and ECHA substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
North America Gear Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market